Can investors use value and momentum strategies in Japan?

Value and momentum are widely regarded as two of the most powerful factors that drive stock market returns. Cheap stocks tend to beat expensive stocks and, although it may sound counterintuitive, stocks which are rising in price tend to keep on going up. One curious exception noted by some analysts is that momentum may be less effective in Japanese markets. Cliff Asness of AQR Capital explains that ‘quite a few authors have pointed out that momentum is an empirical failure for stock selection in Japan’. Does this mean that investors in Japan can’t use momentum strategies to generate stronger returns? Let’s take a closer look by exploring whether investors could improve their performance by diversifying across a range of both value and momentum stocks.
Value in Japan
Buying shares that are priced below their ‘intrinsic value’ (or true worth) - otherwise known as value investing - is one of the oldest and most successful strategies in the stock market. Research by Cliff Asness suggests that value investing does pay off in Japan. He defined the value premium as the extent to which a basket of cheap price-to-book (P/B) stocks outperformed a basket of expensive P/B stocks. The value premium was calculated for stocks in the US, UK, Europe, Japan and a global region (ie. ‘All’). Asness concluded that ‘the Japan region turns in the strongest value results, even stronger than the more-diversified All region’. See here:
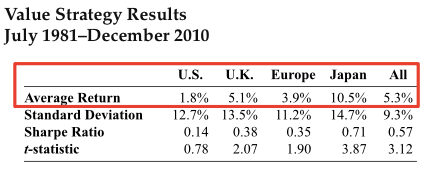
Some academics have attributed the value effect to investor overreaction. When investors hear good news they overreact and stocks become overvalued as the share price is driven too high. Conversely, when investors overreact to bad news, the share price is driven too low and companies become undervalued.
One argument put forward to explain why value strategies are so effective in Japan is that a larger proportion of the country's companies are cyclical. They include the likes of Nissan and Toyota. The overreaction effect is arguably stronger amongst cyclicals because the earnings of these stocks are more sensitive to trends in the business cycle. Indeed, profits tend to fall harder during an economic contraction. Investors could overreact to the first signs of a recession and oversell cyclicals, creating opportunities to buy Japanese companies at bargain prices. This is precisely the argument put forward by CLSA's Nicholas Smith in an interview with the John Authers of the Financial Times.
John Authers: When it comes to choosing stocks within Japan, value really works remarkably well over time... Why do you think that is?
Nicholas Smith: I think the trouble with Japan is its a highly cyclical market, and so when earnings are hot you tend to overestimate how far they are going to go, and on the downside you just don’t know what’s going to happen.
What about Momentum?
Many readers may be excited about the performance of value strategies in Japan. However, the downside -as we’ve already mentioned- is that momentum strategies may be less effective. This is partly because the respective returns of value and momentum strategies tend to be negatively correlated. In Japan value zigged while momentum tended to zag. Asness observed that between 1981 and 2000 the Value-Momentum correlation in Japan was -0.55.
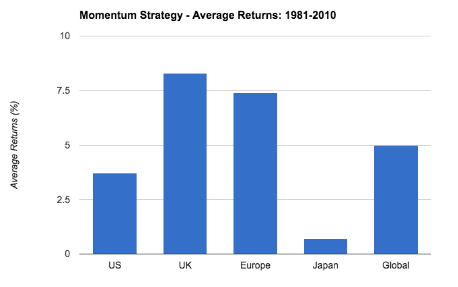
What is the problem here? Asness explains that ‘value has been on a 29 1?2-year tear in Japan. Japanese momentum has been ?0.55 correlated to value over this period’ and has produced relatively poor returns. Indeed, Asness compared the returns of momentum strategies in the US, UK, Europe and Japan. He found that ‘momentum in Japan is far and away the weak sibling’, as we can see here:
What role can momentum play?
This does not mean that momentum has no role to play in an investment strategy. Stocks and other investments should be evaluated on their contribution to a portfolio’s returns and also the portfolio’s risk (ie. volatility of returns).
Between 1981 and 2011, investors in Japan could have reduced the volatility of their portfolio by gaining exposure to investments that were inversely correlated with each other (eg. value stocks as well as momentum stocks). We can clearly see from the chart below that there were periods when value did not work but momentum strategies paid off (eg. 1995). There were also times when momentum crashed and value strategies were more effective (eg. 2007). Although both strategies had their own downturns, the combination of the two would have generated more stable returns. Indeed, Asness explains that:
- The standard deviation (or volatility) of the portfolio which held a mix of high value stocks and strong momentum stocks was 8.6%.
- This was lower than the standard deviation of the portfolio which only held high momentum stocks (20.2%).
- The value-momentum portfolio also generated less volatile returns than the portfolio of value stocks (14.7%).

Furthermore, Asness explains that by diversifying across a range of value and momentum stocks, investors could generate stronger risk-adjusted returns. We can measure risk-adjusted returns using the sharpe ratio - which divides a stock’s returns by the volatility of those returns. All else being equal, a portfolio with more stable returns would have a higher sharpe ratio than a portfolio with more volatile returns. Asness found that:
- The portfolio which allocated 70% of its holdings to high value stocks and 30% of its holdings to high momentum stocks produced a sharpe ratio of 0.88.
- This was higher than the sharpe ratio of the portfolio which only held value stocks (0.71).
- It was also higher that the sharpe ratio of the portfolio which held only momentum stocks (0.03).
Putting value and momentum to work
So value has worked in Japan and investors could generate more stable returns by blending value with momentum. If you want to look for Japanese stocks with high value and strong momentum, how can you do it? This sort of screening is ideally suited to Stockopedia's ValueRank - which ranks every company in the market based on a range of value metrics, including the P/E, P/S and P/B ratios (see here). Furthermore, the Value/Momentum (VM Rank) identifies stocks that may be cheap, but have also strong price momentum in addition to strong earnings momentum (ie. brokers may be upgrading their earnings forecasts for these stocks).
In order to identify companies with a high (or low) StockRank, users may want to check out our StockRank portal (see here). Users can filter the market by value, quality and momentum, as well as size, region and sector.
Since April 2013, we have been tracking the performance of UK stocks with a high ValueRank. Companies with a high ValueRank (over 90) have appreciated by 28% on average, while low ValueRank stocks have fallen by over 20%. We have also tracked the performance of companies with high a VM Rank. Again, companies with high VM Rank have produced strong results (67% on average) while low VM stocks have fallen by around 25% over the same period. See here:

We will be tracking the performance of StockRanks in Japan as we go forward. If you want to learn more about Japanese markets and the investing scene in East Asia, why not check out our latest ebook, Successful Investing in Asia & Australia. It was written to help readers navigate the key exchanges and indexes, and also identify a stockbroker that can help with execution. If readers have any insights into the investment strategies that work, or do not work in these markets, do please feel free to leave your comments below.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
6 comments
Good article.
The cyclicality argument/emotional over-reaction is an interesting one. But surely this is also true for other cyclical markets, such as Canada, Australia, and, indeed, many other emerging markets, which tend to be very resource based? I'd argue that Japan is actually less cyclical than many of these?
Hi guys,
Many thanks for the feedback.
You raise an interesting point about corporate governance, Aislabie. I agree that Japan’s corporate governance is arguably behind UK standards and even the standards of some emerging economies. For example, this article by The Economist notes that 'In 2013 nearly 600 of the 1,400 or so largest listed Japanese firms still had no outside directors, whereas South Korea, China and India all require them.' See here: http://econ.st/1V8TODB
However, while this poses risks, it could perhaps create opportunities too. We've noted that value investing has worked well in Japan. Many academics and practitioners argue that value investors get paid a premium as compensation for taking higher risk. This could be higher credit risk, or risk of underperformance, or in the case of Japan perhaps value investors are compensated for holding stocks with higher corporate governance risk.
No-one is saying that all Japanese companies have poor corporate governance, but perhaps major scandals involving blue-chips (eg. Toshiba) lead investors to paint all companies with the same brush, and many good quality companies in Japan become undervalued as a result. This would create opportunities for value investors and could help explain why value investing has been so effective in Japan.
Just a few thoughts. What do you think?
Best,
Alex
herbie47 - there is no doubt that Legg Mason has had a terrific year on this but looking at their top 10 holdings shows that they have concentrated in the medical sector, which has done very well, but I would expect that they will have to watch this like a hawk (as ,admittedly, they are paid to do!).
Only one stock of the top 10 is on a p/e below 35, and of the top 5 stocks two are loss-making and the other three are on p/e ratios of 54, 83 and 168. 4 are in the medical field
For these high octane stocks it is usually the case that they conform to the old adage "when they are good they are very,very good, and when they are bad they are horrid".
Yes it does look high risk. I sold mine in February.
I have only invested in Japan via funds. The Legg Mason IF Japan fund is up over 200% since January 2013 and up over 80% in the last year. This is better than any of the UK funds I believe, so maybe the locals should be buying? The problem I see is China, back in February when China was having a wobble then so did Japan. Mind you the Legg Mason is up 60% since then.
I believe the main reason for the inability of the Japan market to recover for any length of time is that a large part of the potential Japanese investors will not invest in their own markets. And a significant part of this is the domestic investors lack of trust in the governance of, and the published numbers of, Japanese companies.
This distrust is boosted by regular revelations ( Olympus and Toshiba come to mind) of wrong doing and concealment.
Western investors see these as exceptions and their buying for a while can boost share prices, but local investors suspect there us still much more hidden and fail to support this western investment.Any rally then runs out of steam and the prices subside.
The crash of the 89/90 bubble hurt so many people for so long that even in a prolonged zero rate environment people still shun the possible yield or gain from equities.
So when apparently good value comes from numbers that are not entirely trusted there is no way that the needed local investors will help drive momentum