Can Nick Scali’s quality overcome the headwinds?

Furniture importer and retailer Nick Scali (ASX:NCK) was established more than 50 years ago by the Scali family and listed in 2004. They raised $40 million in the IPO and have never raised any equity capital since.
During its listed life, earnings per share (EPS) has grown from $0.09 to $0.93, an annual growth rate of 14% over 18 years. The share price has increased from $1.00 to $10.09 (at yesterday’s close 09/02/22) and they have paid out $4.275 in total dividends. $10,000 invested into the IPO and held, would have yielded over $130,000 in profits or an annual compounded return of 17% per annum.
This demonstrates how investors can accumulate large amounts of wealth by investing in high quality companies, and then remaining patient despite the gyrations caused by pandemics, property cycles, exchange rates and share market sentiment.
Nick Scali has been a very well run business for a long period of time. It currently has a Quality score of 89 which reflects the very healthy state of the business both now and over time.
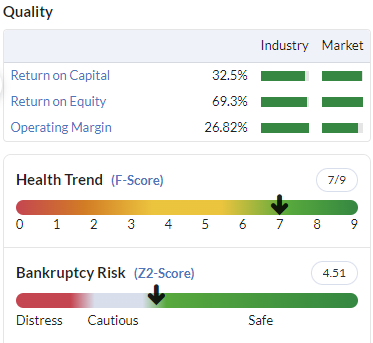
In financial year 2021, Nick Scali, like many retailers, saw revenue grow at record rates as people were restricted regarding travel and going out, so they diverted their spending to sprucing up their homes. But unlike many other retailers, Nick Scali’s revenue growth continued into 2022 and further growth is forecast for 2023 following a record first half.
However, a direct comparison is not entirely fair as Nick Scali’s revenue growth was not all organic. It includes revenue from Plush-Think Sofas which they acquired in November 2021. Plush added another 45 furniture stores to the 62 under the Nick Scali brand.

Source: Nick Scali, 1H FY23 Company Presentation, 6/2/23
The acquisition was funded through debt and existing cash. The purchase price of $103 million represented an EBITDA multiple of 3.8 which was not expensive.
Unlike many acquisitions this one is looking like it will add significant value to Nick Scali shareholders. They have already managed to strip out $20 million in running costs, which are synergy benefits that go straight to the bottom line, as well as paying off $17 million in debt.
On Monday (06/02/22), Nick Scali released their financial year 2023 half year results. Revenue hit a record at $284 million for the half. Net profit was also up 70% to $61 million. The prior period that is being compared with, only included 2 months of income from Plush versus the full six months this half year. The first half of last year also included extended periods of lockdowns in the eastern states.
Nevertheless, it was still a very strong result. Gross profit margins also rebounded to 62% helped by reductions in freight costs that had skyrocketed during the height of the pandemic. They had fallen to 61% last financial year as shown on the chart below. They have also seen big improvements in the gross margins at Plush from 54.8% to 60.5% as processes have become much more efficient.

Source: Nick Scali, FY22 Investor Presentation, 6/2/23
Despite this seemingly strong result, the share price fell 13% on announcement day and a total of 19% as at Thursday 09/02. Which begs the question, why? Admittedly the market as a whole also fell, but by not nearly as much.
It would appear that the declines were driven by a shift in sentiment regarding the outlook for the remainder of this financial year. Management expressed concern that rising interest rates may start to dampen demand, although so far they were not witnessing it.
Some of the commentary from the results presentation included that Nick Scali brand sales orders declined 3.0% but this is in comparison to the boom times of 2021. Further, written sales orders for January were 12.1% below January 2022. This includes price reductions of 5% to 10% in January which management expect to be a trend across the industry. In part this reflects their capacity to pass on some price reductions due to the benefits of the appreciating AUD, but the market probably also interpreted it as a sign that demand is softening. They also declined to give full year guidance, citing uncertainty about the coming months.
Typically Nick Scali earns a little over 50% of its revenue in the first half, although the last few years have not been typical. If this held true, they could expect to earn about $560 million for 2023. Market analysts were forecasting full year revenue of $537 million prior to the results release, and have since downgraded that to $523 million. They are forecasting a further fall in sales to $474 million in FY24.
There is no doubt that pressure is building as interest rates rise and property prices fall, however Nick Scali has ridden through many cycles in its history and has demonstrated it can come out the other side in good shape.
Since the results announcement analysts have made small upgrades to their FY23 EPS forecasts, but small downgrades for FY24.
From a valuation perspective some of the metrics are starting to look attractive following the price retraction. The Value score has risen to 87. The 12m forecasts] rolling PE ratio is only 9.8 and the dividend yield is 7.3% fully franked.
The short-term risks for Nick Scali are heightened as the uncertainties around inflation, interest rates, the property market and economy remain. However the company is conservatively managed and has an outstanding track record of steady growth over the long-term. The value proposition for the shares is much like that of Nick Scali’s lounges. A quality product at a reasonable price.
Important Information: Stockopedia Ltd ABN 39 757 874 670 UK business registration number 0637267 (“Stockopedia”) is an Authorised Representative of Daylight Financial Group Pty Ltd ABN 77 633 984 773 (“DFGPL”) which is the holder of an Australian Financial Services Licence (AFS Licence No. 521404).
Information in this commentary is current as at date prepared unless otherwise stated. However, please bear in mind that investments can go up or down in value, and that past performance is not a reliable indicator of future performance. For more Important Information please refer to the Disclaimer section of this website.
This communication may contain general financial product advice. It has been prepared without taking into account your personal circumstances, and you should therefore consider its appropriateness in light of your objectives, financial circumstances and needs before acting on it.
If our advice relates to the acquisition or possible acquisition of a particular financial product, you should obtain a copy of and consider the Product Disclosure Statement (PDS) before making any decision.
The author holds interests in the following stocks mentioned in this article: NCK. This position can and will change at any time without notice.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
2 comments
NCK is a quality company led by a quality management team, even though the 20% drop was a surprise it allowed me to buy more. Great article, thanks !!
Thanks Chris, your article on NCK cements my thinking/ opinion regarding this stock. Have owned it for many years in the past.
In recent times,since my strategy has changed to short term, I got out of it as it ran out of favour but re-entered about a month ago only to be stopped out again ( the perils of short term investing).
However, will be looking out for news on this stock going forward. Cheers