Can Santa bring me a lump of Coal this year please?

In this piece we delve into a sector with a disproportionate amount of high StockRank stocks, which is of course the Coal sector. And is it any wonder, they're all delivering quality earnings, they’re cheap and growth has gone through the roof. While the main incumbents like Whitehaven Coal (ASX:WHC) and New Hope (ASX:NHC) are well known, this Queensland operator that we are about to discuss is not as well established, however investors have supported the thematic and from a market cap perspective, it is not as large as the big guys.
Shooting fish in the Coal Barrel
One of the best performing sectors for 2022 was the Energy sector, in large part because it has been a stellar time to be exposed to the sector. A looming energy crisis in Europe on account of the war in the Ukraine has sent Thermal Coal prices soaring and whilst the mention of dirty coal can evoke environmental fears, this year, even the most naughty of investors would be happy with a lump of coal under the Christmas tree.
But while the well worn path of ASX:WHC Whitehaven Coal and ASX:NHC New Hope Coal has been documented by analysts one pocket of potential upside lies in Terracom (ASX:TER) . TER own a portfolio of operating assets in Australia and South Africa.
In Australia their operations reside in Queensland with tenements spanning an estimated area in excess of 9,500 square kilometres. This includes the Blair Athol project, its main producing mine that it acquired and restarted in 2017.
The company also has South African assets which it acquired when it purchased Universal Coal Plc (Universal) as at 30 June 2020.
Both these acquisitions are proving to be very shrewd. The South African purchase for example occurred when Thermal Coal based on the Newcastle pricing was just over $50 pt, today the Dec 22 contract is over $400pt.
StockRank score
Terracom (ASX:TER), like many other coal miners, has a very high StockRank(™) score.
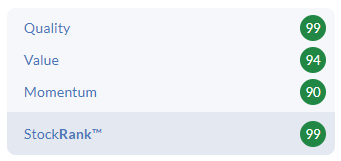
This is due to the quality of earnings, strong momentum in prices and earnings upgrades and the dirt cheap price they are trading at (most likely on account of the ESG discount). It's certainly not everyday you find a stock with a ROE of over 600% that trades on a forecast PE of 3.9x, but here we are.

Financial Health
FY2022 was a landmark year in many respects for TER as it was able to effectively wipe out all its debt by utilising recent strong cash generation.

This transformation of its debt structure has occurred due to the repayment of its Euroclear Bond during FY2022 (US$198 million including principal, interest and fees during a 9-month period).
When we look at the Altman Z2 score, the company is downgraded by the fact that it pays most of its earnings out to investors (rather than retain them) and most of its assets sit in its resources which are not overly liquid. Overall though, the company has manageable exposure to financial risk. Further validated by a strong Piotroski score and low earnings manipulation risk.


Piotroski F-Score

Beneish M-Score
Dividends
The repayment of debt has freed up significant cash flow to pay very strong dividends to investors. TER has paid quarterly dividends of 10 cents (7.5 normal and 2.5 special) in both September and December, and is committed to paying out 60-90% of NPAT in dividends in the near future.

The company has stated that it “... is committed to responsible capital management, maintaining a resilient balance sheet and delivering returns to shareholders.”
While there are no guarantees, with coal prices remaining elevated, despite there being no broker coverage of the stock, investors are hoping for a similar amount for the remainder of the financial year given the statements from the company at their recent AGM.
Even if they payout 15 cents for the remainder of the year, this would take them to an annual yield of 30% and that does not include special dividends or franking credits. With Free Cash Flow per share of over 40 cents, they can afford to do it as well. Even if the company chose to pay at the bottom of the 60% NPAT range, the annual dividend will be around 20 cents, which is still very significant.
The company of course retains the option to do other things with its cash flow besides pay dividends. While it seems unlikely they would make an acquisition at the top end of the cycle. They have said they will look to use excess cash flows in the following ways:
External Growth investments
Internal Growth investments
On market buy back
Additional shareholder returns
Leaders of the company have also been quoted as saying they would consider the sale of the South African operation if favourable terms can be achieved. This would be a further cash injection given one assumes the deal would net a large profit.
For the moment the company is effectively printing money.
Queensland Coal Royalties & Price Caps
But it is not just investors who have noticed this having lifted the price over 550% this year. The Queensland Government cottoned onto it too, introducing new tiers of royalty payments. This extends to all coal miners in Queensland.
Existing royalty:
• 7% for prices up to and including A$100/t,
• 12.5% for prices between A$100/t – A$150/t,
• 15% for prices above A$150/t,
Additional new tiers:
• 20% for prices above A$175/t,
• 30% for prices above A$225/t,
• 40% for prices above A$300/t
A back of the envelope calculation shows this will equate to an extra ~$750M in royalties from the Blair Athol project.
This royalty increase has been very lucrative to the Queensland government fundamentally changing the composition of their budget from an expected forecast loss for the 2022-23 financial year of $1 billion to now predicting a $5.l2B surplus!
The royalties though have had an impact on investment in the sector. For example the recent announcement from Glencore who ditched plans to develop the $1.3B Valeria coal mine and BHP refusing to commit capex to invest in the future of its BMA (BHP Mitsubishi Alliance) business.
Just recently the Federal and State (QLD & NSW) governments have reached an agreement to cap the sale of coal to the domestic market at a price of $125 Pt.
Legislation for example has been introduced by NSW to allow a cap on coal prices, and to whom coal can be sold to and to control its use.
NSW, which is Australia's largest exporter of thermal coal, produces around 200mn t/yr of saleable coal and currently exports around 175mn t/yr.Though after three years of above average rainfall reports of high activity at Newcastle Ports suggest that producers are making up for lost time.
It is important to note here that domestic sales are subsidised at lower term contract prices by significantly higher export prices. Therefore the impact of the cap is not expected to be too significant. But it is something to watch, because when governments get involved in this way, there could be further restrictions imposed.
Outlook
The fortunes of Terracom (ASX:TER) are intimately aligned with the hopes of the coal price. But operationally it is doing all the right things. Beyond paying down its debt obligations which has put it in a net cash position, it continues to sign off-take agreements for the Blair Athol project and powers on with capital expenditure on their other projects.
Pleasingly they are expecting an increase in ROM (Run of Mine) production from 12.6Mt to 13.4Mt this year. This should result in an increase in sales from 8.96Mt to 9.2Mt. They have started the financial year very well with 3.25Mt ROM produced and sales of 2.34Mt showing they are on track for another bumper year.
The company understands better than most that it is on a good wicket. But they will need to watch the rising costs of doing business as cost inflation starts to have an impact on earnings.
In an attempt to curb investor enthusiasm, the company has shared an opinion in line with most analysts that coal prices will moderate.

Though the company is quick to temper such a visual pullback in the expected price of coal, by reminding investors that these price expectations are still at levels much higher than 2 years ago.
It also says that in the short-term the price of coal will be driven by Russian reduction in gas supply to Europe (gas prices now are 10x pre COVID levels). This has resulted in gas prices being 2x the equivalent coal price, incentivising countries to likely substitute gas with coal. According to the company, this has resulted in Coal plant utilisation increasing and a number of coal plants being restarted.
It also points to a supply decline due to Russian sanctions. This is important because Russia supplies 1/3 of premium coal in the global seaborne export market of which 60% went to the EU, UK, Japan, South Korea and Taiwan some of which have banned Russian coal or have self-sanctioned.
The company also appreciates that the world is moving away from Coal. However its role as a reliable and secure energy source in the near term (should) continue to support prices.
The company presented this slide at its AGM. It highlights that its role will remain relevant as the world embarks on its energy transition.

According to this graph the company expects global demand to remain flat (still at elevated levels) until at least 2030 on the back of increased coal-fired generated capacity in emerging and developing economies which still remains quite strong.
Another factor likely to keep coal prices elevated for the minute, is that there is no new capacity coming online. Financing for new projects is almost impossible, and as evidenced by the QLD government’s recent royalty decision, companies are reluctant to invest in the projects themselves. So despite the price rise in the commodity, we are not seeing the usual influx in supply to offset the demand as we normally would.
I found this recent article from the International Energy Agency which explains the current coal situation quite eloquently. You can even download the full report if you wish to learn more.
The moral of the story is that demand for the near term remains robust.
Conclusion
Which is good news for the likes of TER, Whitehaven Coal (ASX:WHC) and New Hope (ASX:NHC) .
However in the case of TER, it has made a strong commitment to total returns (price + dividends) for investors. Should they continue to execute operationally and the price of coal can remain at elevated levels, then they offer the potential for investors to achieve total return gains above market.
And I just want to support Chris’ wish of a Merry Christmas and a healthy and prosperous New Year to you and yours. Thank you for your support.
Important Information: Stockopedia Ltd ABN 39 757 874 670 UK business registration number 0637267 (“Stockopedia”) is an Authorised Representative of Daylight Financial Group Pty Ltd ABN 77 633 984 773 (“DFGPL”) which is the holder of an Australian Financial Services Licence (AFS Licence No. 521404).
Information in this commentary is current as at date prepared unless otherwise stated. However, please bear in mind that investments can go up or down in value, and that past performance is not a reliable indicator of future performance. For more Important Information please refer to the Disclaimer section of this website.
This communication may contain general financial product advice. It has been prepared without taking into account your personal circumstances, and you should therefore consider its appropriateness in light of your objectives, financial circumstances and needs before acting on it.
If our advice relates to the acquisition or possible acquisition of a particular financial product, you should obtain a copy of and consider the Product Disclosure Statement (PDS) before making any decision.
The author holds interests in the following stocks mentioned in this article: TER. This position can and will change at any time without notice.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
8 comments
Hi Elio and Chris,
Please keep the stock analysis coming. The absence of local editorial and stock analysis was definitely the missing ingredient in Stockopedia Australasia and the reason I did not renew my membership before.
The Momentum Monday with stock suggestions is also great! I too am a convert to momentum investing, applying both fundamental and technical analysis. I can see how Stockopedia can be so useful in seeking out the right stocks for this approach to investing.
Thanks,
Wonga
Hi Wonga,
We will definitely be continuing with the stock analysis. Glad to see you have come back to Stockopedia. It is a really solid platform and will only get better with the local presence.
Have a great New Year.
Chris
Hi Elio
Any thoughts on Yancoal Australia (ASX:YAL)?
Yancoal Australia (ASX:YAL) owns coal mines in New South Wales, Queensland, and Western Australia. It was recently the subject of takeover talk with major shareholder China’s Yankuang Energy. Yankuang already own over 62% of YAL.
But in September they ended discussions for the potential acquisition of remaining shares citing ‘recent market conditions’. Which sounds strange given coal prices at the time were quite high (as a reminder the Board knocked back the offer of $1.8B, which at the time was a 16% discount (yes DISCOUNT) to the price (at US$3.60). Price has since recovered and surpassed the point back then. But it was a shock.
Chances are the low-ball offer was to get someone who wanted out, out. But the discount was unusual and it is one of the reasons why I have avoided the company till now . Yankuang has such a major interest it will play a large role in its future direction. Whereas if you want coal exposure without the vested interests, there are plenty others out there
Thanks Elio,
Merry Christmas and a happy, healthy and prosperous New Year to you ,Chris and your families.
Have a good break. The tremendous support this year with guidance and education was and still is, a pillar of strength. Look forward to a long association with you guys as you'll are awesome.Thanks for intro to Stockopedia
Warm regards
Sagie
We think you and Stockopedia are all awesome too. So it looks like the felling is mutual. Enjoy the break Sagie. We've all earned it this year.
Hi Elio,
Coal didn't have a good day yesterday. WHC -7.22%, TER -4.59% and NHC -1.68%. Any thoughts as to why and any reason NHC has a relatively minor fall?
Albert
Nothing out of the ordinary, other than often stocks that have had the best runs in price have the heaviest pullbacks when everyone gets nervous. And the market at the minute is very nervous.