C&C outlook brings cheer to a downbeat valuation

Analyst’s view:
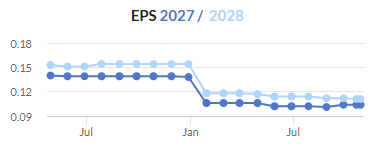
I was moderately negative on this stock at the start of the year, in the aftermath of its profit warning. Many months later, and with earnings forecasts holding steady all this time, I no longer see a need to maintain that negative view. This is a cheap drinks stock with no major red flags to my eyes. So long as it continues to responsibly manage its debt load, I think it's reasonable for investors to hope for better days here and ultimately a better valuation.
Up 4% at 105.6p (£391m) - Interim Results
C&C is the owner of Bulmers/Magners cider, Tennent's lager, a selection of smaller drinks brands, and various large alcohol distributers.
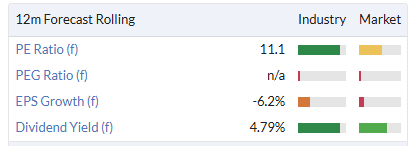
It has had a tough few years with a downturn in profitability and now the market refusing to give it a premium earnings multiple (only around 11x current):
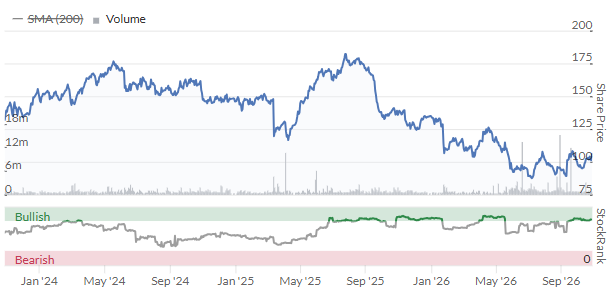
Today's H1 results are in line with expectations and despite a rather guarded outlook statement, the company says it is still "on track to achieve full-year operating profit in line with market expectations".
The fact that the share price is up on this outlook statement suggests to me that sentiment remains pretty poor. Note that the company warned on profits at the start of the year.
Let's take a quick tour of today's interim results:
Net revenue down 3%
Operating profit +4% with an improvement in operating margin from 5.1% to 5.5%
Adj. PBT +4% to €33.3m
There are unfortunately €6.9m of "exceptional" items (H1 last year: €6.3m), so we don't get a totally clean conversion of adj. PBT to actual PBT.
The exceptional items are mostly in the form of "strategic restructuring programmes" and I am not willing to look past these costs, especially since they are running over more than one 12-month period.
Overall, however, the company seems to be performing reasonably well. CEO comment:
“We have delivered a solid first-half financial performance, reinforcing our actions to build resilience in our business.
The general economic environment remains volatile, and we have the important festive trading period yet to deliver. However, we have strong trading plans in place for the balance of the year alongside a number of brand initiatives and the delivery of our developing innovation agenda, all of which give us confidence in our ability to meet market expectations for the full-year.”
Net debt is €114m, with a moderate leverage multiple of 1.4x.
Branded vs. Distribution: revenue growth was led by "Branded" (i.e. sales of branded drinks), up nearly 4%, with help from a hot summer and the World Cup.
"Distribution" revenue fell by 5.7% but this worries me less as it's low-margin work. The company says the revenue decline was "principally driven by the planned exit of some lower-margin customer business, combined with the on-going impact of market attrition across outlets and underperformance in some wine and spirits categories."
Graham's view
I was moderately negative on this stock at the start of the year, in the aftermath of its profit warning.
Many months later, and with earnings forecasts holding steady all this time, I no longer see a need to maintain that negative view.
I will say that perhaps the company could have done a little better, given the very hot weather conditions this summer and the correlation between hot temperatures and cider sales. It's also true that this was a World Cup year - so I wouldn't expect a stronger performance in 2027.
Overall, though, this is a cheap drinks stock with no major red flags to my eyes. So long as it continues to responsibly manage its debt load, I think it's reasonable for investors to hope for better days here and ultimately a better valuation.
At around the current price, the dividend yield is almost a good enough reason on its own to take a second look at this (figures below based on last night's close).
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on C&C (0)
Comments here are also visible in the Daily Stock Market Report
No one has commented here yet! Why not be the first one?