CMC Markets: benefitting from volatile markets

Welcome to the latest in our new series of short-format Stock Pitches. We’ve covered CMC markets a few times on Stockopedia, most recently as one of Ed's 2026 NAPS. I wanted to highlight it now, not just due to its Super Stock status, but because it is a company that should benefit from current market conditions.
Disclosure: At the time of publication, I have a long position in CMC Markets.
The Pitch
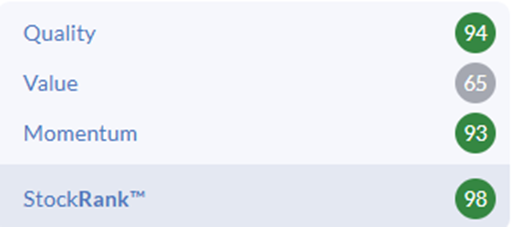
CMC Markets (LON:CMCX) is a Main-market-listed FTSE250 online trading platform founded in 1989 by Lord Peter Cruddas. The company currently has Super Stock status, with a StockRank of 98, and top decile Quality and Momentum scores:
After delivering good results in November, the company said a strong start to H2 meant Net Operating Income would be 10% ahead of expectations. This is before the recent bout of volatility that has affected not only equities but also commodities and currencies.
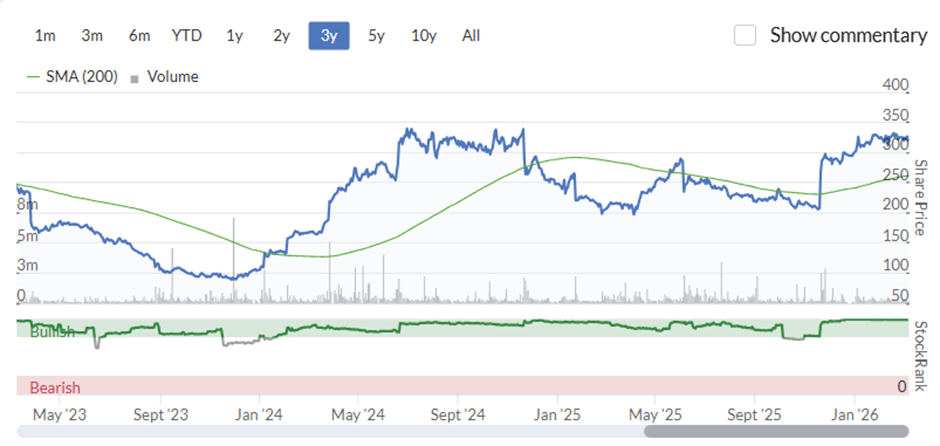
When markets move sharply, CMC’s clients’ trading surges and revenues follow. After suffering from low volatility in 2023, revenues declined by over 30%. Net operating income and the share price have since recovered:
H1 FY2026 delivered net operating income up 5% to £186.2m, with management reporting that the volatility observed during the summer contributed to improved performance. With the company saying that they expected to exceed revenue consensus by 10%, the shares now trade on a forward P/E of 11. But with the chance of a further volatility-driven upgrade, CMC represents a leveraged bet on continued market turmoil.
The Big Picture
CMC Markets has several features that mark it out:
- Volatility winner: When global markets respond to the latest geopolitical news, it can be incredibly hard for investors to know how to respond. The spot oil price has risen in response to the closure of the Straits of Hormuz, but what happens if this is short-lived? Have equities responded too rapidly, or not quickly enough? Should investors buy, sell or protect themselves via options? None of these considerations matters to CMC markets, which benefit not from directional calls, but because markets are moving and this attracts trading volume.
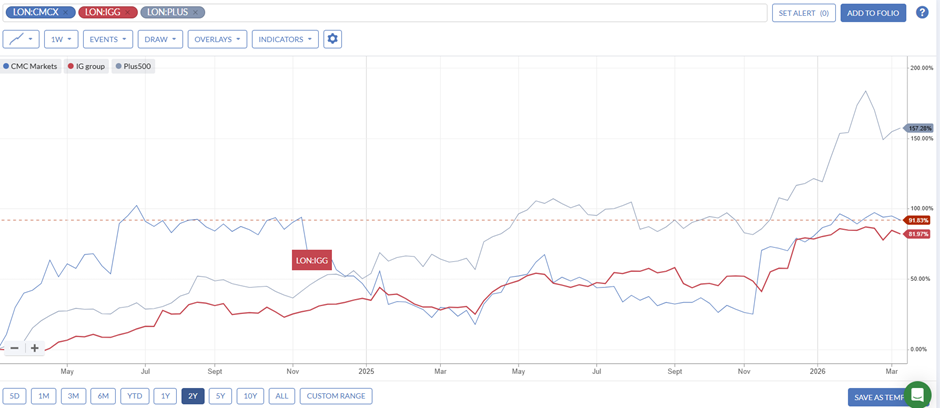
- Dynamic Hedging: Very simply, CMC sit somewhere in between IG Group and Plus500. Whereas IG tend to hedge all client positions and benefit from the spread, Plus500 hedges far less and banks on clients being losers, on average. CMC follows a dynamic hedging strategy, hedging some risks but not others. This usually enables them to capture much of the upside, although at the cost of additional risk. However, their share price has performed much more like the more staid IG Group over the past two years:
- New Markets: As a volume-driven business, the company is always looking to add new trading assets or extend trading availability. They have recently added weekend crypto trading, which increases availability by 104 trading days annually. 24/7 access for indices, commodities, and equities is being rolled out, enabling round-the-clock volatility capture.
- Shareholder alignment: Lord Cruddas founded CMC in 1989 and retains 59% stake. The vast majority of his wealth remains tied up in this venture.
- Diversification: They don’t just provide spread betting and CFDs. Their Australian Investing arm delivered a record H1, with A$65.9m in net operating income (up 34%) and A$91bn in assets under administration. This provides stability, though trading remains core to the business.
Going Deeper
Several factors suggest CMC could outperform significantly if volatility persists:
- Record Client Cash Dry Powder: Management reported retail client cash balances at record highs and growing strongly. This converts directly into trading activity when volatility spikes, creating strong H2 tailwinds.
- Upgraded Guidance: FY2026 net operating income guidance was lifted by 10%. This came after observing summer volatility and strong H2 momentum, suggesting management expects strong performance to continue.
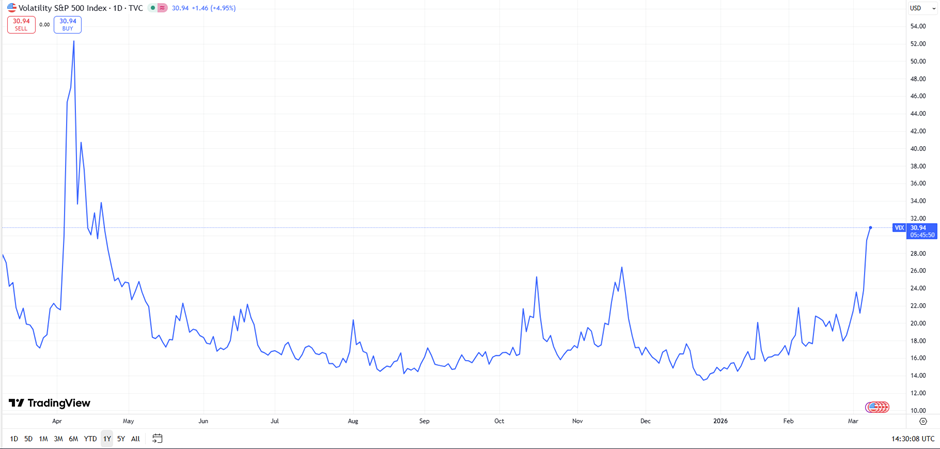
- Perfect Macro Setup: Geopolitical tensions, policy uncertainty, AI-driven swings, and trade conflicts create ideal conditions for sustained volatility. CMC is explicitly positioned to benefit from these crosscurrents. The VIX, a measure of expected volatility for the S&P 500, has spiked recently:
[Chart: TradingView]
However, equities are not the only asset seeing large moves at the moment. Energy and commodities have seen large price swings, and many traders and investors will be looking to hedge exposure, as well as make directional bets.
- B2B Growth: A partnership with Westpac in Australia was announced in September to white-label web and mobile platforms that integrate directly with Westpac's existing technology. This is CMC's largest institutional deal to date, giving it access to Westpac's base of approximately 13 million customers.
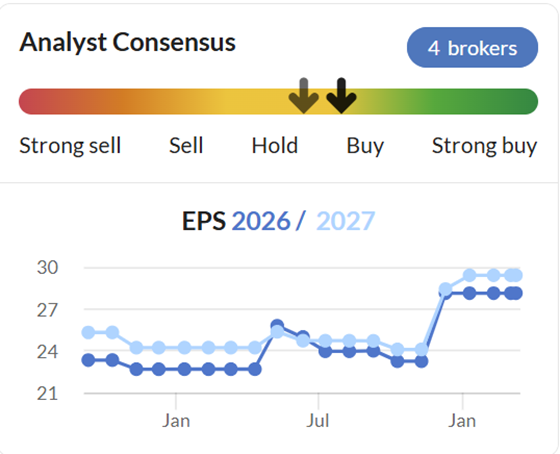
- Operational Gearing: A fixed-cost base means incremental volatility-driven revenue drops straight to the bottom line. This leverage magnifies profit impact during volatile periods, as demonstrated in 2021-2022. More recently, a 10% upgrade to NOI expectations led to the EPS consensus rising by 21%:
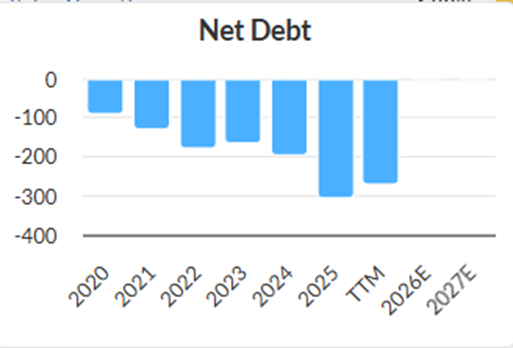
- Cashflow king: The company requires little capital to operate the business, and development expenditure is expensed, meaning that operating cash flow regularly exceeds EPS and turns almost entirely into free cash flow. This can be seen by the increase in net cash in recent years:
They have a policy of paying out half of EPS as dividends, giving a forward yield of around 5%, perhaps higher if earnings increase due to recent volatility.
What The Brokers Say
The company helpfully provides the analysts' consensus on their website:
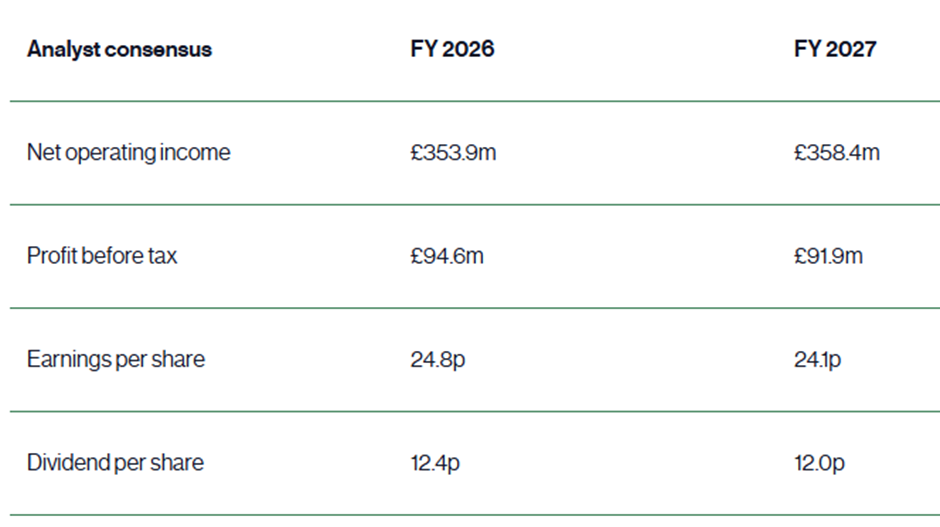
Five analysts cover them. However, unhelpfully, none of this coverage is included on Research Tree. From what I can tell, broker Price Targets are similar to the current price level, and the predominant rating is Hold, which doesn’t give much confidence in the upside potential. However, brokers have been known to be behind the curve (in both directions) when market volatility changes significantly, and notably, there have been no broker updates since January.
The Bear Case
- Volatility Can Evaporate: The volatility thesis cuts both ways. While volatility tends to cluster and current market conditions are most likely to persist for some time, there will be a time when more benign conditions are the norm, and the company’s revenue may suffer.
- A controversial CEO: Lord Cruddas is a controversial figure. In 2012, it was alleged that he was involved in a “cash-for-access” scandal while serving as the Conservative Party treasurer. Boris Johnson nominated him for a life peerage, overriding the parliamentary watchdog.
- Poor employee reviews: On Glassdoor, the company only gets a 2.7 out of 5 rating, with just 21% of employees leaving a review approving of Cruddas as CEO, and 26% recommending it to a friend. The most common complaint seems to be a lack of flexible working, with 100% office attendance expected.
- Regulatory Risks: The Australian regulator ordered client compensation in November 2024. An ongoing class action involves 2,500 clients who allegedly failed screening but traded anyway.
- Buzzword Bingo: Recent results have contained lines such as this from the H1 results: "…are pushing aggressively into Web3 technology because of the pending decentralisation of financial markets (DeFi) through product tokenisation, blockchain, multiasset wallets and stablecoin clearing and payments." How exactly these translate into higher revenue and profits is not explained in plain English.
The Bottom Line
CMC Markets is one of the purest plays on ongoing market volatility. While direct volatility exposure via options incurs time and funding costs, investing in CMC Markets yields a roughly 5% dividend.
The FY26 setup looks compelling. Record client cash, dynamic hedging, and 24/7 trading mean CMC can capture volatility-related upside better than ever. The macro backdrop - geopolitics, policy uncertainty, AI swings - all suggest that elevated volatility will persist for some time. A largely fixed cost base means that any increase in net operating income will drop straight to the bottom line and drive significant upside beyond current guidance.
The company has the scope to keep growing the number of assets that customers can trade and the availability of those trading instruments. However, it is not without competition, and new markets and instruments can entail greater implementation and regulatory risks. At the end of the day, this is a company that should benefit from declines in global equity markets and may provide a useful hedge for those with significant equity exposure elsewhere.
Disclosure: Mark has a long position in CMC Markets.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

6 comments
Also enjoying the more regular pitches and CMCX is also a 'long-term' hold for me.
Many thanks for the discussion on volatility - valuable thinking.
thank you for a succinct and fair summary. I bought recently because in their last TU they said that they had 2 deals of potential similar size to Westpac in the pipeline - one with a MAJOR UK bank which they expected to complete early in 2026. I think this will give the profits recovery a step change in scale. The chart looks very strong and if it can get > 330p it is a very clear break out that would indicate an eventual price of c.500p within 18 months. disc i hold.
Director big holder might sell the business also.
Really enjoying the more regular pitches thanks all!
Held for a good while now, tasty dividend yield is the icing on the cake. "Solid" long term hold for me.