Communisis (CMS): Paper profits

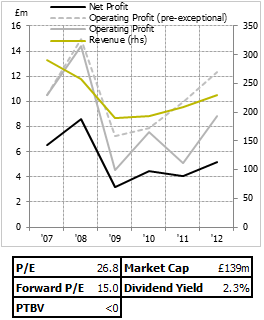 Communisis (LON:CMS) are a business engaged in, ostensibly, a very boring activity. You might argue it's become more interesting in the last few years; they went from being a company mostly involved in the printing of cheques and direct mail to a more 21st Century provider of 'communication services'. They talk about integrating with their customers, providing bespoke solutions and about investing in higher quality printing methods - they made a big deal of acquiring an enormous high-tech printer a while back. Fortunately, both for us and them, the picture they paint of themselves isn't an entirely typical rose-tinted management view of the business; it is slowly being borne out in the figures. Margins are on an upward trend, the contracts they are winning seem to be tilted towards the more value-added end of the spectrum, they're closing older (and more standardised) sites and - perhaps most importantly - their higher margin segment is claiming an increasingly large share of group revenues.
'Slowly' is something of a key word here; by virtue of the sort of stuff they do - handle customer communications and printing services - Communisis runs fairly long contract times, and even longer customer relationships. A significant bulk of the work they do, I reckon, is still the bread and butter stuff. That's not a bad thing; customer relationships are valuable, after all, and doing the bread and butter stuff allows you opportunities for cross-selling. That potential seemed to be exemplified this week, when Communisis announced another contract win with Lloyds, a half year after their first - itself a big deal since it represented the 'largest contract of its kind in the UK'. Management are, as usual, a bit light on the details - I suppose for corporate confidentiality reasons - but we have at least a few hints. They're taking on '14 existing sites' in the UK, for instance, and '310 roles will transfer to Communisis under TUPE arrangements'. TUPE - for those who don't want to Google it as I had to - is the maintenance of existing staff contracts when the operator changes hands. I can only broadly guess with these figures - and I emphasise the broadly - but it does allow us to make some comparisons. We might, for instance, note that Communisis as a whole currently employs about 1,500 people - so 300 more represents about 20%. We might suppose the average staff member at one of these sites would earn ~£20k a year, multiply that by the number of employees (giving £6m) and compare that to the total wage expense for Communisis as a whole - about £51m - and consider that a figure of roughly 10%. These are nothing but guesses; but it should be evident that the contract is clearly quite material. Lloyds isn't the only company signing up for their services, either - all of the UK's top ten building societies use Communisis's services, as well as numerous other blue chip clients.
What I'm trying to say, in a roundabout way, is that momentum here is good. Things are clearly going in the right direction, and while I usually mean that in the sense of the figures in the chart top-right, in Communisis's case I mean it in an operational sense. The figures are lagging these contract wins. The more regular readers of this blog will probably realise that this is critically important for me - I'm not in the business of holding businesses which have a P/E of 27 without a good reason to do so. Growth is an excellent reason. I'm also comfortable with the adjustments the group makes to go from reported profit to underlying profit - I think the underlying profit is a better figure. If I take the operating figure on that front, deduct interest charges and taxation, the historic P/E is closer to 18. That's not cheap, of course; the valuation is still predicated on growth.
Returns on capital are also great at Communisis; growth is, thus, valuable. Management are still bullish on meeting their 10% margin target in the next few years, which again gives us some sort of baseline for looking at the future. Should revenues grow 20% in the next 3 years - to £300m - management meeting their target would pencil in an operating profit figure of £30m. Since the group needs relatively little capital to create that topline growth, debt shouldn't balloon too rapidly - so we might expect finance costs to remain broadly flat. £27.5m of operating profit is clearly a good sum for a group trading on an enterprise value of about £180m, and is even better if the group is still growing then.
There's a lot of 'ifs' and 'shoulds' in my last paragraph - words I dislike intensely. Ifs and shoulds often turn to disappointments when you're forecasting improvements. Why am I still holding on, then?
Well, there're a few reasons. I did trim my position in Communisis last year, so my exposure to it isn't huge - keeping my original purchase post the significant price rises would have signalled a level of conviction not commensurate with that which I actually feel. Management have delivered, though, over the last few years - and delivered in a pretty consistent way. I like their investment plan, and I like their business plan. I also like the contract wins coming out of the business and the increasing contribution from international sources. For the third time this year, I'm also going to do something which - while having worked before - I might come to regret. My strong hunch, given the figures we have, is that the full year results from Communisis will be above where broker expectations currently sit; and broker expectations are pretty bullish at the moment. Operating profit might well disappoint - there are restructuring costs (the group reckons it'll save £4m a year from them when they finish up) - but I think the underlying figures will impress. Two or three years down the line, I suspect broker forecasts are likely to understate it by more.
So I'm holding. I bought it for clear value reasons - I thought the group was misunderstood and cheap. I'm running the winner for reasons a bit more ambiguous. I'm not in love with the company at this price, but things are definitely going right for Communisis at this point in time. I hold in full knowledge that disappointment will mean a downward re-rating. My baseline scenario leaves it with a little upward value. I don't have a bullish scenario; but there does appear to be a possibility for Communisis to continue winning contracts and increasing their provision of services and there's a good amount of value here in that case.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
No comments yet
No one has commented here yet! Why not be the first one?