Cosol: Taking care of the pennies and pounds with software

With the cost of business rising and the availability of resources drying up, it is not surprising that some corporations are enlisting the help of third party providers to help them become more efficient, and therefore remain competitive.
No longer are such exercises seen as just simply the imposition of costs to a business. If done effectively it can be a net benefit for a company as it is able to operate more efficiently.
Cosol (ASX:COS) is one such company that is helping industry to run its assets more efficiently using a selection of proprietary IT platforms and its advisory services.
COS has been in operation as a business for over 20 years, however it listed on the ASX in January 2020. Listing at 20 cents, the stock had a quick and meteoric rise, however has tailed off since then. However at a price of 76.5 cents as at (05/01), COS will go in the record books as one of the ‘good’ IPOs that rewarded initial investors handsomely.
Let’s fast forward the business to today and assess it moving forward.
The company actually formally refers to itself as, “…as a global leader in digital transformation and data exploitation”. This is a fancy way to say that by using data and analytics they help organisations operate their plant and equipment more efficiently, and therefore more profitably.
They service sectors where large and complex assets are being operated and where small improvements can make a very big difference to the bottom line.
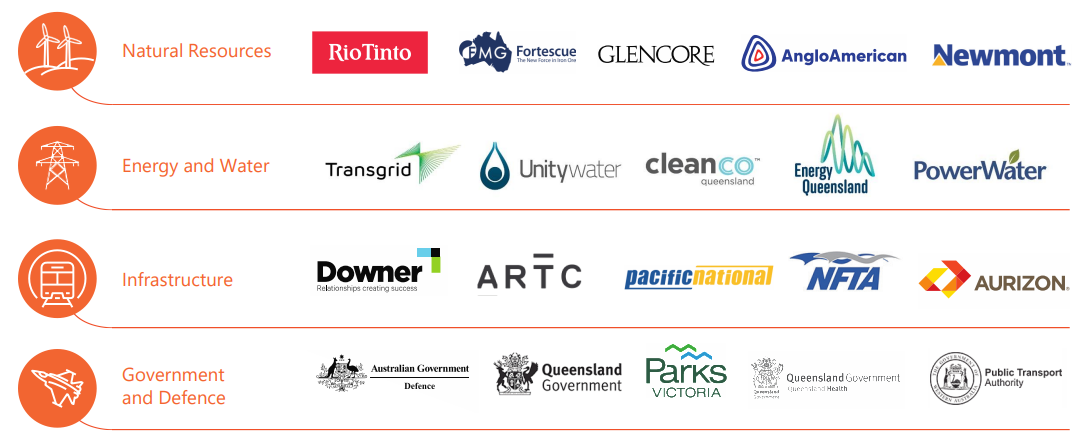
COS’ services cover a range of industries. Divisionally the company is broken up into the mining, utilities, public infrastructure and defence industries. For a little company (market cap $108m) they have an impressive list of major names as clients.
At the moment around 80% of the company’s revenue is generated from within the Asia Pacific region, however the North American business is growing (17% of revenue) following recent acquisitions, and the company has high hopes for the region and has been delivering some solid results to support its belief.
StockRank ™
The StockRank for COS is 80 though it has been bubbling along this level since the company’s full year result in August, and finally crossed above 80 for the first time in October 2022.
The standout element is the quality score of 91.

This score driven not only by the strong return on equity and capital employed (as shown below), but also by the company’s strong cash generation

The company’s financial health also remains quite robust and aligns with their quoted investor statement, “COSOL is all about profitable growth” which was once again reaffirmed at the latest AGM.
To see a company that provides these types of services deliver strong profits and cash flow is very pleasing, as many participants in the IT sector who say they deliver similar services are often not even cash flow positive, therefore this is a big feather in their cap.
Why the average Momentum and Value ranks?
This is an interesting observation. Why is a company with such a high quality rank not yet be fully recognised from a Momentum perspective, or trading at a much larger discount?
As always with any quantitative driven system the reason is in the numbers.
Let’s start with Value Rank first. Given the fact the stock trades on a PE of 20, there is a fair argument to suggest that the stock has been recognised by the market as this would appear to be fair value relative to peers. The good news is the PEG is below 1.0 and the company is expected to continue to grow earnings into the future (more on that in a moment).
Other factors which drag the Value Rank down are the lack of dividend history and the slightly elevated price to book value. However it is important to note that we are relying on historical numbers for these calculations as no analysts are covering the stock yet. Therefore it ignores the current growth trajectory that the company is on.
Which takes us to Momentum, and COS is a business that is well and truly under the radar. There are no quoted broker estimates on the business, which means that the no earnings momentum figures can be applied to the model.
From a price momentum perspective though the stock has done incredibly well scoring greens against all timeframes and measures.

From a more immediate charting perspective, following the peak post IPO, the stock had been on a steady downtrend.
However the company has seen a new higher low, and higher high and it broke through resistance at 70 cents that the price had butted its head against a number of times between Aug 21 to Nov 22. The pullback to 70 cents post the breakout is a positive indicator that the latest run may have more legs to go. 70 cents is now the support level for the price moving forward.

ASX:COS weekly chart since IPO in February 2020.
Shares on issue, director’s ownership, liquidity and dividends
Since listing there has only been a small increase in shares, much of that issued as part consideration of acquisitions that the company has made (most recently the company issued 5.6m new shares as part consideration of Work Management Solutions (WMS). With the company sitting on a strong cash balance, it is unlikely that it will need to raise funds again, unless it makes another strategic acquisition, and that would have to be assessed on its merits at the time.
Two directors, Geoffrey Lewis and Stephen Johnston own a combined 32% in the business. Both joined prior to the ASX listing from former IT services firm ASG Group Limited (formerly ASX listed, ASX:ASZ) before it was taken over.
Investors should note however, that liquidity may be an issue with this stock despite what appears to be OK daily trade amounts as it is susceptible to days of none-to-little trade. Therefore a position in this stock must be considered from a long term perspective as short term traders may be stuck holding the can if the rug is pulled from under them, or there is a need to exit the stock for whatever reason. A holding in this business will likely mean investors would have to continue holding it through the cycle.
The company has consistently paid 1 cent dividends every six months. Investors will be hoping that with the continuing earnings and cash balance increases, that there is a chance that these will be lifted in FY23. This will be dependent on any further acquisitions the business may make in the future.
Outlook
While there is no analyst guidance to frame any thoughts on this, fortunately the company is open in disclosing its view as to what their prospects will be like.
At the time of its AGM the company told us that they expect their first half revenue to be between $35m and $36m at 14% EBIT margin.
Last year for the full 12 months they achieved revenue of $48.3M, so this shows significant growth on the pcp continuing their history of growing quite aggressively.

But it isn’t all chicken and champagne. The margin of 14% is actually a fall from the previous 16.7% it achieved in 2022. The reasons for the expected decline provided by the company were investment in streamlining further the business, integration costs of acquisitions and the integration of WMS which is a lower margin business.
However despite the margin decline, the growth in revenue is most pleasing. The company has started FY23 with some significant contract wins and the contributions of Clarita and WMS to the core platform have been welcomed by COSOL’s customers, who are keen to pursue further services.
Some of the recent news supports that. The recent new agreement with the Australian Department of Defence was an extension on a previous agreement. This contract is for A$8.2m until November 2023 (11 months), whereas the previous agreement was for A$8.5m for 19 months - which was a renewal on a previous agreement.
Further in December the company provided an update on their new business wins in North America worth a combined circa A$4 million. While this amount is not yet overly significant it does provide some confidence that the company's holistic offering is gaining traction, further validating the Clarita and WMS acquisitions.
Conclusion
The thematic makes sense and the recent aggressive growth by the business substantiates it, as companies look for more efficient ways to use their assets and resources to generate an optimum return. And when we are talking about the sectors that COS focuses on, even the most marginal of improvements can have a massive impact on the bottom line.
Important Information: Stockopedia Ltd ABN 39 757 874 670 UK business registration number 0637267 (“Stockopedia”) is an Authorised Representative of Daylight Financial Group Pty Ltd ABN 77 633 984 773 (“DFGPL”) which is the holder of an Australian Financial Services Licence (AFS Licence No. 521404).
Information in this commentary is current as at date prepared unless otherwise stated. However, please bear in mind that investments can go up or down in value, and that past performance is not a reliable indicator of future performance. For more Important Information please refer to the Disclaimer section of this website.
This communication may contain general financial product advice. It has been prepared without taking into account your personal circumstances, and you should therefore consider its appropriateness in light of your objectives, financial circumstances and needs before acting on it.
If our advice relates to the acquisition or possible acquisition of a particular financial product, you should obtain a copy of and consider the Product Disclosure Statement (PDS) before making any decision.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
No comments yet
No one has commented here yet! Why not be the first one?