CUV - Is it safe to come into the light now?
Today we discuss a stock which has taken a winding path to get to here from its early days, with a share price that reflects that volatile journey such has been the path of Clinuvel Pharmaceuticals (ASX:CUV) who are experts in melanocortin (small protein hormones) chemistry and biology.
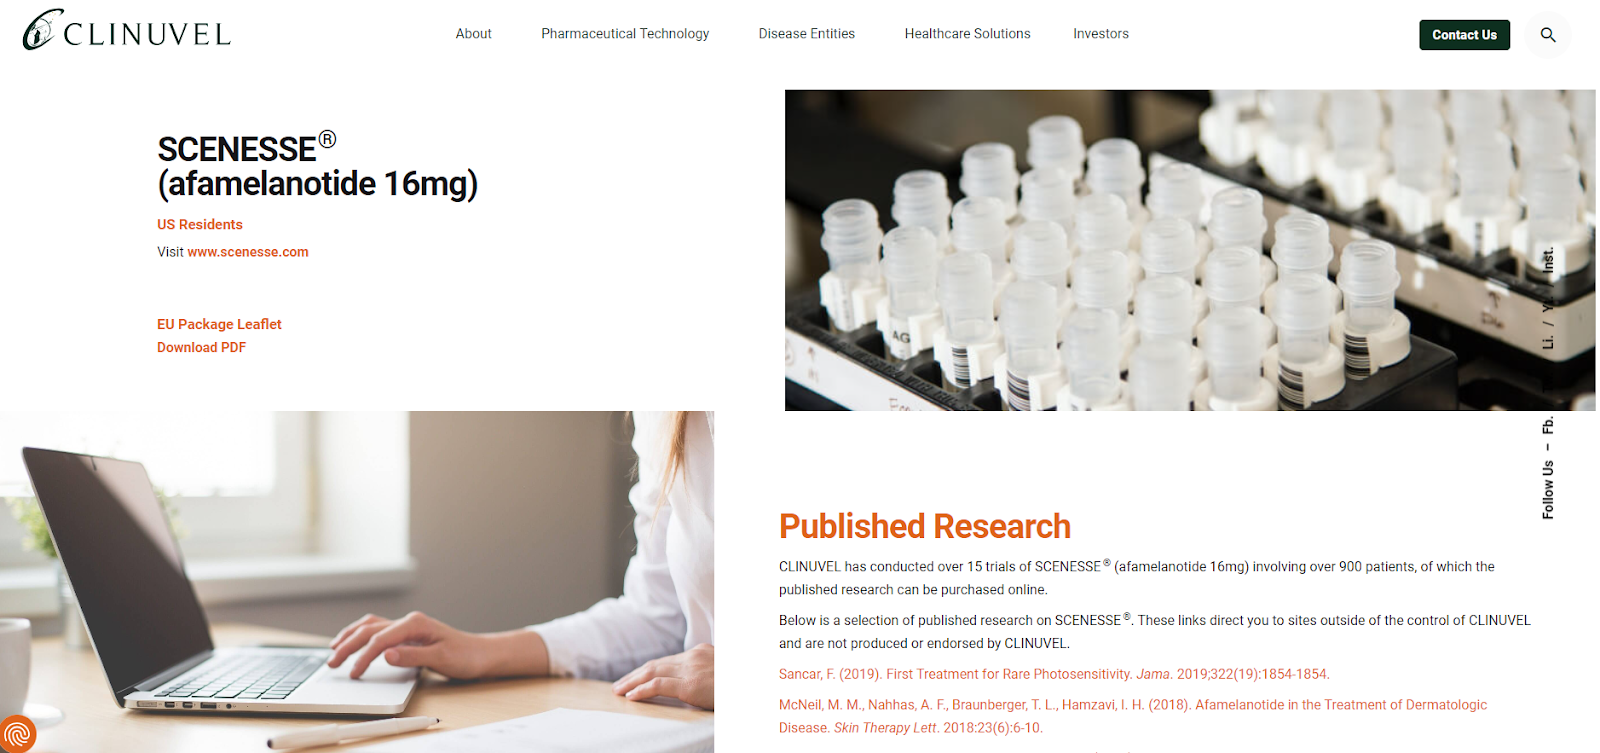
CUV first started its journey listed as Epitan - which at the time sought approval for a chemically induced ‘fake’ tan. It was renamed in 2006 as CUV. Initially the solution was knocked back by the FDA, but in 2005 when an Australian team licenced the molecule, they set about maximising the medicinal benefits of the significant improvement in sunlight tolerability that the molecule delivered in testing to its subjects.
This led the researchers down the path of the rare skin intolerance condition erythropoietic protoporphyria (EPP), a rare metabolic disorder that causes painful photosensitivity to both natural and in some cases artificial light. Further it can lead to liver disease and gallbladder dysfunction. I will stop with the medical science there (there is a lot more on the company’s website, within their reports and on Google if you are interested.)
But the outcome of all this is development of the peptide afamelanotide which is sold to market as “Scenesse” and is used on adults who suffer EPP. I mentioned the disease was rare. In fact the drug has only been administered some 14,500 times over the past 17 years globally. According to the company's website,1400 individuals globally have received Scenesse. The drug can cost between $90,000 - $140,000 though many governments subsidise the treatment for those that suffer from the terrible affliction.
The sales of Scenesse have supported the business for some time as it goes about its R&D work which is quite significant (and we will discuss in more detail within the outlook section) and despite the small cohort, the earnings performance have reflected the difference they have made to its patients. But as alluded to in the introduction, the price has had a wild time of late falling ~60% from its peak in September 2021. So one asks, is CUV ready to step out into the light once more?
Quality
CUV is highly profitable achieving a consistent operating profit margin of above 50% in the last few years. And with the exception of the COVID impact, the company has managed to grow operating and net profits every year since it first became profitable in 2017. In fact profits are now four times greater than they were back then.

Further supporting the idea that COVID was a blip, revenues in 2020 actually rose that financial year showing the resilience of earnings.

CUV Annual report
Currently the company has a Quality Score of 97 which is the highest ranked component of the overall Stock Rank score placing it within the upper tier of Quality stocks on the exchange.
The high score supported by ROCE and ROE above 20%, low Bankruptcy Risk and a Piotroski Score of 6. Further earnings manipulation is rated as low - which for a pharmaceutical company can be quite rare and is pleasing to see.

That last point is also reflected in the company’s growing cash balance and regularly strong free cash flow per share results.


Value
Like many profitable biotech stories the stock rates poorly from a Value perspective. Currently 22 out of 100. This despite the significant pullback in price.
However I feel that a company with sellable products in the US and EU plus a strong pipeline of coming work does deserve a premium.
If there is any consolation, bak when the stock was $43.26, the value score was 4. Prior to the company’s latest annual result the result was 15. Therefore notwithstanding the weak Value Rank, it has been improving.
Further the stock compares favourably to other piers, providing some comfort.

Despite all the above, don’t expect “Benjamin Graham” on the register. Not only because he has passed on... (CUV can’t help with that!), but because by traditional value metrics, it’s not cheap.
Momentum
Here is where I feel the story may be getting interesting and one of the key reasons why I bought into it recently after a long hiatus (plus another reason which I will cover in the outlook section.)
The Momentum Rank is currently 82. Before the company reported it was 73. It even started the new financial year at 56, therefore there is an improvement there. Improvements in the 2024 and 2025 EPS expectations plus the price has moved above the 50 day moving average and is rapidly approaching the 200 day moving average, resulting in the traffic light turning green.

The chart itself is showing some interesting signs. Below is the 5 year weekly chart

ASX:CUV Weekly chart 5 years
While the high of September 2021 stands like a beacon, readers will note the price retraced all the way back down to the $13.45 - $14.15 range which was first seen back in 2018. From that point support has been tested a further three times ( March 20, June 22, September 23) making this a significant level of support.
Further the weekly RSI has just turned positive and whilst still below the zero line, the fast moving average has moved above the slow moving average.

The upside target and good position to take profits would be around the $28 mark close to the previous lower high. Maintaining a position beyond that point (should it get there) will depend on the price action and company developments.
But with strong upside price potential ahead of it and a historically strong support level beneath it (though some 20% now from current levels) the short term rebound since October may be worth supporting (or at least I thought so).
Outlook
When it comes to any pharmaceutical business, looking at the company’s outlook is essential to understand what is in the pipeline for future growth catalysts. Of course this carries risk and investors require patience to let the scenarios play out. But on the surface the pipeline looks full. I will discuss each of these in tow (Note: This is only a general overview and is not too technical in description. You may wish to conduct a more thorough investigation. Refer to the company's website for more details.)

AGM Presentation 2023
Use of Scenesse in Adolescents Expanding the use of Scenesse with Adolescents is a priority with the review process in the final stages of a number of countries. Adolescents are the age group from 12 17 years. This makes immediate sense and the company would hope for little in the way of obstruction there.
Treatment of Vitiligo Vitiligo causes gradual loss of skin pigmentation. Unfortunately this autoimmune disorder is often referred to as “Michael Jackson” syndrome, and the condition is most prevalent and impactful for those with skin of colour. This is next in the company's pipeline and is seen as a superior solution to current immune-suppressant solutions like Incyte’s Ruxolitinib, Clinuvel’s afamelanotide is now in phase III studies with the first patient commencing treatment in October with plans to do tests on 200 adolescent and adult patients. The study which combines afamelanotide with narrowband UVB, has a primary endpoint for 50% body surface repigmentation - something it has achieved in previous trials. The company sees the addressable market for this product to be between US$490-US$570 Million with an almost immediate uptake.
Porphyria treatment. Both Erythropoietic and Variegate results in damage to skin in the form of blistering skin lesions caused by being exposed to the sun that are very slow to heal. The company believes the market size is US$300M.
Xeroderma Pigmentosum. Melanocortins have long been shown to optimise the cellular signals needed to effectively protect against UV-radiation, and enhancing these signals gave us the ability to commercially launch the first melanocortin afamelanotide as a systemic photoprotectant. The company believes the market size is <US$100M
Arterial Ischaemic Stroke The company is working on a fast-acting afamelanotide variant called Penumbra, for use in strokes and vascular disorders when current declotting medication is not appropriate. The company feels if successful this could service a multi-billion market.
There are another range of treatments that the company is looking into researching that are too early to mention here. But one plan that does deserve a mention is the intention to sell over the counter products that it calls PhotoCosmetics. When discussing the opportunity, Managing Director Phillippe Wolgen noted in the annual report, “In essence, we are closing the circle, we are delivering on an expectation that came with the birth of melanocortins, as these had first been introduced in 1980.” While the addressable market is estimated to be worth US$6.2B, the company hopes to achieve penetration of the market by some 1% in the first five years giving it US$60M. One key distinction tomake here though is the company is targeting its messaging on the products being more a skin cancer prevention product rather than a fake tan tool (which it calls a 'bronzer' solution), but with such large potential it is very exciting. Melanocortins have now had years in the field and are considered safe and for a pharmaceutical company to translate its pharmaceutical programs into consumer focused products is unique. It only started its first pilot program in Europe.

Risks
I don’t need to tell experienced investors of the obvious risks involved with pharmaceutical businesses, especially those with trials currently in the field.
Even what would appear to be the most certain of bets can come undone with just one cohort of poor results. Therefore, notwithstanding that Scenesse has been in the field for some time, and the early signs from the Vitiligo tests look exceptional... There is a risk that they don’t work. Investors best remember this when considering CUV.
Beyond the other standard pharmaceutical risks like regulatory, financial, valuation and intellectual property risks, there are some other risks to consider.
This includes competing technology risk. Given how lucrative the opportunities are for the business there will always be some keen for a slice of the pie. For example in 2021 the stock fell heavily on reports of a competing product from Mitsubishi for the treatment of EPP. One of their phase III studies finished last year. Another that was due to complete this year has been extended out to the end of 2024 with past trials experiencing nausea and freckle development. (Either way even if approved it won't be till 2026 till it gets onto the market - and then it has to convince physicians its product is safe.)
Distribution is key for any pharma business and CUV has a long standing policy of going it alone. While this has its benefits, it carries risks as well as it puts extra pressure on the business to perform.
The other key risk investors should be aware of is key person risk. Since assuming the role of CEO in 2005, Dr Wolgen has navigated the business through regulatory setbacks and ultimately got them to first approvals and commercial revenues. He is also their largest shareholder. Coming to 20 years with obvious success and a clear plan for the company laid out for 2024 - 2026. he may decide time is up at some point in the near future.
Conclusion
There is a lot to unpack with CUV and this article tries its best to summarise the complexities and the opportunities that lay ahead for the company.
While risks in this space are obvious, the fact the company has a product in the field, is growing profits and doing so efficiently, means that it comes at the active R&D program with operational leverage and a proven medical solution ready to help many more individuals shine the world over.
Whilst it might be premature to suggest the company can get back to all-time high levels, its runway has enough activity that could a run should a positive tailwind come.
Important Information: Stockopedia Ltd ABN 39 757 874 670 UK business registration number 0637267 (“Stockopedia”) is an Authorised Representative of Daylight Financial Group Pty Ltd ABN 77 633 984 773 (“DFGPL”) which is the holder of an Australian Financial Services Licence (AFS Licence No. 521404).
Information in this commentary is current as at date prepared unless otherwise stated. However, please bear in mind that investments can go up or down in value, and that past performance is not a reliable indicator of future performance. For more Important Information please refer to the Disclaimer section of this website.
This communication may contain general financial product advice. It has been prepared without taking into account your personal circumstances, and you should therefore consider its appropriateness in light of your objectives, financial circumstances and needs before acting on it.
If our advice relates to the acquisition or possible acquisition of a particular financial product, you should obtain a copy of and consider the Product Disclosure Statement (PDS) before making any decision.
The author holds interests in the following stocks mentioned in this article: CUV. This position can and will change at any time without notice.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
2 comments
Thanks Elio. Fascinating company, with a quite polarising MD who marches to the beat of his own drum. It is certainly spinning off cash, and there has even been some talk of it being a takeover target given its low valuation compared to global peers. Let's hope the downtrend is finally over. As is normal with biotech companies, it is a long process to gain approval. Looks like the phase III vitiligo trial which has just started recruiting runs for 12 months, with a 6-month follow-up.
That is correct. News from it will be the big catalyst next.... though I am excited about the OTC products. People will spend so much money on vanity products.... pumped by social media influencers. Where as get a punter to invest in a product like Stockopedia.... and I get the third degree...
Apparently they will only look for influences with a million followers or more... and they are going to pay them in CUV shares...