Daily Stock Market Report (Fri 10 Jan 2025) - SHI, Fast Retailing, APH, ANP, CKN, SBRY

Good morning! We have another takeover offer to round out the week, this time for Alliance Pharma.
1pm: this report is finished! Have a great weekend, and keep an eye out for our weekly podcast!
Spreadsheet accompanying this report (updated to 3/1/2025).
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
J Sainsbury (LON:SBRY) (£6.6bn) | TU | Q3 LfLs +2.8%. Won market share. FY25 adj. operating profit to be in line (£1,010-1,060m). | AMBER/GREEN (Graham) |
Clarkson (LON:CKN) (£1.2bn) | TU | Results for FY Dec 2024 to be slightly ahead of expectations, adj. PBT not less than £115m. | AMBER/RED (Graham) |
Glenveagh Properties (LON:GLV) (£704m) | Full Year TU | Rev +43% (€869m), EPS +112%. “Positioned for further growth in 2025”, favourable mkt conditions | |
Team Internet (LON:TIG) (£297m) | Statement of intention not to make an offer | One of the possible buyers pulls out of the race. | PINK |
Alliance Pharma (LON:APH) (£240m) | Recommended acquisition of APH | 62.5p in cash, 41% premium to yesterday’s close. | PINK (Graham) |
| De La Rue (LON:DLAR) (£218m) | Receives takeover offer (per Sky News) | According to Sky News there is a “full cash offer” at 125p. A partial cash offer was proposed in Oct. | PINK |
Anpario (LON:ANP) (£75m) | Full year TU | Stronger than expected H2 performance. Rev £37.5m, EBITDA ahead of exps. | GREEN (Graham) |
Equipmake Holdings (OFEX:EQIP) (£15m) | Results for six months to Nov 2024 | Rev +19% to £2.5m, adj. operating loss £3.95m, in line with exps. | |
One Media IP (LON:OMIP) (£9m) | TU | FY Oct 2024: rev £5m, EBITDA £2.1m (+15%). Strategic disposal: “much stronger position for 2025”. |
Summaries
Alliance Pharma (LON:APH) - up 38% to 61p (£330m) - Recommended Acquisition - Graham - PINK (takeover)
It's a 40%+ premium takeover offer from APH's largest shareholder, although they point out the shares have more than doubled since they originally approached the APH board. It's a shame to lose another decent company from the UK market, but at the same time reassuring of the value that is probably still available!
Short Sections
Anpario (LON:ANP) - up 9% to 400p (£83m) - Full year trading statement - Graham - GREEN
It’s a positive update from this provider of animal feed additives: year-end sales were higher than expected, so that full-year revenue is now thought to be c. £37.5m (consensus: 35.25m). Higher sales, operational gearing and fortunate foreign exchange movements result in EBITDA being ahead of expectations: Shore Capital have consequently boosted their adj. EBITDA forecast by c. 18% to £6.6m, and they note that this is the fifth upgrade to 2024 forecasts, with four of these coming from positive trading and one coming from an acquisition.
The acquired Wisconsin-based company Bio-Vet “had a strong final quarter due to heightened demand for its products, which support the health of dairy cows affected by avian influenza”, while ANP’s Middle East and Africa segment “delivered an outstanding sales performance”.
And ANP’s year-end cash balance is virtually unchanged on last year at £10.5m, despite spending USD $6m on that Bio-Vet acquisition.
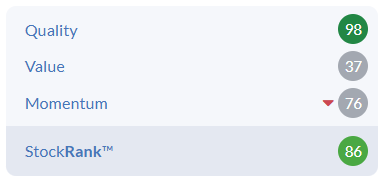
Graham’s view: I’m happy to leave the prevailing GREEN stance unchanged here after yet another positive trading update. If there’s a lesson today, maybe it’s not to fight momentum! Although ANP’s strongest feature according to the StockRanks is its quality. Anpario’s growth over the long-term has been unimpressive but it has built up a head of steam over the past two years and may be worthy of further investigation.
Clarkson (LON:CKN)
Up 8% to £42.20 (£1.3bn) - Trading Statement - Graham - AMBER/RED
The briefest of updates from this shipping company:
Clarkson PLC, the world's leading provider of integrated shipping services, today announces that results for the year ending 31 December 2024, are now anticipated to be slightly ahead of current market expectations.
Clarksons' underlying profit before tax, subject to audit, is now expected to be not less than £115m.
This one was last covered in August, and there haven’t been any other results since then. Those interim results published in August showed a small reduction in H1 revenues and underlying profits, but H2 is seasonally more important than H1.
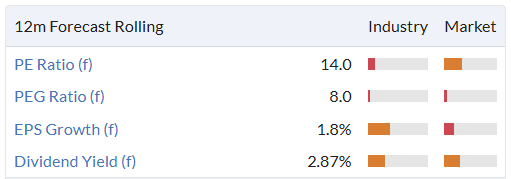
The latest update from Panmure, published today, raises forecasts by 3%: they are now suggesting that FY24 EPS will be 285.4p (FY23: 275p). FY25 is expected to come in slightly lower than that at 279.3p.
That puts the shares on a forward PER of 15x. Maritime/shipping is not my area of expertise but I am struggling to see the opportunity here - shouldn’t this trade at a low-ish PER, to reflect cyclical shipping demand? I think I’ll leave AMBER/RED unchanged for now.
Backlog
SIG (LON:SHI)
Flat yesterday at 15p (£179m) - Trading Update - Megan - RED
Building supplier SIG can blame the poor macroeconomic environment for another year of disappointing results as much as it likes. But it’s hard to find a period of time when it was delivering positive results, regardless of what was going on in the wider economy.
In 2024 the company will report annual revenues of £2.61bn, which is almost exactly what they were ten years ago. In that time SIG has only managed to report revenue increases three times and it’s never managed to string together two consecutive years of sales growth. The 2024 numbers are 4% lower than 2023.
It’s a bleak picture for a company which also suffers from ridiculously low margins. In the first half of the year, SIG incurred £992m of sales costs off £1.3bn of revenues. Operating expenses of £314m left only a sliver of operating profits and the company reported interim net losses.
Yesterday’s trading update indicates that there has been no turnaround in fortunes in the second half of the year. Although SIG is expected to report underlying operating profits of £25m, it is likely to be loss making at the bottom line and will report a free cash outflow of £39m.
It’s also worth being wary of the balance sheet. After refinancing €300m of its borrowing in October, the company’s net debt position stands at £496m, which is almost three times the company’s current market capitalisation and 4.7 times its equity.
Megan’s view:
There could be a value argument to be made for a company which is valued at less than 10% of its annual sales. Even if you add in the debt the EV/Sales ratio is just 0.25.
It’s also worth noting that it has been a very difficult period for companies in the construction sector and SIG’s products are well placed to benefit from rising demand under Kier Starmer’s environmentally-friendly building pledges.
But there is no getting away from the fact that even in the good times, SIG struggles to generate a decent profit. And that debt is alarming. I would stay away. RED
Fast Retailing Co (TYO:9983)
Up 1% yesterday to 52,100yen (£81.6bn) - First quarter results - Megan - GREEN
Investors who appreciate a nicely laid out set of financial results might enjoy a scan over the numbers at Fast Retailing.
The Japanese company, which is best known for its Uniqlo brand, reported numbers for the three months to November 2024 (the first quarter of the 2025 financial year which ends in August) which opened with this table:
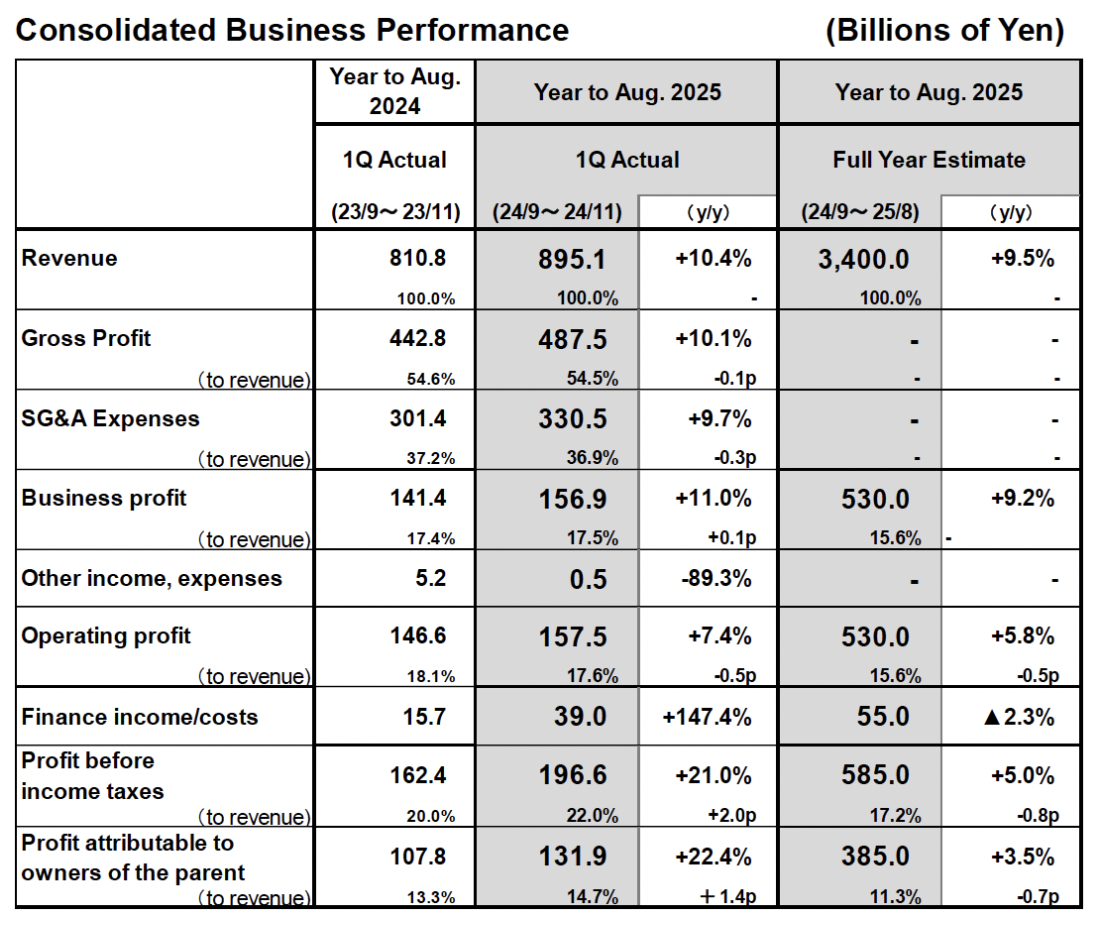
Management goes on to clearly lay out the divisional performance and explain how each part of the business has done well or badly.
And overall, there are definitely more examples of ‘done well’ than ‘done badly’ After reporting its first ever year of 3trn yen in revenues in FY2024, Uniqlo has continued to deliver growth this financial year. Sales were 9% higher in Japan at 266bn yen and 14% higher in international markets at 502bn yen.
Margins are slightly lower than in 2024 and that is expected to persist for the rest of the year, but it reflects the company’s move into its next phase of growth. At the annual results, chief executive Tadashi Yanai said that the focus for investment would be in human resource development and that this would help stimulate further expansion.
It’s a fascinating comparison to executive reports from western companies, where management teams don’t need much excuse to talk about automation and robotics. Human resource development is a far cry from the tech-focused spending that is going to help enhance margins at US and European retailers.
There is something quite refreshing about Fast Retailing’s attitude to growth, which has certainly worked wonders in the past. The company listed 30 years ago and its share price has risen nearly 100-fold in that time.
Megan’s view
I recently acquired my first ever Uniqlo product - a fleece given as a Christmas present. I also browsed my first Uniqlo store (they have been popping up like crazy in the UK) and it was packed. The brand is certainly gaining traction in the UK and the US and it looks like there is more room for growth.
The shares aren’t that easy to come by for UK investors and for those who are interested, they are very expensive, trading on almost 40 times forecast earnings. But I like the company a lot and so for purely illustrative purposes, my rating is green.
Graham's Section
Alliance Pharma (LON:APH)
Up 38% to 61p (£330m) - Recommended Acquisition - Graham - PINK (takeover)
Another day, another acquisition of a UK-listed stock.
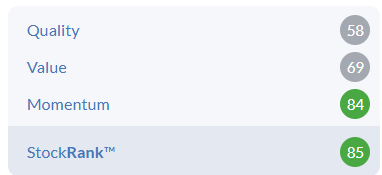
It’s an early win for Ed’s 2025 QVM Portfolio, which included Alliance Pharma as one of its healthcare entries. Strong momentum was the main clue that things were going well:
The share price found a floor over the past year:
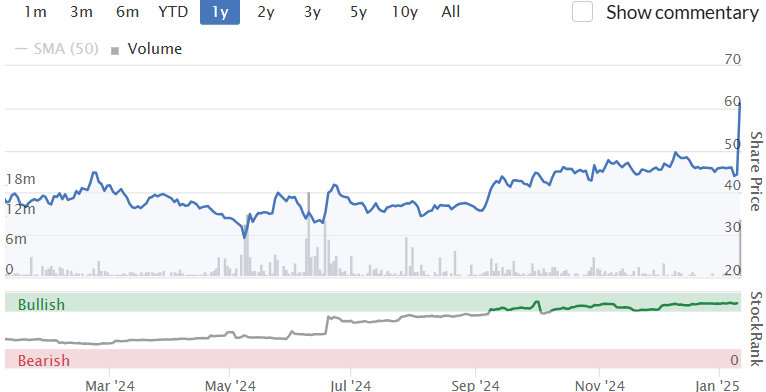
In June, Paul gave the company a big upgrade after it reduced its leverage multiple and restated its intangible assets to more accurate (lower) levels.
The buyer: DBAY Advisors, an Isle of Man-based investment manager. DBAY previously acquired Finsbury Foods (FIF), and it already owns 28% of Alliance Pharma.
The price: 62.5p in cash, a 41% premium to yesterday’s close. Not overly generous, as 30% is typically the bare minimum that I look for in a takeover bid. The announcement points out that it’s a 113% premium to the price before DBAY’s initial approach to the board of Alliance Pharma.
Rationale: DBAY says that Alliance’s public listing has “potential for management distraction” and there has been “limited recent liquidity of Alliance Shares”, so that the listing “does not currently offer significant benefits for the business”.
More positively:
DBAY is supportive of Alliance's leadership team and believes in Alliance's future prospects but considers that Alliance needs to implement a range of operational and strategic initiatives, in conjunction with a period of accelerated investment and selective acquisitions of complementary products, in order to fulfil the growth potential of the business. It has become apparent to DBAY that Alliance needs time away from the public market to allow it to fully deliver these initiatives in a reasonable timeframe.
Irrevocable undertakings: I don’t see much in the announcement in relation to shareholders who have already pledged to support the takeover. The CEO supports it, and I can only presume that Slater Investments (13% shareholder) supports it. On that basis, I presume that it will go ahead.
Graham’s view: it’s a shame to lose yet another company from the UK market but at the same time, it’s reassuring that there is probably still a great deal of value out there available to us!
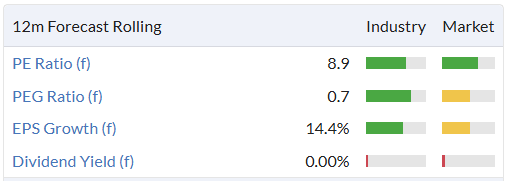
DBAY are getting a good deal on a 1-year P/E basis, and if their investment plan for the business works out, they could do extremely well:
J Sainsbury (LON:SBRY)
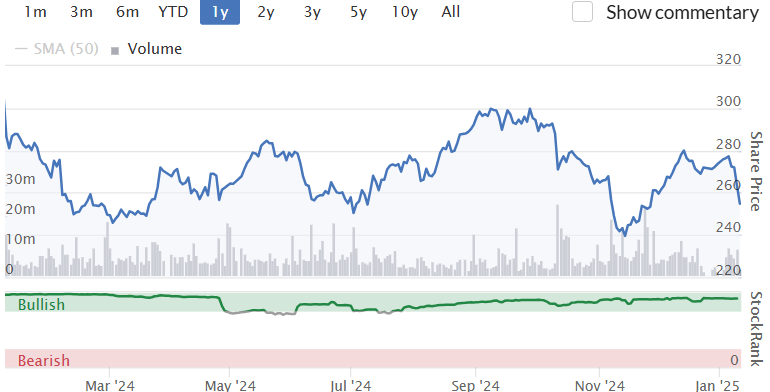
Down 3% to 255.3p (£6.0bn) - Trading Statement - Graham - AMBER/GREEN
We don’t cover SBRY very frequently but after giving TSCO a mention yesterday and with this stock appearing on today’s “Most Viewed” list, I thought I would take a quick look.
The market doesn’t seem to like this update, despite a reaffirmation of guidance for FY Feb 2025.
CEO comment opens positively:
"We have won grocery market share for the fifth consecutive Christmas, with more customers choosing Sainsbury's for their big shop. Driven by our leading combination of quality, value and service, we have achieved seven consecutive quarters of volume performance ahead of the market and further accelerated our two-year volume growth.
The figures:
Like-for-like retail sales +2.8%, excluding fuel.
Sainsbury’s +3.7%, Argos minus 1.4%.
Grocery (+4.1%) outperforms General Merchandise & Clothing (-0.1%).
FY Feb 2025 outlook: retail underlying operating profit in line with consensus and the midpoint of the guided range £1,010-1,060m, growth of 7%.
Financial services is much smaller with underlying operating profit of £30m but this is ahead of guidance (£15-25m).
Graham’s view: as with TSCO, I can’t get too excited about shares in this mature, below-average quality sector. However, as with Tesco, I am inclined to also give SBRY an AMBER/GREEN stance.
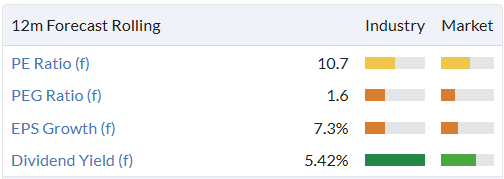
Like many UK blue-chips, this is likely to be of most interest to dividend gatherers who also want the possibility of some growth:
With Tesco and Sainsbury both claiming to win market share, it must be coming from somewhere and that “somewhere” apparently includes Asda and Aldi (external link), although Lidl has continued to grow.
Figures from September:
Asda’s share plummeted to 11.8% in the 12 weeks to 7 September, from 13.1% a year ago. Meanwhile, Aldi’s share also slipped from 10.7% to 10.3% over the same period.
The decline of Asda tallies with rival analyst Kantar’s data, which found that its share had fallen 1.2 percentage points to 12.6% in the 12 weeks to 1 September.
Competition is inherently intense in this sector, which is one of the reasons I stay away from it. Having said that, I don’t have any particular criticisms to make of either TSCO or SBRY. If I was only interested in maximising income without taking on too much risk, their shares would definitely be up for consideration.
One major factor to consider is of course the increase in NICs and whether they could take a meaningful bite out of profits. CEO Simon Roberts is quoted by the BBC today as saying “We’ll have to look very carefully at all hiring decisions”. Price rises for customers look inevitable, as part of mitigation efforts. But all supermarkets are in the same boat as they attempt to deal with this issue.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

65 comments
XPS Pensions (LON:XPS) has dropped back to 200 dma, where it has found support for it's 3x growth over the last 2 years. I see the current gilt/stock/pension turmoil as another "Truss trigger" for their clients and will be topping up after top slicing at 360 on the October spike.
Yes any turmoil should be good for XPS - taken advantage of irrational drop to add a few
ANP£ Very encouraging year end update today and there should be many happy employees after today's news - SAYE scheme launched last month had strike price no more than 300p
Shame about the staggering size of the ongoing ‘hidden’ employee share trust . Presumably mainly for Directors benefit . A whopping £8.6m of the company's cash has been spent in this way without being put through the P & L.
I just watched the H1 results as a consequence of the good TU today. Contrary to the comment above, they had a specific slide front and centre on the employee share trust. And looking at it, I am fairly relaxed: the rewards to shareholders and employees seem well balanced. For me the bigger question/issue is are their markets cyclical or are we seeing secular growth? I am less optimistic than Graham above so a no for me for now.
16% drop in Sosandar (LON:SOS) today. I can't see any reason for it. Guessing we are due an imminent trading update and bad news is expected?
Sosandar (LON:SOS) now down 19%, can't see any news, profit warning rumours, the retail sector is down, even the large caps.volume is high today.
Marks and Spencer (LON:MKS) and Greggs (LON:GRG) have been large fallers this week.
Wow. What a surprise that would be! A small fashion retailer that has made a profit just once in its lifetime and recently did a complete strategy u-turn from exclusively online to a mix with physical stores. One of Paul Scott's stranger obsessions.
Hi Michael, I'll get back to you on that later today! Thanks. G
Many thanks Graham
On Clarkson (LON:CKN) it seems pretty well manged and has good quality metrics and has a great record of steady dividend growth. although not he highest of yields. Scores in the top quintile in the UK dividend paying universe on my work.
There was a big problem with Clarkson (LON:CKN), most of the cash was be paid out as staff bonuses, this was highlighted by Paul Scott. I have not followed recently.
Clarkson (LON:CKN) - Hi Rusty and thanks for the reminder. Indeed Paul has just ranted on about the huge pay package awarded to the top two directors in his daily podcast (along with similar disdain over at Anpario (LON:ANP) ). Not on Tesla scale but they do make profits for shareholders and there are a number of dare I say reputable institutional investors on the shareholder list.
From memory it was not just 2 directors and it was almost all the cash.
In 2022 it was £225m. This is not just a few £m to directors.
Its all in the annual report available on the website - pages and pages of detail but in 2023 by far the largest -£12m - went to Andi Case
So what is the total for 2023?
Do you think £12m to one director is reasonable?
How many millions did he get in 2022?
It is a broking type business where bonuses are often paid. I don't think it is correct to say that most of the cash is paid out to staff as there have been dividends and they retain cash on the balance sheet. There is also a degree of paying out past years as well as bonuses are held back & last year (which I guess he may have been referring to) was a bumper year & included some catch up etc. There was a good explanation of this in the Remuneration report in last year annual report on page 129 0r see the photo below if it is readable?
It was £225m in 2022.
In 2021 it was £148m.
Yes it is on the balance sheet, but is reserved for future bonuses.
From the SCVP 6 March 2023:
"On digging a bit deeper, I’ve found something rather alarming in the notes, right at the end, it says that most of the cash pile is due to be paid out in bonuses, a colossal amount!
I also note from the cashflow statement that £20.4m was spent buying shares for the employees’ ESOP. Plus an £88.8m increase in the “bonus accrual”. This dwarfs the cash paid to shareholders, divis of £25.9m."
Hi jjis Agree your comments although I am not investing here soley for the divi - I think there is only one significant competitor here in UK and thats Braemar (LON:BMS) but I expect both coys would argue they specialise in different sectors of the same market.
It is not just about the dividend with this, it has offered pretty decent total returns, although obviously anything could happen in the future.
Greggs (LON:GRG) What happens when you increase prices to cover NI hikes
People were quick to complain on social media, with one person writing on X: "Anything above a pound for a Greggs sausage roll is criminal. I remember them being 80p."
Commenting on the increases, another person said: "What the f***. Why are Greggs sausage rolls £1.30 now?"
Source SKY news.
This is going to happen everywhere, so I don’t see this negatively effecting Greggs. Their efficient model means price increases will be less than other food retailers.
Taking it one step on from Dragon's post above - perhaps many people will simply change their spending behaviour, after all for me there is a threshold above which things are such poor value that I have no interest in wasting money on them.
Case in point is burger king - I have just been into their Guildford branch where 2 Wagyu burgers and chips and onion rings costs almost £30.
My other half and I said that it was just ridiculous to pay that and decided we won't be doing that again in a hurry.
Extrapolate to £7 a pint in my local pub and so on across a range of business sectors and you have the perfect recipe for people to rein in their spending on items where they think prices have become ridiculous.
I feel there is a limit to what people will pay for things and so my take on it is reduced sales for a variety of businesses in 2025 as people are more choosy on how and where they spend their hard earned cash.
That clearly does not bode well for the economy and the trick will be to identify those areas where people continue to spend or have to spend money.
You would expect the supermarkets to benefit if people are trying to rein in their food and drink budgets. A meal for 2 in a pub with a couple of drink each goes a long way in a supermarket - especially Aldi!
The other approach being taken is shrinkflation to anchor prices but smaller product size. Just had a flat repainted and Dulux emulsion tubs now only 7.5L were 10L, and don't mention the size of piece of cheddar to go in my sandwich. I think I need that £7 pint
Dulux came out bottom in one test of emulsions, coverage was very poor.
It is not the cheapest but you need to use more of it.
The stupidi small minded economist Rachel Reeves appears to have killed the Greggs sausage roll as well as the hopes and dreams of a nations entrepreneurs.
Before bemoaning the price of a burger or a pint we need to be very very clear that this is the result of costs spiralling for the providers .
And costs have spiralled to pay for our doctors and train drivers whos myopic self interst have shafted the nation
At least the civil servants with their fat pemsions , flexi time wotk from home and mental health awareness days wont be forced to queue with the rest of us tax paying peasants bring bled to death in the queues at Greggs .
Maybe our economic path to growth and fiuture success is nothing more than a shadow move by Reeves to get her Greggs pasty quicker .
Greggs (LON:GRG) I hold - I've added some today and will add more if it falls further, doesn't feel like a falling knife ? (I hope !)
like Greggs !
Re Loungers (LON:LGRS) big big stock market success! I went to the one in Deal late lunch today (busy) 4 front of house. Kitchen up steep stairs. No dumb waiter!!! If the UK did productivity cap ex the place would be transformed. But why bother when staff were cheap? As a Londoner what really struck me was how SLOW the pace of life is outside the smoke. This country deserves to be poor? The FT pointed out that Starbucks is being hammered in China by 'automated' competition. The Loungers was not an old fit out, just an exploitation of cheap labour.
Hi Graham, I asked a question yesterday re Impax Asset Management (LON:IPX) and was not sure where it's best to post eg on an original article?
Does anyone know if posters of articles get notified of comments? Thanks, Michael
You can set that up in your account.
Hi MIK, I'm responding to you on yesterday's thread. Thanks. Graham
The Telegraph reports on mixed news for the housing market.
About 700,000 households expect higher mortgage rates this year as a result of increased borrowing costs. It is reported that Sonia swaps have increased from 3.4% in September to 4.2 % this week.
The Telegraph goes on to report that there is good news for approx 340,000 households on two year fixed deals who should see their borrowing costs fall when they renew this year
It looks as if De La Rue (LON:DLAR) is now going to be taken off the market at 125. Not my most successful investment, but I will be out at a profit at that price. It will be interesting to see how this plays out - the sharp drop in sterling we are experiencing must surely change the calculations of value.
On Fast Retailing Co (TYO:9983)
I like the products and the philosophy and have purchased there on occasion for the last 10y or so (they sell trousers that do not look like they were sprayed on / do have usable pockets / dont make me look like a fat carrot) and have a nice online offering.
but green and a 40x per?
I think you are sort of telling me that you expect FRC to grow profits about 17% pa faster than (say) sainsburys every year for the next 10 years or so ( 1.17^10 = 4.8, 40/4.8 = 8.33, sainsburys pe = 8.38)
Now as the sp has grown 20.86 times from 2005-2025 and that means growth of 16.4% pa, this may be possible. Certainly in the North America there are only 96 shops. but it seems the current price assumes perfect execution over 10 years and no adverse economic events and no change in consumer tastes.
Not sure how Ed’s NAPs manages such good fortune! Three of his NAPs picks are already up in excess of 15% Metals Exploration (LON:MTL) & Serabi Gold (LON:SRB and now Alliance Pharma (LON:APH. My experimentation with some form of the NAPs never seemed to achieve the same results. Admittedly not followed 100% but early year 2014-17 were reasonable. Since then invariably lost money so didn’t follow any selections this year!
Yes a good start to the year for the NAPS - with a new all time high thanks to Alliance Pharma (LON:APH) bid this morning. I will circle back next week with thoughts on redeploying the funds.
I’ve held Metals Exploration (LON:MTL) since the 2p mark, is a gem of a company and due to re rate soon with the recent takeover over of CNR, fy results soon to be announced and more news on runruno, and exploration results at abra. I’m holding on this one tight until we see 10-15p
I sold my NAPS holding of Alliance Pharma (LON:APH) this morning, and when I ran a screen across all sectors in both the UK and the US the top ranked stock (StockRank 100) was Qifu Technology (NSQ:QFIN) . A joint UK/US NAPS system might be interesting, so I will buy Qifu this afternoon.
Qifu is a Chinese company. Caveat Emptor.
I realise that. I have been impressed by the performance of the NAPS selections, which have bettered my own stock picks over the past few years, and so I have decided to put a sizeable chunk of my portfolio into data-driven investments without quibbling too much with the results of the scans. I am happy to wait and see how that works out.
Its in an interesting space, good growth potential
Thanks for covering Fast Retailing Co (TYO:9983) Megan. Maybe a bit expensive for my tastes but I love Uniqlo clothes and I agree it is very popular in the UK. In this cold weather I am very thankful for their cheap but high quality base layers!
On the 2nd and 3rd columns of the results there is a percentage figure - do you know what that relates to? It's a bit confusing alongside the YoY % figure.
I agree on the quality of their clothing. Am very impressed.
The small % figure in the 2nd and 3rd column is the margin (e.g. 54.5% gross margin).
Agree all your comments Megan but just like UK Mkt the Japanese Mkt not impressed. It fell 6.5% yesterday and seems to be about 10% down on the last few weeks. I wonder what UK managers of Japanese funds available here think - I don't know of a fund with TYO;9983 listed in the top ten
When we have sold all our businesses and the owners have disappeared overseas what will become of old blighty? Trumps favourite philosopher was Ayn Rand and her book Atlas Shrugged is an interesting insight into a future where all the "useful" people read, monied, go to another place, read Dubai. So I am not so sure that our businesses being sold to overseas interests is ever going to be in the interests of us or anyone else in these climes. We simply see a net movement of wealth away.
Being an open market that attracts international capital is beneficial to investors in the U.K. What we need however is an environment that encourages entrepreneurs to start and list their businesses here to replace them. However with recent increases to CGT, CT, ENI, and divi taxes, and the reduction in BADR, I fear we have killed that golden goose.
Hi The London Snail. Being an open market is theoretically brilliant and I support wholesale. However I think there are assets you should defend (Thames Water??) and I think you should note how others are behaving i.e. not encouraging free open markets and thereby putting yourselves at a huge disadvantage. Look for example at the US when has that been truly an open market (ignoring the way Merril Lynch transferred all their debt to the UK and their assets to the US in 2008, the petro dollar has always kept their currency at a pitch that enables them to buy overseas businesses. The French have never openly played the game etc etc). Just my views.
We are Doomed! (as Laurie of Dads Army would exclaim )
About time Alliance Pharma (LON:APH) was bid for. Should be more though
Good morning Paul Walton, more is always better but how much more, what was your expectation for Alliance Pharma (LON:APH)? Consensus broker TP is 65p, and DBay (stake building and therefore the most likely bidder) have form when it comes to seeking value, (they took out Finsbury Foods in 2023 and the premium to share price wasn't generally considered very generous apparently).
Checking back on my notes there was a strategic review announcement due at the 'end of the year', whether calendar or financial doesn't matter with Alliance's FYE being 31st December, but the absence of that announcement was in hindsight probably a clue that something was going on in the background, or alternatively there was a problem.
The SP at last nights close was only 15% over the same time a year ago, and it's been tracking sideways within a range for months. Admittedly for AIM listed companies that's quite an achievement.
Was expecting 80p but cant complain. Can utilise elsewhere now
I am voting against not that it will make any difference, another good company going for song in my opinion
Absolutely
I posted earlier in the week about the need to watch any Investment Trusts that you hold, and to make sure that you vote in any AGM's.
Here https://www.trustnet.com/news/... is a current list of the Investment Trusts that may well be attacked by an American corporate raider.
This is important for the survival of one of our core and best established investment industries.
Hi Grey Investor,
Agreed. I posted a couple of comments on the Investment Trust thread to that effect, I hold Baillie Gifford Us Growth Trust (LON:USA) in my AJ Bell account and there is a voting instruction option on the drop down menu. This links to the voting form so it is an easy task. I assume other platforms will have the same facility. Needless to say I have voted against the American gambler!
Bond volatility and weakness is attracting attention and since yield levels are now similar to those reached in 2022 when the Truss govt fell the question is being asked - are we in trouble again? Can we pay the bills ? There are two differences between now and then, firstly yields are rising everywhere - not least the US - with very little to choose between UK and US 10 year rates. The second is the scale of the move, in 2022 the 10Y yield spiked over 200bps compared to a relatively lower 80-90bps now. Ofcourse it seems odd that yields are rising when rates are falling - but we have had no term pm in the bond market for quite some time. Term pm is normal, should be expected and is returning reflecting inflation risks.
Todays employment data from the US we can hope it is not too strong, I fear it won't be weak... all eyes on the reaction.
Very insightful. I agree that the new normal does not look like the period 2008-2023 so as you say higher rates and term premium should be expected. Btw that's a very neat table, which platform/source does it come from?
Term PM meaning term premium?
it looks like
https://tradingeconomics.com/s...
Higher rates make bonds more attractive and equities less attractive, so equity market falls.
What i am not sure about is if money goes out of bond market to make bond yields rise, where does this money go, because it does not go into the equity market.
Anyone have suggestions?
Depends on what you mean by "money", but I'd say it goes into bank deposits, reserves, money markets.
Possibly cash at the moment - hiding due to president change.
Bank to the bank - shrinkage in the fractional reserve banking system (some economists might call it deflation)