Daily Stock Market Report (Fri 10th July 2026) - EZJ, IPX, AVG

Good morning!
Not everybody who reads this is a football fan, but the match against Norway tomorrow is difficult to ignore. Economically, these games lead to millions of extra pints being served in pubs, and significantly increased betting activity. So there is more than one reason to cheer for an English win tomorrow night.
In politics, Andy Burnham is currently unopposed as the next Labour leader. With 322 nominations from Labour MPs so far, it's almost mathematically impossible for anyone else to even run against him.
Will he succeed in ending "forty years of neoliberalism"? As I've said before, I expect him to engage in a little more intervention in the utility sector and perhaps other major industries, compared to his predecessor. But beyond that, we might not see much radical change.
Overnight market movements:
The FTSE is up 0.2% at 10,490
S&P 500 is down 0.1% at 7,535
Brent crude (September) is unchanged at $76.25/bbl
Gold is down 0.1% at $4,120/oz
Bitcoin is up 1.2% at $64,050
Today's Agenda is complete. Spreadsheet accompanying this report: link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Vodafone (LON:VOD) (£22.5bn | SR75) | Niel family group buys 16.2% of Vodafone Group plc from Emirates Telecommunications Group (E&). Price per share of £1.104792. Vodafone’s relationship agreement with e& is terminated and their nominee director resigns from the Board. | ||
easyJet (LON:EZJ) (£4.5bn | SR49) | Agreement in principle on a cash offer from Apollo at £7.15 per share, superior to the £6.90 per share offer from Castlelake. | TAKEOVER (Graham) | |
Johnson Service (LON:JSG) (£615m | SR80) | “...notwithstanding the challenges being experienced within hospitality, the Board continues to expect to deliver another year of progress and margin improvement and, therefore, we remain on track towards achieving our targeted adjusted operating margin of at least 14.0% in 2026.” H1 revenue in line with the prior year. | ||
Hays (LON:HAS) (£563m | SR35) | Net fees down 5% like-for-like. £20m net cash, in line with expectations. “Our actions to deliver strong consultant net fee productivity growth and cost discipline continued to offset our lower net fees in H2 26 and we currently expect FY26 pre -exceptional operating profit will be at the top of the £37.0 -46.0m consensus range.” | ||
GlobalData (LON:DATA) (£547m | SR38) | Proposed to return £30 million to Shareholders by way of a Tender Offer at 85 pence per Share. | ||
Picton Property Income (LON:PCTN) (£368m | SR58) | Revised offer: 0.190 LondonMetric shares and 0.894 SREIT shares per Picton share. Increases the SREIT exchange ratio from 0.881 to 0.894. The Picton Board reaffirms its support for the Proposed Offer. | TAKEOVER | |
| Avingtrans (LON:AVG) (£212m | SR75) | Launch of proposed placing & Result of Placing | Placing to raise c. £21m gross at 640p. New shares to represent 9.8% of the existing share capital. Issue price equal to the closing price yesterday. Net proceeds to be "deployed principally to expand its nuclear capacity by building out its facility in Michigan, including acquisition of manufacturing equipment and expansion of its workforce, so as to be able to accommodate expanded demand from both existing client orders and prospective new projects". | AMBER/GREEN = (Graham) Assuming that we can trust management projections, the question is whether it's worth investing £20m plus fundraising expenses to get an additional EBITDA of £9.6m - £17m in three years. I think the answer is probably yes. I can't predict how much of that EBITDA will get converted into real, after cax net income and free cash flow, but the track record at Avingtrans is decent. So on its face, the maths here makes sense: £20m of investment will turn into £9.6m-£17m of additional EBITDA in a few years, and that in turn will generate hopefully a nice chunk of additional real profits. I can see why investors have marked the shares higher today. I'll leave our moderately positive stance unchanged. |
MJ GLEESON (LON:GLE) (£136m | SR41) | Adjusted Group Profit Before Tax for FY2026 in line with current market expectations, including a robust performance from Gleeson Homes and the previously announced delays to site sales in Gleeson Land. Outlook: “The outlook for the new financial year is uncertain as a result of the economic impacts of geo-political events and potential policy changes with a new UK Government…. the Group is ready to benefit from a recovery in market conditions.” | ||
Impax Asset Management (LON:IPX) (£121m | SR74) | Net outflow £994m, plus another £754m outflow from Impax Environmental Markets. AUM increases from £22.3bn to £23.3bn. | AMBER/GREEN ↑ (Graham)
Cash reserves of £46m (March 2026) cover a decent chunk of the market cap here. Without even adjusting for that, the P/E multiple was only 7x last night. At this sort of valuation, any sign that the business is not headed for oblivion should be treated very positively, in my view. I’ve been AMBER/RED on this stock, reflecting the short-term negative trends. There was a really serious profit warning from Impax in April, which shouldn’t be forgotten. However, on a long-term view, I don’t really believe in the current valuation - I think it’s worth significantly more than the market is giving it credit for. The StockRank style is Contrarian, which is one of my favourite styles. | |
MPAC (LON:MPAC) (£88m | SR38) | Duncan Tyler has been interim CFO since April. Becomes permanent CFO from 31st July. | ||
Genedrive (LON:GDR) (£20m | SR16) | Minister for Health Innovation and Safety, Preet Kaur Gill MP highlighted rapid pharmacogenetic testing for identifying newborn babies at risk of antibiotic-induced hearing loss as a practical example of personalised medicine. | ||
Sancus Lending (LON:LEND) (£13m | SR55) | The MD of Sancus Lending (UK), LEND’s subsidiary, becomes Group CEO. Trading update: “the geo-political and macro-economic backdrop has impacted activity levels across the Group's markets, and consequently profitability, in the first half. These trends persisted throughout June 2026. As a result, the Group is implementing measures, including efficiency initiatives, that are expected to return it to operating profitability during the second half of 2026.” |
Graham's Section
easyJet (LON:EZJ)
Up 15% at 674p (£5.2bn) - Statement regarding possible offer for easyJet plc - Graham - TAKEOVER
I’m taking our colour off this (which for the record was AMBER/GREEN) as our views on the merits of easyJet stock no longer seem relevant at this stage.
With Castelake having put easyJet in play with their takeover efforts, private equity giant Apollo has turned up with a recommended offer.
Terms: £7.15 per easyJet share (this is 3.6% higher than the £6.90 Castlelake bid).
There is also a “Stub Equity Alternative” whereby those shareholders who wish to continue holding easyJet will be able to own the vehicle through which Apollo owns easyJet. The precise terms of this alternative “remain subject to further discussion and agreement.”
As with Castlelake, there is a “best endeavours” commitment to get past any regulatory hurdles that might arise.
Financing: equity financing for the deal will come via Apollo funds. In addition, “Barclays has provided a letter to Apollo indicating that they are highly confident of being able to arrange the required debt financing for the Cash Offer.”
And some background:
Apollo has followed easyJet for many years and continues to regard it as one of the most attractive businesses in the global aviation sector and a highly differentiated franchise with significant long-term growth potential. Apollo believes in easyJet’s existing strategy of evolving and strengthening the low-cost carrier model, most notably through upgauging the fleet, enhancing the ancillary and loyalty offering, and scaling Holidays into a structurally differentiated earnings stream. Apollo further believes that easyJet management’s operational and commercial ambitions can be substantially accelerated via the access to incremental capital and longer-term business and strategic planning that a private company setting affords.
While Castlelake may be aviation specialists, Apollo are effectively specialists in everything - they are a trillion dollar asset manager.
Today’s announcement includes nice words about easyJet’s management team, employees, and the value of the brand.
Graham’s view
This further underlines how cheap the stock was, prior to the interest from Castlelake.
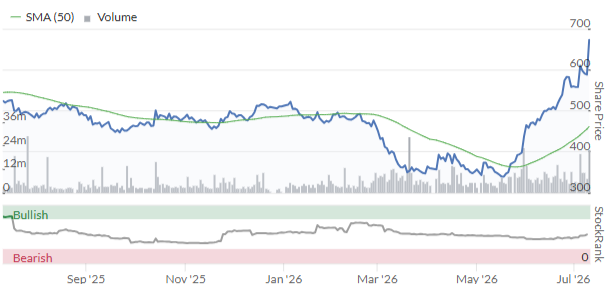
The Iran war knocked it below £5, down towards the £3.50 level, which was only around half the level at which private equity valued it:
A few points to consider.
Will it go ahead? I think this is going to be more achievable than the Castlelake takeover, due to the sheer size and resources available to Apollo. I did think that Castlelake were more likely than not to achieve regulatory approval (with their plan to involve an EU “partner”). I don’t see any detailed plan here as to how Apollo will navigate EU/UK airline ownership rules, but if there is any way to do it, I’m sure they will find it.
Will easyJet shareholders support it? I don’t know is the simple answer. The longer answer is that I think the funds are likely to support it, and I’d be surprised if the Haji-Ioannou hadn’t had some input by this stage. So there is a decent chance that the Haji-Ioannou family do support it.
Is the valuation fair? As I said previously, I didn’t think that £6.90 was obviously too cheap. If you look past the official balance sheet numbers and the current levels of profitability, then it was possible to argue that the stock was too cheap based on what it will look like in two years. easyJet have locked in hundreds of Airbus aircraft orders and purchase rights, which are valuable. Their airline slots and existing fleet are valuable. The EPS forecast for 2028 is 62p, which makes a 2028 P/E multiple of 11.5x. If everything goes right, then I think a buyer will do very well, even at £7.15. But UK stocks aren’t priced on that optimistic basis. Without a bid, there has been little prospect of achieving a £7+ share price.
Overall, therefore: I do think it will be possible for this deal to go ahead, I think easyJet shareholders are more likely than not to support it, and I think the offer is a pretty reasonable one. But also, let's see if Castlelake want to make another bid - the ball is now in their court.
Impax Asset Management (LON:IPX)
Up 18% at 111.8p (£146m) - Q3 AUM Update - Graham - AMBER/GREEN ↑
(At the time of writing, Graham has a long position in IPX.)
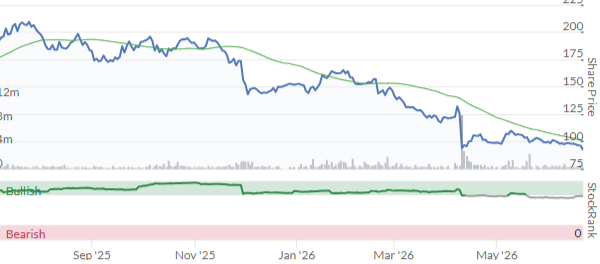
An amazing percentage gain here today, but it’s from a low base. These shares are seriously depressed, having topped out over £14 five years ago:
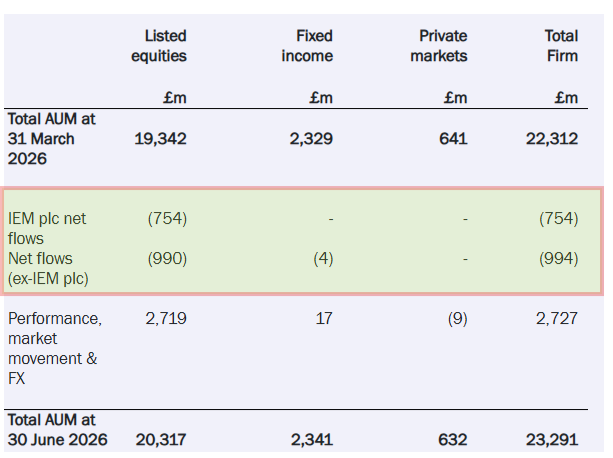
The Q3 AUM update is not so amazing: outflows of £1.7 billion.
£754m is being lost from Impax Environmental Markets, where the activist investor Saba has successfully ousted Impax (what to call it now - Saba Environmental Markets?).
Elsewhere, there was an additional £994m of outflows:
So what’s the good news?
Positive market movements of £2.7 billion, leading to an overall rise in AUM for the quarter.
Net outflows were £2 billion in Q2. So if we are willing to treat the IEM situation as a one-off, the Q3 performance is at least a big improvement on that.
CEO comment:
"With global equities markets reflecting the structural trends on which we focus, the performance of our thematic equities, systematic equities and fixed income strategies since the start of the calendar year has remained strong, with most outperforming relevant indices.
"Our net flows picture has also improved…
"Meanwhile, with our systematic equities funds in the U.S. receiving net inflows during the Period, we are responding to client demand in Europe with the intention to launch our first UCITS product in this area later this year."
Graham’s view
Cash reserves of £46m (March 2026) cover a decent chunk of the market cap here. Without even adjusting for that, the P/E multiple was only 7x last night.
At this sort of valuation, any sign that the business is not headed for oblivion should be treated very positively, in my view.
I’ve been AMBER/RED on this stock, reflecting the short-term negative trends. There was a really serious profit warning from Impax in April, which shouldn’t be forgotten.
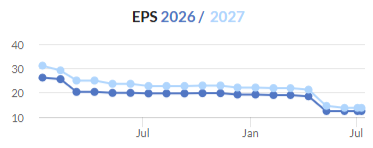
However, on a long-term view, I don’t really believe in the current valuation - I think it’s worth significantly more than the market is giving it credit for.
For example, even after today’s share price gains, the ratio of AUM to the market cap remains highly distressed at 160x. Adjust for cash and you get 232x. In these terms, the valuation of Impax is only about a third of the value at Polar Capital Holdings (LON:POLR).
With the net flow picture having improved, I’m going to stick my neck out and take us up two notches to AMBER/GREEN. I just think it’s too cheap on a long-term view.
The StockRank style is Contrarian, which is one of my favourite styles:
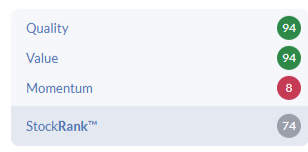
Extreme quality, and extreme value - the only weak point is Momentum, and there must be a good chance that this is about to start improving?
Avingtrans (LON:AVG)
Up 5% at 661.3p (£224m) - Launch of proposed placing & Result of Placing - Graham - AMBER/GREEN =
The market really likes this growth-oriented £21m placing.
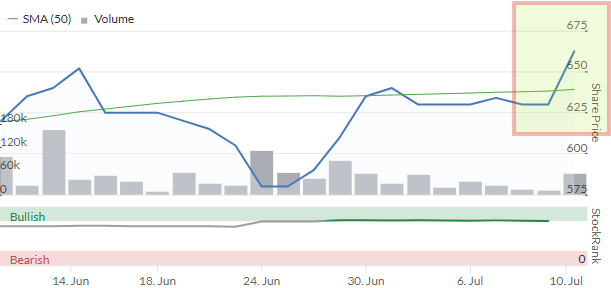
The "Result of Placing" RNS confirms that they did indeed raise funds at 630p, which was yesterday's close.
At the interim results in February, the company reported net debt of £12m, which is by no means unreasonable for a business of this size and profitability - less than one year of forecast net profits.
So Avingtrans entered this fundraising from a position of strength, a) because it's existing balance sheet was not in bad shape, and b) because the placing itself is highly growth-oriented.
On that second point:
With sufficient capital expenditure deployed, management believe that the Company has the weighted opportunity in its addressable market to grow annual revenues in nuclear by up to circa £90 million by 2031, from its current levels of circa £35 million.
For context, total revenues are currently running at around £160m, so an additional c. £55m would be highly material. The planned nuclear investment arising from this placing is expected to achieve additional revenues of £27-45m (a pretty wide range, it must be acknowledged), and additional EBITDA of £9.6m-£17m (another wide range) in FY31.
Net proceeds will be used as follows:
· approximately £7 million towards the build-out of the Company's new facility in Michigan, USA;
· approximately £4 million on manufacturing equipment;
· approximately £1 million on workforce expansion and training;
· approximately £3 million for general working capital purposes; and
· the balance of approximately £5 million retained as contingency,
Graham's view
Assuming that we can trust management projections, the question is whether it's worth investing £20m plus fundraising expenses to get an additional EBITDA of £9.6m - £17m in three years.
I think the answer is probably yes. I can't predict how much of that EBITDA will get converted into real, after cax net income and free cash flow, but the track record at Avingtrans is decent. At the most recent interim results, £9.6m of adj. EBITDA turned into £5.7m of after-tax profits.
So on its face, the maths here makes sense: £20m of investment will turn into £9.6m-£17m of additional EBITDA in a few years, and that in turn will generate hopefully a nice chunk of additional real profits. I can see why investors have marked the shares higher today. I'll leave our moderately positive stance unchanged.
Going to leave it there for now, enjoy the footie if you're a footie fan - otherwise enjoy your Saturday night as usual! Cheers.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

40 comments
The S&P 500 finally had a bullish MACD crossover for the first time in over a month.
Since the beginning of this bull market, it has been bullish for $SPX, with a 100% success over the next 5 trading days.
US market going higher might help the UK market as well.
All the best
Wherever you look the deficiencies of the LSE and Govt policies are evident in the sad undervaluation of UK companies, EZJeasyJet (LON:EZJ) the latest to be snapped up; VODVodafone (LON:VOD) must be looking at shifting overseas; asset managers ridiculously bombed out (cf. IPXImpax Asset Management (LON:IPX) . That’s just today. The sooner Burnham makes handouts to UK investors (iSAs, SIPPs, pension funds contingent on investing in UK the better. Of course, I’m talking my own book as a patriotic investor in over 80 British companies, over 80% sheltered in ISAs.
SK Hynix (NSQ:SKHYV)
Opened at $174, UP 17%
Another successful IPO handled by the US investment banks and listed on the best stock market!
All the best
FYI castlecate have issued a run of the mil RNS stating they are considering their position in light of the Apollo bid for easyJet (LON:EZJ) ...
Interesting times ahead one feels...
SK Hynix (NSQ:SKHYV) ADR’S INDICATED TO OPEN AT $180 ABOVE THE IPO OFFER PRICE OF $149
All the best
A few weeks ago, someone on here mentioned CT Automotive (LON:CTA) , having been tipped in a BASH event. Whoever it was I owe them a thank you and probably a beer or three.
I took a look at them, liked what I saw and built a position, plus taking some for my grandchildren’s JISAs. They are now starting to move in the right direction, and given company forecasts, they could have a good way to run once the seller is finally out.
Worth a look. A nice micro cap with a very high stock rank of 95.
No coverage of the fund raising by Avingtrans (LON:AVG)!? One of my largest small cap holdings. Held for several years. A shining example to other UK small cap companies.
In brief, AVG placed around 10% market cap at close to recent SP (an achievement in itself). 630p. SP currently up almost 5% at 660p
I've now covered AVG! Thanks for the prod. G
Since this is a Friday. I've got a curious question which I've always wanted to know the answer to.
When viewing RNS on Stockopedia. For anything older than ~2 years.
1) The RNS formatting goes completely out the door, making it unreadable. The only way I've been able to make sense of it is copy pasting it to an LLM and asking it to format for me.
2) Clicking the link to open the Refinitiv version in a new tab.... just gives a blank page. Guessing its because Refinitiv delete after a while?
Is this a problem for anyone else? How do other websites manage to preserve RNS releases in the past, but Stocko doesn't after 2 years worth?
Its a really fundamental problem, because essentially the main thing we're paying a Stockopedia subscription for is data, the data to be processed (eg Stockreports, Stockranks, etc), and that data presented nicely to be used... and I would have thought historical RNS data is a core feature?
Have you tried clicking the 'view original RNS' link? That should open up the original RNS document and hopefully a bit more readable.
It does.... but only for RNS from the last two years?
For example this one from January 2024. The preview loses all formatting. Its ok for this one, but some are just garbled text.
Then, clicking the "view original RNS" - which is what I meant by the Refinitiv version - as it opens up a webpage hosted by Refinitiv - gives me a blank page?
https://www.stockopedia.com/sh...
I clicked on that link and it looks okay to me. My first guess is that it's to do with your browser... Perhaps try a different one?
That's so weird!
And just to confirm... Both the link I provided above, AND the refinitiv webpage that the "view original RNS" link goes to?
I've tested on both Chrome on phone and laptop. Not tried other browsers though.
stockopedia link works
'original RNS link' gives me a blank page, also
using safari browser on a macbook for context!
Do you think Impax Asset Management (LON:IPX) has now bottomed? Could there be other fund managers circling, looking to pick up AUM of £23b ?
Yes it feels like this could be an inflexion point - flows are gradually improving and recent fund performance has been strong (which should in turn further help the flow situation over the coming months). The valuation is really at rock bottom so even a modest improvement in underlying performance could drive a significant share price recovery in my view.
Impax Asset Management (LON:IPX). No good news to suggest this is the bottom. Sure it might be the bottom, but not a single green shoot, and monster outflows continue. Contrarian is my least favourite group! Usually means you have to wait and wait to get your reward!!
I hiold Living Reit (LON:LIVE) , which used to be called SOHO until a few days ago. The share price now in my portfolio is blank (leading to a valuation of zero for LIVE in the portfolio), even though LIVE's own stock page shows a price. I reported this via the green button a day or two ago but have had no reply and today the green button leads to a blank pop-up box.
Any ideas?
Pop-up box working OK for me at 10:30
Try again, all that is missing on the Stock Report I see are the Stock Ranks. Edit, all the summaries are in red ink so we have to wait some more.
I have exactly the SME problem and reported it yesterday as well. Not fixed yet but they are looking into it
Thanks. Living Reit (LON:LIVE) has been fixed now.
Vodafone (LON:VOD) Needless to say, sold 60% of this on Monday at a slight loss. But I still get the last div. Why did the price keep falling when an industry specialist could see the value? Are UK investment professionals as bad as the UK civil service?
What I find amazing is ChatGPT said it expected the price to rise to circa 110 :)
Aye, but did it buy any itself. :-)
'Are UK investment professionals as bad as the UK civil service?'
nothing is as bad as those!
as incoming prime ministers always find out ;)
I sold out a few weeks ago - it looked to cheap but the price had been going down for a while. Suspect this acquisition could mean the future for Vodafone to remain listed on the ftse may be at risk. Think all the tracker funds that are linked to the S&P really help prop up US shares compared to FTSE shares and with a lot of big ftse companies getting taken out suspect the ftse will keep getting weaker and shares like Vodafone continue to be undervalued.
Any thoughts on easyJet (LON:EZJ) offer from Apollo? I'm delighted by the emergence of a rival as I hold but disappointed that it is Apollo as they have a habit of making offers and then walking away. Tempted to take the price today at 665p. Do we think Castlelake might top this?
Taken profits personally. My insight was that Castlelake would get to an approved offer and that there would be some competitive tension. From 670p it's over to the arb guys to make the last few %. I have no edge on regulatory approval and closure dynamics
Sold 1/2 at £6 which doesn’t seem a great deal now, but happy to bag at least some profits just in case. Was a big holding for me!
Is it me or are prices not updating on the site at the moment?
edit: looks like working again.
Prices are delayed, so they will not update for awhile.
Try Google Finance.
Share prices on here have at least a 20 minute delay.
15-20 mins delay - do not use stocko for live pricing!
instead: use trading view, sharescope, google finance, apple finance etc. etc. if you want up to date pricing, particularly at open and close (and especially if you are dealing in the US markets!)
Avingtrans (LON:AVG)
No mention of the 10% placing at par.
If they can get it away at last nights closing price, they will have done very well.
They have got it away at a price of 630. The current price shown on SP is 659.
Hays (LON:HAS) guides to top of analyst expectations, which is positive given the profit range is quite wide! However, year-on-year growth is still negative at -5%, and the company indicates cost cutting is driving success.
Estimates via their website:
Yes, can’t get excited about that sector but well done to others who are making £
DCC (LON:DCC)
There's a piece in today's FT where the founder of DCC, Jim Flavin, rejects the takeover bid.
Here's an AI summary :
DCC founder Jim Flavin has joined Aviva, Fidelity and Ninety One in opposing KKR’s £65.25/share bid, arguing it materially undervalues the business. He believes DCC’s refocused energy business, high returns, strong cash generation and soon-to-be debt-free balance sheet justify a valuation closer to £100/share. He accepts such an increase is unlikely but hopes shareholders reject the current offer.
Source: Financial Times article by Jude Webber, Founder of energy group DCC blasts board for backing takeover ‘on the cheap’ (10 July 2026).
(I hold)
Hi Richard
I am a holder ( saw this as part of my core holdings portfolio) seeing the planned transformation as well considered. I ( no particular basis of assessement like Flavin!) declined the tender offer (too low) and was in 2 minds about the offer at £65. The transformation has not been allowed to bear any fruit but to me take out at £70 is closer to what I would see as fair given where we are
If KKR walk away the board will need to deliver being minded to accept the KKR offer says to me are they not. Not sure the three houses and Flavin have enough leverage to upset the apple cart