Daily Stock Market Report (Fri 11 April 2025) - CCT, XLM, NIOX, BP., HLCL, OPT, KIST, ONDO

Good morning! We've reached the end of another tumultuous week in the markets.
The FTSE rose 3% yesterday and is set to open up by another 1% this morning, around the 8000 level.
After the dramatic announcement yesterday of a "90 day pause" on Trump's tariffs, excluding China, today is shaping up to be a quieter day for headlines.
2pm: I've made a clean sweep of today's announcements. Have a relaxing weekend - I think we all deserve it!
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
BP (LON:BP.) (£54.9bn) | Upstream production lower quarter-on-quarter. Gas/low carbon energy: realisations broadly flat. Net debt up $4bn due to working capital build. | AMBER (Graham) [no section below] Sentiment around BP has been poor, especially in comparison with Shell (LON:SHEL), rightly it seems as BP's earnings forecasts have been slipping for some time. Today's guidance for lower production, partly due to divestments, looks to have been priced in already. BP had net debt of $23 billion at the end of 2024 and the $4bn increase in Q1 is expected to reverse. It has an investment-grade, single-A credit rating from all ratings agencies and so it should be reasonably secure. Since it's a resource stock, I take a neutral stance by default. | |
Niox (LON:NIOX) (£280m) | SP down 20% | AMBER/GREEN (Graham) Some pros and cons here. The potential PE buyers have walked away, and the stock is undoubtedly expensive against short-term earnings. At the same time, the company's growth and improving quality up to this point are intriguing. | |
Helical (LON:HLCL) (£215m) | SP up 5% Forward sale of a joint venture (City office, 100 New Bridge Street) for £333m. Will distribute 50-100% of net profits to shareholders. Net debt currently £127m. | AMBER/GREEN (Graham) [no section below] Taking a moderately positive stance here as the entire REIT sector appears undervalued. Helical's most recent interim results showed net tangible assets of £408m (331p) and thanks to disposals, their pro-forma loan-to-value was only 15.9%, "its lowest ever level". The sale announced today is expected to trigger shareholder returns after it completes in April 2026. This stock carries additional risk due to its small size and dependence on the success of a small number of large projects, but I expect that the £215m market cap leaves scope for plenty of upside if they progress as planned. | |
Optima Health (LON:OPT) (£150m) | Acquires Cognate Health for up to €9m, adding €7m revenue and €1m EBITDA. Cognate earned PBT of €0.86m in 2024. The Board will continue to evaluate bolt-on acquisitions. | AMBER (Graham) [no section below] This provider of employee health and wellbeing services only listed in October 2024, when it demerged from Marlowe (LON:MRL). The acquisition today relates to a company providing very similar services in the Republic of Ireland, expanding Optima's geographic reach and customer base, and enabling it to more easily serve customers with employees in both jurisdictions. I think the valuation at 9x EBITDA (assuming a full earn out) is probably fair and the rationale makes sense. I'm neutral on Optima until it develops more of a track record as a standalone entity and I have more time to evaluate it. | |
Kistos Holdings (LON:KIST) (£101m) | 8,050 boepd, in line. Adj. EBITDA $95m. Statutory loss $52m. FY25 production guidance reiterated. | AMBER (Graham) no section below] No particular view on this company, but I note that it's the current vehicle of Andrew Austin (17% shareholder). While running iGas Energy, he transferred £10m of iGas shares to an American firm, Equities First Holdings LLC. The arrangement was described as loan to fund the acquisition of iGas shares, but that's not how I interpret it. Equities First was the same firm used by Quindell's Rob Terry. I personally wouldn't touch the stock of any company managed by CEOs who have used Equities First. Although those who got involved with Austin's subsequent company, RockRose Energy (RRE), did very well indeed. Let's hope he can guide Kistos to similar success. | |
Character (LON:CCT) (£47m) | Withdraws market guidance for FY25. USA 20% of sales. Still confident company will be profitable for this financial year. | AMBER/GREEN (Graham) Downgrading this Super Stock by only one notch as the tariff problem is contained to a modest portion of their total sales and their cash position should help them get through this. | |
Ondo InsurTech (LON:ONDO) (£47m) | Revenue +40% (£3.8m). EBITDA positive by end FY March 2025. Cash £4m (before the repayment of a £1.3m loan note). | AMBER/RED (Graham) [no section below] I'm going to downgrade this a notch to AMBER/RED as the assumptions behind a valuation at such a high multiple of sales must be terrifically bullish. The company says that "annualised contracted recurring revenue" is now £5.9m but this includes the revenues for a pilot scheme. If the pilot is successful then all bets are off but for now the cash balance isn't particularly high (less than £3m) for a company that is expected to remain loss-making for the next couple of years, even if it is producing positive EBITDA on a run rate basis by the end of the current year. | |
XLMedia (LON:XLM) (£13.4m) | They will buy back up to 70.9% of their shares at 11p. No further distributions prior to suspension. | PINK (Graham) Company suggests that the returnable cash value is no more than 10p in their base case scenario. So the 9.8p share price is fair enough. |
Character (LON:CCT)
Down 7% to 240p (£44m) - Trading Update - Graham - AMBER/GREEN
I’m getting vibes similar to 2020 when I read some of the announcements this week. The macro situation has made it impossible for some companies to make forecasts regarding their future performance.
That’s the case with Character, designer and distributor of toys and games. Their manufacturing takes place in China and as they outline today, 20% of sales are to the US and now presumably subject to a 145% import tariff.
The Board's visibility for forecasting sales to USA (which were c.20% of Group turnover in the last financial year) and its ability to assess the financial implications for the Group have been considerably obscured by these events. Consequently, the effect of the imposition of the trade tariffs will be felt in the second half by the Group and, as a result, the Company is withdrawing the market guidance for the year ending 31 August 2025. Despite this, the Board remains confident that the Group will be profitable for the current financial year as a whole.
For H1 (the six months to February), trading is anticipated to be in line with H1 of the prior year, when adjusted PBT was £2.1m.
The Board is confident that Character can “ride out the storm”.
Prior Forecasts
Checking the forecasts that were in place prior to this update, I see that FY25 was expected to be very similar to FY24. For example from Allenby:
FY25 revenue £123m (FY24: £123.4m)
FY25 adj. PBT £6.7m (FY24: £6.6m)
Net cash was forecast to increase from £13m to £16m. As I noted in January, the company has been spending some of its funds on a £2m buyback.
Graham’s view
I am often inclined to treat the withdrawal of guidance as worse than a profit warning - as I would much prefer to have a guide for how bad things are, rather than no guidance at all!
In the case of Character today, however, the blow is softened by a number of factors:
Affected sales are a somewhat small (20%) portion of their total sales.
We have guidance that they will still be profitable for the year as a whole (although this does give leeway for a loss in H2).
Their healthy cash balance should help them through this difficult period.
Therefore I’m happy to downgrade this by only one notch to AMBER/GREEN.
This reflects the risk that lost sales to the US could be very costly in the short-term. For example, the risk of an inventory build-up or agreements with manufacturers that need to be restructured. It wouldn’t surprise me if Character lost about a year’s worth of profits and was still dealing with the fallout of this problem a year from now.
For now, the share price is refusing to fall out of the bottom of the range it’s been in for last two years:
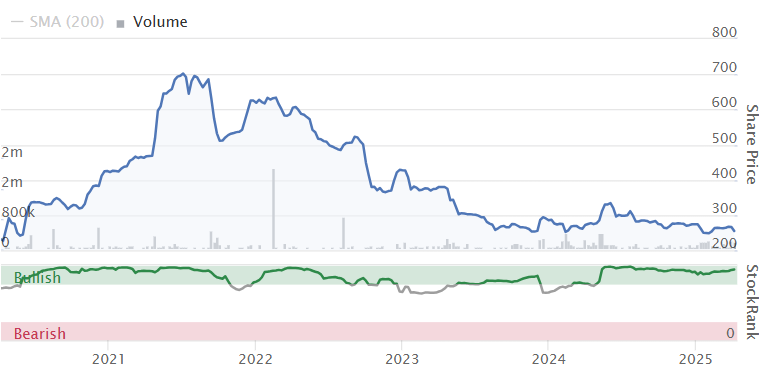
Especially considering the company’s cash balance, I’m comfortable retaining a moderately positive stance here. But maybe they should consider a 90 day pause on buybacks?
XLMedia (LON:XLM)
Up 3% to 9.8p (£14m) - Tender Offer - Graham - PINK
I noted last week that XLM had funds higher than its market cap, and was sending cash back to shareholders. But this isn’t a type of trade that I go for these days, having learned the hard way that taxes, costs and delays often lead to disappointment.
This paragraph in today’s announcement is key, discussing potential tax liabilities:
While there is potential for both upside and down side to these calculations, in its base case scenario, the Board does not expect there to be more than approximately 10p per Ordinary Share of returnable cash value remaining in the Company assuming full take up of the Tender Offer. Further returns, if any, will follow settlement of the Company's liabilities as part of the liquidation process.
The tender offer announced today is at 11p per share, but it’s only for 70% of the company’s remaining shares.
The remaining 30% of shares will be suspended and then I guess there should be some additional distribution to those shares at some later stage.
With the company itself estimating that 10p is the cash value of the shares, I can make no argument against XLM’s 9.8p share price today. And I’m relieved that I stayed sceptical of the initial cash figure that I calculated last week (£18.9m) - taxes and shutting down costs are always bigger than I expect!
Niox (LON:NIOX)
Down 19.5% to 56.67p (£225m) - Response to Rule 2.7 announcement & Strategic Update - Graham - AMBER/GREEN
This is not a share we’ve covered regularly here in the past, perhaps because it’s in the life sciences sector. I see that NIOX is the company previously known as Circassia that traded under the ticker CIR.
The company makes medical devices for asthma diagnosis and management.
Today we learn that a PE buyout fund has decided to not proceed with an offer for it.
Further to the announcement made by NIOX Group plc ("NIOX") regarding a possible cash offer for NIOX by Keensight Capital ("Keensight"), Keensight confirms that, in light of the current macro-economic backdrop, it does not intend to make a firm offer for NIOX.
I’ve been looking through NIOX’s most recent annual report for clues as to the company’s exposure to the US-China trade conflict. Medical devices are not exempt from Trump’s tariffs at present.
My initial search isn’t coming up with much specific info, only broad statements. For example:
NIOX outsources a number of important functions to a range of suppliers. In particular, the Company’s products are manufactured and distributed by third parties.
Their recent full-year results announcement (1st April) contained no commentary on the potential impact of tariffs.
Response to today’s news: NIOX have discontinued their sale process and have also given the market a reassuring trading update:
As noted in the preliminary results announcement on 1 April 2025, the current year has started well. Sales growth in the first quarter for the Group as a whole was 18%. Net cash as at 31 March 2025 was £15.4m.
An updated outlook statement and confirmation that full-year expectations were unchanged would have been most welcome!
Graham’s view
I was an asthma sufferer myself which gives me an extra reason to support this company’s efforts to improve the diagnosis and management of this condition.
The recent results showed the company making a clean pre-tax profit of £7.8m, up from £4.1m in the prior year.
Pre-tax profit is set to grow strongly again in the current year, supported by revenue growth of 13%. Although with Q1 growth of 18%, maybe they can beat that forecast?
I note a recent uptick in EPS forecasts:
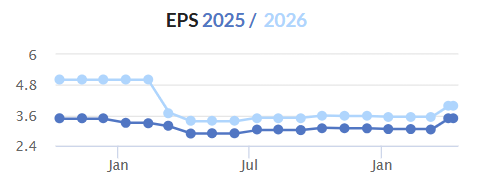
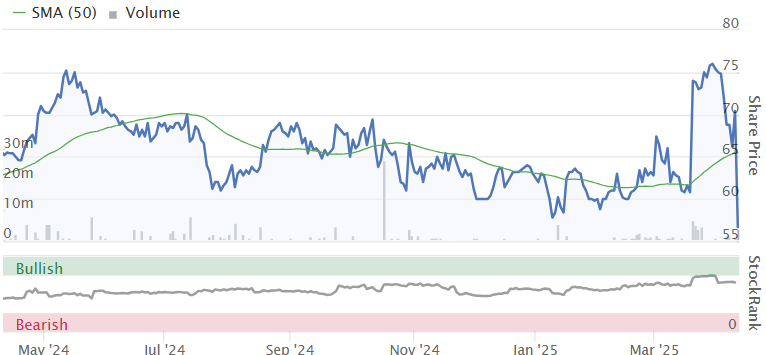
Although the share price is down today, that doesn’t seem to have anything to do with the specific performance of the company, although it likely does reflect macro risks that the company faces.
I’m leaning towards a positive view of this stock as, although expensive relative to earnings, the growth figures are promising and profits are becoming increasingly meaningful.
The company also seems to be shareholder-oriented, returning surplus cash to shareholders in a prompt manner. From the 2024 results statement:
The Board has decided to adopt a policy with regard to the return of cash to shareholders, given that for some time the Group has generated cash in excess of its investment needs. The first opportunity to utilise this policy is likely to be towards the end of the current financial year. Going forward, the Group will, on a rolling basis, return 80% of free cash flow to shareholders in the medium term, through ordinary dividend payments and additional cash returns.
In conclusion, I’m going to give this an AMBER. I would like to be more positive, but I need to temper my enthusiasm for a few reasons:
Even after today’s fall, the £225m market cap is a high multiple against forecast earnings over the next few years.
The potential PE buyers, having considered the risks in the current macro environment, have walked away.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

40 comments
Hi Tommy
Fingers crossed it all comes good health and portfolio wise. Post more… you obvs have value to add.
P
Thanks Graham, for yet again a Stirling comprehensive report.
So some random thoughts for a Friday night.
Yes I have a glass of wine as no swim training tonight, and yes I am focusing on the positive!
Outside of the world of investing, I have personally been through the worst fortnight in my life, and I am still living and breathing. A long journey lies ahead and it is not going to be pleasant. But I am alive, I have not as good health as I thought at the start of the week, but it is a lot better than it could have been, and there is a path through this, and more tests still to be done. Thank you GP, thank you NHS, ok the wait might be how long, but I am in several queues and still doing tests but there is a plan. Then there are several other things to just have to work through which are going to be ouch ouch and ouch but if I am on a glass half full I can see the other side of the river, lots of rocks but I can at least get out of the rapids. Or maybe it is just a small island and I am not where I think I am in crossing the rapids, we shall see what tomorrow brings. Park Walk and the Yorkshire Masters Swimming Championships, that is easy what tomorrow brings :)
As to the financial world, well I did the year end accounts on 05 April 2025. Sorry habit of doing tax returns for various family members and apart from myself now no one needs to do one, so tick I have done good since taking over various family members money from advisors. Son do Good, Little Brother do Good.
My girls, well the last month has been hard on their JISA's, but they are still up overall when you look at their lifetime and it is a while until they can access, if they chose to do at that point, so right decisions made, granny has put a little gift in for the tax year, so keep drip feeding them when we can from the family not as much as the past but anything is better than nothing. Ouch but overall Dad do Good if looking beyond the 12 month time frame.
Mum, her ISA (aka Pension) obviously what it was on 05 April and what it was 06 April different story. So mum was able to withdraw to give the allowed gifts of capital to me, Big Sis, and the four grandkids, took all dividends to enjoy life, and as of 05 April had a capital gain of about 1% over the year (so about 3.4% if you include the withdrawal of capital), and the dividend income was ~8.9%. A big thank you to Ken and various others on the income dialogue - yes it is not everyone's priority, and some might not think it is exciting, but when mum is 83 this year and you can say plan on keep living life, doing good, enjoying yourself, not worrying about what the central heating costs, or modifications to future proof the house. Son do Good.
Big Sis, well we had gone to cash on the basis she was moving house and setting all the financing up for that to break chains and all that, so forget 8 months of the year. Role forward, overall down about 1% for the year after life changed in several walls and starting to reinvest, this is now all about getting a passive income and allowing her to reduce hours, or potentially stop work totally. So not great, but following Mum's ISA plan, lots of small investments which give a good yield. So I have a checklist, I am trying to follow that check list. Whilst she doesn't need the cash today, dividends are reinvested, but as soon as she says the word, they pay into her current account. So Little Brother doing ok, lets see how next year is watch this space!
As for me, well life see the first paragraph.
So ISAs sold before Christmas through necessity.
So left with two SIPPs, on AJ Bell and one Vanguard.
I will start with Vanguard, this as the name says it is about low cost ETF investing, I will be honest I need to re-read Edmund Shings book about momentum investing and moving averages and basically doing a once a month check and follow that. It is a bit like Eds portfolio but with ETFs. Anyway overall a 4.2% gain, so not as good as it could have been, missed the big spikes up, but also missed the recent draw downs. I am trying not to do my Buy High, Sell Low, Buy Even Higher, Sell Even Lower strategy here. So for me I did ok, could have done a lot better, but slept at night which with everything else going on is important. Slowly even with the volatility going on right now, I am trying to remember what the notes I had written in Covid were, I bought back but too early, got nervous and lost more. This time I am going back into the market with smaller purchases on the down days, Vanguard Funds - Vanguard S&P 500 UCITS ETF (LON:VUAG) is down 5% then buy a few at lunchtime, don't bet the house, just drip feed in again this is a several year journey.
AJ Bell, this is the start of my follow what I have done for mum strategy, I am just under 5 years from possibly starting to draw my pension, so looking at what income can I get, and how do I build a good income portfolio. So moving away from a few larger positions (e.g. 10 maximum 20 holdings in total) to lots of smaller positions, so yes I miss out on the big gains from things like offers on Care REIT (LON:CRT) but also I am not hit by big falls on a profit warning. So for the year an income of about 6.2% achieved, my model pension calculator assumes 5% is achievable, with a 4.2% capital gain, obviously on 05 April...so better than the Vanguard, but more actively involved here as this is where I see the future for my personal investing focus.
So yes I am probably missing out through moving a chunk of my pension into income earlier than I need to, but it is also about getting that confidence within myself that I can get the income I need to retire when I want to.
So thank you to the Stockopedia team, I have been here a long time now and it has been a good journey! And I will continue on that journey. You are worth the fees!
Thank you to the fellow posters, sorry Ken no detailed analysis but my brain cannot cope with that right now, I am on a simple checklist if things meet that then that triggers buy or sell.
So it is a good day, life is ok, I am still here, I am still investing, I did good, could do better but then every day is a school day!
Good luck all
Tommy
Tommy H. ; I understand the need to set down thoughts at times such as you just experienced.
My recent experience of the NHS Cardiac Unit at my local hospital, yesterday, was excellent and only took two weeks from when booked to get the CT Angiogram. You will be in good hands.
Realised a total goof on my maths, sorry folks, good job it was not a detailed analysis, AJ Bell total gain for the year was 4.27%, but as the income was 6.2%, that actually was a capital loss of 2%...
Thanks TommyH for this post. There is something very therapeutic, even reassuring about your take on things. Good health is true wealth. Good luck
Reading all the various comments on Trump here today, you need to be aware of just who is feeding him and Vance their ideology. Check out Curtis Yarvin, aka Mencius Moldbug. Spine chilling.
https://en.wikipedia.org/wiki/...
For the first time since subscribing to Stockopedia I’ve stopped reading the comments on the daily stock market report thread, and just read the excellent analysis by the team. I might miss a few good posts, but each time I’ve looked, gone are the often excellent replies on the shares covered by the team that help us with our investment decisions, and instead too many opinions and replies to them on Trump and his character or other off topic subjects. People are free to post what they like, but is it time to focus more on Companies again?
Ken, we've just had one of the most dramatic two week periods in macro news in quite some time. An objective measurement of this is given by VIX hitting 5-year highs. I'd give some slack to people wanting to discuss this - it's not permanent! By the way, I was thinking of you when asking for a 90-day pause on CCT's buybacks. Maybe I don't support buybacks as often as you think! G
Good point Graham and knowing that you are relaxed about the current comments probably means my post is not what many here think about them either.
As for buybacks, I decided after our last posts where we disagreed about them not to post to post a reply again unless it seemed obviously detrimental or beneficial for the share price. It would be wrong for you to refrain from posting your buyback views for fear of yet another counter reply from me!
Though I don’t like buybacks (and the current widespread Investment Trust buybacks are failing, with some Trusts admitting so as their discounts widen even more) I agree some work well if executed sensibly; like when Management think the share is good value. That’s what Next (LON:NXT) do and their buybacks over the years have been very effective. So like you in reverse I don’t always denigrate buybacks.
Yes,a Black Monday followed by a Fantastic Friday, all in one week! The weather hasn't been all that bad either but seriously, I'm looking forward to more gains than losses next week.
Ken
A bit unfair on folks I feel. As Megan wrote on 4 April
“It feels a little futile to be writing a Week Ahead in these conditions. Financial results don’t matter much when the world has tipped over the brink and into an all out trade war and the biggest economies are now hurling tariffs at each other.”
This is the worst scenario in markets I can remember and detailed analysis of individual stocks in isolation won’t help – as I can see in my portfolios 8-(
Jim. I’ve already replied that I accept my post was misguided.
Does anyone have the link to the spreadsheet that tracks the colour rating's given to stocks
Gag, I haven't updated that recently, sorry! https://docs.google.com/spread...
Thanks. Can you keep the link at the top of each day's report please
thanks Graham
Quick note re: the format. I've added direct links to each news item in the summary table above. I hope this is useful and just wanted to highlight it as we've not been linking directly to the news recently, as the new news format rolled out. But now you can go directly from the summary table to the actual news item! Cheers. G
Yes , its the old question , who's the more dangerous , evil people or stupid people ?
As the much missed poster "wolf of small street " said on his brilliant summer bowls thread "avoiding stupidity is easier than seeking brilliance" what a great line and so apt for current times.
I don't understand why the market and the media are surprised by the events of the past month.
If you let a 5 year old loose in a sweet shop all day it is very likely that he will eat chocolate all morning and then be sick all afternoon.
If you give a malignant narcissist an enormous amount of power you get the results we are seeing.
Narcissists:
Wants to be the centre of attention with all eyes on them, so they do outrageous things as often as possible.
Are only concerned about their emotions at that point in time. So they change their opinion and position on a whim.
Are focused on themselves, so they have a weak grasp of reality and facts. They build an alternate reality where they are super human. A genius who sees things that other people do not see, which means they ignore advice and all types of social norms.
Has a superiority complex where others are inferior. Trump said on Tuesday that world leaders were calling him and saying " Please sir, i am begging you to cut a trade deal with me'.
Malignant:
Enjoys humiliating and embarrassing other people.
Enjoys inflicting pain on others. Trump has a policy where suspicious looking people with tattoos that might me gang related are sent to a Supermax prison in El Salvador without any trial or due process. There is no hope of release because they are outside of the legal system.
Trump is not interested in keeping to this 90 day pause. It was only announced because the Treasury Secretary threatened to resign. So no surprise that today Trump has said he is putting tariffs on pharmaceuticals. This will mean poor people will not be able to afford to buy their medicine. So it is double win for him.
Eventually the cabinet will sign the 25th Amendment, Trump will be declared mentally unfit and Vance will take over. Until that time i am in gold, silver, cash and gold / silver miners.
Vance might be Trump on steroids, be careful what you wish for!
Trump is mentally ill, Vance is not but should know better.
He could be but equally he did compare his master to hitler in the past, so I think he is one who will kiss up for power when needed, I do fear for the US though this lot seem hell bent on blowing everything up so it does make you wonder if there will be anything left to salvage in four years time.
I think you’re completely right with your comments. As mad as it sounds we have a next door neighbour who I i am convinced is a narcissist. Displays all the above, attacked another neighbour who stood up to him and even as he was arrested for GBH still insisted the sky was purple. Until I experienced it personally I didn’t realise narcissists are very dangerous people. Sorry not investment related but just wanted to share.
Can they kick him out ? its seems crazy they have given him so much power to run amok and blow everything up without even sending him to the naughty corner for thirty minutes , other than when bond markets showed him who the real master is.
I also wonder how far away from a 2008 like event we were on last Tuesday evening.
There is a provision in the 25th amendment for the vice president and a majority of senior Republicans to declare him unable to discharge the duties of his office, but it’s vanishingly unlikely that this is going to happen.
I think Stocko did an article recently about insider buying and one of the key takeaways IIRC concerned clusters of purchases by insiders. For anyone interested then, I've been taking note of this phenomenon at Trifast (LON:TRI) where Nick Mills has been loading up with over a million quid's worth of buys since November and today's RNS indicates some additional purchases by a NED and the Non-Exec Chair bringing both of their holdings above £100k. CEO, Iain Percival topped up £50k in February to add to a sizeable purchase last August. The Director's Dealings page on Stocko is a sea of green.
Hopefully Harwood / Rockwood have better luck with this one than with Niox (LON:NIOX) .
The NIOX PE offer from Keensight has been withdrawn and the shares were down just over 20% at open. Trump's tariffs bite again. I had sold once the offer was announced leaving 10% price on the table which seemed sensible in this febrile market. The fall seems excessive as the RNS says NIOX is in discussions with other parties, so I bought back in. The shares have already bounced 5%. This is, in my view, a high-quality company which will find a home with some medical equipment manufacturer out there, just not Keensight.
The fall seems excessive as the RNS says NIOX is in discussions with other parties, so I bought back in
Good company, but that’s not how I read it:
“the NIOX Board has also concluded that continuing the Private Sale Process ("PSP") at this time is unlikely to yield an optimal outcome for shareholders. Accordingly, the PSP is being discontinued with immediate effect.”
I have no idea what's going to happen with Trump, the market and tariffs, but for reasons I don't fully understand gold has been in an uptrend for quite sometime whether that will continue?
My approach to participating in its current popularity is through Ramsdens Holdings (LON:RFX) that I added to yesterday using the proceeds from the sale of my fortunately modest holding in Treatt (LON:TET) . I now have a full position in the former, which trades at a sub 8 PE with a dividend yield in excess of 5% and cash on the balance sheet.
I doubt Ramsdens Holdings (LON:RFX) will ever be highly rated, but I don't know. If yadi's speculation regarding the gold price proves correct, perhaps it will!
I haven't done so but will also look at H & T (LON:HAT). Both are counter cyclical.
I really like Ramsdens which I don't own but it is extremely high on my watch list. A quality business with good metrics, cheap and with a lovely 5.5% dividend which also seems uncorrelated to the general mayhem out there.
Yes very keen to buy some Ramsdens Holdings (LON:RFX) but don't want to add after it's just spiked higher (although still cheap so maybe I should just buy now). For gold, I do hold H & T (LON:HAT) and also Golden Prospect Precious Metals (LON:GPM) which has done well but still on c20% discount. To keep things simple I should probably also buy some direct gold, eg via £SGLN
"for reasons I don't fully understand gold has been in an uptrend for quite sometime whether that will continue?"
Gold has been useful investment for the last ten years and here will be many charts online which give a perspective on how it has performed versus other assets. A recent short program on Talking Pictures showed life in the Royal Mint circa 1965. The commentator talked in sober tone about Gold Sovereigns having a face value of £1 but would actually cost near £5 to buy - I cant remember the exact figure but perhaps other subscribers saw the programme..
Apart for the various economics of the gold price there is quite a strong culture in some parts of the world for holding gold. I would imagine that recent global actions will have only intensified their desire to hold a physical asset.
There is an old investment adage that once you see the bandwagon coming it's too late to jump on board. Inflation might be a test of the gold price at some stage. I would also guess that there might be some inevitable profit taking . Who knows.
As an aside there is a theory that some of the gold at Fort Knox has disappeared. Sounds like something out of a Bond novel?
https://www.nbcnews.com/tech/e...
A trade for the next 4 years
GOLD has been the bright spot in this tumultuous two weeks.
This is one trade/investment where your views on macroeconomics matters more than reading the accounts and reports.
A process to move away from the dominant dollar and treasuries has started in earnest and we are at the early stages. Nothing like this we have witnessed in the last fifty years.
The governments and central banks all over the world are the big buyers and retail investors are far behind.
It may be called a speculative market but I have increased my bet.. if you think $3000 is high , wait until it hits $4000.
Yadi
The gold/silver ratio is at extreme values also. Might be worth watching silver for a catch-up run.
I certainly expect to hold gold for some time to come.
Totally agree re gold , Trump has really blown up the US in my opinion they need to roll over $9 trillion of debt this year alone I can't see China, Japan, UK and EU queing up to buy them , by all counts they are trying to get all US domestic banks to load up with them what a mess.
Eh, what, ePARO?
Posted a picture of the GDP figures from the ONS from my mobile. Not showing here for some reason. Cannot amend post as there's no edit button on an Android mobile! Just ignore.