Daily Stock Market Report (Fri 11th September 2026) - PAF, STEM, TRN

Good Morning!
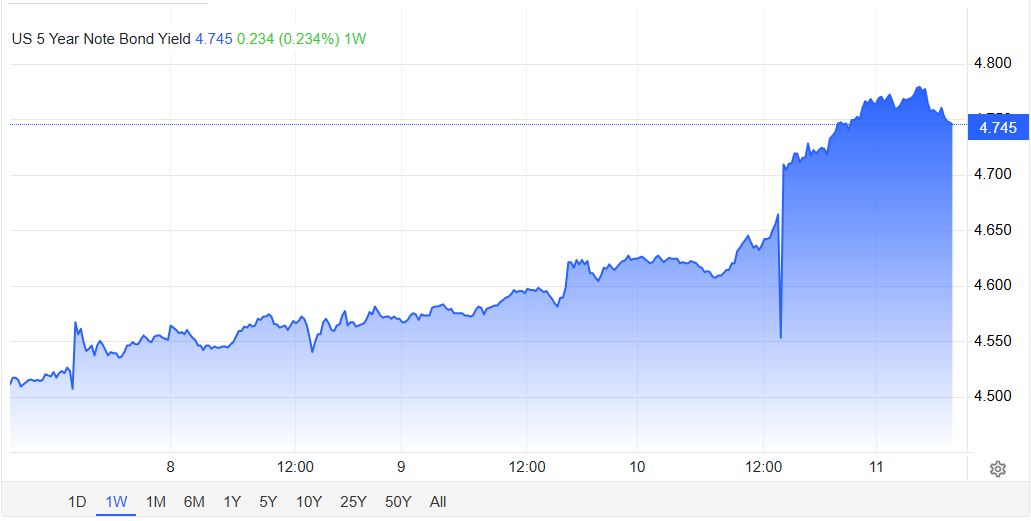
Oil prices above $100/bbl and rising bond yields continue to weigh on market sentiment today. The US 5-year started the week at around 4.5% and is now close to 25bps higher:
Perhaps the only good news is that the UK economy grew faster than expected in July, the Office for National Statistics said. Economists had predicted no growth, but the figure came in at 0.4%, following 0.3% in June and zero growth in May. Expansion in the services, production and construction sectors were behind July's figure.
Overnight market movements:
The FTSE is up 0.2% at 10,629
S&P 500 is up 0.4% at 7,621
Brent crude (November) is down 2.0% at $103.34/bbl
Gold is up 0.8% at $4,352/oz
Bitcoin is flat at $77,266
Today's report is now complete.
Spreadsheet accompanying this report: link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Pan African Resources (LON:PAF) (£3.07bn | SR52) | DFS shows annul production 35-40koz with 15 year LoM, Past-Tax NPV13 $109m. | AMBER = (Mark) This DFS looks reasonable, but at $109m NPV versus a $4bn+ market cap, it doesn't really move the needle. More concerning is yesterday's trading update. While Headline EPS showed big increases versus the previous year, it appears to be a significant miss versus what was expected by brokers earlier in the year (I can't see any up-to-date coverage to provide any further guidance) This leaves the company on a historical P/E of around 10. This isn't expensive, but it stands out against smaller gold producers trading at P/Es of around 3 for the same period. Possible production increases and a stronger gold price may make FY27 look better, but every gold producer is looking to add production right now and are similarly exposed to gold price trends. Some investors may value the scale and consistency here, but given the much higher valuation than smaller peers, I keep our neutral view. | |
Berkeley groupHoldings (LON:BKG) (£3bn | SR57) | Anticipate pre-tax profits to be slightly weighted towards the first half of the current financial year, subject to the timing of completions. Expect net cash to be in the region of £250 million for the half year | ||
Trainline (LON:TRN) (£661m | SR82) | H1 Net ticket sales flat at £3.263bn, Revenue -1% to £233m. | AMBER/GREEN = (Mark) These figures aren’t great, at least on the sales side. However, they don’t need to be, given the low forward rating. The company is doing well at converting flat sales to increasing EPS. The CMA investigation remains a risk, but is unlikely to cause very serious reduction in profits, whatever the outcome. With a low forward P/E and sizable share buyback announced today, it makes sense to keep our mostly positive view. | |
| Everplay (LON:EVPL) (£427m | SR60) | Wardogs passes one million copies sold | The 100-player tactical first-person shooter game, has exceeded one million copies sold in day one after launching into Steam Early Access, also reaching over 340,000 concurrent players on Steam. | |
| SThree (LON:STEM) (£359m | SR98) | Statement re Possible Offer | Circle8 and SThree and confirms that it has submitted a proposal to acquire the entire issued and to be issued share capital of SThree in a possible cash offer by Circle8 for SThree.
No figures given. | TAKEOVER/AMBER = (Mark)
I can see why the market is sceptical about this possible offer. The bidder doesn’t look particularly credible to me to be making a cash offer of the scale required to win over shareholders. The RNS reads more like the precursor to an all-share merger. |
C&C (LON:CCR) (£331m | SR56) | Reached an agreement with Asahi UK to acquire all of its UK wholesale interests for nominal consideration. | ||
Integrated Diagnostics Holdings (LON:IDHC) (£224m | SR72) | H1 revenue +37% to EGP4,856m, EBITDA +38% to EGP1,325m, Adj. PAT +40% to EGP802m. Cash EGP1,926m (25H1: EGP1,708m). | ||
Kore Potash (LON:KP2) (£220m | SR24) | LBT $753k (25H1: $435k LBT), cash $7.54m (31 Dec: $10.56m). | ||
Vanquis Banking (LON:VANQ) (£199m | SR40) | Ian McLaughlin has informed the Board of his intention to step down as CEO for personal reasons by no later than the end of the year. | ||
Atlantic Lithium (LON:ALL) (£119m | SR18) | LBT $6.92m (FY25: $6.50m LBT), Cash $9.74m (FY25: $5.39m), after $18.3m equity rise in period. | ||
KEFI Gold and Copper (LON:KEFI) (£90.3m | SR8) | Further update following its announcement on 7 Sep regarding the serious security incident at the Company's Tulu Kapi Gold Project. All employees who were affected by the incident have been accounted for and there have been no further fatalities or injuries sustained. | ||
Cobra Resources (LON:COBR) (£49.9m | SR5) | Completed initial reverse circulation drilling programme at the Blue Rose copper-gold-molybdenum discovery, including 74m at 1.02% Cu and 0.25 g/t Au from 70m. | ||
Gemfields (LON:GEM) (£48.9m | SR28) | September 2026 Commercial-Quality Emerald Auction generated $29.6m revenue from all 44 lots sold. Average price $9.72/carat. | ||
One Health (LON:OHGR) (£39.1m | SR81) | Trading in the early part of FY27 remains strong and in line with management expectations. | ||
Kendrick Resources (LON:KEN) (£32.7m | SR18) | Results for an additional 4 diamond drill holes including 3.05 wt% LREO over 37.9m | ||
Fiinu (LON:BANK) (£12.9m | SR1) | H1 Revenue £371k (25H1: £0k), LBT £2.27m (25H1: £980k LBT), Cash £2.7m (31 Dec: £3.9m). | ||
LPA (LON:LPA) (£10.5m | SR81) | Has experienced strong trading, resulting in increased revenue, and adjusted earnings for FY26 are now expected to be ahead of current market expectations. |
(Market Caps - last night's close)
Mark’s Section
Pan African Resources (LON:PAF)
Down 1% at 125p (£3.04bn) – Trading Statement & DFS on Soweto Tailings Retreatment Project- Mark – AMBER =
Today's news is the release of a DFS on a tailings retreatment project, but we didn't comment on yesterday's trading statement, so I'll look at that too. One initial concern is that the RNS title appears to have a spelling mistake for the word "Tailings." This may indicate a lack of attention to detail, which is key in mining project delivery! That aside…
Tailings Retreatment:
In places such as South Africa, where gold has been mined commercially for decades, large tailings dumps are common. These are where the waste rock is deposited after gold has been extracted. Because these have already been processed, most of the gold has been extracted. However, not all of it. Typically, this waste may contain 0.5g/t. (It is worth thinking about what that means. Gold is heavy, so 0.5g is a tiny speck, and this is distributed amongst 1 tonne of ground rock.)
In contrast, a reasonable grade for an open-cast mine would be 3g/t. For underground mining focussing on specific quartz veins, the number may be 10g/t on average - still small amounts but many times more concentrated than tailings.
Despite the very low grade, tailings can be economic to reprocess. There are two advantages. First, the hard, energy-intensive work of digging up the rock and grinding it into a fine dust has already been done. Tailings can usually be mined by monitor, spraying them with a giant water jet to slurry them and pumping them to the plant. Secondly, sitting in the sun for years can oxidise some of the contained gold, making it easier to extract. Processing technology has also moved on, making extraction easier in some cases.
DFS:
Just because reprocessing is possible doesn't mean that it is economic. Nor is it always easy. One of my holdings, Goldplat, has a very high-grade (2g/t+) tailings dump but has struggled to get reprocessing off the ground for various reasons (type of material, permitting, plant availability), despite it clearly being economic at current gold prices. (Perhaps the only benefit of this is that I now know a lot about Tailings Reprocessing and the associated challenges!)
Hence, before committing capital to reprocessing tailings, mining companies treat these like any other project and create a Definitive Feasibility Study (DFS). This is the final, most rigorous study, with detailed engineering, accurate cost estimates and enough certainty for a company to make a final investment decision and for banks/lenders to use it to decide on project financing. A DFS typically covers detailed resource/reserve estimates, mine design and production schedule, processing/metallurgical flowsheet, capital and operating cost estimates, environmental and permitting status, and financial modelling.
Pan African is releasing this study today, and investors care most about the last part: financial modelling. These are the headline numbers:
Using a gold price of US$3,550/oz the project returns
- Post-tax NPV13 of approximately ZAR1.85 billion (US$109 million)
- Real ungeared internal rate of return (IRR) of approximately 29.55%
- Payback period of approximately three years, post-commissioning
The Company gives us an NPV13, meaning the net present value of cash flows at a 13% discount rate. This seems realistic to me. Investors need to be very wary of companies that publish NPV figures at a discount rate of 10% or, in some cases, even 5%. These would be far too low for most projects, let alone a new mine in some far-flung place. 13% for an established miner, but in a high-risk jurisdiction, is probably about right.
Investors can also sense-check the key production numbers:
- Annual gold production of 35,000oz to 40,000oz from STR, with Life of Mine (LOM) production of approximately 561,000oz over a project life of approximately 15 years
- LOM all-in sustaining cost (AISC) of approximately US$1,750-1,800/oz, excluding cost savings from renewable energy supply
- Value-engineered project capital estimate of approximately ZAR3.68 billion (US$216 million at ZAR:US$=17.00), which now takes into account the dedicated new TSF and associated remaining infrastructure
However, unless an investor is a mining expert, there is usually nothing of note in these numbers, and you have to trust the company knows what it is doing.
Gold Price:
The biggest issue I see with this NPV is that the gold price assumption looks a little high. At $3,550/oz, this is well below the current $4,400/oz spot price, but not that low in a historical context.
The NP13 of $109m is reasonable. But against a $4.14bn market cap, it is only 2.6% of the business's value today. It may well be worth more if gold prices stay strong. However, the reality is that this project doesn't really move the needle.
Trading statement:
We tend to get rather strange announcements from companies dual-listed on the Johannesburg Stock Exchange. UK market rules say companies should update investors if the likely financial outcome differs significantly from market expectations, as defined by broker forecasts. However, JSE rules require companies to update investors if expectations differ significantly from the previous period's results. Hence we get this wording:
Shareholders and noteholders are advised that the Company has a reasonable degree of certainty that:
- headline earnings per share (HEPS) for the current reporting period is expected to be between US 17.35 cents per share and US 17.94 cents per share, compared to HEPS of US 5.89 cents per share for the corresponding reporting period, an increase of between 195% and 205%, respectively.
A quick look at the Stock Report shows an analysts' consensus of 22.7c for EPS, so this may indeed be a miss, despite the big percentage increases.
There's not much research on Research Tree to guide us, but an Edison note from March this year does show 24.77c for FY26 EPS. While it is hard to say this is definitely a miss, it does look like a disappointing figure to me.
Production growth:
The good news is that production is forecast to increase further from the 275koz delivered in FY26:
Group production is further expected to increase for the year ending 30 June 2027 to between 280,000oz and 302,000oz, largely attributable to increased production from Tennant Mines.
However, FY26 came in at the very bottom of production guidance, and the bottom end of FY27 guidance would be only a very minor improvement.
Valuation:
Taking the midpoint of the company's FY26 guidance range, this is 17.65c EPS, or around 13p at current exchange rates. This puts the company on a historical P/E of 10. While it is hard to describe this as expensive, it is higher than the rating many smaller gold miners are on at the moment.
The Company's scale and consistency have value, and higher gold prices could drive higher EPS. If they can start to increase gold production from here, that will also help. However, these dynamics are hardly unique to this Company – every gold producer is trying to increase production and is exposed to the gold price.
Mark's view
I can see the attraction of this Company as a larger, and perhaps more stable, gold producer. With a £3bn market cap, it will attract investors who want sector exposure but wouldn't consider something with a £100m market cap. However, the operational and financial results look a bit disappointing to me, at least compared to expectations.
This leaves smaller investors with a dilemma: how much they value scale and stability versus smaller peers trading at earnings multiples half or a third of this company. Personally, I think we should be more cautious in our view, given that smaller peers look like a much better value right now. Roland's previous AMBER view looks about right.
SThree (LON:STEM)
Flat at 294p (£359m) - Statement re Possible Offer - Mark - TAKEOVER/AMBER =
It is strange that a "Statement re Possible Offer" hasn't caused a jump in the share price. Partly because the "Response to Media Speculation" RNS came out on Wednesday and caused a 15% jump in the share price.
Today we don't really get much more detail. The RNS goes into great detail on the strategic rationale for the move, but doesn't indicate a price.
Although this is described as a "possible cash offer", this is the sort of behaviour that typically comes with an all-share offer. SThree shareholders don't care what the strategic rationale is, just what they will get paid for their shares!
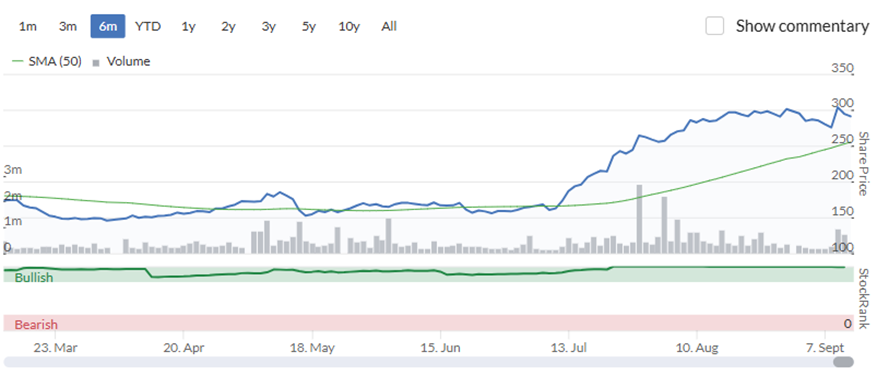
My second thought is that the market may have already got wind of this. After all, the share price has doubled since the start of July:
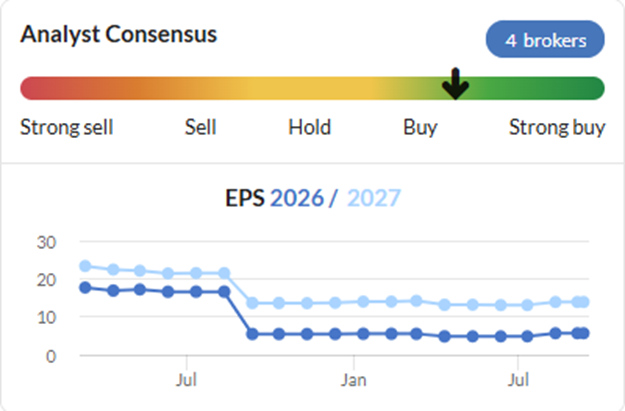
On no real improvement in trading outlook:
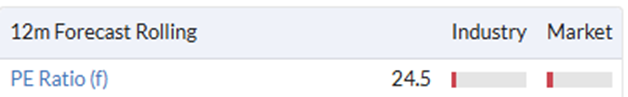
Making the shares look very expensive:
However, this move doesn't really stand out amongst the sector:
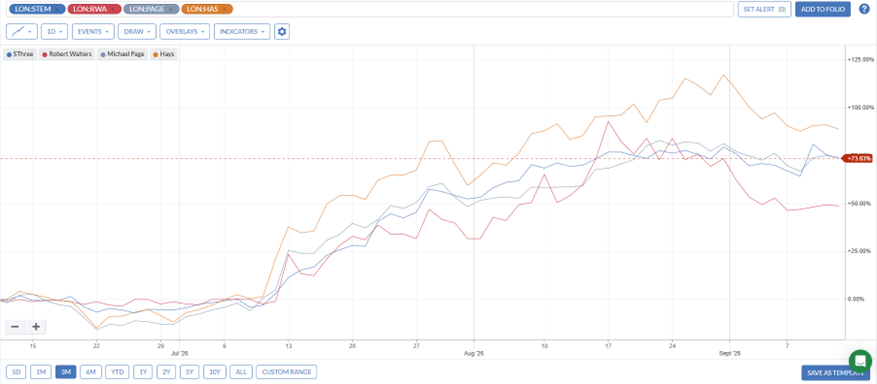
Investors seem to have decided now is the time to buy larger recruiters for a sector recovery, despite no signs of recovery in the actual financials or outlook.
The acquirer:
The only Circle8 I can see is this:
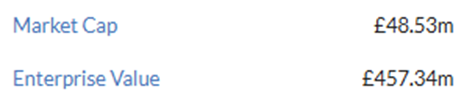
Assuming this is the right company, it appears to have been permanently loss-making since listing.
So straight away, this doesn't look like a credible cash bidder for a £350m market cap UK company.
Mark's view
I can see why the market is sceptical about this possible offer. The bidder doesn't look particularly credible to me to be making a cash offer of the scale required to win over shareholders. The RNS reads more like the precursor to an all-share merger.
Then there's the timing. Why make the offer now, after the shares have already doubled off lows? In general, I am sceptical about this recovery in the share prices of major listed recruiters. The market appears to have suddenly decided that a huge recovery in prospects is underway, despite little sign of it in company trading updates or broker forecasts.
This makes me wonder if this is like the housebuilders more recently, where every market assumption that things are suddenly getting much better gets repeatedly dashed on the rocks of higher bond yields.
That said, the momentum generated by this share price recovery means that the algorithms like the stock:
However, unless brokers significantly upgrade their forecasts in the next few months, none of these Ranks are likely to stay high once the algorithms digest the FY26 results, leaving the quant investor with a real dilemma.
With all this going on, I think we should remain neutral. AMBER.
Trainline (LON:TRN)
Up 2% at 195p (£661m) - TRADING STATEMENT - Mark - AMBER/GREEN =
Trainline describes this update as a "Robust first half performance", but I'd hate to see a half that wasn't robust!
Ticket sales were flat, and revenue down slightly:
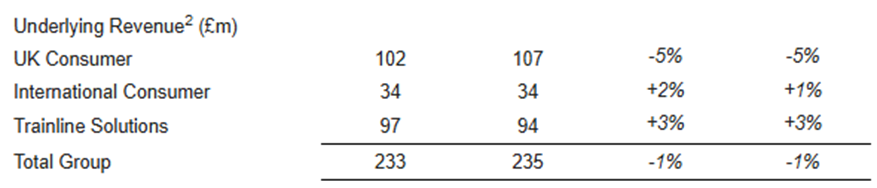
To be fair, this is a period when regulated train fares have been frozen.
And the company confirms it is trading in line with guidance:
Market guidance: Trainline reconfirms its FY2027 guidance for Group net ticket sales of between £6.2 billion to £6.45 billion, Group Underlying Revenue of between £440 million to £455 million and Adjusted EBITDA as a % of net ticket sales at c.2.9%, with International Consumer expected to breakeven this year.
While revenue looks like it is declining in real terms:
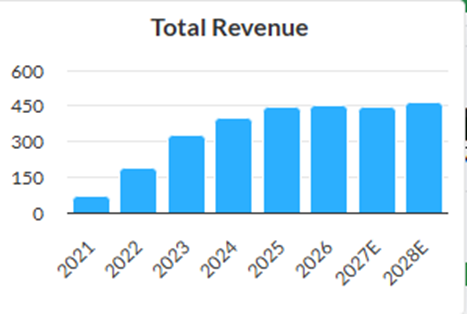
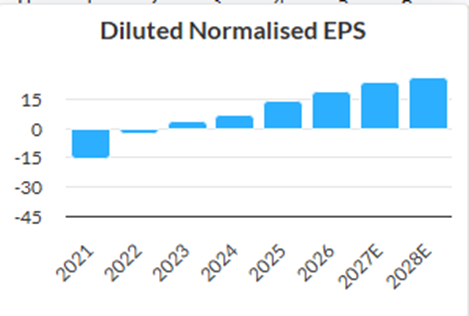
They are doing better at converting flat revenue into growing EPS:
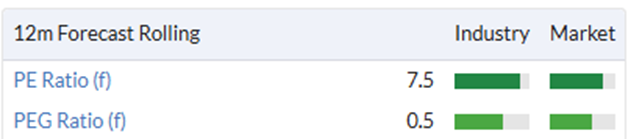
This makes them look very cheap:
However, it is tempting to think of the company as completely pointless. Why would users pay Trainline for something they can get from the train operators for free?
This risk is that the CMA feel the same way. We don't get much of an update on their investigation today:
Trainline is proactively engaged with the CMA in relation to its ongoing investigation on fees presentation. We are seeking to meet both the DMCCA requirements and the sector-specific requirements of rail retailing.
The good news is that Trainline also provides the back end for some UK train operators. So while banning ticketing fees would undoubtedly have a huge impact on their business, it would not destroy it completely. The reality is an outright ban looks unlikely; instead, the issue is how soon in the booking process fees are made visible to users. This could reduce booking demand but is unlikely to be catastrophic for the company.
Buybacks:
Perhaps the biggest news is the announcement of a new share buyback:
Trainline has today announced a new share buyback programme of up to £100 million. The new programme will commence upon completion of the existing programme and is expected to run over the subsequent 12-month period.
Given the sub-£700m market cap, this is a sizable programme and, if completed, should materially impact the share count and hence EPS.
Mark's view
These figures aren't great, at least on the sales side. However, they don't need to be, given the low forward rating. The company is doing well at converting flat sales to increasing EPS. The CMA investigation remains a risk, but is unlikely to cause a very serious reduction in profits, whatever the outcome.
With a low forward P/E and sizeable share buyback announced today, it makes sense to keep our mostly positive view.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

51 comments
CPI data is up, on the warm side and not consistent with doing nothing. Yields are rising across the board and look like a one way bet.... which is a little unpleasant for markets because stresses are already emerging. Looks to me like this is not Goldilocks at all....the economy isn't slowing and data is out of sync with monetary policy.... commodities are rising and the Dollar is falling. However equities seem to be taking it all in their stride today.... which may well be due to Oil having a weak day but who knows. Seems to me we are slowing running out of rope and a more cautious stance is appropriate.
RD
I, and others I am sure, appreciate you taking the time to share your respected view on things.
TY
AJ Bell rebrand update: I have received a call to advise that they are reverting back to the original colours.
Oh, good. But the designer has already been paid. lol
Hope HL do the same current app blinds my eyes
European Green Transition (LON:EGT)
Mentioned this in a more detailed analysis on the 13th Aug when trading at 11p.
Although it has moved higher since, this is still very much undervalued.
Experienced but also well proven management (Cathal Friel) targets £50M revenues in a couple of years. With about 14%-16% FCF generation, this should be trading around £110M market cap (40p) in 2-3 years time.
Tribal (LON:TRB) also trades at attractive multiples. I will try and write a detailed analysis in the next few days. However, management should stop wasting £6M in worthless dividends and use that money to buyback shares at current levels, enhancing EPS by 5% p.a.!
We hold both companies in our UK portfolio.
DYOR
All the best
Tribal (LON:TRB)
Takeover announced!
All the.best
Tribal (LON:TRB)
The volume today was a bit of hint ;-)) unfortunately not a large holding for me but I added a few this afternoon when I saw the prints going thru .
Well done Yiannos.
Tribal (LON:TRB)
We have been adding for 2 weeks now and have explained to our members (yesterday) why this was a takeover target as well after the Eleco (LON:ELCO) announcement.
Happy for you!
All the best
St Leger tomorrow!
It's the St. Leger race tomorrow. You can return to the stock market on St. Leger's day - Oct. 2nd. https://en.wikipedia.org/wiki/...
Originally run on a Wednesday which makes more sense of the saying!
It was actually the Derby which used to be run on Wednesday. And it's St. Leger Day, rather than St. Leger's Day. Sorry to be so pedantic.
Bodycote (LON:BOY) still above the offer price so presumably Market thinks there may be a counter-offer to come ?
We're still waiting for CVC to indicate whether or not they'll table a new competing offer.
Plus- mine paid ok. Check your records……
Today, we remember the innocent lives lost, their families, and all the heroes who stepped up and showed extraordinary courage on 9/11, 2001.
Well said
Here Here. I am still traumatised - lost my ex-manager on that day. I am still not able to watch any documentaries concerning that fateful day it's too harrowing.
Currys (LON:CURY) Rockwood Strategic (LON:RKW) Kenmare Resources (LON:KMR) Central Asia Metals (LON:CAML
We still have a few places available for the next Yellowstone Private Investor Evening on 16 September. This is a chance to meet management teams and fellow private investors face to face in a relaxed environment. Listen to company presentations and then take the opportunity to ask your questions over drinks and canapes. The following will be presenting:
Currys: Dan Homan, Director of Investor Relations
Rockwood Strategic: Richard Staveley, lead fund manager
Kenmare Resources: Tom Hickey Managing Director
Central Asia Metals: Gavin Ferrar, CEO
Doors open at 5.15pm and the event starts at 5.30pm in EC1
Register: Join Webinars & Events | Yellowstone Advisory
#CURY #RKW #KMR #CAML
Chapel Down (LON:CDGP) have started to harvest. As a shareholder hoping for a vintage year ! The gold shareholder discount of 33% is a useful return- if you like the wines.
Have you tried Gusbourne? I think they're even better. The wine that is, not the shares.
My favourite is 50% Tattinger owned Domaine Evremond. But at a higher price point. Just bought the 2nd release.
Oooh not heard of them before - I'll have to give them a try. Thank you!
Not opened the second release yet. Waiting for my daughters both to be here so we can taste 1 & 2 together.
I did some digging into the growing conditions / harvest last week as I keep a watch on Chapel Down (LON:CDGP)
Looks like while volumes might be in the average range, given the late May frosts did some damage, the quality this year is going to be really high. Given the nice hot summer.
This is perfect for the growing English Sparkling Wine category.... whilst demand volumes are steadily growing, my fear is that there's somewhat of a glut of production capacity at the moment. So a big volume harvest for the industry is bad, given the surplus glut of wine it results in.
But OK volumes, and better quality? Much better. As it helps to create a strong product and reputation; probably this year's sparkling wines will be higher in quality than most champagnes (they had a poor summer - too hot). AND easier to sell for the price premium that ESW needs, given its higher cost base (eg UK labour, smaller scale operators, higher supply chain costs vs champagne at the moment).
However, all the harvest coming out this year will only be on shelves as ESW in 2-3 years time. So its quite a patient waiting game....
Meanwhile, the bumper harvest of 2023 + 2024 in terms of volumes are going to hit the shelves this year, next year... possibly pressuring per-bottle pricing and margins.
French are expecting excellent Champagne this year, with higher levels of alcohol than usual due to hot summer, apparently had to relax some rules relating to alcohol content !
Volumes are reported as likely to belower at Nyetimber.But as you say quality should be up.
Plus500 (LON:PLUS) . I have been trying to chase up an unpaid dividend from Plus 500 due on 9 July. My broker tells me that none of their clients have received this dividend and they are in touch with the Registrar with, as yet, no payment. I have also contacted the Registrar and received no response.
Does anyone have any information or have/have not received their divi?
My dividend was paid okay and I use FreeTrade currently.
Plus500 (LON:PLUS) My dividends were paid by AJ Bell and IG on 9 July
Everplay (LON:EVPL)
RNS this morning you've missed.
1m units of Wardogs sold on day one.
Published by Team17.
(I hold)
A.
https://uk.finance.yahoo.com/n...
Thanks, I wasn't sure how material this news was when I looked at the list this morning, but it seems to have moved the share price by 10%, so I've added it!
Well there's a slice of luck for once, bought yesterday
Morning gents. Any chance of some commentary on SThree (LON:STEM) announcement this morning. Thanks
Even though the proposed offer for SThree (LON:STEM) is tentative and at an early stage I find it very surprising that the share price has hardly moved. Does this indicate that the market thinks it won’t happen or the offer is likely to be at a derisory premium. I hope not as it would make a nice change for one of my smaller holdings to be acquired at a significant premium (preferably like that shareholders in Eleco (LON:ELCO) achieved!!
Isn't this morning's announcement just Circle8 (NMQ:CIRC) trying to reassure its own investors that their current holding won't be diluted as a result of the proposed purchase for SThree (LON:STEM) ? Interestingly, Circle8's share price is down 85% in the last 12 months. And as far as I know, no purchase price for SThree (LON:STEM) has been mentioned yet.
I've added this in as it wasn't published at 7am, will take a short look now.
Morning... Did Boohoo (LON:DEBS) get updated yesterday in the end?
Saw that there was quite a bit of ember commentary on it...
Maybe you could cover Pan African Resources (LON:PAF) trading update from yesterday, that was missed? As it is a quiet day.
Mark, thanks for covering Pan African Resources (LON:PAF) today, just seen it, as I have been out all day.
I'd appreciate any comments from the team or subscribers on LTIT's tender offer this morning. We hold, and full disclosure, every time Michael Lindsell spent a lot we spent a bit on their shares. He's down a lot and so are we, but as all directors including Nick Train and Michael Lindsell are not selling the 20% of shares shareholders can tender at 5% below nett asset value on calculation day, we'll stay onboard too.
We don't tend to look at listed trusts on the DSMR. Mainly because the analysis involves either just our view of the manager, or we would have to analyse each public holding. However, in this case there is a specific corporate action:
This seems a very sensible action if the manager believes that a drip-drip of sellers keep hitting the price and widening the discount beyond what is reasonable. In this case, they report a 696p NAV at 8th September versus a 544p close last night, a 22% discount.
If this tender is successful and allows the drip-drip sellers to exit at a price they are happy with then it may well reduce the discount. However, a listed trust should trade at a disount to NAV IMO to reflect the extra charges of the structure versus just owning the assets directly. The 5% seems pretty reasonable, and is backed by management not tendering.
My concern if I held would be that there is nothing stopping the discount then widening again afterwards, particularly if the future results aren't strong. Whereas trusts that have an ongoing buyback policy tend to provide the liquidity when sellers need it.
The other concern is that if you really believed in the long-term performance potential, you'd rather they retained and invested that cash. After all, if the performance is very strong going forward the disocunt will narrow naturally.
Overall, this makes the decion to tender or not quite a conundrum, and one I don't have a definitive view on.
The performance of Lindsell Train Investment Trust (LON:LTI) has been poor over 1, 3 and 5 years. Hence the discount. Moves like this rarely reduce the discount post the tender but I guess at least LTIT holders can claw back some of the losses- shares are down 21.6% this year. So you can tender at 5% below NAV. A manager who performed well for many years but the last 5 has not been great that is an under-statement. I do not hold but if I did would tender- you will probably be able to buy back at a lower price post-tender.
JASVFS
You’ve now had 2 very good replies on the Lindsell Train Investment Trust (LON:LTI) tender offer and I agree with everything in Charles’s post abou how to handle it.
I don’t hold and wouldn’t want to. Performance for ages now has been diabolical and I don’t like their top10 holdings including 30% in Lindsell itself and a Lindsell Fund.
If wondering whether to continue holding, you could take up the tender offer in full and IFIF there is a chance to tender for more than the 20% (I haven’t checked) then apply for far more if you are looking to escape, and hope you get a larger than 20% allocation.
If 20% is the limit then if deciding you want to continue holding it looks best to do do as Charles suggests?
Frustrated to see that the NAPS has taken off since July and stands at +25% whilst my daily efforts to outsmart the market stand at +10% only this year after two good years.
I know the feeling Doctor Dave, although I am not doing quite as well as you! Haha... My VM screen also started well - +7% since 1 July. I am becoming convinced of the Stocko black magic!
7.5% overall here ... a week ago it was 10.3% - I'm taking it as a buying opportunity and reinvesting my accumulated dividends.
Perhaps some would see this thread as a little low brow for Stocko but no doubt that’s the attraction for me along with a little human interest. It also prompted me to crunch the numbers and I was pleasantly surprised to find, accepting the recent downturn, that from July to July my ISA was +27%. I am a compulsive share shopper and would be curious know how your holdings compare to my fluctuating 90+
Well done Mr Kurtz!
+27% over one year also. My focus is VM but with a large side order of Recovery. Mean stock rank 83.