Daily Stock Market Report (Fri 12th December 2025) - CARD, CPI, SPA, TEK, TRB, FTC

Good morning! I'm hoping to get a chance to update our spreadsheet later today.
We have what looks like two profit warnings, an upgrade and a takeover in today's news - slightly more dramatic than your typical Friday!
Today's report is complete. Have a wonderful weekend - and thanks for all the comments and the thumbs up!
Companies Reporting
| Name (Mkt Cap) | |||
|---|---|---|---|
GSK (LON:GSK) (£74bn | SR91) | European Medicines Agency's Committee for Medicinal Products for Human Use has recommended expanding the indication of GKS’s RSV vaccine to all adults aged 18 years and older. The European Commission's final decision is expected in February 2026. | ||
Aberdeen (LON:ABDN) (£3.6bn | SR90) | Aberdeen has reached agreement with MFS to acquire the management of closed end fund (CEF) assets totalling £1.5bn. | ||
Harbour Energy (LON:HBR) (£2.8bn | SR67) | Agreement to acquire substantially all the subsidiaries of Waldorf Energy Partners Ltd and Waldorf Production Ltd, currently in administration, for $170 million. Adds oil-weighted production of 20 kboepd and 2P reserves of 35 mmboe. | ||
Capita (LON:CPI) (£453m | SR79) | Trading Statement & Statement re closed book Life & Pensions | Update for 11 months to 30th November: adjusted revenue performance “broadly consistent with” H1. Full-year revenue guidance reduced (compared to guidance at the half-year results) at Capita Public Service, Contact Centre and Pension Solutions. | BLACK? AMBER (Graham) Revenue guidance is reduced in three divisions but this is offset by a strong pipeline figure and news that the company has managed to strike a deal to get out of legacy Life and Pensions contracts. That exit could cost shareholders dilution of 5% if it is settled in shares, and both Capita and Royal can choose to settle it in shares if they wish. Short-term momentum is very strong and Capita is trading on a cheap multiple (7x): if the revenue guidance hadn't been rather weak-sounding, I might have been obliged to upgrade our stance on this share today. |
ITM Power (LON:ITM) (£385m | SR40) | Basic Design Engineering Package contract for a project in Australia, and Front-End Engineering Design contract for a project in Canada. Combined capacity 70MW. Value not given. | ||
Card Factory (LON:CARD) (£336m | SR79) | SP -23% UK store sales performance is lower than expectations. Adj. PBT for the year is now expected at £55-60m. Previously guided for mid-to-high single digit % growth in adjusted PBT from FY25’s result £66m. | BLACK (AMBER ↓) (Graham) Downgrading to neutral seems fair given the severity of this profit warning. At least the company is still profitable, and management remain confident enough to pay a progressive full-year dividend - either that, or they are justifying the continuation of a buyback to fund employee bonuses. Overall, I do think these shares offer good scope for recovery and upside potential if the consumer recovers soon, but it's not a bet I'd personally be interested in making. Card shops are a danger zone for investors when it comes to the retail sector, which is already a fairly treacherous sector. | |
Filtronic (LON:FTC) (£312m | SR63) | “Enters the second half with a robust order book, strong customer engagement and growing pipeline, providing the Board with confidence in a strong H2 and a full-year performance in line with market expectations.” | AMBER = (Graham) [no section below] This is a designer and manufacturer of communication products for the space, defence and telecoms sectors. We've been cautious on it, seeing as it has been an expensive "High Flyer" with falling momentum - although that's not true currently, with the MomentumRank apparently on the mend after a period of share price consolidation. Today's H1 update sees broker Cavendish leaving forecasts unchanged, including adjusted EPS of 3.2p in the current year (FY May 2026) and then 3.9p in FY May 2027. It's great to read that the customer base is diversifying away from SpaceX, with "a broader pipeline of opportunities", and net cash is fine at c. £8.5m (depending on how it is calculated). Following today's "in line" update, I'll leave our neutral stance unchanged. | |
Tribal (LON:TRB) (£134m | SR88) | SP +8% “Tribal expects to deliver FY25 revenue comfortably in line with, and adjusted EBITDA ahead of, current market expectations.” Movement from net debt (£3m) to net cash (£5m), allowing a special dividend of 1.5p to be paid in January. | GREEN ↑ (Graham) [no section below] Roland was AMBER/GREEN on this educational software and services provider in August when the company raised expectations. It raises expectations yet again today and the market cap is now, as I type this, some £144m: 40%+ higher than it was when Roland looked at it in August. The net debt to net cash movement for the year is £8m which is consistent with a net income forecast of over £9m. With EPS forecasts in a rising uptrend, I'm content to nudge this up to fully GREEN seeing as the valuation here doesn't yet strike me as excessive. Tribal's customers are likely to be "sticky" (universities, further education colleges and schools), and I calculate that the Enterprise Value to Sales multiple for the current year is only 1.5x (quite low if this is valued as successful software business). | |
Audioboom (LON:BOOM) (£110m | SR50) | November 2025: “Revenue of US$9.1 million, gearing strongly to adjusted EBITDA profit, representing the highest monthly results for both key financial metrics.” | ||
1Spatial (LON:SPA) (£52m | SR27) | Possible Offer at 73 pence per share, 57% premium. Potential buyer has "completed commercial due diligence, has a clear understanding of the 1Spatial business and requires only limited confirmatory diligence to proceed to an announcement of a firm intention to make an offer". Board of 1Spatial "intends to unanimously recommend the Possible Offer". | PINK (Graham) | |
Tekcapital (LON:TEK) (£23m | SR90) | Innovative Eyewear has launched two new, light-adaptive sport smartglasses in its cutting-edge Reebok Powered by Lucyd collection. These new variants of the Octane and Nitrous frames are designed for use in the gym and for outdoor sport. | AMBER =(Graham) [no section below] This is a non-regulatory press release and it can be safely ignored if investors wish to ignore it. But Tekcapital already published a similar press release on December 1st, and it's back again with another one today - why? Do investors really need to know every time its subsidiary Innovative Eyewear launches a new product? The frequency of these releases is overly promotional for my liking. According to the Q3 update, Innovative Eyewear made a loss of $5.7m for the nine months ending September 2025. |
Card Factory (LON:CARD)
Down 23% to 73.8p (£257m) - Trading Statement - Graham - BLACK (AMBER ↓)
A short but highly consequential trading update from CARD factory:
Over recent months, the pressures facing the UK consumer have been well publicised. It is an inescapable fact that these pressures have impacted consumer confidence and shopping behaviour, contributing to soft high street footfall. Those conditions have persisted as we moved into our most important trading period, leading to a UK store sales performance which is lower than our previous expectations.
More positively, the company’s Irish and American businesses continue to trade in line, and the integration of Funky Pigeon is “on track”.
New guidance: if current trading trends persist, FY January 2026 is expected to see an adjusted PBT of £55-60m.
Estimates: A note from Edison Research in October suggested that FY26 adjusted PBT would be £70.7m, a 7% increase on the £66m result for FY25.
At the midpoint, new guidance is therefore a 19% cut to adjusted PBT.
Graham’s view
We’ve been GREEN on this one, which obviously doesn’t look too smart in the light of this profit warning:
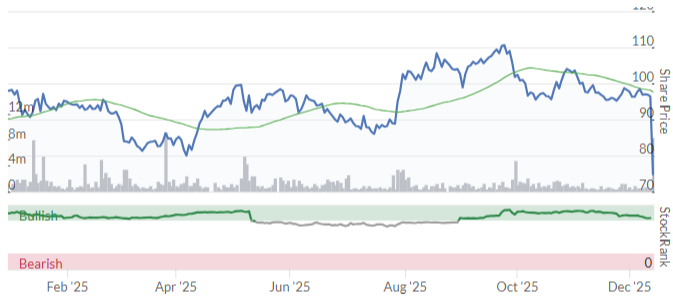
I’m inclined to downgrade our stance all the way to neutral today.
In my previous comments (e.g. September), I’ve made it clear that I view card shops as a particularly dangerous niche in the retail space, as they are essentially selling commodities. But I was happy to stay GREEN on the stock with that disclaimer attached, given the cheap multiple attached to earnings expectations at the time.
Back in 2012, I witnessed CARD’s rival, Clinton Cards, going into administration and shareholders losing everything. That episode stuck with me, and I’ve never wanted to get involved in a card shop since then. Clinton Cards, incidentally, has suffered financial distress on multiple occasions since then, under different owners.
It’s an unfortunate reality that most retailers seem to get into trouble sooner or later. And card shops seem to be more accident-prone than most.
The good news is that CARD is still profitable: with over 1,000 stores, it does enjoy scale benefits and should not suffer negative operating leverage as quickly as a smaller chain would.
And management, in a sign of confidence, have announced today that they still intend to announce a progressive full-year dividend. So they don’t seem to be panicking.
They also announce that their ongoing share buyback will continue, but I wouldn’t read too much into this. The buyback announcement in October noted that “the shares acquired are intended to be used to satisfy awards under the Company's employee share plans.” So the point of this buyback is to fund bonuses, not to return cash to shareholders.
Balance sheet: as I noted in September at the half-year results, CARD does have a leveraged balance sheet with £78.9m of net debt excluding leases, plus another £121m of lease liabilities.
The non-lease leverage multiple at the time was 0.6x - a modest figure. But I certainly wouldn’t ignore the lease liabilities.
Conclusion: if after-tax net income is £43m this year, that puts the shares on a current-year PER of 6x at the current market cap. However, if the weak consumer trends of recent months continue throughout FY January 2027, then we will certainly see a decline in profitability next year, and the forward multiple is therefore materially higher than 6x.
That being the case, I think a neutral stance makes sense here at the current level: if the true PER is, for example, 8-10x (based on current trends continuing for most of FY27), then it wouldn’t surprise me if the shares were fairly valued at this level. There’s scope for an upside surprise if the consumer makes a swift recovery, but you’re smarter than me if you can predict when that might happen!
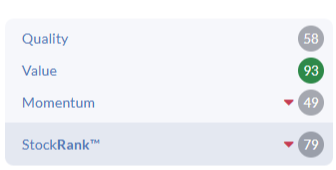
The StockRanks did well, noticing the declining share price momentum and dropping the overall score in advance of this profit warning:
Capita (LON:CPI)
Up 1.5% to 402.5p (£460m) - Trading Statement and Statement re closed book Life & Pensions - Graham - AMBER =
The market has shrugged off what appears to be a downgrade in revenue guidance from support services provider Capita.
Key points:
Adjusted revenue in the 11 months to November “broadly consistent with the first half performance”.
Public Service (largest division, majority of total revenues) +4% with H2 revenue growth moderating slightly
Contact Centre (2nd largest division) down 18.3%, “reflecting the impact of previously announced contract losses and volume reductions”.
Outlook for the full year:
From a full year perspective, we now expect growth in Capita Public Service to be slightly below mid single digit, a high teen digit reduction in Contact Centre and low single digit growth in our Pension Solutions business. Our guidance on margin improvement, free cash flow (including the £14m previously announced Information Commissioner’s Office (ICO) settlement) and debt, together with our medium-term targets, remain unchanged.
This divisional revenue guidance is below what the company said at the half-year results. Here is what they said in August:
Capita Public Service guidance upgraded to mid single digit revenue growth, Contact Centre now expected to deliver a mid teen revenue reduction.
In Pension Solutions we expect a mid single digit revenue increase…
So Public Service is now “slightly below” August guidance, Contact Centre is seeing a larger decline than anticipated, and Pension Solutions has grown less than anticipated.
But the market doesn’t seem to mind, as the more forward-looking business pipeline has grown considerably:
In the second half of 2025, we’ve seen a significant increase in the Group’s unweighted contract pipeline, with total contract opportunities across all divisions now valued at £16.5bn, up 41% from the half year. This represents the highest level the Group’s unweighted pipeline has been for several years. Of this, £3.5bn relates to opportunities which have a strong technology component.
And there's some nice jargon re: AI which reads like it could have been composed by AI:
In recent months, we also launched our AI Catalyst Stack for customers which leverages our operational expertise and hyperscaler partnerships to embed AI in mission-critical services, driving faster transformation, reducing costs, and improving outcomes for citizens and customers.
CEO comment: “While some challenges remain, we are making good progress and continue to work hard to build a Better Capita.”
Life and Pensions contracts: part of the “Regulated Services” division, the “Life and Pensions” business is shutting down. The last contracts with Royal London are being exited at an initial cost of £22.5m (which might be settled in shares), plus another £30m to be paid in three equal instalments.
This is a very expensive deal that could result in 5% dilution to shareholders, but it sounds like it’s necessary. Capita CEO again:
“This marks the completion of a key element of our ‘manage for value’ strategy, eliminating a significant future annual cash outflow from the Group and enabling us to focus fully on areas where we can deliver sustainable value.”
Graham’s view
This is not a sleep-soundly type of stock, but it is cheap:
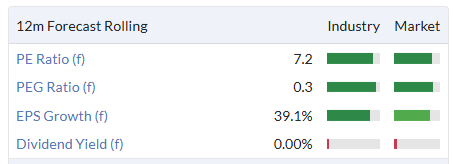
Given the public sector focus, shouldn’t it be a winner in an era of increased government spending? That new pipeline figure does sound very promising.
Although the balance sheet gets me less enthused.
Net debt at the half-year results, excluding leases, was £87m.
Operating profit is forecast to be higher than that, so it should be a very manageable debt pile.
However, the overall structure has a few issues. There are over £300m of lease liabilities for a start. More importantly, tangible net assets are minus £280m.
This is a case where customers are funding the company with upfront payments, so it’s probably nothing to worry about, but I’m going to stand by my view that the balance sheet is not supporting any bullish arguments here.
This is all about earnings, and profit at a company like Capita is the difference between two large numbers. For now at least, it is getting the equation right:
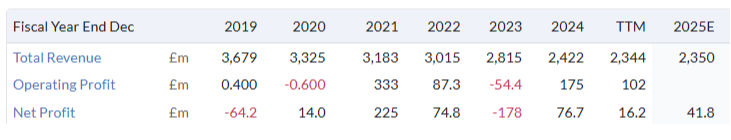
Putting it all together: if the recent revenue performance had been stronger I might have been compelled to upgrade our stance, but I think that I can justifiably stay neutral on Capital today.
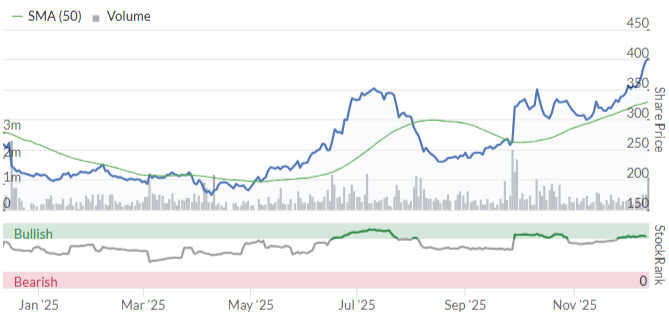
Momentum is 89 and rising, and technically it is breaking out to new highs - so it’s looking great in the short-term. Longer-term, I'm not convinced.
1Spatial (LON:SPA)
Up 45% to 67.5p (£75m) - Possible Offer for 1 Spatial plc - Graham - PINK
Is it just me, or has takeover news gone a little quiet lately?
That changes today with news of a “possible” offer:
The Possible Offer at 73 pence per 1Spatial share values the entire issued and to be issued ordinary share capital of 1Spatial at approximately £87.1 million
1Spatial is “a global leader in providing software, solutions and business applications for managing location and geospatial data.”
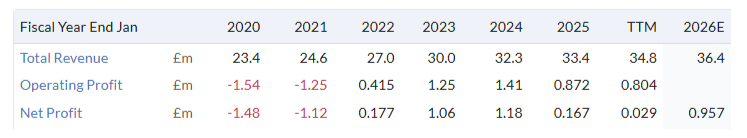
We haven’t covered it too much, because it has been barely profitable and difficult to assess:
The largest shareholders here seem happy with the prospect of getting out at 73p. Threadneedle and Canaccord Genuity have both pledged to support the offer, if it materialises.
And we have a brief trading update:
The Board re-iterates the outlook statement made in the Company's interim results, noting that the final out-turn for the year is dependent on the timing of delivery of key contracts.
The possible buyer: a very similar company called VertiGIS that provides “Enterprise Geospatial Mapping Software” and is present in nine countries including the US, Canada and Australia.
Rationale for the Board's recommendation to accept the possible offer: besides providing “certain and fair value” to existing shareholders, the Board says that the takeover will "accelerate" their strategy under private ownership, and “create a compelling strategic combination”.
Graham’s view: this appears to make sense for the company, for its current shareholders and for the buyer. I don’t know if the price paid is fair but the suggested valuation is over 2x revenues for a business that has been listed for a long time and never generated much profit. It seems reasonable now to let it evolve under new owners who are willing to pay a strong premium (it is hard to turn down a takeover offer at a 50-60% premium).
So let’s hope that the offer materialises and goes through as planned. All that’s left now is “limited confirmatory diligence.”
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

75 comments
I have held Tekcapital (LON:TEK) shares for a number of years, based on a buy recommendation by Simon Thompson in the Investors Chronicle (who still has it as a buy) . It's a portfolio company that has invested in several companies that have threatened to disrupt the market that they operate in. But they have had some significant failures and disappointments over the last 3-4 years, which has resulted in a share price that has been a roller coaster ride and significantly discounted against NAV. However, several of the investee's have begun to move towards profitability, which can often be followed by share price re-ratings and hopefully a decent return for shareholders in TEK. It's interesting to see that it now has a StockRank of 90 and falls into the category of Super Stock. The question I ask myself now is, is now a good time to buy more TEK or perhaps buy shares in the likes of Guident on the NASDAQ at the forthcoming IPO. I would be very interested in peoples thought here, as there does not appear to have been any real discussion on Stockopedia that I can find.
For a contrarian view of Card Factory (LON:CARD) and the impact of postage
Put together, postage rate increases - which have been in place for some time but so far not majorly impacted the number of cards given out - are a big but not critical factor.
The real villain is consumer spending and costs to operate in in the High Street. Every business I speak to there is hurting: NI and wages are up, footfall and turnover down. That's why many competitors are not just suffering but dying.
However, Card Factory has this year (finally) got a foothold in online via Funky Pigeon where its omni-channel offer should give Moonpig a bit more of a challenge, it seems to have got some international businesses away providing some diversification and is still profitable whilst it is hurting physical retail competitors are shuttering. (The exception is Cards Direct (88 stores) who have the same offer as Card Factory but no online and much less scale being 1/12th of the UK stores. )
Will the consumer ever bounce back? Will we keep giving physical cards? Will the supermarkets or online crowd the specialist 'card and small gifts bought instore' niche that Card Factory (LON:CARD) . All of these can be bad for Card Factory (LON:CARD) but may also reverse.
In the meantime, debt is now under control, leases are short and a retail bloodbath means lower rents and ultimately we must see Government action on rates etc else we have a lot of low wage jobs disappearing. As we wait, a big dividend is coming that may be cut but would still be decent.
I will wait and hope the price goes down some more but expect to be a buyer again before Christmas.
Another excellent commentary today, especially:
There’s scope for an upside surprise if the consumer makes a swift recovery, but you’re smarter than me if you can predict when that might happen!
We are definitely not smarter than you Graham!
Trufin (LON:TRU) breaking out to an ATH after good volume yesterday. Yesterdays unscheduled TU gave us a 'materially ahead' and suggestions of returning some of their healthy cash balance to shareholders. There is usually a TU in early January. More of the same maybe?
I dont disagree (Filtronic (LON:FTC) - this is a great company, doing well. But as it stands there is an opportunity cost at sitting on 140p shares producing 3.5p EPS for the next two years. Having exited I will keep watch with interest and there may well be a good time to come back in.
OK, Santa slump
I am a long term holder of Card Factory (LON:CARD) and was surprised by today's announcement. I think there may be an element of market/postage impact but the card market is very resilient. I supect the real reason is the sudden insurgence of Cards Direct who now have 88 stores and are a carbon copy of CF and have no doubt captured a decent chunk of market share. I admit not to have seen these guys coming. The mgt challenge is to stave off this competition in the core business and drive growth through the USA, card partnerships (like the one with Aldi) and to take a higher % of gifting market. Whether CD's business model is sustainable who knows but they have rapidly expanded to 88 stores and give CF a wake up call.
They sell crap cards from the high street what do you expect l!
You know something's wrong when the cost of postage exceeds the cost of a card. To rub salt in the wound, postage for a card to us in Germany costs GBP3.40. What a rip-off. No wonder that so many people are sending ecards this year and donating to charity what they would have paid in postage. I thought Card Factory (LON:CARD) would be a good recovery play, and bought a few a while ago. But I'm now under water. Time to bail I fear.
Card Factory (LON:CARD) Oh dear. This seems to be a company that people either did well with on a recovery, or not so well with otherwise. Personally, I find it hard to get excited about a company that sells greeting cards. I prefer to get a pack of charity cards or buy one out of Tesco. Our local stationers sells cards, as does the Nickel'n'Dime store, and more besides.
But then again, I'm a total curmudgeon, so make of that what you will. As we say in Scotland, "Every penny a prisoner."
'There’s scope for an upside surprise if the consumer makes a swift recovery, but you’re smarter than me if you can predict when that might happen!'
Where is the upside going to come from? And why would the consumer make a swift recovery?
will Card Factory experience an increase in business rates?
what about increasing the minimum salaries again next year?
Hi Mark, I must admit I can’t see the investment reason for card factory. Walked past a shop today whilst buying a birthday present for my son and didn’t feel the need to rush in card factory to buy a card from their shop. I may be being biased because I try to avoid retail.
Thank you for burying, sorry covering Card Factory Graham, I should have waited for your analysis. We have a modest holding which went from profit to loss at 8.00am and I repeated my usual buy in haste, repent at leisure, with a few more at 73p. I'm riding Funky Pigeon America and the Irish to the rescue. Having been lucky with Clinton Cards should have restrained me!
You must have been very lucky indeed with Clinton, JASVFS! All the best. G
Defence stocks. I see folks discussing MS International (LON:MSI) and Cohort (LON:CHRT) and their disappointing performance.
I'd like to chip in by tuppence as a holder of BAE Systems (LON:BA.) (7.7% portfolio holding). It's a share I lucked into due to its high SR (StockRank) at the time, mere weeks before Russia kicked off. As the saying goes, you still get to keep your lucky money.
BA had a pretty good track record, so I figured I would just buy-and-hold as a quality share. I did top-slice back in August as my portfolio was getting a little top-heavy for my liking.
In retrospect I should probably have sold all of them. I've introduced a loose trading rule that if the Value score falls below 20, I should probably sell. My thinking is that I can hold quality shares indefinitely, but if the value score weakens, it probably time to get and and recycle into a better opportunity. It can be hard to do if it's been a great performer.
One thing that put me off is that some time ago, a Defence ETF was offered on the market. That made me feel a little off, feeling that perhaps it was getting to be a hot sector ("When the ducks quack, feed them", as the saying goes).
Shares will undoubtedly fall if Ukraine signs some kind of peace agreement. I don't think the story stops there, though. Europe recognises that it needs to up its defence spending (exactly how enthusiastically it embraces that is a different matter).Getting back to defence companies generally ... which shares are best to own? You have a choice between the first-tier leaders, which are likely to be expensive, and lower down the list, which are likely to be cheaper.
Anything can happen of course, but I read a (classic) trading book that said go with momentum, the leaders. If you don't like trading, then I'll offer some advice from Peter Lynch: sometimes the next McDonalds (maybe some other company, I'm not sure) is McDonalds.
Leaders seem to have more clout.
Having said that, CHRT fits my quality screen, so it's definitely something I'd consider buying were it not for the fact that I've got enough defence shares.
MSI passes my quality screen too.
Make of that what you will.
Any ideas why Wynnstay (LON:WYN) has dropped so much today can’t see any news + recent results were positive?
My impression is that the market is a little bonkers at the moment. Look at Ingenta (LON:ING) - I hold. In the last 5 days it's been over 90p and down to 75p, all on no news. I guess the market makers will blame the low free float.
Anyone heard any rumours about MS International? Share price seems in free fall this week.
MSI x I honestly think it’s just a run on defence stocks in general. Look at Cohort’s 30% fall on a slight easing of expectations
My guess is that the recent trading update from MS International (LON:MSI) is starting to sink in with investors. In particular the decision by NAVSEA (United States Navy) that it "has decided, for the time being, ....to award contracts annually.." whereas "Earlier communications with shareholders indicated that "MSI" was hoping for a longer term contract with NAVSEA"
With the current Xenophic, anti-European rhetoric out of the US administration, that decision could be material for MS International (LON:MSI) .
The valuation was already getting quite stretched and perhaps this is an indicator of trouble ahead, or perhaps not, but I imagine some investors would rather not wait to find out.
Yet Huntington Ingalls Industries (NYQ:HII) (no doubt with the approval of the Pentagon) has just awarded major contracts under the AUKUS programme to Babcock International (LON:BAB).
HII Deepens Partnership with Babcock International Group in Support of Virginia-Class Submarine Construction - HII
Babcock signs contract to support the next generation of nuclear submarines - Babcock International Group
In addition, BAE has secured several major contracts with the Pentagon including a $1.7 Billion contract to supply APKWS Laser‑Guidance Kits which was signed this month. This is a five‑year indefinite delivery/indefinite quantity (IDIQ) contract with the U.S. Navy.
BAE Systems awarded $1.7 billion U.S. Navy contract for continued production of APKWS® laser-guidance kits
It is interesting to note the BAE contract will be delivered from their plants in Hudson, New Hampshire and Austin, Texas. However, the Babcock AUKUS submarine contract will be delivered from Rosyth Dockyard in Fife, Scotland. The BAE contract is consistent with the US administration's desire to onshore manufacturing. The Babcock contract award is a recognition that the US has fallen behind in warship design and industrial capacity to actually build warships. To give one small example (and there are many): The U.S. Navy’s Littoral Combat Ship program is widely considered a failure because the ships were under‑armed, plagued by mechanical breakdowns, and failed to deliver on their promised modular mission. Scotland will build as many as 10 warships (type 26 and 31 frigates) over the next 3 years compared to the 30 to 35 warships planned in US shipyards. Given the respective sizes of the populations, and the dire state of Scottish ship building for so many years, that is truly astonishing.
In my view, this administration will do everything they can to lure the UK away from Europe into their sphere of influence so I would not conflate this administration's view of the UK with Europe (despite President Trump's stated deep love for Mr Khan).
I think there are specific issues with both Cohort (LON:CHRT) and MS International (LON:MSI) and I also think the shares simply charged away from reality and have now corrected (as has the whole sector .... take a look at the Rheinmetall AG (ETR:RHM) and BAE Systems (LON:BA.) and Kongsberg Gruppen ASA (STO:KOGo) charts). It does not help that on 16 July 2025, three Cohort plc directors — Chairman Nick Prest, CEO Andrew Thomis, and Finance Director Simon Walther — along with their spouses (Persons Closely Associated, PCAs), sold a combined total of over 560,000 shares at a price of 1,743.24p per share. I thought that was a big fluttering red flag and sold 2/3rds of my position ... right at the top it turned out. I also hold MS International (LON:MSI), Babcock International (LON:BAB) and BAE Systems (LON:BA.).
Fidelity, JP Morgan and Goldman Sachs have all issued a bullish view on European defence stocks. The question is whether Cohort and Ms International are a good way to play it and I am not sure.
Thankyou guys. This is why I love this page, you always get sensible responses from thoughtful people. I am very dark on the subject of defence I am afraid. I believe war is coming across Europe. War destroys wealth and there are few places you can be to change that. That said defence has got to be one. I console myself that if I am wrong (and I hope I am) the European states still have years of under investment in this area to catch up on.
As an aside, as i was walking my dog this morning I got talking to someone who has just been made redundant from their product manager job in a drug company. Third time in recent years. This is in Cambridge where AstraZeneca have announced they are reducing their investment. It appears the reasoning being Trump is insisting that the FDA only pass drugs where the Company has a US presence. So investment is going to the US. I have not been aware of this and I think it important given the size of the US market relative and the fact that other countries do look to the FDA when passing drugs. I wonder if Hvivo become more valuable in this new world. (I am not a holder but as from today I am watching them).
Thanks Camtab,
I have asked my pharmacy journalist pal what she thinks of this FDA and Trump story.
More later
Threepeat did you get a response from your friend?
Sorry no reply
Could you look at TMIP today please? There is a lot going on there!
TMIP
forgive my ignorance Ian , what is TMIP?
It's Taylor Maritime Limited.
I'd be interested to hear thoughts on the Capita (LON:CPI) "closed book life and pensions resolution" and the impact on the business going forward. This seems to be a positive development and the market agrees despite the "broadly in line" trading statement. Shares have had very good momentum recently. Richard Staveley holds in Rockwood Strategic (LON:RKW) and sees very decent upside.
I’d also be interested to hear any thoughts on Capita (LON:CPI) . Market reaction to the life and pensions arrangement is positive so far and that’s on top of very strong gains ahead of this announcement. Guess a lot of insiders knew it was coming as the negotiations took place and could profit accordingly. There’s no way of policing it.
Is the "rally" underway?!
Blink and you'll have missed it.
Yes 40 points retreat now
Maybe for Xtrackers S&P 500 Inverse Daily Swap UCITS ETF 1C (LON:XSPS) it is just starting....
I wrote a few days ago of my crazy hypothesis on why unlikely for a Santa rally, because too much Retail Money, and not from the moneyed classes but the GenZ and lower income classes who have greater access to trading apps, fractional trading, and derivatives that are more akin to gambling. In December and Jan, these are the groups that are most squeezed in discretionary income. Buying shares comes from that pot of money, as its fun/gambling. We might even see some people sell Nvidia shares to fund buying Xmas presents, Xmas grocery shop.
(I hold in the Boon Fund)
Card Factory (LON:CARD) although the company cites pressure on consumer as the reason for poor footfall I cant help feeling that in their 'posted card' market the business must be hit hard by postage charges that are higher than the cost of the product for a service that is awful at best.
Postage charges that are higher than the cost of the product for a service that is awful at best.
A bit harsh, no? Out here in rural Yorkshire the delivery service is not only “first class”, but performs a vital community function for many isolated folk. Not to mention that the post office itself (yes, I know it’s a different business) which acts as a gateway to the Royal Mail, maintains access for us hayseeds to vital services such as banking. It’s a huge relief to us when online shopping is delivered through the Royal Mail. At least they can find our house!
I am aware that the provincial service is a lot better than suburban/urban, however as the majority live in the latter this is what will affect the most. I am very much suburban, i get post once a week delivered by a different postie every time! and this week's delivery had letters for 2 of my near neighbours and one for the correct number but in an adjoining street. My daughter recently bought her first flat in inner London and over half of her 'welcome to your new home' cards never arrived. So yes there was a thinly disguised rant in my post but still relevant I feel.
The postal service in small town Gloucestershire is quite often diabolical, so I agree with your rant.
A first class stamp at £1.70 feels a 'little' high when not so many years ago it was 25p.
And a tracked 48h package takes 15 days and counting...
And here in Gibralter its 90p to send back to the uk!!
Unlike Evri who invariably deliver to wrong address
Unlike Evri who invariably deliver to wrong address
Unquestionably the worst. Has stopped us shopping at our beloved Uniqlo since Evri took over their deliveries.
It sounds like you live in particular spot that happens to be well covered - I think you're in the minority though and I find Royal Mail to be very unreliable and much worse than even a few years ago (depsite much higher stamp costs)
I live near a small rural town. There used to be 6 banks. Now they're all closed. So the post office is quite important to my family.
I agree about delivery. I feel I'm taking a right punt if something is going to be delivered by a courier. Evri is quite common, with a shocking reputation. Touch wood, though, it's been OK.
Back when I used to work in my old firm we had an old laptop. IT was in Manchester, and I worked in Aberdeen. Anyway, this laptop was absolute garbage. I had to send it back to Manchester. On a later occasion, we were shy a couple of laptops, so IT said they'd send one over to us. Sure enough, back came the laptop.
After awhile, Manchester wanted it back again. I took efforts to find the cheapest method of delivery I could. I mean, like, I didn't care if that meant that they dragged the package from the back of the delivery van or fired it from a canon in the direction of Manchester. I ended choosing UPS as just the guys for the job. They also had a lousy reputation, and they were cheap.
Alas, the laptop arrived back at Manchester in one piece.
Interesting that they site lower footfall. I went into Norwich for a spot of Christmas shopping on Wednesday. I can't remember the shops being so quiet in the run up to Christmas. The only one that seemed to be doing any business was Hotel Chocolate., with queues at the till. Car Parks had plenty of spaces as well.
Here in rural Suffolk the postal service is dire, and we effectively only have deliveries every other day at best. Time sensitive weekly mags, eg Money Week, published Thursday, can arive as late as Monday. Norwich we found heaving 8 days ago!
The good people of Norwich have obviously shopped early for Christmas. All done by the time I managed to stir myself.
Well I'm perfectly happy with Royal Mail deliveries only three times a week. I just wish they could be allowed to get rid of the first and second class nonsense and the 6 day delivery obligation which we all know doesn't work. Anything urgent - gets delivered by email or Amazon
I'm in rural Norfolk Grumpy I reckon we get post once a fortnight now to the point its quite a surprise when you come home and find a letter on the doormat.
Well.... November consumer spend data was terrible. Especially the Barclays Consumer Spend Report.
Black Friday seemed to have done well, still in growth YoY. But maybe that pulled forwards loads of December spend.
So maybe Dec is set up for a terrible month.
Norwich is my nearest city also Lord G but personally I don't think its a patch on what it was 25 years ago, there's still good parts but St Stephens Street is really run down, nothing happening with the huge Debenhams store doesn't help either.
I've never seen so many people sleeping in doorways. I go to Cambridge 2-3 times a year also and the difference between it and Norwich is now vast where late 90's I would have had them on par as places to spend a day in.
Don't get me wrong I know there are plenty worse but Norwich does seem run down in parts now.
I sold out of Card Factory (LON:CARD) this morning and am reviewing other investments dependent on UK consumers. This is a very low margin business and if they are struggling on the top line then with business rates and another increase in the minimum salary next year I fear their profit could disappear. Lost about 15% on my original purchase
Card Factory (LON:CARD) I think it is a very well run business that has been shafted through no fault of their own. Apart from the large increase in their running costs, rent and staff, the cost of postage being more than the cost of their product makes no sense and puts people off sending cards. The fact they have released a trading update now, before the peak trading period, makes me think that they are warning shareholders that the usual mid January TU could be a disaster.
Brutal sell off today, one I hold so this has been painful. Looks like a 10% profit forecast reduction which the market has decided deserves a 26% price reduction.
Card Factory (LON:CARD) A box of twenty Christmas cards is only £3 in Card factory. But send them second class, which i did this week, and it costs £17.40 in postage.
That's an odd thing from a psychological point of view. I suspect we'd be more content if the £1 or so total for each Christmas wish to friends and family cost more for the card and less for the postage.. I wonder too, how many hours the Victorian well-wisher would have had to work to send his 20 cards? Have we yet achieved peak "I want something for next to nothing" would you think?
Against the concept that we have no money to spend, I only just managed to buy my christmas tree from "Homebase" for a mere £45, spurning the Waitrose £60 offer, also going like hot mince pies. All that money for a dead tree that will last a fortnight?
Well said. Too often those that complain about these costs are all too happy to spend £5+ daily on a warm milky sludge they will instantly forget.
I noticed last year that the number of cards we received really dropped off in number, even from best friends who always send birthday cards. This year I did consider if it was even worth bothering. I did have some boxes of unused cards from last year. Bought lots of 2nd class stamps, now posted and hopefully soon delivered.
Some of my friends have migrated to electronic cards. But not many so far.
Cost-wise there isn't much in it. I prefer to bus it to town, buy a card in the Card Factory shop and have a pint and a couple of Stryka bombs in Wetherspoons. Yes, it is sad but helps to make life worth living.
They are the invention of the devil!
Last week I bought into Filtronic (LON:FTC) and have been trying to rid myself for quite a while of Card Factory (LON:CARD) (at a profit of course), these two are a perfect fit in my financial IC engine, pistons up, pistons down.
Upbeat statement from Filtronic (LON:FTC) but limited financial info. I hold
Hmm. Cash down off the back of capex investment. The amazing upgrade cycle it’s been on for a year or so seems to be over (for now at least) and the forward rating is extremely high. Tread with caution, IMO.
Agree. Filtronic (LON:FTC) warm words from the board but EPS unchanged at a very challenging PE of 40 for this year and next. Not adding up at this price for me. I'm out.
I'm listening to a podcast at the moment where they stress that the most important next step in the AI story is data centres in space - intense 24hr solar energy (6x more energy collected than on Earth) and no cooling costs. Energy and cooling are some of the largest costs for AI data centres. So the question is - how do they then get low latency data from space to Earth? It makes sense the Musk is involved in this company - he has xAI, he has the rockets and he has options for one of the only companies in the world (FTC) that can move data at the required latency rate between space and Earth. I'm bullish on FTC for this reason - will be a 3-4 year story here I think before it really moves (providing they can stay ahead of any competition)
Have a look at Seraphim Space IT Seraphim Space Investment Trust (LON:SSIT)
Profit warning from Card Factory (LON:CARD) .
What was previous profit forecast do you know?
They were previously guiding and trading roughly around an adjusted PBT consensus of about £65–70m, so this cut to £55–60m is c.15–20% below.
£55-60M is slightly above the expected profit shown on Stockos stock report.
I think that is pre tax
Card Factory (LON:CARD)
Morning, Lord Gnome! As suggested by Charles, the £53m on the StockReport is an after-tax figure, while the £55-60m guidance in the RNS is pre-tax.
Thanks for that. Ever since I have been using Stocko I have assumed that profits were stated before tax and earnings were net of tax. My mistake, could have been a costly one.