Daily Stock Market Report (Fri 13th February 2026) - Portfolio & Watchlist YTD, SDI, SBTX

Good morning folks! We've made it to the end of another week.
Seeing as it's a quiet Friday, I've reviewed both my personal portfolio and my 2026 watchlist, in the hope of bringing you some interesting commentary on the year-to-date performance of one or both of them. However, each of these portfolios has barely moved so far this year!
In my personal portfolio, the really big movers this year are companies in which I have fairly small stakes:
- Rightmove (LON:RMV) (3% of the portfolio): this is down 16% as investors fear that AI will replace the need for a centralised property portal. I don't want to dismiss those concerns out of hand, but I do struggle to imagine a world where property portals become obsolete as people search for properties using new AI tools instead. That said, I admit that I have personally found that ChatGPT is extremely good at valuing properties, and I have no doubt that it could be used for idea generation for property hunters. Rightmove is now back around the price I paid for it many years ago, though it has paid many dividends over this time. It's at 14x earnings which in my view is extremely cheap if the bearish AI thesis is wrong.
- ASA International (LON:ASAI) (2% of the portfolio): this is up 17%, helped by an ahead of expectations update that we covered here. It's a high-risk idea but I'm pretty excited about the potential of this international microfinance lender. The price is certainly a big part of what got me interested, and it's still trading at just 4.4x earnings, according to the StockReport.
- Evoke (LON:EVOK) (1% of the portfolio): this is up 25% but I am still nursing a (fully deserved) large loss on this one, as I've continued to hold it even after it ruined its own balance sheet. Management are now considering the sale of some or all of the group's businesses. I think the recent UK tax changes could be the nail in the coffin for this one, and I'm likely to sell out at some point. We are RED on it - see here.
All told, my portfolio is only up slightly year-to-date. I think my total return is 0.3%, vs. 5% by the FTSE All-Share Index.
As for the 2026 watchlist, it's doing a little better, tracking the FTSE All-Share more closely with a return of 4.8% year-to-date. The biggest movers here are:
- Polar Capital Holdings (LON:POLR) - this fund manager is up 17% helped by a very strong AUM update that included net inflows, very high performance fees, and their first share buyback. Backing quality is working in this case.
- PayPoint (LON:PAY) - up 15% after an "in line" update that reassured investors after its November profit warning. Leaving this financial infrastructure business on my watchlist for another year was a little controversial, but I think it was just too cheap on a P/E multiple of 6x . Even today it is not even trading at 7x forecast earnings.
- Peel Hunt (LON:PEEL) - up 11% after confirming that it is beating expectations for FY March 2026. But as I've previously explained, those expectations never made sense to me in the first place. In any case, it's great to see that the London markets are getting busy again.
- Hostelworld (LON:HSW) (in which I have a long position) - down 9% despite an "in line" update in January. I really like the value on offer here for a successful online travel agent with a well-defined niche, although in theory I guess AI could also disrupt the business model. They are profitable, cash generative, and trading at 9x earnings.
So that's a brief overview of both portfolios year-to-date. As usual, investing is messy, unpredictable and difficult, but always interesting!
There are no other stories where I think I can make a useful comment today, so I'll wrap it up there. Have a great weekend!
Spreadsheet accompanying this report: link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our View (Author) |
|---|---|---|---|
Natwest (LON:NWG) (£52bn | SR70) | Income of £16.4 billion and a Return on Tangible Equity of 19.2% are significantly up on last year, and ahead of guidance, whilst dividends per share increased by 51% compared to 2024. CET1 ratio 14% is up 40 basis points. TNAV per share up 55p to 384p (share price 595p). 2026 outlook: return on tangible equity greater than 17%. | ||
SDI (LON:SDI) (£84m | SR80) | Net consideration £9.3m. PRP “designs and manufactures custom high performance microLEDs, LED light engines and monolithic LEDs for a range of applications within the avionics, defence and industrial sectors”. PRP’s 2025 revenues £5.99m, reported EBIT £1.54m, net assets £4.43m. | AMBER/GREEN = (Graham) I'm comfortable staying moderately positive on this. Limited organic growth is the main counter-argument but it does at least still have the M&A engine working in its favour, as evidenced by today's acquisition. | |
Skinbiotherapeutics (LON:SBTX) (£50m | SR23) | SP -34% | RED ↓ (Graham) [no section below] I looked at this for the first time in June and took a neutral stance, willing to give it the benefit of the doubt as it raised fresh funds (over £4m) and announced an agreement to sell its supplements into SuperDrug. That may have been too optimistic as we learn today that the CEO has abruptly left with the Board asking questions about his conduct. The statement in today's announcement that "there will be no further comment at this time" leaves the market to assume various worst-case scenarios. In December, the company said it was on track for revenue this year (FY June 2026) of £6.2m, and adjusted EBITDA of £0.7m, which would represent excellent year-on-year progress. However, following today's announcement, I have to assume that it will be difficult to meet these expectations, following the loss of the CEO and at this delicate stage of the company's development. Therefore I'm afraid that a downgrade all the way to RED seems most sensible. | |
Celebrus Technologies (LON:CLBS) (£49m | SR39) | The Board has approved a share buyback programme of up to 1 million shares. “The Company intends to hold all Ordinary Shares so purchased in treasury for the purpose of satisfying future obligations in relation to its employees' or other share schemes.” | [GN] This buyback merely reduces dilution from various share schemes; it is not designed to permanently reduce the share count. | |
Nexteq (LON:NXQ) (£43m | SR61) | Nexteq has secured its first customer win and initial software license purchase order for its recently launched gaming software platform, “Launchpad”. This is the first commercial software-led sale for Quixant, which is Nexteq’s gaming brand. | ||
Cellbxhealth (LON:CLBX) (£12m | SR6) | CLBX has “decided to discontinue maintenance of its FDA establishment license and device listing for the Parsortix® system, which aligns its regulatory strategy with the Company's current operational and commercial priorities and strengthening cost discipline.” “This change has no impact on CelLBxHealth's sales pipeline, market forecasts, customer support, or ongoing partnerships.” | ||
GSTechnologies (LON:GST) (£12m | SR1) | 66.7% owned subsidiary Semnet has now formally issued and served a writ of summons against the sellers of Semnet a former Semnet manager “to vigorously pursue claims for alleged breaches of fiduciary and contractual duties”. The total damages sought are approximately US$4.2 million. |
SDI (LON:SDI)
Up 4% to 83.97p (£88m) - Acquisition of PRP Optoelectronics - Graham - AMBER/GREEN =
SDI calls itself “the buy and build group, focused on companies which design and manufacture specialist lab equipment, industrial & scientific sensors and industrial & scientific products”.
That doesn’t exactly roll off the tongue. I tend to think of it as a smaller iteration of Judges Scientific (LON:JDG).
Today it announced the acquisition of PRP Optoelectronics Ltd for £9.3m.
Key points:
PRP makes “custom high performance microLEDs, LED light engines and monolithic LEDs for a range of applications within the avionics, defence and industrial sectors”.
It is said to have “long-term revenue visibility, supported by long-term agreements, with a stable, blue-chip customer base and strong international revenues.”
Financials: in 2025, PRP had revenues of nearly £6m, EBIT of £1.5m and net assets of £4.43m including cash.
That remark about “including cash” is important, because SDI is paying £9.3m for the business excluding the cash. It’s paying an additional £2.8m for the cash (some of which is deferred until after completion).
So SDI is paying £9.3m for £1.5m of trailing EBIT, which is £1.125m assuming 25% tax. That makes for an earnings multiple of about 8x.
SDI itself trades more richly than that, as you’d expect for the acquiring company:
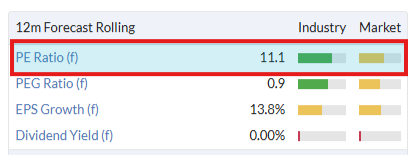
The above PE ratio could be increased slightly if you wished to adjust for £14m of net debt at SDI as of October 2025.
Indeed, SDI have updated us today with some cash and debt figures which imply that net debt had increased to £18m as of January 2026.
And this acquisition will also be funded by debt - the revolving credit facility from HSBC.
SDI’s CEO comment:
"The acquisition of PRP is a significant milestone for SDI, marking our entry into the avionics markets. The business boasts a range of products in a very particular niche, which have applications across multiple sectors, including in aviation and on platforms, including the General Dynamics F-16 and Airbus A320 among others.
Graham’s view
I have no objection to this. Of course it benefits SDI shareholders to see acquisition take place as cheaply as possible, and with small companies like PRP, I would ordinarily expect to see a lower trailing earnings multiple than 8x. But there may be very good reasons for the price paid. Maybe this is the going rate for businesses making LEDs?
Checking SDI’s interim results, I see organic growth was 3% (at constant currencies), buttressed by 6.9% growth from acquisitions.
We’ve been AMBER/GREEN on this for pretty good reasons, I think. Until organic growth speeds up, it’s hard to argue that it deserves a dramatically higher valuation than it’s already got. But at least the M&A engine is still working in its favour, meaning that the prospects for shareholders should hopefully still be decent.
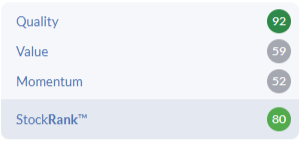
The StockRanks seem to agree with me: a view that’s positive, but not excessively so.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

43 comments
Looks like an AI enabler. Forward PE reported as 10x so if all goes to plan could be a winner. Id more Japanese stocks as Phil suggested but the £10K minimum trade size is a bit intimidating for me.
Has Sanderson Design (LON:SDG) been tipped anywhere. I hold it and do think it could be a bid target, but the price is up 30% this week. Or is the market just re-evaluating it after the positive FY trading update ? it was trading on a very low rating. Cost have been cut and with the recovery in North America maybe it is just that. Analysts seem to have a median target of 94.5p.
Totally understand, I’d be the same if it was 35% of my stock portfolio!
Congratulations to be in that position, it’s been a great investment thus far.
Without wishing to get into political territory, I'd have thought microfinance (lending to entrepreneurs to grow their business) could be considered a socially positive form of lending? As compared to consumer lending, for example.
Elixirr International (LON:ELIX) super value now, AI fears no doubt. Have to see where bottom may be.
Graham,
First thanks for all your hard work.
Regarding Rightmove (RMV) I came across an article posted on 13/11/2025 that may partially explain the weakness in the share price. It can be found at:
https://www.investments.halifax.co.uk/research-centre/news-centre/article/?id=21219784&type=bsm which states
Rightmove acknowledge notice of a potential legal claim on Thursday, amid mounting criticism over the cost of its listing fees for estate agents and new reports that thousands of firms could seek up to £1bn in damages.
Any views?
PS I tried inserting the link but failed. Hence I inserted it longhand. Sorry but computer skills are NOT my forte.
RE: Rightmove (LON:RMV)
Yes the legal case is a threat, although probably most of the recent weakness has been due to AI fears. These types of cases can take years to resolve, but the main risk is that it attracts regulatory interest due to market dominance - and potentially limits RMV's ability to put prices up.
In reality no one likes having to pay a middleman, but the agents need to list where the buyers look, and the buyers look - mainly - on Rightmove. Changing that will take more than some clever site-skimming AI. But anything that restricts the company's ability to control prices is a real issue. It's likely to be a drag on the share price for some time.
If looking at UK based marketplaces I think Autotrader (LON:AUTO) looks the better bet, same type of economics, less immediate regulatory risk.
timarr
Re: RMV, that is the sort of news story that's consistent with my reason for investing in Rightmove in the first place! Charging unfair/excessive fees is exactly the type of accusation that gets levied against a quasi-monopoly, and I invested in RMV precisely because I viewed it as a quasi-monopoly. And I would be astounded if those estate agents were successful with their claim but I guess anything is possible.
If it helps at all Butch, and I'm on a desktop pc, I left-click behind the last letter, an m, and drag back to the start of the link and let go th mouse so that the link is highlighted . Then I hold Control tab down and click C key and let go. Then I go to a new Tab on the browser you have up, click the address line and then hold Control key down a nd clicthe V key. This is copying and pasting de luxe. There, I just did it in reverse: https://www.investments.halifa...
Just click on it for now.
Silver
And to really economise on space Butch when posting a link, click on the chain link symbol on the top line of the text box you are typing in, this gives a menu from which you click on insert link. You should get a box where you can then paste the link you copied and below it a shorthand word such as "here". You should then get a hidden link here, highlighted in blue.
I re-read your post and see you might have already tried this so to practice you can go to an old thread and play around and edit then you'll know next time.
Thanks Sam, every day is a learning day.
Thank you for your advice. I will try next time. I am on a PC
Just doubled my stake in KEFI looks v good to me any comments please
What’s the attraction compared to for example Serabi Gold (LON:SRB)
Their announcement on 11 Feb and the MDs comments seem very interesting Bohemie don’t you think?
Yes all very interesting but what does it all add upto - far too complicated for the man in the street to comprehend. And the directors themselves hold only a tiny percentage of the total - in fact the list of major shareholders adds up to just 10%
I hold, have done so since it was cheap, I think it's one for day traders, has been all along. The thing is, KEFI Gold and Copper (LON:KEFI) hasn't got any gold ore out of the ground yet let alone poured. Investors like myself have been diluted but not visibly, nevertheless, those financial companies who have put money in for Harry Adams will have their pound of flesh. Dreams of a long-paying investment can be rudely awakened by say, a take-over as per Centamin, just as things were sailing along. I like to spread my investments but you can't beat a gold miner who is taking gold to market.
I don't normally look at US shares but one that has caught my attention is PayPal Holdings (NSQ:PYPL)
Does anyone here have any opinions or thoughts on this company and whether it is a value opportunity or value trap. Here is what Gemini says:
Investing in PayPal (PYPL) as of February 13, 2026, presents a high-risk, high-reward scenario as the company transitions from a high-growth fintech leader to a contested value stock. While the stock currently trades at distressed valuations, it faces severe competitive pressure and recent regulatory scrutiny. Current Market PositionAs of February 13, 2026, PayPal's stock is trading near $39.09, a significant drop from its early 2026 levels of approximately $58. This decline followed a disappointing Q4 2025 earnings report and a lowered 2026 profit outlook.
Key Investment Risks
Investment Opportunities
Key Insights
PYPL
I hold paypal - i was happy to buy in at 60p thought it looked nice and cheap at that price - so i look pretty silly now. I havent fundamentally changed my viewpoint - but havent had time to review the recent update to see in details whats gone so tragically wrong (i only have asmall holding).
what paypal does have is a very good worldwide customer base - its tricky though perhaps they are getting attacked on all sides ref margins. I would have though there core customers that are left are unlikely to leave en masse for a slight saving elsewhere just because its a tried and tested product. certainly in uk if you dont offer paypal if its anything like discretionary purchase someone may simply not buy if thats not an option - perhaps with caveat that i use apple pay alot more now - so perhaps they are losing out.
have i doubled down on my purchase here to take advantage of price drop and take up to more like full holding - not yet.
Not one of mine, but I read widely.
Here is some analysis by an enthusiastic holder of PayPal Holdings (NSQ:PYPL) :
Why PayPal Is Now My Portfolio's Largest Position
..and less enthusiastic with some history:
I started using Paypal when it was part of EBay over thirty years ago. Ebay was a bit of a wild-west story then but they had a monopoly on on-line auctions and a pretty big share of general e-commerce. I made a couple of successful claims against companies that over promised and under-delivered and liked the idea of one company holding my credit card details and have used it ever since, however, one company I use a lot is Amazon. They seem to be eating everyone else's lunch sales wise, they don't use Paypal and they have my credit card on file anyway so maybe that's a factor plus most people realise now that when paying by credit card, the contract is with the card company so a transaction is easily reversed on non delivery. Even as I read recently, restaurants having bills reversed after people have eaten a meal and left???? You have to wait 30 days for Paypal to cancel, so another factor.
Hi Bsharman. PayPal Holdings (NSQ:PYPL) I too had invested in Paypal, at the beginning of 2025 and held them as they continued to fall, as I use Paypal in the UK and liked the company. However, I'm a member of a very good and large chat group of USA investors and they are totally disparaging of Paypal, the business and the product. They say none of them use it, they don't know anyone who uses it and there are much better alternatives anyway.
There has recently been a change at the top and through my USA chat group I discovered that Paypal are using the UK to carry out a test of a major new strategy, which if successful will roll out in other areas. They choose the UK due to the high uptake here of digital wallets, payment using cell phone etc, and that it's a tough market. It seems we are ahead of the game in some areas!
However, I think I’m a high user of Paypal, as I have an Am Ex card links to it and so use Paypal whenever I can't use my Am Ex card online and I do a lot of purchases online for business and personal use. So you'd think Paypal would have contacted me by email to let me know of these great new services they are offering, especially because if this doesn't work here, they are even more dead than they are now. Because of this really terrible marketing and the reality of this business in the USA, where the product is not used and is deemed as a dead duck, I've finally given up on Paypal and sold. I invested the proceeds in Nebius NV (NSQ:NBIS. That was 5th Feb and that investment is already doing better than Paypal did over the past year. Yes they might turn around, but that is a massive if and to be fair, if the turn round works, it’s take a few years and when there are so many other companies that have so much more potential, paypal is just not worth the risk.
Natwest (LON:NWG)
Nice announcement today followed of course by a fall in the share price.
I bought these in 2024 on the basis that they were offering at that time an 8% dividend and were coming out of public ownership, as a bit of a punt. Since then they have supported my portfolio by making 180% rise in share price.
Maybe there is a little bit of profit taking today. Also, maybe a fear that at some point the Govt may choose to take a windfall tax on banks, a perennial concern, or that some of the Bank of England payments to the Banks will cease, as some challenger parties have suggested.
With the Bank's proposed buy back and dividend stream healthy, its still one to sit on a bit further for me (I suffer from the difficult bit of timely selling of shares) but would be interested in the views of others.
If it’s falling on today’s update then it must be time to sell!
I understand Graham's enthusiasm for £ASA but I have come to the conclusion that I really cannot make profit - and probably a lot of profit on the backs of usurious lending to people who have a poorer position in life than my dog. On the spur of the moment, and Graham's undoubted enthusiasm and figures that are very accurate, I bought in substabtially. A week later I sold. What made the difference? in the intervening week, I did a significant analysis on AI.
Just to check, did you sell ASA for moral reasons or did your Ai research uncover something negative?
sorry. Please ignore. Didnt finish. Ran out of time to edit. Redo later
On Evoke (LON:EVOK) - I'm currently holding one their competitors Rank (LON:RNK) who I have a hunch might pick up some of their online brands, also those of others. Already, several online casinos have withdrawn or announced their withdrawal from the UK market due to the increased Remote Gambling Duty.
Why I think Rank could be in prime position to consolidate the online casino market cheaply:
My Friday food for thought!
(I hold in the Boon Fund)
Nice work, Boon!
Hi Graham,
Thanks for the update on your portfolio. Do you still hold Volvere (LON:VLE) in size or did you top-slice into recent price strength? It’s my best performer personally so interesting to know if you have done anything with this one ?
Hi OldSchool, as I've said before, I'm a seller of Volvere as the position is too large for me. As of today it's still 35% of my single-stock portfolio.
Recently signed up for the USA subscription and have noticed that, even for established shares such as Microsoft, the value rank is below 25. I don't normally touch shares with a value rank below 40 let alone 25. Do you need a different mindset when approaching American shares?
Microsoft has helped to drive the US market higher in recent years, it's a $3 trillion company and part of the Magnificent 7. Generally speaking, there aren't any obvious bargains in US blue-chips these days.
Yes. I raised on Twitter yesterday my disquiet at Pershing Square Holdings (LON:PSH) now owning 3 Mag7 shares (Alphabet (NSQ:GOOG) Amazon.com (NSQ:AMZN) and the recent addition of Meta Platforms (NSQ:META) . The clear view of the majority of US investors is that being able to buy such companies at 25x earnings is value. They may be right, but personally I see so many opportunities around the world where valuations are much more reasonable. And as there is evidence of a bit of rotation out of the Mag7 into almost anything else, I don't see a huge reason to get involved.
Also, be aware that almost all pension funds in the US are passive (a result of a litigious culture where you get sued for underperformance). So every month, as long as employment holds up, money pours into the market on a weighted basis: so the biggest companies get the most new investment. It's a one way bet, until it isn't. At which point nobody really knows what happens next.
Interesting conversation! Looking at Amazon.com (NSQ:AMZN) and Microsoft (NSQ:MSFT), they are on FY26 and FY27 ratings of 25.6 & 21 and 24.2 & 21.1, respectively. Given these two, plus Alphabet (NSQ:GOOG) are exposed to, and control, the most exciting growth area in the world, data centres and cloud, I think these are indeed cheap. If AI is truly going to be widely adopted, every single company in the world will need cloud access to run systems. Don't forget, the data center build out is only just beginning. Personally, I view this weakness as an opportunity to buy in to these three at decent valuations.
Holding 3 Mag shares in a concentrated portfolio makes it look like Ackman has run out of original ideas - other than how to do some complicated financial engineering around PSH that will doubtless end up with more revenues for him and less for the investors.
NVIDIA (NSQ:NVDA) had a value rank of 0 and 1 but the shares still soared. The PEG was below 1 though. US shares look expensive compared to UK but they often lots of cash, no debt and high growth.
The stock ranks essentially say that stocks which have a high stock rank on average outperform stocks with a low stockrank. It isn't saying that every stock with a low stockrank will underperform.
Think you have missed my point, was not talking about the Stockrank, just the Value rank on US stocks. Since NVIDIA (NSQ:NVDA) VR has soared to 5 the shares have gone flat.
NVIDIA (NSQ:NVDA) got a lot of flak about being over priced but most people missed the growth and it beating forecasts. Now growth has reduced and VR has gone up.
I've bought a couple of US stocks recently and have found some value. However, its difficult! I look for high Q/M type stocks but if a company also have decent value then - BINGO! I also look at the PEG value which assuming a stock delivers on the growth promised at least makes one feel that the valuation might be justified.
Microsoft's PEG is 1.6 - not too expensive. This, and some other large US tech stocks seem to be getting cheaper tat the moment. There might be a buying opportunity soon perhaps?
One interesting stock that screened well recently for me was Strattec Security (NMQ:STRT) ;
This has a PEG of 1.1
Cheers,
Jim
I also dipped my toe into the US market in late December - to diversify away from a portfolio largely based on UK value stocks/stocko NAP selections.
I used the Phil Hoffer screen to identify potential candidates and invested in Micron Technology (NSQ:MU. Its undoubtedly higher risk and the rankings currently show:
Its forecasting the sort of growth you just don't see in the UK market:
Aug 2025 net profit actual $8.5bn
Aug 26 net profit f/cast $38bn
Aug 27 net profit f/cast $51bn
- Current peg ratio 0.2. IF (big IF) it achieves the forecasts then p/e falls to 10.2.
I have noticed the shares are volatile and bounce around daily. I don't kid myself that they wont be immune if AI shakeout fears turn into reality.
I would say yes, you do need a different approach to pure stock ranks for the US market. Ed has commented in the past that the ranking system seems to work better in the UK than the US. Personally I ignore the value ranks for US stocks (and make my own judgement), and am very glad I have done over the years. Imo Microsoft, Amazon and Meta are all fair value at worst and potentially are looking very good value. These are some of the strongest moats in the world. They are some of best diversified businesses you can find. There end markets are decades long growth stories. I am buying, will keep buying if they drop more and will hold through all the noise. They are all well positioned to continue to disrupt and continue to be long term winners. Just my opinion, but honestly some of the crap on the UK market that has higher valuations than the hyper scalers is laughable. For instance a year ago, bytes was trading at a higher rating than alphabet, and we can see what the prices have done since. I think people get carried away with p/e and forget that maybe the best companies in the world are actually worth a pretty decent premium. And these businesses are so good that if they drop you can usually safely buy more. You don't have to constantly re evaluate every RNS etc to time the perfect entry and exit. So my opinion is the stock ranks are wrong on the value metrics for lots of US businesses and I'll keep buying at these levels.
Totally agree. After 2 decades of investing in the UK (on top of global trackers), the penny has finally dropped that, if you want capital growth (rather than income), you need to have large exposure to long term quality US tech compounders (e.g. Amazon, Alphabet, Microsoft, Meta). UK stocks are cheap but generally so for a reason. There are few UK companies that are genuinely leaders in sectors with massive global tailwinds. If you can buy Amazon, Alphabet & Microsoft for low to mid 20 p/e ratios, taking a 5 year view, you are extremely likely to outperform the UK market.