Daily Stock Market Report (Fri 14 Feb 2025) - TATE, XPS, WG., TLY, NWG

Happy Valentine's Day,
Mark has given us a view on TATE to get us started.
1pm: hanging up my pen there for the week, have a nice weekend!
New research piece by Alex: Can brokers outperform simple algorithms in the world of investing?
The Week Ahead has been written by Keelan this time, including an in-depth look at Jet2 which will publish a full-year trading update next week.
Share price movements today
At the Investors Chronicle, Simon Thompson has published his bargain shares for 2025. These include my largest holding Volvere (LON:VLE) in addition to Crystal Amber Fund (LON:CRS), Gattaca (LON:GATC), Creightons (LON:CRL), Agronomics (LON:ANIC), Assetco (LON:ASTO), Carr's (LON:CARR), K3 Business Technology (LON:KBT) and Tavistock Investments (LON:TAVI). Several of these shares have risen in response to being tipped in this way.
My attitude to this is as follows: if I was already thinking about selling, then the day of a tip is a fabulous day to sell, as I'll probably get a higher price with extra liquidity.
On the other hand, if I wasn't thinking about selling, then I take no action. I haven't sold any of my VLE shares yet but as they approach my estimate of fair value I may start thinking about it!
In general, the people who react to a tip by buying are very unlikely to have the patience to stick around for the long haul, as they don't have real conviction of their own in the idea. So in the end, I don't think that tips make much of a difference: you get an initial spike of buying activity, but then it quickly dissipates. The new buyers will probably sell and move on to something else before too long.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Natwest (LON:NWG) (£35.2bn) | Annual Results | EPS 53.5p, up 12%. RoTE 17.5%. TNAV per share increases to 329p. Outlook: RoTE 15-16%. | AMBER/GREEN (Graham) [no section below] Outlook for 2025 suggests a small deterioration in return on tangible equity (ROTE) but income is expected to rise >4%. Possible small rise in impairments to 20 basis points. CET1 stable at 13-14%. I think it's ok to be moderately positive on the major banks although they are not the bargains they once were. PER 8x. |
Coca-Cola Europacific Partners (LON:CCEP) (£30.3bn) | Preliminary Results | Rev +3.5%, operating profit +8% (heavily adjusted figures). Guidance: rev +4%, op profit +7%. | |
SEGRO (LON:SGRO) (£9.8bn) | Results for FY24 | 5% growth in earnings and dividends. £91m in new headline rent. Confident outlook for 2025. | |
XPS Pensions (LON:XPS) (£719m) | TU | FY March 2025 materially ahead. Rev £226-229m, +15-16%. Efficient delivery, op. leverage. | AMBER/GREEN (Graham) Downgrading this as valuation is starting to make me nervous. But it's a very impressive growth story and I remain generally positive on it. |
John Wood (LON:WG.) (£452m) | TU | FY24 in line. Prior years may need to be restated. Outlook: EBITDA in line but with negative free cash flow and additional cost reductions needed. | RED (Graham) Totally uninvestable. Admits it has problems with its financial culture. Terrible balance sheet, debts expiring next year. Needs to fix a range of problems before I'd consider changing my stance. |
Distribution Finance Capital Holdings (LON:DFCH) (£69m) | Authorisation to conduct consumer lending | Plans to launch asset finance/hire purchase in H1, having received FCA authorisation. | |
Fiinu (LON:BANK) (£34m) | Equity fundraise | Raised £1.25m at 10p (last night’s SP: 12.5p). Use of funds: develop “Plugin Overdraft” product. | |
Transense Technologies (LON:TRT) (£22m) | Strategic partnership | Ohio-based Haltec becomes a formal distributor of TRT’s advanced tyre inspection tools. | |
Totally (LON:TLY) (£13m) | Outlook update | Profit warning: FY March 2026 expectations assumed the renewal of an NHS contract. | AMBER/RED (Graham) Low-margin service providers deserve modest valuations. This one may offer some speculative upside but I don't see it as a solid investment opportunity. |
Backlog
Tate & Lyle (LON:TATE)
Down 9% to 575p - Trading Statement - Mark - AMBER
This statement starts off well:
Tate & Lyle delivered another quarter of solid operating performance, with volume and EBITDA growth and continued strong cash delivery.
Like many businesses at the moment, they are cost-cutting:
We delivered further productivity savings during the quarter, with good progress against our five-year US$150 million productivity target.
But this doesn’t seem to be enough, as the rub is:
For the year ending 31 March 2025, excluding CP Kelco and in constant currency, we now expect revenue to be mid-single digit percent lower and for EBITDA growth to be towards the lower end of our guidance range of 4% to 7%.
Perhaps not surprising when they have revenue down 6% in the first 9 months of the year. Last year they generated £328m EBITDA, so 4% growth works out to be £341m. It is a seasonal business, but they say:
While market demand remains broadly stable, we have not yet seen the acceleration in demand we expected in the second half of the 2025 financial year
As always seems to be the case with these things, they have completed their buyback program just before a profits warning and share price drop!
On 9 January 2025 we completed our £215 million on-market share buyback programme to return the net proceeds from the sale of our remaining interest in Primient to shareholders.
They probably can’t afford another buy back in the short term, as the acquisition of CP Kelco leaves them with significant leverage. In October, following the CP Kelco acquistion, they said:
Net debt to EBITDA leverage anticipated to be approximately 2.3x at the financial year-end following completion.
But this is presumably now a bit higher due to EBITDA coming in at the lower end of guidance.
Mark’s view
The CP Kelco acquisition makes it really hard to value this as it impacts the EBITDA, net debt and share count. So, in this case, I defer to the StockRanks of the pre-acquisition business:
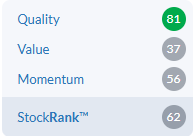
These suggest that it is a reasonable business but one that is hard to be excited about. Particularly when many other UK-listed stocks look cheap at the moment. AMBER
Graham's Section
XPS Pensions (LON:XPS)
Up 11% to 385p (£802m) - Trading Update - Graham - AMBER/GREEN
Let’s start with the good news story of the day. Performance at XPS is materially ahead of expectations.
XPS Pensions Group plc ("XPS" or the "Group") is pleased to provide an unscheduled trading update (unaudited) for the year ending 31 March 2025.
Revenues are now expected at £226-229m, vs. consensus forecast of £226m.
Revenue growth will be pushing 16% at the higher end - and with only a month and a half left until year-end, surely the company must believe that it is likely to get close to £229m?
However, beating the revenue forecast by less than 2% is not enough for performance to be materially ahead. There must be conversion into higher profits. Let’s read on:
High levels of demand for our services from continued regulatory change, new clients, and the inflation-linkage of our contracts, combined with the resilience and predictability of our business model has driven a strong performance for the year. Growth drivers in the year include GMP [guaranteed minimum pension] equalisation, rectification projects following the McCloud judgement, and the impact of new business wins in the Risk Transfer market.
Thanks to XPS’s cost management, efficient delivery and operational gearing, full-year results are therefore anticipated to be materially ahead.
Estimates
Thanks to Canaccord for spelling this out for us in a new research note. Their new PBT forecast for FY March 2025 is £57.9m (previously £54.7m).
At first glance, it seems that this might be a case of an additional few million pounds of revenue dropping through very efficiently into profits.
However, according to Canaccord, who are the company’s broker, the main driver is work relating to the McCloud judgement being delivered more efficiently than previously expected. So it is mostly on the cost side of the equation that XPS has succeeded.
For FY March 2026, there is a smaller increase in expectations, with the adj. PBT forecast rising from £58.3m to £58.9m. And there is another, even smaller increase in expectations for FY March 2027.
CEO comment:
"We are pleased to be on course for another year of strong financial performance. There has been strong demand for our services, as clients have needed support to respond to market and regulatory changes. At the same time as achieving strong growth, we have been delighted with the results of our annual client survey, which were extremely positive. At XPS our culture is at the heart of what we do, and I would like to thank all our people for the way they support each other and our clients."
Graham’s view
I’m a little perplexed by the 11% increase in the share price today.
The PBT forecast for the current year has only increased by 6%. I get that this is “materially ahead” of expectations, but when it’s delivered through cost management rather than incremental revenues, this is not the most exciting way to beat forecasts. Cost management cannot be relied upon to deliver growth indefinitely!
This is borne out in the fact that broker PBT forecasts for future years have barely budged.
So I would have thought that a more modest share price increase this morning would have been justified.
Thinking about the company more broadly, this is a stock that we’ve liked for some time.
I was GREEN on it in June 2023 at 170p, thinking that it was a little expensive relative to earnings at the time, but that it had the potential to keep growing. I liked the high rate of organic growth (17% at the time) and inflation-proof, recurring revenues. There seems to be no shortage of demand for pensions-related services.
The June 2023 review was followed up by more GREEN reviews in November 2023, June 2024 (by Paul) and October 2024 (again by Paul).
Not only have earnings grown substantially, but the multiple attached to those earnings has grown too - from about 14x to 18x. The compound effect is that the share price has more than doubled.
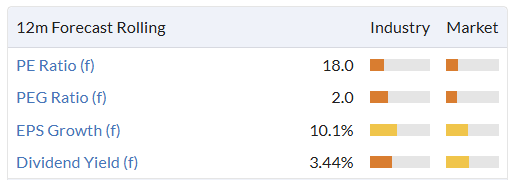
Based on the latest share price and Canaccord’s update, the latest P/E ratio is about 20x. And that’s using adjusted EPS - the actual P/E ratio will be higher than this.
So perhaps I should downgrade this to AMBER/GREEN now, on valuation grounds?
In 2023, the earnings multiple was 14x and organic growth was 17%.
Now, the earnings multiple is 18x and there is only revenue growth of up to 7% pencilled in for next year. PBT is only forecast to grow by 2%.
However, as it has in the past, I believe that XPS is very likely to beat these expectations:
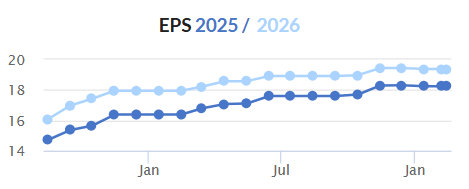
So we might be able to assume with some confidence that XPS will beat the latest set of expectations.
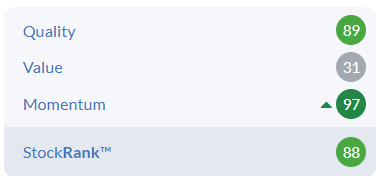
But I fear that it will be much harder to prove that it is undervalued, now that it is already trading at an adjusted PER of 20x. And at this sort of rating, any disappointment could lead to a sharp reversal.
I am therefore going to downgrade my stance this to AMBER/GREEN. I’m still very impressed by its growth and I like it as a candidate for a long-term hold. But the valuation is starting to worry me a little.
The StockRanks see the same thing:
John Wood (LON:WG.)
Down 33% to 43.5p (£302m / $380m) - FY24 Trading Update - Graham - RED
There is a lot to unpack with this trading update but firstly can I say commiserations to anyone holding this overnight. A 33% fall would be enough to unsettle anyone.
We last covered this in November, a day when WG shares fell 44% in response to the previous major profit warning.
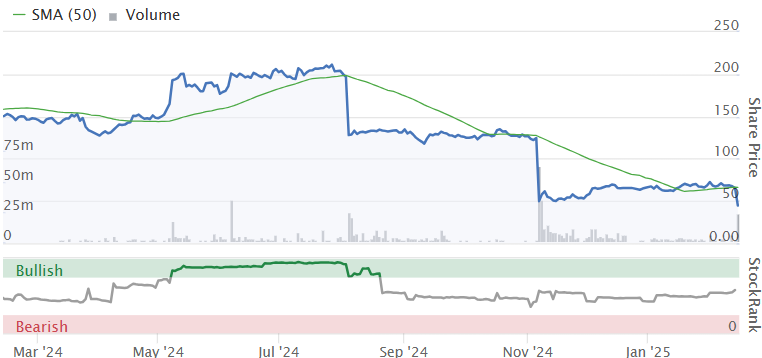
I’m relieved to see that I was fully RED on it then due to its “extraordinarily high risk and a lack of redeeming features”. Problems included:
horrific interim results
continued exposure to losses from historic risky contracts
the need for an independent review of contracts, seemingly instigated by WG’s auditor
Negative tangible book value
Extremely high receivables
Net debt of nearly $700m excluding leases.
Today’s update tells us that FY24 EBITDA of $450-460m is “broadly in line with guidance”.
FY23 EBITDA was $423m, so full-year growth will be 6.4% to 8.7%. This is indeed close to previous guidance for “high single digits”
However, the bad news starts here.
There was weaker-than-expected Q4 trading, and the company mitigated that by cancelling executive and employee bonuses and “actively managing working capital at year end”.
Net debt excluding leases is still nearly $700m and that’s the year-end figure. Kudos to the company for publishing its average net debt figure, even if it’s an unsettling one: $1.1 billion.
Independent review: this is ongoing. WG are “evaluating the extent of prior year adjustments which the company expects will be required”.
Given prior results, it has become pretty obvious that the numbers here are a mess. So it’s no surprise that more adjustments are needed. The only question is how big they might be. We’ll have to wait to find out.
WG admits to having serious problems. It’s rare that we see “financial culture” being acknowledged as a weakness:
The Company is initiating steps to strengthen significantly the Group's financial culture, governance and controls in light of material identified weaknesses and failures
Transformation: as we knew already, WG is not doing any more “lump sum turnkey” work, as they are the riskiest type of contract.
WG has been in the worst of both worlds: on the one hand being aggressively pursued by some customers in relation to the work done, while at the same time having to pursue other customers who have failed to pay. It seems that lump sum turnkey contracts have a tendency to create this situation.
On the cost front, WG are looking to achieve savings of $60m in FY25 and then a further $85m in FY26. There will be one-off costs involved in this.
They say in bold:
Following these actions, the business will be on a firmer operational footing, but cash generation has yet to materialise and financial strength needs significant improvement
Updated 2025 outlook
We expect double-digit adjusted EBITDA and adjusted EBIT growth (excluding the impact of disposals) in 2025
This remains in line with market expectations, though our pathway to this now includes taking additional cost reduction measures as outlined above
So they will only achieve their EBITDA/EBIT targets by cutting themselves down in size.
And the costs of cutting - redundancy, etc. - will be categorised as exceptional items. So there is little hope of clean accounts any time soon.
Negative free cash flow is expected, at minus $150m to minus $200m. The company plans to balance this with disposals. Average net debt is again expected at $1.1bn, before taking disposals into account.
Graham’s view
This is totally uninvestable in my view.
There is a $1.2bn RCF expiring in October 2026, and a $200m term loan expires then, too. The clock is ticking. WG has managed to pass its covenants up to this point, but my worry is that they have only done this by resorting to extreme measures, and that more extreme measures may be required.
They are not allowed to have a leverage multiple (net debt to EBITDA) of more than 3.5x, and they are not allowed to have interest cover of less than 3.5x.
At the interim results, they reported a leverage multiple of 2.5x and interest cover of 3.9x. So they were in compliance then.
My sense is that they are now running the company on the basis of keeping a compliant EBITDA figure, as they have no other choice. But successful businesses do not operate this way.
I don’t know if there is any price at which I could turn positive or even neutral on this share. The list of problems and red flags just goes on and on. From an investment point of view, my stance is the same: it’s extraordinarily high risk, with a lack of redeeming features.
Totally (LON:TLY)
Down 23% to 5.1p (£10m) - Outlook update - Graham - AMBER/RED
This health service provider was well-summarised by Paul in 2023:
The fundamental problem with TLY, is that it’s doing quite big, low margin contracts for the NHS, but seems to have a fair bit of risk within those contracts - both cost over-runs, and uncertainty over renewal.
Today we learn that TLY’s NHS 111 contract has not been renewed by NHS England. It’s not a reflection of TLY’s work, but of a change in strategy at the NHS.
Revenue from the existing £13m contract was already going to be mostly recognised in the current financial year (FY March 2025).
For this financial year, TLY is still in line with expectations (£85m revenue, £3.5m EBITDA - note the very low EBITDA margin!)
Here is the profit warning:
The Board's financial expectations for the year ending 31 March 2026 did assume a renewal of the NHS 111 Contract, however at a reduced level. Work will commence to redeploy workforce where possible along with securing new contracts with new providers, although exceptional costs are expected. Based on the current revenue run rate of the Company, new contract wins and the current new business pipeline the Board now expects the financial performance of FY26 to be at a similar level to that which is expected to be reported for FY25.
Estimates: with many thanks again to Canaccord who have released a new revenue forecast of £85m for FY March 2026 (down from £95m) and a new FY March 2026 EBITDA forecast of £3.5m (down from £4.5m). So the loss of this contract is resulting in the loss of c. £10m of revenue and £1m of EBITDA. The implied EBITDA margin on this lost contract is unfortunately much higher than the average EBITDA that TLY earns across its business.
The new FY March 2026 forecasts now perfectly match the forecasts for FY March 2025.
Canaccord value the stock based on an EV/sales multiple. Using an earnings-based multiple isn’t appealing, as profits aren’t at a meaningful level - adj. PBT is expected to be less than £1m.
Graham’s view
The low margins here are very unappealing. I suppose this could be interesting on a speculative level as it’s perfectly possible new contracts (as resources are redeployed) and small changes in the revenue/cost equation could lead to profits spiking in the next year or two. But for now the company is bobbling around, not far above breakeven. I think that low-margin service providers such as this do deserve modest valuations. I’m AMBER/RED.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

50 comments
ST has also tipped my largest holding VLE which has risen in response. He has done this before, for this stock. Thanks Simon, if you're reading this!
Can be a good time to sell, following a share tip. ST bargains of the year, are down about 30% against the All Share index, over the past 2 years.
Must be due a good year, l suppose.
I do hold some Creightons (LON:CRL).
Can't sell either Creightons (LON:CRL) or Volvere (LON:VLE) at the moment, on my platform, so much for a market.
Just a positive on some of the bigger companies, Natwest (LON:NWG) has been good to me since I invested last year. A decent dividend and over 100% return proves sometimes there can be undervalue, though to be honest I got rather lucky on this one. Whether it will continue is moot, and I know a lot of analysts don't like banks.
Natwest (LON:NWG) I worry about the Gov. shareholding. Desperate to raise money they could just dump these in the market.
Nexxen International (LON:NEXN) does anyone know why their shares have halved today on no news that I can see?
They have delisted
For myself the annoying thing is that being one of my dogs I sold last December and within days the SP doubled. Now it is going to the Nasdaq I am glad it left my portfolio.
They haven’t delisted yet - they delist at close tonight.
The data provider obviously made a mistake and provided the consolidated price after close and then had to row back this morning (hence it appears to have halved when it has done no such thing)
Nexxen International (LON:NEXN) They did mention a 2 for 1 share split.
2:1 consolidation (not split) Rusty
As at cob tonight they will consolidate the ordinary UK listed shares at 2:1 to match the existing ADRs. Then they will move the ADRs to a Nasdaq listing on Monday.
Thus if you hold 1000 shares tonight in the UK you will get 500 shares on Monday which will be on Nasdaq. The price on the Nasdaq is currently double the price in the UK ($10.08) or £4. So you will own half the number of shares at double the price. Ie no impact.
For some reason the data provider assumed the consolidation at close last night (a day early) and made a mistake. The price (for today) remains where it was at 400p.
Stockopedia says: "Nexxen has actioned a 2-for-1 split today"
It is a right mess, my platform, has it down 97% but share price is around 400p.
https://www.stockopedia.com/sh...
Reasons to be cheerful.........listening to theToday program, there was an item about the Thames Tideway Tunnel starting to flow today. (Although listening to the Archers it does not cover Ambridge.)
Crystal Amber
went up by 5% this morning because Simon Thompson repeated his tip , this time in his 2025 bargain shares.
Funds and Investment trust were not discussed in this site before but recent changes may expand discussions to cover this group of investments in the future. CRS qualify for discussion on market cap of £124m and has done well over the last year, returning 42%.
Charles Mitchell covers this in his investment trust sector in Stocko. This is a superb section of Stocko dedicated to funds and investment trusts.
Pinewood Tech showings what it can do with new contracts - and there should be more to come?
Pinewood Technologies (LON:PINE) showings what it can do with new contracts - and there should be more to come?
With 7% dilution:
In recognition of the significant scale of this contract and the importance of the partnership going forward, Pinewood has issued warrants to an affiliate of Global Auto Holdings in respect of a maximum of 6,098,093 ordinary shares up to an equivalent of 7% of the current issued share capital of Pinewood (the "Warrants"), which shall be exercisable at a strike price of 330.0p (based on Pinewood's closing share price on 13 February 2025) in tranches subject to the satisfactory completion of the installation of the Pinewood Automotive Intelligence™ platform into the entirety of each relevant geography, with the equivalent of 5% for the UK, 1% for North America, and 1% for Scandinavia.
Without having had the time to analyse this properly it's hard to say what it really means, but it's certainly unusual.
timarr
Tate & Lyle (LON:TATE) is another to add to the list of companies that should not have been undertaking a buyback. What a ridiculous time to do so. They make a major acquisition of CP Kelco and then push their leverage even higher. This is just nonsense bravado to try and tell the market that they have total confidence in the acquisition and the cash generation that should follow. Well, here is a suggestion for management. Why not suspend buybacks until the new business is successfully bedded in and debt has started to fall, surely a much more prudent approach?
I am not saying that CP Kelco will be a bad deal, just simply that many acquisitions don't pan out as planned. I would also add that Tate & Lyle (LON:TATE) has hardly been a management success over the years!
Have to agree on Tate & Lyle (LON:TATE) - has been a very poor performer over the last 8 years I have held. There was one spike when talk of potential acquirer but that came to nothing. We shall see if following Stockopedia's views on profit warnings turns out to be accurate in this case as I sold my holding this morning. You can now guarantee that the potential acquirer will return and the share price will rocket. However, I took the view that even at a 40% acquisition premium my investment still wouldn't be back to original cost so just not worth the uncertainty of continuing to hold.
Creightons (LON:CRL) has been on a trot in the last week but I can't see a clear reason for the change in mood. Anyone know?
Tipped yesterday by Simon Thomson I believe and also perhaps with GDP rising slightly might give the hope that spending over Xmas may not have been as bad as some have feared? I held from about 20p then sold out at 38p, bought back in at 28p, hoping to double if they can get moving.
Creightons (LON:CRL) is it one of Simon Thompson's bargain stocks of the year? Last year's lot did about minus 15% for the year!!
That doesn't bode well.
They also announced last week that they will move to AIM. I've revisited that statement and hidden in there appears to be a decent indication that their FCF is coming together:
The Company's cash at hand as at 31 December 2024 was £2.0 million. As at 31 December 2024 the Company carried out a review of its cash requirements for the next 12 months. Scenarios modelled included the removal of the Company's largest customer, reduction in gross profit margin and increases of 10 per cent. in total overheads. These sensitivities are considered by the Directors to be more extreme than the conditions prevailing during the last 12 months but demonstrate that even without management addressing current overhead levels or increasing prices to customers, the Company would not fully utilise available cash (and committed bank facilities) over the next 12 months.
The Directors have therefore formed a judgement, at the time of approving the financial statements, that there is a reasonable expectation that the Company has adequate resources to continue in operational existence for the foreseeable future being at least twelve months from the date of this document.
Creightons (LON:CRL) why move to the AIM? Several stocks have announced they are moving from the AIM to the main market, which has gone down well, see Mortgage Advice Bureau (Holdings) (LON:MAB1), many see the AIM as failing soon.
Its market cap is £22M. Not worth hassle and costs, which of course drives up profitability, can get more auditors, move faster to get things done.
Would you move to this?
"many experts believe it is struggling due to factors like low liquidity, declining investor interest, a lack of new listings, and recent changes to tax rules which have made it less attractive for companies to remain listed, leading to a significant drop in its overall performance compared to other stock markets."
l think many decent AIM companies will be moving to the main market
Creightons (LON:CRL) have said that due to their size, they don't attract any index tracker funds and that a move to AIM could assist in IHT/Stamp Duty transfers.
I haven't had the chance to go through their accounts, but looked at a rough minimum cost to hold a full listing (back of a fag packet) £425,000 on FTSE vs £125,000 on AIM on an ongoing basis.
For a company like Creightons (LON:CRL) and their recent woes, that is a significant saving. I have no view on whether it is a good move given it won't affect my ability to trade, I'm not bothered.
IHT relief could be wiped out as the Govt. is desperate to raise taxes. Several larger stocks have announced plans to delist from the AIM, Nexxen International (LON:NEXN) GlobalData (LON:DATA) Gamma Communications (LON:GAMA) and Mortgage Advice Bureau (Holdings) (LON:MAB1). Would not surprise me if Burford Capital (LON:BUR) did.
A few people think the AIM will be disbanded soon.
Yu (LON:YU.) would do well to consider this
I suspect many will stay for the tax incentive and maybe there will be a movement into AIM, the tax incentive is valuable for shareholders
If that goes, l think it will be end of the AIM. Look at the performance of AIM shares before the last budget. The larger stocks are moving out.
In October '24, 92 stocks had delisted from AIM, in a year. Only 6 stocks were over £1bn, an all time low, 2 of which plan to delist, this year.
Minus 2.7% but 19.3% less than the All share index.
K3 Business Technology (LON:KBT) up 22% today, just because of a share tip.
Strange that these are not behind a paywall.
They are pretty useless last few years, will all spike then gradually drop back
Apparently tipped as a 2025 Value play in Investors Chronicle
Ah, thanks. That could be it .... Creightons (LON:CRL)
Hermes International SCA (EPA:RMS) showing the sector how it's done today, seems to me to be a fantastic set of results (but am biased as it is my #1 holding) and there's a special divi on top. This is the standout biz in the luxury sector, and as I have said the growth is now rotating towards the US and away from China which has been a factor in swinging the SP up & down. Hoping for good signs at the open....
PARIS, Feb 14 (Reuters) - French luxury group Hermes HRMS.PA reported an 18% rise in fourth quarter sales on Friday, showing robust appetite from wealthy shoppers for the most expensive luxury items like its Birkin bags, which cost upwards of $10,000.
Sales for the end-of-year period came to 3.96 billion euros ($4.14 billion), an 18% rise at constant exchange rates, accelerating in the important end of year period, with the fastest growth in the Americas and Japan.
Hopefully this is good news for Burberry (LON:BRBY) Burberry . I bought last year after reading Roland’s excellent article ‘Burberry , buy now for recovery’. My fingers are crossed for more gains to come.
Hi LumpedOn
This from a news feed of Hermes International SCA (EPA:RMS)
PARIS, Feb 14 (Reuters) - Hermes HRMS.PA is looking into adding an haute couture line, which it could launch as soon as 2026 or 2027, Axel Dumas, executive chairman of the French label said on Friday.
"We are thinking about an haute couture line," he told analysts at a presentation of the group's full-year results.
"There has to be an aesthetic reason, it has to be beautiful, there has to be specific know-how," he added.
Regards
Howard
Howard - thanks. Maybe that's why it's given back nearly all its 5% gain this morning !
They clearly know the biz better than me, but I wouldn't like to see distractions like this. Hermes International SCA (EPA:RMS) has always appealed to me because of its moat - the Birkin Bag - and the tight focus on product range that generates terrific margins.
I also hold a large chunk of LVMH Moet Hennessy Louis Vuitton SE (EPA:MC) but check the SP progress over the last 5 years and see the impact of a large revenue stream from fashion lines.
Hindsight is easy, but I wish I'd got on with my idea to rotate LVMH into Hermes over summer last year. Just such a hard decision at the time to merge my #1 & #2 holdings into a single biz... As they say, always trust your gut.
XPS Pensions (LON:XPS) worth a look today.
Trading update:
"A strong finish to the year, performance anticipated to be materially ahead of expectations."
Hi David, I think you are right, with all the regulatory changes in workplace pensions, and more on the way it's a no-brainer. It's one of my top five largest positions—growth with a 3% yield. What's not to like?
XPS Pensions (LON:XPS) start administering the John Lewis Partnership pension scheme from this month too - 130,000+ members
Have I missed some news on MS International (LON:MSI) ? Did the market not know that yesterday's options existed?
US buy local policy, and don't fund Ukraine?
If people are selling MS International (LON:MSI) based on that then they need to do a lot more research on the stocks they buy Snowdrop
MS International (LON:MSI) already operates locally in the US so makes no difference
Don’t fund Ukraine is irrelevant for MS International (LON:MSI)
It is clear defence spending long term is only going one way (and it’s not down)
This is small uninformed and under researched retail shareholders selling tiny amounts in an illiquid stock. MS International (LON:MSI) is now on a cash adjusted PER of about 6 !!!
The options are immaterial - satisfied from Treasury
MS International (LON:MSI) What just 13,334 options?
Woodford seems more optimistic on the economy than the Bank of England... https://www.woodfordviews.com/...
Yeah he did a seminar last night. Reckons there will be 4 rate cuts this year including the one recently. Thinks growth will be higher than forecast and inflation won’t be as bad as feared
one interesting point he made about China was that if you invested in a Chinese index fund back in 2014 you would actually have earned a negative return on your investment over the ten years
The story out of China is getting more and more ominous by the day. The mother of all property crashes.
The market's reaction to John Wood Group's update, has to be 'intrigue of the day'. Anyone know of a more torturous restructuring?