Daily Stock Market Report (Fri 14th November 2025) - Burry steps away, GDWN, PPHE, DFS, MTL, CRS, SALT

Happy Friday!
This is at risk of becoming a weekly "What has Michael Burry done next?" column, but I can't help noticing that Burry has deregistered his hedge fund.
A letter dated October 27th to his investors said that he is returning capital. The reason given: "My estimation of value in securities is not now, and has not been for some time, in sync with the markets".
On October 31st, he said "Sometimes, we see bubbles. Sometimes, there is something to do about it. Sometimes, the only winning move is not to play."
On November 10th, he accused the "hyperscalers" (tech mega-caps META, GOOG, ORCL, MSFT, AMZN) of understating depreciation by extending the useful life of their Nvidia chips and servers, which in turn inflates their earnings.
He very recently disclosed a large bet against Palantir, although the size was not as large as the media originally reported: he spent $9.2 million on 50,000 Palantir options, each of which is for 100 Palantir shares, these options having a strike price of $50. The maximum profits on the bet are therefore $250m if Palantir goes to zero in 2027. That would not be bad for a fund with AUM of c. $155m earlier this year.
Perhaps he and his investors are unhappy with his recent performance? Perhaps he's not sure what the best strategy is to short the AI/tech bubble, and so he prefers "not to play" the game of shorting it with other people's money? Or perhaps he simply prefers investing away from the limelight of having a registered fund. Either way, I very much doubt that this is the last we've heard of him.
Mello London is next week, and several of us will be there! If you are thinking of going, they have given us a 25% discount code: STOCKOPEDIA25. This will make a 1 day ticket £74.25 (instead of £99) or a 2 day ticket £126.75 (instead of £169).
Tickets can be bought here and the programme is here.
Have a great weekend everyone.
Spreadsheet accompanying this report: link (last updated to: 5th November)
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Melrose Industries (LON:MRO) (£7.9bn) | Our guidance for the full year remains unchanged: revenue £3.425 - 3.575 billion. Adjusted operating profit of £620-650m. | ||
Land Securities (LON:LAND) (£4.8bn) | Increase in guidance. FY26 EPRA EPS growth expected to be at the top end of c. 2-4% guidance, before the impact of a disposal. | ||
| Goodwin (LON:GDWN) | Placing of shares in Goodwin Plc | The family sell 1.6% of the company to a limited number of institutional investors. | AMBER/GREEN (Graham) I’m inclined to leave our moderately positive stance unchanged here. The sale by the Goodwin family doesn’t change very much. It does let us know that the stock’s valuation is rather full - but we knew that already. |
Supermarket Income REIT (LON:SUPR) (£1.0bn) | Acquires 20 Carrefour supermarkets in France through sale and leaseback transaction. €123m invested at a net initial yield of 6.6%. | ||
PPHE Hotel (LON:PPH) (£628m) | Eli Papouchado and Boris Ivesha (owning 44% collectively) “intend to hold a small handful of meetings with financial investors in relation to a range of potential options, from contributing growth capital to PPHE, to a potential partial monetisation of their stakes in PPHE.” | PINK (AMBER/GREEN) (Graham) I'm inclined to view this as Papouchado and/or Ivesha looking to crystallise the work they've done and the value they've built over many years. It could be good or bad for the stock price (although the market has interpreted it positively). The downside risk is that it creates a large overhang, with up to 44% of the company’s stock being perceived as (or actually) up for sale. The upside risk is that the company ends up going private, and existing shareholders get to cash out at a number closer to EPRA NAV. EPRA value per share was £28.07, according to the interim results: that's 66% higher than the current share price. It’s a very speculative possibility, but the talks that are about to take place could be the catalyst. | |
DFS Furniture (LON:DFS) (£371m) | “Whilst it is still relatively early in our financial year and we are mindful of the broader macroeconomic environment and the uncertainty created by the upcoming Autumn budget, we remain comfortable with the range of consensus profit expectations.” | AMBER/RED (Graham) Another reassuring in-line update. Perhaps I'm too cautious on it; I just think it's worthwhile to be very careful in this sector, especially when large leases and other debts are involved. For now at least, the company is performing well and I can understand why the market is putting it on a respectable PER of c. 11x. I may be forced to revert to neutral if it continues to pump out positive updates and clean profits. | |
Metals Exploration (LON:MTL) (£366m) | SP -2% Operations at Runruno were impacted by the Super-typhoon Uwan. The Company is revising its annual gold production guidance from 70-75k oz to 65-70k oz. | BLACK (Graham) [no section below] I'm no expert when it comes to this share but the moderate share price reaction and the text of the RNS itself says that the typhoon is not a major problem for the company. From midpoint to midpoint, the reduction in production guidance is 7%, and this results not just from the typhoon but from cyanide contamination in September. Sadly this typhoon has resulted in some deaths and the displacement of over a million people in the Philippines. | |
Frp Advisory (LON:FRP) (£361m) | £6m plus payment for net assets acquired (£650k) and earn-out. Arc is “a renowned FCA-regulated provider of financial advisory services to the real estate sector.” | ||
Idox (LON:IDOX) (£326m) | Shares subject to irrevocable undertakings/letters of intent to support the takeover have increased from 22.97% of shares to 29.47% of shares. | PINK | |
MJ GLEESON (LON:GLE) (£220m) | “The Board, whilst mindful that the Government's Autumn Budget will be announced on 26 November 2025, expects that the results for the financial year ended 30 June 2026 will be in line with current market expectations.” | ||
Crystal Amber Fund (LON:CRS) (£95m) | Crystal Amber Asset Management intends to resign. Strategic proposal from Tarncourt Capital to manage the fund. | GREEN (Graham) [no section below] I mentioned this one very recently, commenting on their interesting portfolio of mostly unlisted equity investments, and their 29% discount to NAV. I also noticed recently that their investment manager Richard Bernstein had turned up as the CEO of Insig Ai (LON:INSG). It didn't seem very plausible that he could continue both roles, and a solution has now been found. CRS shares could very well continue to trade at a discount but surely their new manager will be thinking about how to narrow it? | |
Shield Therapeutics (LON:STX) (£71m) | STX’s partner, MEDLEAP Pharma, has initiated a Phase II trial for ACCRUFER® (ferric maltol), a new drug candidate for Pulmonary Arterial Hypertension (PAH), for patients in Japan. | ||
Steppe Cement (LON:STCM) (£39m) | Proposed capital repayment of approx. 1.5p per share. $4.35m in cash to be paid in GBP. | ||
MicroSalt (LON:SALT) (£30m) | 2025: confident of exceeding its original expectation of full year revenue of $2.0 million. 2026 projection: sales to total $7.0 million based on in-hand volume estimations and its current customer base, rising to more than $15.0 million in 2027. Guidance at the interim results: 2026 revenues of $6.5-7m, and at least $13m in 2027. | RED (Graham) [no section below] A genuinely exciting situation here where the company claims to be on the verge of achieving a massive step-up in revenues. There is no broker coverage so investors who are willing to do the work here and verify the company's claims could get a real edge. However, I'm going to leave my negative stance unchanged from last time when I listed seven reasons for caution. I'd like to wait and see if the promises turn into reality. Checking the interim results, I see that the company's gross margin improved from deeply negative to breakeven. That's a start. Cash was $0.9m. | |
Aptamer (LON:APTA) (£26m) | “With £1.95 million of binding contracts already secured and seven months remaining in the financial year, the Board is confident that full year revenue will materially exceed the prior year's performance.” | ||
Rentguarantor Holdings (LON:RGG) (£18m) | Individual franchised branches of Winkworth Estate & Letting Agents will have the option of introducing the RentGuarantor service to their tenants. | ||
Goldplat (LON:GDP) (£16m) | “A strong operating quarter supported by the high gold price and good supply from South America and once off supply in South Africa.” £200k dividend. |
Graham's Section
Goodwin (LON:GDWN)
Down 8% to £205.76 (£1.55bn) - Placing of shares in Goodwin Plc - Graham - AMBER/GREEN
A brief RNS this morning that discloses the sale of 1.6% of Goodwin Plc by the Goodwin family.
The buyers are “a limited number of institutional investors”.
GDWN shares have had an incredible multi-bagging run:
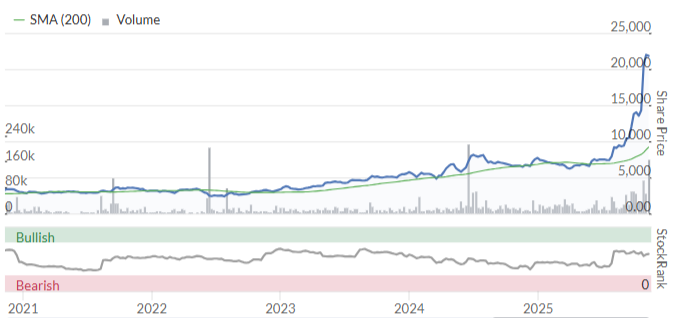
122,000 shares have been sold - these were worth £4m five years ago, £8m a year ago, and c. £25m today.
Whenever an insider sells out, it’s important to put it in context.
The Goodwin family are still very heavily invested in their company. At the moment, the shareholder list consists only of individuals, and I think that pretty much all of them are family members. Their combined holdings are 63%, with Richard Goodwin having 50%. The top 5:
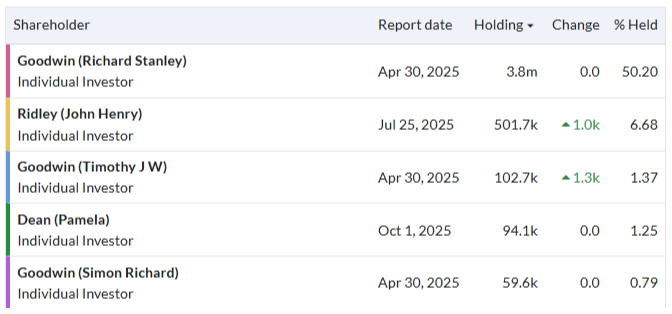
In this context, the sale of 1.6% doesn’t change all that much. The family remains in control of the business and they are still highly motivated to see it succeed.
However the sale of c. £25m of stock should, I think, be seen as a signal that the stock’s valuation is reasonably full.
The ValueRank is only 6:
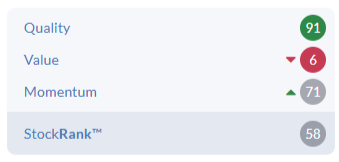
However, please bear in mind that the valuation metrics involved here are unusually backward-looking, as the company generally doesn’t get involved in the City’s usual routine of attempting to meet market forecasts. I don’t blame them for that - my own largest holdings take a similar approach.
But this does mean that the P/E ratio you’ll find on Goodwin’s StockReport is a trailing PE, not a forward-looking PE. All other metrics are also trailing metrics.
It wouldn’t matter so much if Goodwin’s EPS wasn’t growing so quickly.
At the October update, they told us to expect a trading PBT for FY April 2025 of over £71m - that’s double the result for the prior year.
The ValueRank can’t take that into account yet, so I do think the ValueRank is a little understated.
But at a £1.55bn market cap, it is arguably expensive even if you take the new PBT forecast into account. I estimate the current-year P/E multiple at 29x.
Putting it all together, I’m inclined to leave our moderately positive stance unchanged here. The sale by the Goodwin family doesn’t change very much. It does let us know that the stock’s valuation is rather full - but we knew that already.
PPHE Hotel (LON:PPH)
Up 13% to £16.90 (£707m) - Graham - AMBER/GREEN
I’m putting a PINK on this as PPHE is now officially considered to be in an “offer period”, as a result of this announcement:
Eli Papouchado and Boris Ivesha (the "Shareholders"), who collectively own c.44% of the voting rights of PPHE Hotel Group Limited ("PPHE"), note the recent media speculation and confirm that they intend to hold a small handful of meetings with financial investors in relation to a range of potential options, from contributing growth capital to PPHE, to a potential partial monetisation of their stakes in PPHE.
In some ways this resembles the Goodwin announcement above, but the market has responded very differently.
In the case of PPHE, Eli Papouchado (age 88) is the founder, while Boris Ivesha (age 72) is the President and CEO.
Mr. Papouchado was Chairman from 1989 until the beginning of this year.
Mr. Ivesha shares his CEO duties with a Co-CEO.
I have spoken to management here a couple of times - my notes after my most recent meeting with CFO Daniel Kos were written up for Stockopedia here. He made good arguments as to why the valuation of the company using real estate principles (the “EPRA” valuation, £1,188m) is more realistic than the balance sheet value, and much higher than the current market cap.
Today’s announcement mentions the potential for the company to receive growth capital. While Mr. Kos also expressed to me that the company wished to raise growth capital, I think investors will rightly focus instead on the possibility of a “monetisation” of the Papouchado/Ivesha shares.
In practice this could mean a large placing, as we had with Goodwin.
Another possibility - however speculative - is that an investor might be found who would be interested to buy the entire group. Not just the Papouchado/Ivesha shares, but all of them.
Graham’s view
I’ve been reluctant to upgrade my stance on PPHE for a couple of reasons. Firstly, it issued a profit warning in August and I don’t want to upgrade my stance on a company where estimates are under pressure.
Secondly, I try to avoid being unduly swayed by persuasive management teams - top executives are always very convincing!
In the case of PPH, I was AMBER/GREEN on it prior to the August profit warning, and I’m happy to return to that stance today.
There haven’t been any further downward revisions to earnings forecasts since August:
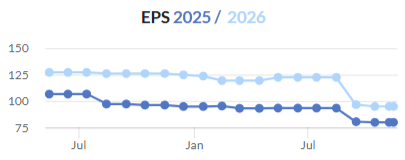
When it comes to interpreting today's news, I'm inclined to view it as Papouchado and/or Ivesha looking to crystallise the work they've done and the value they've built over many years.
it could be good or bad for the stock price (although the market has interpreted it positively). The downside risk is that it creates a large overhang, with up to 44% of the company’s stock being perceived as (or actually) up for sale.
The upside risk, as I’ve mentioned, is that the company ends up going private, and existing shareholders get to cash out at a number closer to EPRA NAV. EPRA value per share was £28.07, according to the interim results: that's 66% higher than the current share price. It’s a very speculative possibility, but the talks that are about to take place could be the catalyst.
DFS Furniture (LON:DFS)
Up 0.6% to 159.44p (£373m) - AGM Trading Statement - Graham - AMBER/RED
DFS Furniture plc (the 'Group'), the market leading retailer of upholstered furniture in the United Kingdom, provides the following update in advance of its Annual General Meeting later today.
It’s a nice little update from DFS. Key points:
Order intake growth in line with expectations
Outperformed the market according to Lloyds Bank data (external link outlining the Lloyds-DFS relationship).
Expects to deliver strong year on year profit growth in H1 (period to December).
Key sentence:
Whilst it is still relatively early in our financial year and we are mindful of the broader macroeconomic environment and the uncertainty created by the upcoming Autumn budget, we remain comfortable with the range of consensus profit expectations.
Expectations: profit before tax and brand amortisation £37.6 to £43m, with a consensus figure £40.6m.
Graham’s view
I upgraded our stance on this (from RED to AMBER/RED) in September, after an in-line trading update accompanied the full-year results.
The question for me today is whether it deserves another upgrade after another in-line update.
My instincts say no, because we aren’t cautious on this stock due to concerns that it won’t hit earnings.
We are cautious on it due to a) the sector, which demands a low valuation, and b) the DFS balance sheet, which isn’t very strong.
Net debt was last seen at £107m, which is on top of lease debt.
I tend to think about stocks in terms of how many large risks are involved. Roughly speaking, if there is one large risk, I can live with that. If there are two, I am cautious. If there are three, I tend to avoid it altogether.
At DFS, the risks are:
The sector, which is both cyclical and highly competitive. No moat.
Large lease liabilities. It’s normal, but it is a risk.
Financial net debt, last seen at £107m.
I wish them well but I’d rather stay cautious on this share until the balance sheet improves further and/or the valuation becomes even more obviously cheap.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

77 comments
Can anyone conform the placing price for the Goodwin (LON:GDWN) shares? I have read that it was £190 which implies a 17% discount to the closing price on the eve of the placing.
Would be fascinating to know who bought the shares. Was it just two investors? Given that it is so difficult to value Goodwin one senses that the new investors will have done their homework on the valuation which looks way higher than that of much bigger quality names such as Rolls Royce, Halma and Renishaw.
The fact that the placing was done through Rothschild, rather than some unknown regional broker, suggests that the Goodwin shares have probably gone to a good long-term home which is what the family would want.
Re Goodwin (LON:GDWN) I’d respectfully suggest today’s sale tells us more about the timing of the budget than the valuation of the business…firstly it wasn’t a sale by the Directors it was a sale by other wider non PCA Goodwin family members who were deemed part of the concert party and therefore the sale needed to be RNS’d but no further details needed to be released in terms of price or resultant holding. The exec directors hold their shares predominantly in a an IoM trust so aren’t exposed to whatever tax related budget surprises are incoming. Incidentally we saw similar but smaller sales by wider family members when the company did a tender offer at £48 a share a couple of years back.
As to valuation you’re right to point out it’s gone up a lot…but then again there’s rather a lot going on in the business that suggests we’re in for some step changes…in a good way..in the months and years ahead.
BTW I hold
Hi Rhomboid1
Just curious
How do you know who is the exact seller?
Thanks
Because the RNS said who wasn’t selling …(J M securities No. 3) whilst still referring to the Goodwin family …and that there was any RNS at all made it clear they must have been part of the concert party but not currently directors or connected parties under the PCA definition
I have read the RNS!
Thanks
I got that wrong…they all harvested some gains pre budget…disclosure should arguably have been clearer
Thanks for clarifying this Rhom.
I wasn’t trying to suggest that you were wrong as you are one of the few here that are always crystal clear.
Just the original RNS did not make sense to me.
All the best
Well having back tracked on tax rises lord knows where she will get the required 20 bil from there have been rumours of lowering the tax thresholds maybe the 48k working people limit Starmer has been banging on about is where higher rate tax will now kick in.
Poor old Reeves I can see her howling again come budget day.
Volex (LON:VLX) I hold. Very clear presentation of recent results and future plans given on IMC platform earlier - recording will be available soon. New project involving AFC Energy and their hydrogen generator mentioned. https://fuelcellsworks.com/202...
Volex is exposed to so many positive drivers it would be a surprise if it did not do well. It just has one material weakness in its numbers, being the very low margins that prevent it from enjoying a higher rating. On the surface it provides similar products to market leader Prysmian. Under the hood the numbers are substantially different. We hold both under our geographical diversification strategy.
BnB
Interesting. I first heard of Prysmian about a couple of hours ago when Nat Rothschild mentioned them in reply to a question regarding Volex (LON:VLX) getting into the national grids market! He acknowledged them as a main player and said Volex would not be competing as they preferred working in more niche areas where they felt they could excel.
Or perhaps he got lucky once?
I learnt a new word today, 'zugzwang', which I am reliably informed is a term used in chess. A situation where a player is forced to move, but every possible move makes their position worse.
Rachel Reeves is basically in political zugzwang right now — she has to act, but every option makes something worse. If she cuts spending, she angers her own MPs; if she raises taxes, she hits voters and business confidence; if she loosens fiscal rules, the markets punish her; and if she sticks to them, public services suffer. She can’t stand still, but every move carries a cost — that’s why her position feels so fragile.
Yes - Zugzwang is indeed a term used in chess and yes it describes a situation where the opponent has no viable move.
Probably one of the greatest players in creating Zugzwang for an opponent was the Grandmaster and former World Champion, Tigran Petrosian. It was once reported that he was the first player to create Zugzwang with 32 pieces on the board.
Yes - Ms Reeves is in a no win situation.
I learnt a new word today, 'zugzwang'
I first encountered the word reading Money by Martin Amis, where it plays a key part, a book that is an appropriate title to reference on an investing site. It happens to be my favourite novel of all time (I'm a literature graduate and have endured all the classics). It contrives to sneak a trenchant contemplation of identity, masculinity and Freud into a biting satire of 80's excess and the power of money, which in turn is layered beneath a hilarious and bawdy romp through the world of advertising agencies, sex clubs and Hollywood. It contains the least politically-correct joke of all time - seriously - at which I could not stop laughing for several days and is, to this reader, the funniest book ever written, whilst moving me to tears at every reading. I return to it every five years or so and find greater depths at every visit. I'm not alone. The director of the Hay Literary Festival described it as the greatest novel of the 20th century.
Those who have read it will hopefully smile at the recollection. Those who have not - I envy you.
Solves my what to listen to next conundrum thanks bnb
Funny, it lies half read on my "I'll finish reading that.....sometime" pile. It has been there for several years.
From memory, I wasn't very far through when I parked it.
BnB I have ordered a copy of the book!
I hope you like it.
It is her job to do what needs to be done - her reluctance shines a light on her inadequacy.
Give over - she's not that good....
I agree....to an extent. I just think she needs to call the bluff of her backbenchers. Raise income tax, and put some cuts through to public spending. They wont like it....but what are they prepared to do. My guess....absolutely nothing. They can see the polls and wont want to trigger an election. And as far as replacing the leadership goes....with who....the parliamentary party is too split to even agree on a shortlist! Reeves needs to get on with the job...pull the trigger...and risk the internal political heat.
You are right here, the basic maths is that she can either screw the economy and the markets, and have happy backbenchers. Or she can go for sensible economic decisions and have a seething back bench.
In the first instance the market will do a “Truss” and have her out of a job in a fortnight, or she can expect the backbenchers to seethe, wring their hands and still be doing that when the finances start to recover, at which point they will forget whatever they were angry about and sing the praises of the government. My bet? She will screw up the economy.
Worry is she might actually think she is doing the sensible economic decisions.... and end up screwing the economy anyway.
I agree. The country needs the money. I would say in my opinion Labour made a mistake claiming taxes would not go up when they were elected. Where did they think the money would come from to solve the fact the country is skint?
After the backbenchers voted against any form of public spending cut, it was game over for Starmer and Reeves. I think they know this.
Hi Graham, I'm conscious that you had a marathon set of results yesterday and today's list is also unusually long for a Friday, but do you have any thoughts on the fall in 3i (LON:III)?
The 3i fall is puzzling - I too haven't found any commentary on it either - whether here or elsewhere. It's classified as a private equity investment trust - which trade at a discount of maybe 30 per cent or so to NAV - although from memory, over 60 per cent of its investment is in Action, the Dutch retailer. Compared to Tesco, its figures stack up well.
It seems the fall is due to disappointing figures from Action, by far their biggest holding.
Don't know any details though, not a holder.
3i (LON:III) the CEO bought 30,000 yesterday. That is about a £1m.
The private discounter, Action, is 3i largest holding comprising 80% of its NAV. Actions’s October sales performance was weaker than expected, esp in France, and that’s why 3i has tanked. 3i has also bought another 2% stake in Action from GIC.
I would be careful investing in 3i (LON:III) as you’re basically betting on Action doing well and there is really no diversification in 3i’s portfolio.
And a further 2% (presumably in the market) taking them to 64% holding
It trades at a premium to NAV I think not at a discount
3i
I am an ex holder. it is a share which fascinates me. A private equity at a massive 48%premium (risk no1), its main investment is in a non food retailer called Action (risk no2). Its long term performance, however, has been extraordinary over the years.
Yesterday drop relates to slowing growth in Action sales.
I first bought many years ago after the current CEO bought £1m shares and subsequently the share price kept rising. I notice he has done it again. The difference is, the first time purchase was at a discount but the recent buy , even after recent falls, is still at a huge premium.
For me, rarely, any premium is worth paying.
Yes, I am frequently gobsmacked by how management at 3i (LON:III) can justify the lack of diversification in the portfolio. Absolutely not what investors signed up for a few years back. Of course while Action keeps performing and hence 3i (LON:III) continues its relentless ascent no questions are asked. However when the music stops will be the day of reckoning.
I have absolutely zero interest in buying a private equity fund with 80% of its assets in one overseas retailer and even less interest in paying a thumping premium for the pleasure!
I believe the thing which caused the share price to drop yesterday was the comment made by the board of directors which stated that they will be cautious in deploying capital as the transaction market and the wider environment are likely to remain challenging into H2.
David.
Re your Michael Burry comments, very interesting. I am an IT Director and am pretty skeptical about the benefits of AI outside certain niches. I recently wrote a paper for the Board in which I made some critical comments about AI in our industry and how the reference stories were largely relabeling. I applied our AI tool to smarten the paper up, ...... and it deleted or edited all negative comments!! I am, needless to say, making sure I have got my money out of my AI Stocks (all NASDAQ).
I applied our AI tool to smarten the paper up, ...... and it deleted or edited all negative comments!!
It's the start of "the rise of the machines".
I think the rise happened 7-8 years ago I think its no fluke that the division in Western societies started really gaining traction when social media platforms exploded.
This might be an interesting watch if you have 1/2 hr to spare.... (there is clearly an agenda here - so as usual : beware of confirmation bias)
I have to say in my current world (consulting/interim marketing operations lead), I am finding new uses of AI almost daily. Things that would have taken days are taking hours, things that would have taken hours are taking minutes. And we are barely scratching the surface.
Do you have any tips/sites worth visiting on how to use it best ?
Well I am learning like the rest of us but I am finding that the more I put in, the more I get out. So P&L figures, conversion stats, thoughts, hypotheses, meeting notes, interview notes (pretty much all dictated but after the fact so that I can add my interpretation of what happened.) I am using enterprise chatGPT inside a project so all chats get assimilated. And with some strong underlying instructions which get evaluated with each prompt. And always human in the loop.
Many thanks for coming back to me.
Initial moves from Bonds and £sterling are negative with long Bonds 20-30y yields +13bp and £ -20-50bp..... Im not sure what the thinking behind todays newspaper stories can be but if the government were in any doubt how the market would react I guess they have their answer. This situation cant be allowed to play out until the budget so something better must be announced over the weekend. Im going to assume a huge fuss but we should have something that works fairly quickly - we know the playbook since we have been here before.
Maybe that is the one benefit from all of this. Either anger your back benchers over the next 3 and a half years, or anger the markets 3 and a half minutes after you stand up on budget day.
Sadly it seems she'll do the former. Ironically that'll scupper the bank benchers too, not that they seem to understand that.
My guess is they were forced to put this out by internal frustration at broken election pledges....and have been naive to hope the markets will be relaxed. I guess Reeves is gone now anyway and someone credible will have to be put in to increases tax and cut spending ..... otherwise the government will fall.
Ange maybe RD ? she seems to know plenty of angles when it comes to finances
Need a very positive front foot statement by Sunday IMO
It's honestly an absolute circus. The number of about-turns by this government would make an Olympic ice skater dizzy. After the embarrassing disaster over attempting some minor spending cuts earlier in the year only to be shot down by their own backbenchers at the last minute, they've gone and done it again - preparing the whole country (and the markets) for income tax rises and making a special speech to lay the groundwork only to then totally reverse course again. All this does is create the impression of in-fighting and a disorganised mess with no fixed direction of travel and no long term plan. Nothing can be trusted as the party can't even agree with itself. The only thing the market hates more in the long term than bad news is not knowing what's going on at all - well done Labour for creating the worst possible outcome and prolonging and strengthening the international perception that the UK deserves a 'moron premium' on our debt costs. Heaven only knows what sort of hotchpotch mélange of a shopping list of small measures we will now be faced with to fill the gaping void that was supposed to be filled by the income tax rise. I despair.
Brilliant BIACS - couldn’t have expressed it any better!
Brilliant BIACS - couldn’t have expressed it any better!
Ange Postecoglou?
We can only dream
Lol yes Ange's infamous high line in football is in the same bracket as Reeves not going ahead with income tax rises. Both policies didn't work and Ange paid the price. Will Reeves?
So much for bashing the blockers (back benches) and the bold words both at conference and the early morning podium a couple of weeks ago.
There was a degree of wisdom in the old practice of staying completely silent until the budget is announced in parliament.
What we have now on the budget in the MSM (not here - we are more sensible, but have no choice bit to swim in the same water) reminds me of a busy ADVFN bulletin board as a TU approaches.
As such there may be some valuable information / prediction out there, but good luck finding it.
A sea of red today best to avoid ticker watching
Big drops are the best times to top-up or start a new position!
In my current portfolio, looking at topping up Nichols (LON:NICL) and Rank (LON:RNK) , albeit both have Budget risks in terms of increased "sin" taxes. Especially now Income tax is off the table... System1 (LON:SYS1) also looking like a good top-up, being double hit by the wider gloom around BOTH advertising and technology.
Then outside my current holdings, I've got on my radar Unite (LON:UTG) Barratt Redrow (LON:BTRW), Billington Holdings (LON:BILN) and Eurocell (LON:ECEL) . You'd notice all are in a somewhat similar sector (housing or construction related). All been hit by gloomy sentiment going into Budget. Hence all share prices sitting at levels I think are good buys. If there an ETF for this basket, I'd spread my risk around. But going to have a stab at choosing one or two to add as positions into my portfolio shortly.
However, could all go lower as we head closer to the Budget and the media frenzy ramps up?
It might not be your bag but amongst construction sector stocks we really like Alumasc after recent falls. Eurocell and the like need economic recovery to flourish. Alumasc just needs it to keep raining.
Eurocell and the like need economic recovery to flourish.
yes - i very much see the litmus test of labour as being their ability to deliver the level of new homes they promised. in that regard they are running the show the buck stops with them and any excuses for failing to deliver imho will be very weak. they simply need to do whatever is necessary to start that process happpening now. Up to now i get the disticnt impression they have almost given up before they have started. imho without that actvity ramping up and the the current polciy of making it super expensive to move house or sell up and bank ones profits - and lack of ability to reduce interest rates. its almost as if everything that they should be doing to go in the right direction is going south. I think the best we can hope for is that inflation worries dissipate interets rates come down and the interest paid by the governemnt on its debt also comes - very little sign of anything working in that regard though once you add in rising unemployment.
Worth mentioning the placement of shares in Goodwin (LON:GDWN) as announced this morning - from family direct to Institutions
https://www.stockopedia.com/sh...
Yes I certainly don't begrudge the Goodwin (LON:GDWN) family cashing in a "relatively" small stake of around £26m, considering that just one of the family owns around £800m. I don't believe that it signals anything negative about the company or its prospects. However I do take issue with the fact that the announcement made no mention of the price of the placing - I assumed (perhaps wrongly) that it was required disclosable information for a publicly traded company?
Further to this, I asked AI (which I realise is not necessarily correct), and received the following answer with both PWC and Slaughter & May citations:
"Under the current and newly updated UK Listing Rules, disclosure of the placing price is aimed at ensuring transparency for all market participants and is considered inside information that must be made public without undue delay. These rules help maintain market integrity and allow all shareholders and the market as a whole to assess the impact of the placing transaction"
Another edit - perhaps I've jumped the gun as I just re-read the RNS and note that settlement of the placing is expected on 17th November 2025 when presumably they will make a further announcement on the price.
The price is only disclosable if one of the directors were involved in the transaction (as they've disclosed in previous transactions). It seems it was a placing by other members of the family who are not directors.
Ah yes, that's a very good point. Thanks Brothersinarms.
It seems like placing was at £190 and to two institutions. Seems a fairly large discount to me, I’m sure they’d have got a better price with a private client placing. Placing coming from non management so that’s good news, I’m sure it’s just a CGT swerve ahead of the budget.
Thanks The Ox 2906. Can I ask where you would find that info?
I saw two trades at £190 on Sharescope…the co said “institutions” so I'm assuming it’s two of them!
Don't know why they took such a lowball price, they should have sold some in the open market.
3i (LON:III) Always a little skeptical of Dir buys that follow disappointment but fair play to Simon Burrows....£1m investment after yesterday is a decent message from him.
Always sad to see anyone fall on their sword.... extremely difficult circumstances lead one there .... but I very much agree that especially for private investors --- not playing in markets you don't understand is a valuable tool. If it isn't working and costing you money just sit in cash for a while and wait it out. Works for me and often saves you some money too. Good luck to Michael I say.
Going to hazard a guess that Aviva (LON:AV.) weakness was also some fear re budget measures that may affect pension contribution allowances. Sadly for all, the situation is far from resolution and current government look set to gamble with a market reaction they may not enjoy. No visible sign of extreme stress yet just further weakness in £ sterling and bonds but as we remember last time, if we ht pinch points then the automated sales will flow -- and no doubt the BoE will have to step in again. I would love to imagine they have a rabbit to draw but fear not and thus more volatility and negativity for a week or two. It goes without saying that cash will help smooth some of this .... whilst it may look awful at times I imagine it will all be over rather quickly so fingers crossed for the best outcome possible. The current government are on the ropes and one can't help wonder how long this is allowed to continue before the white towel is thrown in. Good luck all.....
P:S Some decent content on Merryn Talks Money recently, not least the Art Laffer episode - hopefully some of those in the treasury listen too.....
https://www.stockopedia.com/sh...
MS International (LON:MSI) put out this RNS after market close yesterday afternoon. Good news?
I would be surprised - I don't think I have ever seen delayed results being good for a share price before. Admittedly MS International (LON:MSI) are saying that it is due to the company's growth in recent years, but my concern would be that the accounts department might have missed something meaningful (and negative) as a result. We shall just have to wait and see.....
MS International (LON:MSI) they do reference that this is in line with a recent decision to allow more time to prepare accounts due to recent growth. I cant find any mention of this anywhere so assume it was not shared with shareholders. I also wonder if there is a possibility that they have had, or are negotiating, an improved offer for the three other divisions. the market seems to think it is positive news with the stock up 6% back to an ATH.
Yes, on a grim day like this it does seem as though someone is expecting a positive reason for the delay. Good luck to holders of the stock.
MS International (LON:MSI) Seems very strange that the shares are up 8%, on the back of this announcement, l have taken some profits. I was looking to reduce my holding anyway.