Daily Stock Market Report (Fri 15 Nov 2024) - DUKE, SOLI, VLX/TTG, NEXN, REC, GLE

Good morning! It's been a hectic week, let's see what Friday has in store for us.
Wrapping it up at 1pm. Thanks for all the interesting comments! Graham.
Explanatory notes
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day. We usually avoid the smallest, and most speculative companies, although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We have a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Add your own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
** New SCVR summary spreadsheet for calendar 2024 ** This is the live one! (updated 6/9/2024)
Archive - SCVR summary spreadsheet for calendar 2023
Companies Reporting
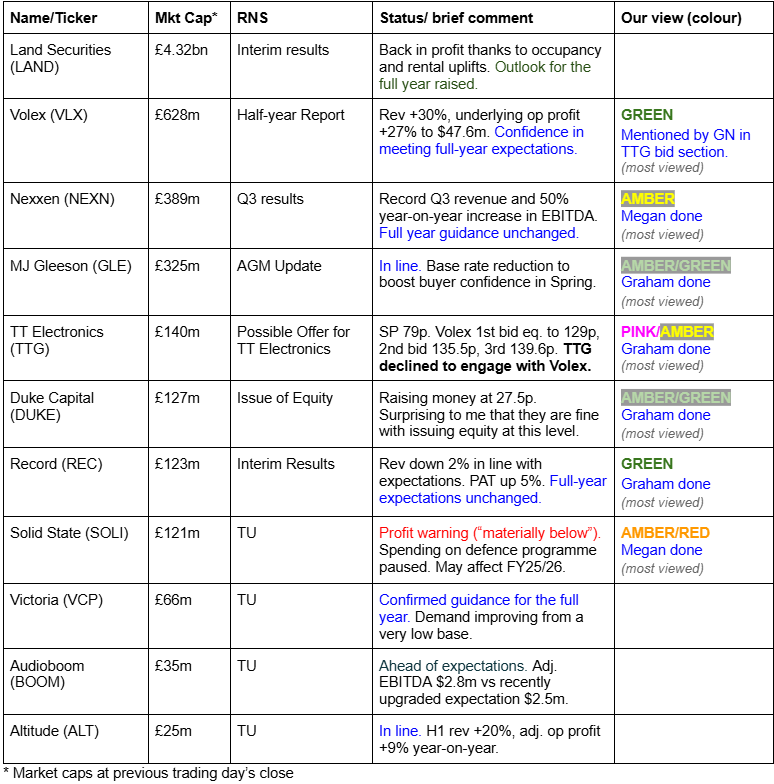
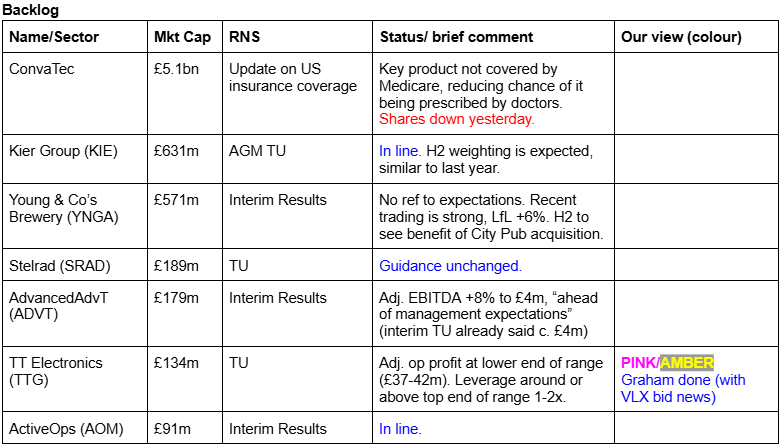
Summaries
Solid State (LON:SOLI) - down 48% to 110p (£121m) - Trading Update (profit warning) - Megan - AMBER/RED
A delay in orders from defence customers has forced the company to issue a major profit warning for the year to March 2025. Sales are now expected to be “materially below” consensus expectations. The delay, which management think has been caused by the government’s strategic defence review scheduled for next summer, could also impact orders into the new financial year as well. Shares have fallen a whopping 48% in early trading.
Duke Capital (LON:DUKE) - down 5% to 28.4p (£121m) - Issue of Equity - Graham - AMBER/GREEN
I’m disappointed to see DUKE raising funds at a price of just 27.5p. NAV is around 40p and I hoped that management would wait for the share price to recover closer to that level before raising. However, they could not wait any longer and for me this is a blow to the investment case. I downgrade this from GREEN.
TT electronics (LON:TTG) and Volex (LON:VLX) - TTG up 36% today to 107.8p (£192m) - VLX down 12% today to 301p (£546m) - Possible Offer for TT Electronics - Graham - AMBER on TTG, GREEN on VLX
Exciting news for shareholders in both companies as VLX reveals it made two bids for TTG, neither of which have been entertained yet by TTG management. A mix of cash and shares is proposed. If it goes ahead, VLX would pay the price of higher debt and substantial share count dilution for their most adventurous acquisition to date. It looks like a reasonable offer to me and if I held TTG, I’d be inclined to accept.
Nexxen International (LON:NEXN) - up 7% to 313p (£389m) - Q3 2024 Results - Megan - AMBER
Upgraded adjusted EBITDA guidance for the full year, alongside the confirmation of another $50m buyback scheme. Management has also proposed the cancellation of the AIM-traded shares in favour of Nasdaq and shareholders will be given a vote on this at the AGM in December. Nasdaq feels like a more appropriate market.
Record (LON:REC) - down 0.6% to 62p (£123m) - Interim Results - Graham - GREEN
The outlook for the full year is in line with expectations so perhaps the biggest news here is the launch of a €1.1 billion infrastructure equity fund. Revenues from this source should help to offset the loss of a client from Record’s “custom solutions” business, who switched over to their Passive Hedging product.
Short Sections
MJ GLEESON (LON:GLE)
Down 2% to 546p (£319m) - AGM Trading Update - Graham - AMBER/GREEN
It’s a brief AGM update from this homebuilder.
Key points:
Full year results (for June 2025) at this early stage are still expected to be in line with expectations.
However, the results will be “more weighted to the second half than usual”. This can be interpreted as an amber flag.
Gleeson Homes:
As anticipated, the lack of conviction in the market continued through the Autumn. Last week's base rate reduction was welcome and is expected to bolster buyer confidence into the important Spring selling season.
There’s an increase in net reservation rates but also continuing margin pressure.
And confusingly, they “will be selling overall on a lower average number of sites than last year”, despite opening 27 new sales sites during the year.
Gleeson Land: this should deliver a full year result materially ahead of last year.
Graham’s view: after reading this update, I think there’s an elevated risk of a profit warning this year, but it’s still early days and there is all to play for. My overall positive view is unchanged and so I will leave our AMBER/GREEN stance unchanged.
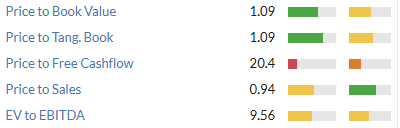
Graham's Section
Duke Capital (LON:DUKE)
30p (£127m) - Issue of Equity - Graham - AMBER/GREEN
We had news at 5pm last night from Duke Capital, “a leading provider of hybrid capital solutions for SME business owners in Europe and North America”.
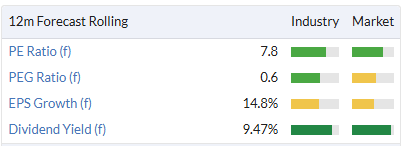
I’ve been GREEN on this stock, on the basis that it was trading at a discount to balance sheet NAV. My plan was to switch to AMBER/GREEN or AMBER if the stock made it to net asset value, c. 40p.
The reason for this strategy was twofold. Firstly, as an investment vehicle, I think it’s fair to value it relative to NAV.
Secondly, I believe that Duke will become more valuable the more diversified it is, and I’m aware that management are keen to raise money. My working assumption was that management would raise money as soon as they could do so in the region of 40p.
For context, the last time that Duke raised money was at 35p in May 2022. NAV per share was 37p at the time.
So I’m a little disappointed by last night’s announcement.
Duke are looking to raise at least £15m from a Placing, plus another £3m in a Retail Offer.
The price is the disappointing bit: they are looking to raise at only 27.5p.
Is this all they think existing shares are worth?
In one sense it’s fair enough: I’m the one who has focused on balance sheet NAV; management themselves haven’t talked about it much and instead tend to focus on recurring cash revenue as their main KPI, e.g. £6.3m of quarterly recurring cash revenue in Q1 FY 2025.
While cash revenue is a very important number, you do need to apply some sort of theoretical interest rate/capitalisation rate to it, if you are trying to value Duke as a whole. I prefer the objectivity of NAV.
And the fact that Duke waited two and a half years since the last placing suggests to me that maybe they were waiting for the share price to recover to a better level, before they raised more funds. But perhaps they grew impatient.
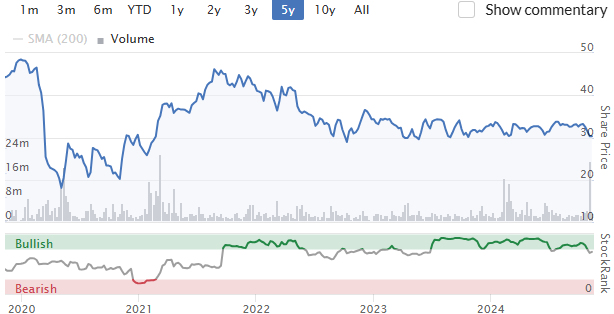
Covid, followed shortly afterwards by higher interest rates, have put a dent in Duke’s valuation. In late 2021/early 2022, the share price nearly recovered, but then I guess higher rates starting from Dec 2021 put a stop to that.
It was shortly after rates started rising that Duke carried out its last previous fundraise:
Graham’s view
This fundraise is negative for my GREEN thesis as I was relying on the company to avoid raising funds except at levels where I thought it would be attractive for them to do so.
I therefore have to downgrade my stance here. Perhaps I should go straight to neutral but that might be a little drastic. Let’s go to AMBER/GREEN for now. The shares do still offer a nice yield and as I said at the top, Duke does become more diversified, and therefore more valuable, the larger it grows. So the placing is not all bad news.
TT electronics (LON:TTG) and Volex (LON:VLX)
Possible Offer for TT Electronics - Graham - AMBER on TTG, GREEN on VLX
TTG: up 36% today to 107.8p (£192m)
VLX: down 12% today to 301p (£546m)
TTG is a stock I was positive on, until they issued a horrible profit warning in September, causing a sharp fall in the share price:
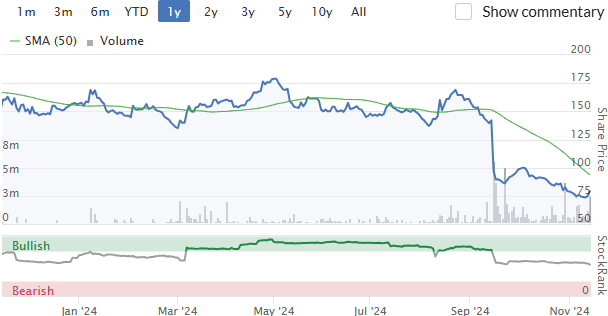
Today we learn that VLX has spotted value in it.
They do not say when they submitted their bids, but I’m confident that they all took place after the recent profit warning.
1st bid: 129p (of which 62.9p cash, the rest VLX shares).
2nd bid: 135.5p (of which 62.9p cash).
3rd and latest bid: 139.6p (no change to the terms of the offer, but with a higher VLX share price).
VLX notes that the latest bid is a 76.7% premium to last night’s closing price for TTG.
However, TTG has not engaged with VLX, i.e. the directors of TTG do not seem interested in recommending the bid to their shareholders.
Rationale for the bid
Firstly in terms of each company’s activities, it’s clear that they might be able to work together. TTG is an international designer/manufacturer of electronic components with sites dotted across the UK, the US and Asia. Their products are used in healthcare, aerospace/defence and various submarkets where processes need to be automated/electrified.
Volex, meanwhile, are “global integrated manufacturing specialists”, and they love to acquire: 12 businesses have been acquired since 2018.
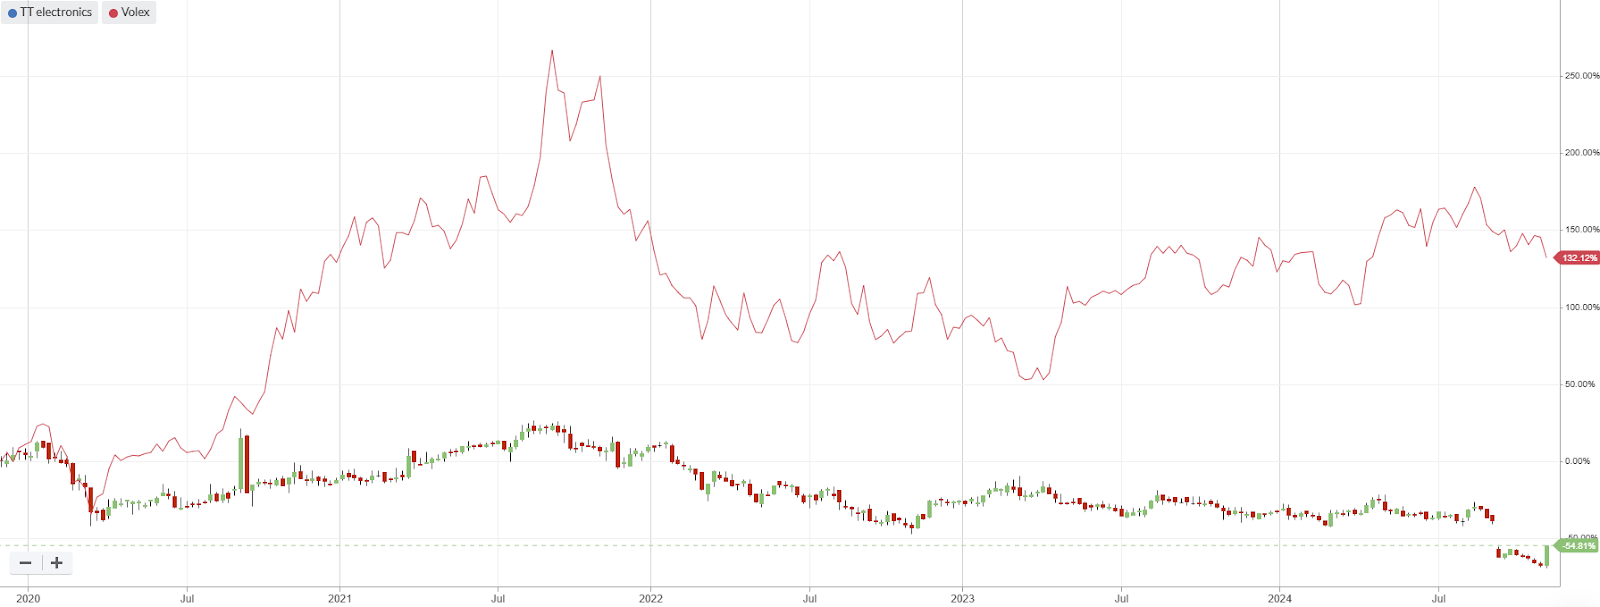
Volex, under the leadership of Lord Rothschild, has been the far superior investment over almost any timeframe.
The trend has been maintained over the past year, thanks to TTG’s recent profit warning.
Here’s a 5-year chart with TTG in candlesticks, VLX in red:
VLX aren’t afraid to put the boot into TTG management today (emphasis added):
Despite the resilience of TT Electronics' underlying business, it has faced persistent challenges in recent years, which Volex believes have been exacerbated by execution missteps by the Board, including former and current executive leadership. As a result TT Electronics' shares are trading at a 10 year low.
It’s hard to argue with the view that mistakes have been made at TTG - I said as much in September at the time of the profit warning, which was blamed on “operational efficiency issues” in North America.
Those issues have cost the company c. £18m of operating profit in 2024. A trading update posted only yesterday by TTG confirmed that profits for 2024 would be at the lower end of the range they previously suggested.
Here’s the latest on the problems facing TTG:
There remains a significant management focus on the operational challenges identified in the trading update on 16 September 2024 in two North American sites. The underlying operational efficiency issues relate to an evolution of product mix over the last couple of years in both locations, and we are now dealing with specific productivity issues exacerbated by increased volumes and product complexity.
Graham’s view
I don’t see any response from TTG in relation to the VLX bid yet. Perhaps they will say that the VLX bid is opportunistic, which it is.
But I also think it’s potentially quite a reasonable offer. A 77% premium to the most recent share price is a huge premium, in anyone’s book.
However, the fall in the VLX share price today adjusts things.
As I type this, VLX is down by 12%.
The bid is 62.9 pence in cash plus 0.223 new Volex shares for each TTG share.
That’s £111m in cash plus £119m of value in Volex shares, assuming the Volex share price stays around £3. Total value: £230m.
Net debt was last seen at £127m (June 2024) so let’s call that a £355m enterprise value.
TTG’s 2024 adj. operating profit will be somewhere in the region of £37m.
We therefore get a valuation of less than 10x adj. operating profit.
Maybe that’s a good deal for VLX but I wouldn’t say that it’s a steal. After taxes and other items are accounted for, I think VLX will pay a reasonable multiple for TTG.
The counter-argument is that 2024’s profits are temporarily depressed by the problems in North America, which will be fixed sooner or later. Without those problems, adj. operating profit for 2024 should have been £55m.
TTG’s shareholders will have the final say on this. They may look at VLX’s interim results, published this morning, and feel envious: revenues +30%, underlying operating profit +27% to $47.6m, and full-year expectations unchanged.
Volex does already carry over $150m of net debt (ex. leases) and my calculations suggest that this would almost double if their bid for TTG was accepted. Volex shareholders would also be diluted by over 20%.
In summary: I think the bid is opportunistic but also reasonable.
On TTG itself I was neutral, due to my loss of faith in management. I remain neutral on it now, and I’d be inclined to accept the VLX bid.
As for VLX, this is a stock where Paul has been GREEN. I think the debt and dilution proposed today should be a cause for some concern. And if they succeed in taking over TTG, I expect that improving it will be hard work.
On balance I’m happy to leave the GREEN stance unchanged due to Volex’s track record of successful acquisitions, but I think this could be their most difficult one yet - not just in terms of getting it over the line, but also in terms of making TTG a successful component of their empire.
Record (LON:REC)
Down 0.6% to 62p (£123m) - Interim Results - Graham - GREEN
Record plc… the specialist currency and asset manager, today announces its unaudited results for the six months ended 30 September 2024 ("H1 FY25").
Some decent results here, key points:
Assets under management up 4% during the period.
Revenue down 2% year-on-year to £21.1m, in line with expectations.
PAT (profit after tax) up 5% to £5m
Trading for the full year remains in line with expectations.
Performance fees: an important but volatile contributor to profits, these fees were £1.6m in H1, slightly higher than H1 last year.
Thanks to TB in the comments for pointing out this important line in the commentary: the exceptional performance fees of £4.3 million earned in H2 FY24 are unlikely to be repeated in the second half of this year.
The “revenue by product” table shows increased fees from currency management (up £2m) offset by lower fees from Record’s “custom solutions” within Asset Management. An important client has switched over from Custom Solutions to Passive Hedging, as previously announced.
Net cash is almost unchanged year-on-year at £14m.
Interim dividend unchanged at 2.15p.
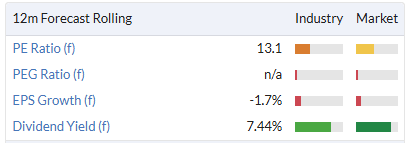
The yield here is one of its best features:
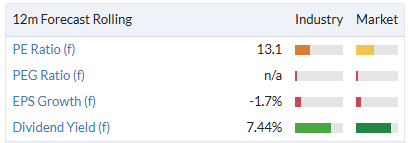
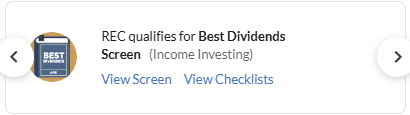
On that point, Record passes 5 bullish stock screens, two of which relate to its yield:
And turning back to the interim results, here’s a snippet from the comment by the new CEO:
We have continued to focus on delivering best-in-class solutions to clients in our six core product areas, and we are seeing increased demand for our Hedging for Asset Managers and FX Alpha products in particular. I am especially delighted to announce the launch of our Infrastructure Equity Fund. This is an important milestone in the growth of our Asset Management offering, which will deliver sustainable long-term revenues and where we continue to develop our pipeline.
Graham’s view
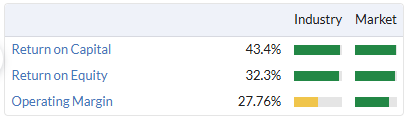
Record continues to exhibit the features that initially attracted me to it: namely high profit margins and a strong and very liquid balance sheet (net assets £28m, almost entirely consisting of liquid assets).
Quality metrics are fabulous:
The missing ingredient is growth, and indeed the loss of a client from “Custom Solutions” is a return to the old trend where Record would lose clients from its more profitable products.
A helpful note from Panmure this morning suggested that Record could earn 17 basis points of revenues on its new €1.1 billion infrastructure fund - that’s a couple of million euros in additional revenues, hopefully providing a surplus over its associated costs and with the potential to grow over time, over and above its initial commitments.
I’m going to give this stock the thumbs up with a GREEN stance, as I am a long admirer of the company and I think that even in the absence of rapid growth, it’s a nice stock to own (I’m a former shareholder).
Additionally, I’m intrigued to see what their young new CEO might achieve. He’s an internal hire who has been with the company for his entire career. Perhaps he will bring a fresh approach to an old, respected name?
Megan's Section
Solid State (LON:SOLI)
Down 48% to 110p (£121m) - Trading Update (profit warning) - Megan - AMBER/RED
It’s never a good sign when a company is forced to issue a trading update just 9 days after the last one. This morning, Solid State (LON:SOLI) has announced that revenue from a major defence programme has been delayed. Financial results in the year to March 2025 are therefore expected to be materially below current expectations.
Solid State supplies electronic components to industries with complex demands. In 2024, the defence sector contributed 44% of sales, with 20% generated directly from NATO sales.
Today management has suggested the order delay is a result of the UK government’s strategic defence review, that has forced customers to pause orders pending completion of the review, which is due next summer. As a result, management cannot currently be confident that the order delays won’t impact sales in the 2026 financial year.
Chief executive Gary Marsh commented:
"While the current delays in receiving orders are frustrating, our relationships with the Forces and key defence prime contractors underpins our confidence in the Group's position within this sector. The Board remains optimistic about the medium and long-term outlook for defence spending given the current geopolitical climate.”
Megan’s view:
When Graham covered the company’s trading statement last week, he downgraded his view from green to amber/green. His rationale was that earnings momentum had stalled slightly, and shares were starting to look prohibitively expensive.
I agree with that view. Although Solid State has been a phenomenally high performer since it listed on AIM in 1996, a weakening of momentum is definitely a reason for concern.
The company’s over-exposure to sectors highly impacted by geopolitics also merits some caution. Customers in hard-to-access sectors like defence are reliable and sticky in good times, but one-off events (like today’s one) can cause material disruption. Management had flagged this in 2024 financial results and continue to aim to balance out defence sales from private industrial sectors, most noticeably medical.
It’s likely that the revenue from key defence programmes has only been delayed and Solid State will recoup that in subsequent years, but for now it is unclear how long the lower demand will last.
While today’s whopping share price fall might look tempting, given the quality of this company, we have written before about the perils of buying on a profit warning. This feels like a prime example of a company whose troubles might not yet be behind it.
I am minded to downgrade our view further awaiting more clarity when the company issues its interim results in December. AMBER/RED
Nexxen International (LON:NEXN)
Up 7% to 313p (£389m) - Q3 2024 Results - Megan - AMBER
Last week I covered digital advertising agency S4 Capital (LON:SFOR), whose results pointed to the challenging market conditions facing companies in the sector. Analysing numbers from Nexxen International (LON:NEXN) this morning is like night and day. This is also a digital advertising platform, but its specialist field is CTV (“Connected TV”) where its expertise means demand is soaring.
Revenue in the third quarter was 13% higher than the same period last year at $90.2m. The company has also swung back into an operating profit and reported net margins of 23%.
On an adjusted EBITDA basis, management has raised its guidance for the full year from $100m to $107m and has announced an acceleration in spending plans in the world of data and AI.
The company’s performance in the last year has not gone unnoticed by shareholders. The shares have outperformed the wider market by 76% and are currently trading well above their 200 day moving average.
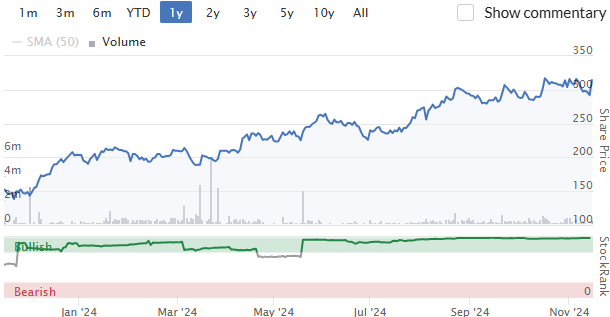
However, long-term holders are still not back in the black. The share price fell off a cliff in late 2021 after acquisitions widened the net debt position and revenue growth disappointed, but numbers today bring reassurance that, operationally, things are on the right track.
And it’s not just the operational performance that has supported shares this year. Management initiated a $50m share repurchase scheme in May and followed this up with another $50m repurchase scheme in October. The average number of shares in issue has fallen to 141m from 153m at the end of 2022.
There are still some red marks though. Receivables remain worryingly high at $201m - more than the revenue reported in the period. That suggests the company’s customers are not good at paying bills in a timely manner.
The company also insists on heavy adjustments in its own reporting. On an underlying basis, profits have been far from consistent.
Megan’s view
Today’s numbers are encouraging and the approval of another buyback scheme should give further support to the shares for the next few months.
In December, shareholders will be given a vote on a proposed delisting from AIM in favour of the more tech-savvy Nasdaq market. This feels like a more appropriate market for the Israel-based company.
For long-term investors, there are too many unknowns. For those looking for a short uptick in momentum, the trend of the last few months looks like it has further to go. AMBER
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

96 comments
Noticed Liontrust Asset Management (LON:LIO) on the top risers table today volume currently double the daily average , was rumors last year of a merger with Artemis but nothing came of it just wondered if anyone knows anything or if its just punters trying to pick the bottom ?
Trouble is - nothing makes sense these days. Divi now 17% ? and to top it all - its a Friday. Too cold to go down to Bookies today, so this is next best - Half year figs due Thursday 21st -
That must be it then people buying in hoping the outflows won't continue to be as bad as previous , I have a feeling they will be disappointed hopefully I am wrong.
Volex (LON:VLX)/TT electronics (LON:TTG) - And now a response just released this afternoon from TT
The TT Electronics Board confirms that on 31 October 2024, the Company received an unsolicited conditional proposal from Volex to acquire the entire issued and to be issued share capital of the Company for 62.9 pence per share in cash and 0.223 new Volex shares for each TT Electronics share (the "Volex Proposal"). Based on Volex's closing price of 325.0 pence per ordinary share as at 31 October 2024, the Volex Proposal valued each TT Electronics share at 135.5 pence.
On 7 November 2024, the TT Electronics Board, having carefully considered the Volex Proposal together with its advisers, unanimously rejected the Volex Proposal as fundamentally undervaluing TT Electronics and its long-term prospects.
The TT Electronics Board also announces that it has recently received and rejected an all-cash indicative proposal from another party at a significantly higher value than the Volex Proposal. There are no ongoing discussions with this party.
Yet again - issues with why this was not declared days ago
TT electronics (LON:TTG) Volex (LON:VLX)
Agree : I cannot see why this wasn't disclosed to the market from the initial approach - surely it should have done given the 70% premium and (I presume) a serious bidder. Also:-
"The TT Electronics Board also announces that it has recently received and rejected an all-cash indicative proposal from another party at a significantly higher value than the Volex Proposal. There are no ongoing discussions with this party."
So a bigger premium and all cash and we only learn this when Volex (LON:VLX) forces their hand with their lower bid.
The London market is seriously broken.
A.
Annyone know why OPG Power Ventures (LON:OPG) are down 21% today? Can't see any news
Maybe this notice of investigation?
OPG Power Ventures (LON:OPG)
There is an announcement.
All the best
Excellent news, argh, thanks!
I await Graham's update on Record (LON:REC) (I hold). Looking at the numbers today, costs slightly up with no real movement in AUM compared to the end of June, although they are reporting versus the prior H1.
If my maths is correct, $0.5bn of outflows in Q2, $0.1bn of FX gain and $0.9 gain from Market Movements.
The last 2 years they have earned significant performance fees in Q3, £3m in Dec-22 and £3.5 in Dec-23. However, buried in the 'Interim Management Review' underneath the revenue by product table is the following;
'We continue to see opportunities for earning performance fees in some of our Passive Hedging mandates, with £1.6 million earned in the period compared to £1.5 million earned in H1 FY24. However, the exceptional performance fees of £4.3 million earned in H2 FY24 are unlikely to be repeated in the second half of this year.'
Performance fees per annum
Looking at FY25 on the stock report, i think they are being a bit conservative on the revenue for 2025, if history is anything to go on and AUM stay at a similar level, i think revenue will be in the region of FY24 and FY25 even with the lower performance fees, with PAT being in the region of closer to £10m than the £9m quoted on the stock report. However on 12x it appears reasonably priced around 65p per share.
Is Volex going to be covered today? I don't see it marked up for review despite its popularity here? Many thanks.
VLX has just been written up - hope it's helpful. G
Thanks Graham looks like we crossed!
Hi
Here is a precisely articulated presentation of why April 2025 is going to be a really bad time for the UK.
An especially bad time for 50% of the working population who do not work in large businesses or very small owner managed business of two or three people.
The risks lie very heavily with people-centred businesses such as NHS, hospitality, child care, government, house and commercial builders, the list goes on and on.
I think it is worth a viewing the presenter is very good at analysis and presentation. The structure is the issue, the impact, the action required by government (which they will fail to do I suspect).
Net outcome is high unemployment in the UK.
Regards
Howard
Not usually a fan of these videos as there is usually an angle, but he seems very balanced and makes some great points..
Looking forward to the day when the light at the end of the tunnel doesn't turn out to be an oncoming train.
I thought this presentation was a little simplistic. An alternative outcome to mass unemployment is a bout of inflation that protects company profits but neutralises the spending power of individual consumers. My voluntary activities see me managing a medium sized social enterprise that, to all intents and purposes, is a not for profit hospitality business (it’s a renowned music venue with a strong progressive political background and my capitalist presence on the board is extremely anachronistic). We are in no position to offload staff, being under-resourced as it is. And despite being relatively unaffected by the erNI change, thanks to the increase in employer’s allowance, I’ve calculated that we need to raise our drinks prices by 10% to compensate for the 5% input cost inflation that I see coming down the line.
Amid the criticism of Rachel Reeves, I think it should be remembered that the outgoing Tory government laid a fiscal trap for the incoming chancellor by cutting employees NI by 2%. If anything tangible is represented in her £22bn “black hole”, then it is this wilfully destructive bit of party politics by the charlatans that hollowed out our public services and divorced our main trading partner. The rise in erNI is simply an attempt to recoup this glaring loss to the public purse. If it results in lower wage rises then it simply puts employees back to where they were before Hunt’s parting fiscal gambit.
Out of interest BnB is the increased employer ni allowance allowable against each member of staff or for the business as a whole regardless of number of staff members and business turnover ?
For the business as a whole
Thanks BnB so if I have it right as an example for someone like Tesco who has say 10,000 employees assuming all earn over the new lower employer nic limit for 25/26 £5k gross per annum ish from memory they will be allowed an increase in employers ni allowance of £5,500 in total which will offset the increase for about ten members of staff only ? (rough numbers but I think I have the jist of it)
Regards
Andy
That’s roughly my understanding, Andy. I believe it covers about 9 employees earning over the lower earnings threshold - it’s a c.£610 increase per employee and the allowance has increased by 5.5k.
Employment allowance was upped from £5k to £10.5k. Previously your total wage bill had to fall below £100k to qualify, but they will be removing this cap.
It will offset much of the NI increase for small businesses with up to 10 employees but after that it's a big hike.
I stepped in to hold the fort between permanent financial controllers for a charity recently, and you could see the Employment Allowance was offset from the Employer NI bill over the first 4 months of the year. Whether that was a function of how the outsourced payroll provider processed things or how HMRC spreads it out it I don't know.
I stepped in to hold the fort between permanent financial controllers for a charity recently, and you could see the Employment Allowance was offset from the Employer NI bill over the first 4 months of the year. Whether that was a function of how the outsourced payroll provider processed things or how HMRC spreads it out it I don't know.
Thats how it works - basically you start the new tax year with 5.5k in the bank to draw down on - if employers ni bill is 1375 per month - you deduct 1375 each month from the 5.5k pot and pay no employers NI that month. When the pots gone you start paying the employers NI in full.
Many thanks for the extra clarity it does look like being a big headwind for any medium and large retailers, plus also the big financial services companies moving forward.
Many thanks BnB appreciate your input as Paul S said previously this is the killer where the billions in the budget will be raised.
The likeS of the big supermarkets with thousands of employees a lot of them part time probably earning 8 - 15k is going to cost them low hundreds of millions extra per year which means food inflation is heading back up for the rest of us.
Your not far from being spot on The Phoenix - as BNB has quoted for all employees paid over 9.1k its £620 extra cost PER EMPLOYEE - plus 1.2% of salary over £9.1k too on top of the £620
against this they are given back £10.5k - so that will probably cover the cost for 15 low paid employess out of the 10,000 - for other 9985 that have to pay then extra "per employee wad"
Note they score for 10.5k ref allowance claim as previously their large NI bill would have prevented them making any employment allowance claim - so they (unlike smaller companies) would NOT have claimed the £5.5k in place for smaller employers previously
Assuming they are making profits they they will pay less corporation tax @ 25% so c£465 per employee not £620?
How much did you have to pay for your username? -:)
All the best
You've lost me Yiannos?
Admittedly, I was clutching at straws earlier, but was just meaning that EPS wouldn't be reduced by the full amount of the NI rise.
Nothing like that!
Kouremenous is exactly the same as Κουρεμένους in Greek!
All the best
It's a very small village in Crete. Delightful place with the most warm and generous people :-)
That’s Kouremenos though?
What a chump I've been. Not only have I spelt my user name wrong but I also named a boat I owned with the wrong spelling!! Hey ho :-)
What does Κουρεμένους mean?
Hopefully nothing offensive :-)
A rather sad story for many GreekCypriots.
During the 2010-2103 Greek financial crisis, all deposits in Cyprus were cut to £100K in one of the major banks (Cyprus Popular Bank)-even if you had €10m you were left with 100K. Also all bond holders lost entirely their money.
The whole procedure was called a haircut.
Kouremenos is someone that had a haircut.
Kouremenous is the plural and that’s what all these people are called.
All the best
As you say, a very sad situation. Thanks for the explanation. Cheers
But if they increase their prices to maintain profits the tax bill will be the same. Hence inflation goes up and the consumer pays.
Agree strongly with your final paragraph BnB. If only Labour had not boxed themselves in by matching the Tory promises on tax cuts including that promise not to increase employee National Insurance. Those Tory tax promises were so easy to make when there was such a low chance they would win the election.
I bet Rachel Reeves wishes now that they had done the obvious in the election campaign and said that the NI cut just before the election was an unaffordable election gimmick that unfortunately they would have to reverse. That would have raised £10 billion! Fuel duty (with petrol down from a peak £2 to around £1.40) could have raised another £5 billion.
That would have meant manageable tax increases for businesses instead of the punitive ones which at a stroke ruined all their efforts before the Election to show they were business friendly.
Ken, as you say this would have been the simplest and most effective solution to address a large % of the infamous £22bn 'black hole'. Removing the two pre-election employee NI cuts could have been 'sold' to the electorate quite easily. It was a Tory bribe in the hope that it would win votes - it didn't work so reverse it! Also your point about fuel duty is also fair comment. Reeves and the Labour Party have made a serious strategic error, one of many I fear, which will come back to haunt them - though perhaps not to the extent described in the above video!
I wouldn’t take notice of anything this guy says or writes.
Print , print , print is his logo.
All the best
"I wouldn’t take notice of anything this guy says or writes."
I agree, the guys a hardcore MMT crank. Once he'd eventually led us into a depression he'd then complain central banks/politicians hadn't done it right and it was nothing to do with him.
Wolfie he is a proven lunatic.
Really worrying that 25+ gave a thumbs up without knowing what he represents.
All the best
So what are folks doing with TT electronics (LON:TTG) and Volex (LON:VLX) today - I have both. Sell TT and buy more Volex ?
If I held TT electronics (LON:TTG) I would sell into the strength in the price created by the Volex offer. Just my view. There is of course the outside chance of a bid from another party, who knows?
As for Volex (LON:VLX) I have a full sized position and shall sit on my hands. Nat Rothschild holds 25% of the company and has never sold a share so despite his wealth is fully aligned with shareholders.
I do hold both but more in Volex (LON:VLX) 135p is not a bad offer but l'm hoping for a better one, 140p would be acceptable to me. Tempted to top up Volex (LON:VLX) but will wait.
As of this morning Solid State (LON:SOLI) has just become available (as a takeover option) to Volex (LON:VLX) if the TT electronics (LON:TTG) deal does not conclude....
Volex (LON:VLX)
Well one can’t accuse Nat Rothschild of lacking ambition. TT electronics (LON:TTG) has been a basket case, despite the fact that it should be a beneficiary of the move towards electrification. Over time I would expect the management at Volex to sort out the mess that is TTG, although as a holder of the former I would prefer them for the time being to focus on the continued integration of Murat Ticaret.
The share is bouncing around and is down around 10% much of which I suspect is a result of the offer for TTG that I would leave to stew in its own juice.
Agree - I was kicking myself with a small holding in TT electronics (LON:TTG) and nearly sold yesterday, which I'll hold for now. However Ive taken opportunity to top up Volex (LON:VLX)
Can’t argue with your approach bohenie, best of luck.
The only comment I have is a vague memory of one AIM company trying a hostile bid for another AIM company. It didn't come off, and probably chewed up a lot of adviser fees. Can't recall the name of the parties.
That said, it may come down to the structure of the shareholdings in TT electronics as to how nervous the Directors should be. Would imagine there will be a bit of back channel contact from either party with their principal holders
Duke Capital (LON:DUKE)
For anyone interested…I was logged into my account earlier and so had a quick look. You could easily buy in the market lower than the 27.5p placing price. I was offered 27p. So may be no need to hassle your broker about the retail offer.
Yes, I took the opportunity at 27.1p although Interactive Investor (as often happens) scaled back the number of shares I was able to buy, despite having sufficient funds.
I also acted on the read across from Solid State (LON:SOLI) and took some profit on Cohort (LON:CHRT) and see it has come away 5%, using the funds for a quick relief rally profit on SOLI. I don't normally trade but the fall looked too deep.
Just want to say thanks to Graham and the team. I'm really enjoying the diverse coverage of larger, more stable and more liquid businesses.
You're welcome Acorn! We're only getting started :)
Tekcapital (LON:TEK) The Executive Chairman may be interested in the company's owners, "...we look forward to keeping shareholders updated with the anticipated progress of our other portfolio companies...", however he appears to ignore those who are retail investors when conducting a fund raising, according to today's announcement.
Chris I sold them for this very reason a while back. They have listed shares they could sell but choose instead to issue new shares constantly and ignore the retail base.
Does anyone have a view on Altitude (LON:ALT) ? It has fallen 15% today on an (admittedly slightly anaemic) in line trading update. I hold.
Hi Graham, Megan,
MJ GLEESON (LON:GLE) have updated the market today, in-line but rather uninspiring:
[I do not hold]
It's a bit of a shock seeing companies with updates and news on a Friday!
Best wishes,
TEIN
Very glad I sold my holding in Solid State (LON:SOLI) back in 2021 & 2022 at a reasonable profit though did miss out on subsequent share price rises. This morning profit warning and share price crash attributed to delayed defence orders. Is there any read across to yesterday’s poorly received results from Qinetiq (LON:QQ.) which saw the share price fall 9%. Also see BAE Systems (LON:BA.) is a little weak in last few days. All this seems counterintuitive given the prevailing view that Trump is good for the European defence sector. It would be great if analysts at Stockopedia could look at the recent news/results from companies in this sector.
Solid State (LON:SOLI) follow the directors, you won't go far wrong, interesting history of directors trades and the share price.
Rolls-Royce Holdings (LON:RR.) are off as well. If the war in Ukraine does end how will that affect defence companies? Cohort (LON:CHRT) still going well, next update in 4 weeks time.
Hi Rusty2. I agree with your 'follow the directors ' comment. For me, it is always a red flag if there are sales and no specific reason, i.e. tax/retirement etc.
For your RR comment, I have played knife catcher on this roller coaster for five years and largely bought it because of the SMR ( nuclear ) story. I think that rationale still holds for me, plus air travel back
Good luck
personally I sold my Cohort (LON:CHRT) , it's had a very good run but with the uncertainty surrounding defence and the (very) round number which often brings sellers I sold just above £10
Yes l know what you mean about round numbers on Cohort (LON:CHRT) l'm in 2 minds. I don't really understand why defence stocks are struggling a bit recently.
Robbie Burns is quite bullish.
Surly European allies will have to up their spending seeing as the US will reduce their contributions?
Yes European but British? Thought we were already up to level of spending?
If the wars do cease then some orders will be cancelled?
You could be right, with Ai though will everyone be looking to upgrade to the latest and greatest kit?
I suppose there could be extra tariffs on UK companies exporting so plenty of unknowns. I am in MSI with has been hoovering at around £10 for a while. Will wait on next update and go from there.
MS International (LON:MSI) up 10% earlier this week, down 10% today. Madness of AIM
Graham, I think you need to amend the headline on ConvaTec (LON:CTEC) . The shares were up a smidgeon yesterday (not sharply down as reported). The 'key product' accounts for just 4% of total sales and this after hours setback last night has only sent the shares 1% lower this morning.
ConvaTec (LON:CTEC) were down yesterday, according to both my brokers, HL have it down 3,5%. Hope you are not using Stockopedia share prices.
Ahhh yes, Rusty. Apologies. They were down 3.5%, as you say, but this was after about an 18% rise on Tuesday following a strong trading update. Therefore, I think the headline is rather misleading. I don't hold, but I just wanted to point out that the outlook for the company looks somewhat better this week rather than worse.
Hi Sparkler,
Thank you for pointing this out, you're right, overall it has been a positive week for ConvaTec following the trading update on Tuesday.
I suppose my concern (and the reason for describing InnovaMatrix as a significant product) is the fact that ConvaTec has sunk a lot of money into this treatment. InnovaMatrix was an important driving force behind the $450m acquisition of Triad Lifesciences back in 2022 and since then the company has invested a lot into further clinical trials.
Overall though, you are right shares have had a pretty good week following the earnings upgrade announcement on Tuesday.
Hope update from Nexxen International (LON:NEXN) gets covered here today:
Raising full year 2024 Adjusted EBITDA to approximately $107 million from approximately $100 million.
$166.5 million cash.
Approval to launch a new $50 million Ordinary Share repurchase program which is expected to begin on November 19, 2024 and continue until May 19, 2025 or completion.
Delisting from AIM and moving to Nasdaq where similar companies are valued much higher than Nexxen International (LON:NEXN)
Good morning Graham. I think there was some writing on the wall about Duke Capital (LON:DUKE) . The fabulous 9% divis were well covered in the past few years, at 5.5x, 2.5x and last year 1.75x, but this year they are at 1x, so it was hard to see how this could continue.
re: DUKE
Thanks very much for the comment Andrew, I see what you mean - the calculations on the StockReport (EPS/DPS) do indeed give the dividend cover numbers you suggest.
Interestingly, the free cash flow figures given by Duke paint a different story.
For FY24, DUKE reported free cash flow of £17.9m, with free cash flow per share of 4.34p. They paid a dividend of 2.8p per share.
So we can get a different answer depending on whether we use cash flow or earnings to find dividend cover. My sense is that they didn't have to raise money here - they could have just slowed down on their investing activities, and let existing free cash flows pay the dividend. But ultimately, they want to be a bigger company than they are right now.
Really don't know this one but on quick glance the return on capital looks low to me and spread of return over finance cost not so clear.... so the market has pushed the equity to a discount to manufacture a better equity return from the situation. Intuitively I would have thought this was an opportunity rich area but it isn't reflected in the numbers. Their own borrowing costs seem prohibitively high.
This type of strategy dents confidence in the business in my view. If you are going to offer discounted shares to yourselves and mates and not existing shareholders it creates an unbalanced surprise, who knows what they will do next. Divi cuts on the cards, who knows… very disappointing.
Two thoughts on this. Firstly, none of us knows if Duke needed the money urgently because of an opportunity with one of their investee companies. I guess it could be some time before we find out.
As for existing shareholders not sharing in the cheap shares on offer, the market provided just such an opportunity today. I added at 27.12p
Re: Duke Capital (LON:DUKE)
I have a small position, of which i sell down a bit of every now and then.
This management team treats our equity as confetti! The number of shares in issue (approximately as i am using Stocko numbers) has gone from about 177m in 2019 to 477m now.
The share price has gone from about 45p in 2019 to about 29p now.
Someone ought to give them a lesson in Economics 101, greater supply=lower price!!
This thing will go nowhere for the next 5 years if they keep doing this.
ChrisW, I understand your pain but I do think it's important to point out that DUKE management have been very clear about their desire to grow to a much larger scale - that won't be possible without printing shares from time to time! If they had issued at something much closer to 40p (let's say 36p+) I think that would have been reasonable. 27.5p is just too low IMHO.
Graham indeed, i should have spotted the comment "Grow to a much larger scale". That of course doesn't necessarily include any benefits for shareholders, which is what is happening.
I hope they are paid no more than 5 years ago, so that we are all in this together!!!
P.S. TEKCapital are the ultimate offenders in not recognising that equity capital is precious!!
P.P.S. Compare and contrast with Next (LON:NXT) !!!
And just to wrap this up, the CEO's compensation in 2019 was about £245/- , in 2014 it was £783/-.
He's not sharing the pain is he?
I don't think their advisors are either, nice work for Cavendish (FinnCap as was)
There is research today on Duke Capital (LON:DUKE) on Research tree for those interested
If they can invest adding to the Royalty income and maintain the dividend, then it will remain good income stock
Volex (LON:VLX) making offer for TT electronics (LON:TTG)
Fabulous HY results this morning from Volex (LON:VLX) . Surely the SP will rocket today and level-off at a price which makes their part cash/part shares offer more enticing to TT electronics (LON:TTG) ?
Volex (LON:VLX) is down over 5%. Make that now 10%, the market does not like something, not studied them yet.
Wouldn't call them fantastic - EPS growth of 2% looks pretty pedestrian at first glance.
Well I read that one wrong! They've rocketed in reverse gear. I guess the news about the rejected TT bid has massively outweighed their strong HY.
Higher debt, eps barely moving and a bid for TT electronics (LON:TTG) (that serial underperformer) . Hardly a recipe for a rising share price.
Net finance costs increased to $12.0 million from $5.4m a year ago. Not insignificant given operating profit is $11.7m!
H1 operating profit was $36.6m
Volex (LON:VLX) Where do you get $11.7m from?
Bit of a surprise from Solid State (LON:SOLI) Solid State plc (AIM: SOLI), the specialist value added component supplier and design-in manufacturer of computing, power, and communications products, announces a trading update following receiving news of an expenditure delay regarding certain potential defence orders.
I hold Qinetiq (LON:QQ.) which reported yesterday with no mention of delays but the share price did sell off in the afternoon. (I hold QQ.)
Look out for possible warnings from others in the defence sector following the delay at Solid State (LON:SOLI)
I think that's a good point about the defence sector and disruption to orders. I suppose with some of the larger contractors, orders are more international and so less disrupted by UK government spending, but it will definitely be worth watching out for any announcements from other defence companies.
Graham and I will be talking about sectors impacted by recent geopolitical upheaval in our webinar next week. Defence will definitely be something to look at - a hot sector based on what is going on in the US, but reasons for caution as indicated by SOLI today.
Hi Megan,
Just made a comment on thread before I saw your contribution! Look forward to any work on defence sector.
Tiddler Rosslyn Data Technologies (LON:RDT) ties up a partnership with Top 5 consultant:
Partnership with Top 5 global consulting firm
Rosslyn (AIM: RDT), the provider of a leading cloud-based enterprise spend intelligence platform, is pleased to announce that, following extensive negotiations as previously announced, it has now been awarded a contract by the US-based entity of a leading global consulting firm (the "Consulting Partner") to establish a centre of excellence to enable the Consulting Partner to best utilise the Rosslyn solution to deliver value for customers. In addition, the Consulting Partner intends to recommend Rosslyn as its preferred supplier, and the Company is pleased to also announce that it has secured its first customer (the "Customer") via this partnership. The contracts with the Consulting Partner and the Customer have a combined value of £520k over three years, with the contribution to revenue in the current financial year being c. £185k.
https://newsfile.refinitiv.com...