Daily Stock Market Report (Fri 16th Jan 2026) - POLR, GLE, SPSY, CCT, JSG, POS

Good morning!
Relieved to reach the end of a busy week for the daily report! Have a great weekend everyone.
Spreadsheet accompanying this report: link (updated to 16th December)
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our View (Author) |
|---|---|---|---|
Ninety One (LON:N91) (£2.1bn | SR84) | AUM at 31 December 2025 of £159.8 billion (30 September 2025: £152.1 billion; 31 December 2024: £130.2 billion). | ||
Genus (LON:GNS) (£1.75bn | SR56) | H1 adjusted PBT tax of approximately £50m, which is ahead of expectations. Including a milestone payment, adj. PBT is £55.6m. The Board now expects FY26 adjusted profit before tax (excluding the milestone payment) to be moderately above the top-end of current market expectations (£82.7m to £85.0m). | ||
Bodycote (LON:BOY) (£1.33bn | SR85) | Acquires Spectrum Thermal Processing, an Aerospace and Defence focused heat treatment provider based in Cranston, Rhode Island, for a cash consideration of approximately $8m. | ||
Impax Environmental Markets (LON:IEM) (£775m | SR) | Reaction to Saba, their largest shareholder, “in response to Saba's relentless pursuit of short-term objectives at the expense of IEM and the wider UK investment trust sector.” If Saba does not tender all of their shares under this “Continuation Tender Offer” (to be approved by a special resolution), it will be cancelled and an “Exit Tender Offer” (to be approved by an ordinary resolution) will be proposed instead. | ||
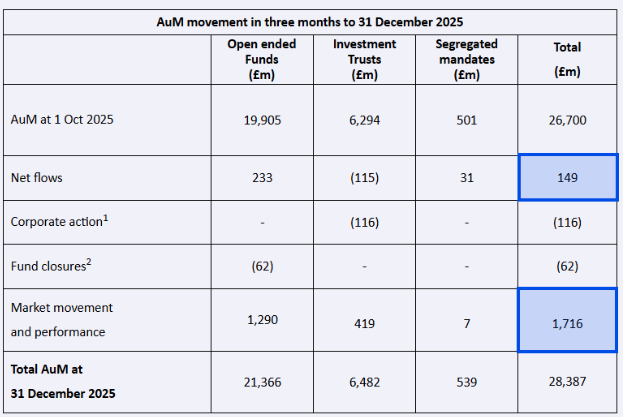
Polar Capital Holdings (LON:POLR) (£599m | SR96) | 31 December 2025 AuM was £28.4bn compared to £26.7bn at the end of September 2025 (+6% over the quarter). Fund performance and market movements of £1.7bn and net inflows of £149m, offset by fund closures of £62m and a £116m return of capital. | GREEN ↑ (Graham) Happy to upgrade my stance on this after a quarter of net inflows, excellent performance fees, and the landmark announcement of a £15m buyback. | |
Johnson Service (LON:JSG) (£535m | SR53) | 2025 revenue +4.3% to £535.6 million. Organic growth 1.4%. Adjusted operating profit growth in line with market expectations, and an improved margin heading towards the 14.0% target. On track towards achieving the targeted margin of at least 14.0% in 2026. | AMBER = (Graham) [no section below] Barring Covid-related disruption to the hospitality sector several years ago, this linen and workwear provider has typically been a solid performer. ROE and ROCE have been good if unexceptional, and EPS forecasts have been sturdy. Today’s update maintains that track record. While investors wait for profit margins and/or the valuation to improve from the current 10x P/E multiple, they are at least enjoying a 4% yield to pay for their time. Sustained buyback activity has also been juicing annual EPS. Given £112m of financial net debt and moderate top-line growth, I’ll cautiously leave us neutral here for now. | |
MJ GLEESON (LON:GLE) (£225m | SR54) | Results for the full year will be in line with current market expectations (FY June 2026 PBT: £24.3m). For H1, will report the sale of 848 homes, c. 6% more than H1 last year. Demand for new homes remained subdued but steady; expect to see an improvement in open market sales through Spring. | AMBER ↑ (Graham) Upgrading this housebuilder to a neutral stance on the back of an "in-line" update with very encouraging forward-looking metrics, and with exciting EPS forecasts in place for FY27 and FY28. This is cheap against its balance sheet and against forecast earnings at the current share price. But I'd like a little more hard proof before taking us back to a positive stance on this one. If you think I'm being a little too cautious, please do bear in mind that this stock issued two profit warnings last summer! | |
Avation (LON:AVAP) (£88m | SR41) | Twelve-year lease agreement for a new ATR 72-600 aircraft with Cambodian Airways. Scheduled to be delivered new in October 2026. | ||
Spectra Systems (LON:SPSY) (£76m | SR71) | Cartor Security Printers (as part of a consortium) wins HMRC contract for production and supply of vape duty stamps. Estimated value £38.4M ($51.84M) including VAT over five years with an option for an additional year. Spectra expects approximately 15% of the total five-year revenue. | AMBER = (Graham) [no section below] 15% of £38.4m is £5.76m, and if we assume an additional year perhaps the value of the contract to Spectra is £7m. Putting it another way, the annual value of the contract is £1.15m. So it’s good news but I’m not sure that it moves the needle massively against forecast group turnover for 2026 of £28.5m. I remain neutral on this one after earnings were downgraded last year. | |
Character (LON:CCT) (£42m | SR49) | Trading conditions remain challenging. LfL sales in four months leading up to Christmas 2025 were down c.11%. H1 sales will be down year-on-year but revenue for the year as a whole to be in line with last year's full year outcome. Due to the mix and enhancements, adjusted PBT will more than double. | AMBER ↑ (Graham) [no section below] | |
Plexus Holdings (LON:POS) (£12m | SR17) | “While our reported results reflect a deliberate investment phase following an exceptional prior year, we made solid operational progress.” | AMBER/RED ↑ (Graham) The latest forecasts from Cavendish suggest we'll see £9.4m of revenue in FY June 2026, generating an adjusted PBT around breakeven (£0.2m). The following year, it's expected we'll see revenues of £11.8m and adjusted PBT of £0.7m. I'd put a wide range of uncertainty around these but even so, the situation is not quite as bad as I thought. Cash at June 2025 was £2.5m, and the Chairman has lent the company £2m since then (at an 8% interest rate). It still looks very high-risk, but I don't think a fully RED stance is justified on the basis of this cash position and the earnings forecasts. | |
Cellbxhealth (LON:CLBX) (£11m | SR7) | Q4 and full year 2025 revenues of approximately £0.4 million and £1.4 million respectively. Cash £7.3m. Reducing costs at all levels, voluntarily delisted from OTCQX. Rationalising its operations at Guildford into one facility. |
Graham's Section
Polar Capital Holdings (LON:POLR)
Up 6% to 628p (£638m) - Aum Update - Graham - GREEN ↑
Polar Capital Holdings plc…, the specialist active asset management group, today provides an update in respect of the three months to 31 December 2025.
It’s very pleasant to see inflows and rising AUM at this asset manager.
The net flows are pretty small (£149m), but anything positive is to be welcomed. Note that they are overwhelmed by positive market movements of £1.7 billion:
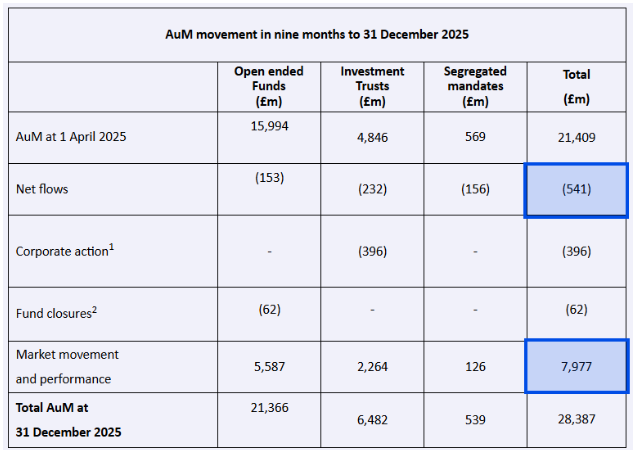
The situation is even more stark for the financial year-to-date, where net flows are negative (minus £541m) but where market movements are nearly 15x bigger and are positive (£8 billion):
Performance fees (after staff bonuses) are looking great: £16m in the financial year-to-date, versus only £7.9m in the entire previous year.
These profits were generated “by the Biotech, Healthcare Opportunities and the two Convertible Bond funds, with smaller contributions from the Artificial Intelligence, Healthcare Blue Chip and Japan Value funds.”
CEO comment:
It was a positive end to 2025 for the firm. We delivered net inflows during the quarter and performance fees crystallised above the level accrued at the end of September 2025 and the prior year. The elevated performance fee profits have supported the Board's decision to announce a £15m share buyback programme, signalling confidence in the business and reflecting our disciplined approach to capital allocation, as well as our focus on delivering long-term value for shareholders.
With a market cap well north of £600m, a £15m buyback is not going to radically change the share count, but it doesn’t hurt!
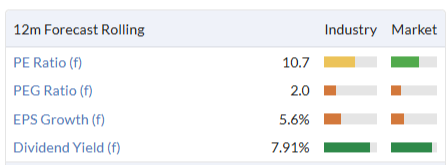
And I’d argue that a buyback is achieving decent value here:
Outlook includes typical commentary on why active management in general has done so badly:
"Although higher rates, volatility and broader dispersion would typically favour high-conviction active strategies, market leadership remained unusually concentrated for much of the year, making consistent outperformance difficult for many diversified approaches. Independent data indicates that, in aggregate, fewer than a third of active managers globally outperformed in 2025.”
In other words: the very largest companies, which have the heaviest weightings in major indices, remained strong in 2025. For active managers - who are typically underweight rather than overweight these names - this makes it very difficult to outperform.
Two-thirds of Polar’s strategies outperformed their benchmarks.
Looking ahead, “client engagement has improved, and the new business pipeline is strengthening”.
Graham’s view
I’ve been consistently positive on this one, although I did moderate my stance to AMBER/GREEN in more recent times.
While a quarterly inflow doesn’t prove that there has been a fundamental change here, I’m happy to use it as a signal for an upgrade back to fully GREEN.
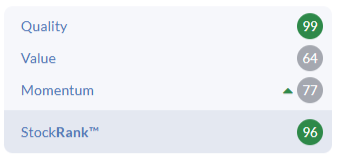
The StockRanks would approve: this is a Super Stock and one with rising Momentum:
In technical terms, this has just broken out of the range it was trapped in since 2022:
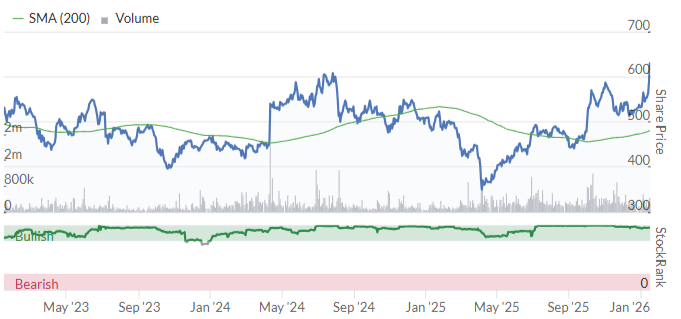
The buyback is another interesting signal, even if it’s not huge. I can’t find evidence of any previous buyback by Polar Capital Holdings Plc, only by its trust. So this decision is something of a landmark.
So while I’ve always been pretty optimistic about this one, I think the reasons for optimism today are strong enough to justify escalating my stance!
MJ GLEESON (LON:GLE)
Up 4% to 399.3p (£233m) - Trading Update and Notice of Results - Graham - AMBER ↑
It’s an in-line H1 update from this housebuilder.
Let’s see how they handled Budget uncertainty:
Demand for new homes remained subdued but steady through the Period with buyers' lack of confidence in the current economic environment compounded further by commentary during the run-up to the late Autumn Budget. With Budget concerns fading and following the interest rate cut in December, we expect to see an improvement in open market sales through the Spring selling season. On that basis, we remain confident in our forecast for FY2026.
It’s not all good news for buyers: to offset build cost inflation “and an increasing regulatory burden”, higher selling prices are planned.
Volumes: 848 homes, up 6% on H1 last year.
Other metrics augur well for H2 and for the year ahead:
Net reservation rates are up, even excluding bulk deals (from 0.44 per site to 0.48 per site).
Including bulk deals, net reservation rates have jumped from 0.55 per site to 0.75 per site.
The current forward order book is also much bigger at 978 plots, vs. 597 plots 12 months ago.
Gleeson Partnerships - launched in mid-2024, this initiative has delivered its first homes, but most housing associations that might use it are still waiting for government funding to arrive.
Gleeson Land - 15 planning applications were submitted in H1 (vs. only 2 in H1 last year).
Also, one very large land sale is forecast to go through this year, but it depends on a technical process beyond Gleeson’s control.
Net debt finished H1 at £22.5m which should be a very manageable figure.
CEO comment: reiterates the message.
We are pleased to have delivered a solid performance in a subdued market. We now expect to see an improvement in new home sales through the Spring selling season on the back of last month's rate cut, and as uncertainty in the run-up to the Budget continues to subside.
Estimates are helpfully provided on Gleeson’s website: PTB £24.3m, EPS 30.7p (giving a P/E of 13x at the current share price).
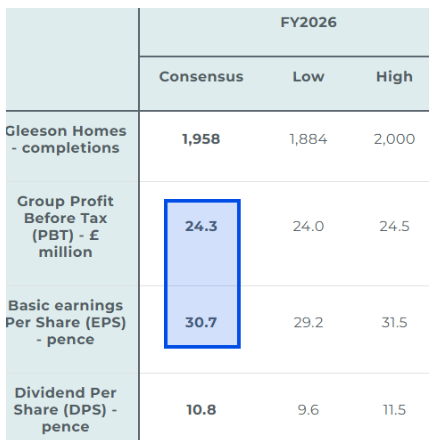
FY27 and FY28 are provided too, and they’re very interesting: EPS is expected to rise to 40.4p for FY27, and then 50p in FY28! I think I’d take FY28 estimates with a large grain of salt.
Graham’s view
This stock gave us some profit warnings last year, in June and July, and we turned cautious/negative on it.
But checking my commentary at the time, I still had hope for the medium- and long-term, due to the valuation on offer (a material discount to net asset value).
EPS forecasts have been stable since then, and today’s in-line update maintains that:
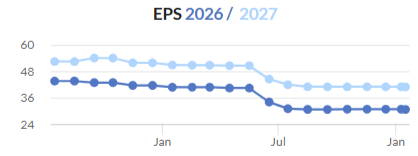
I note that the management structure was simplified around the time of the profit warnings, with regional CEOs being given more control but with the group CEO also taking on more responsibility for the performance at Gleeson Homes.
Given the strong improvement in the forward metrics (the order book and reservation rates), I have no hesitation in taking us back to a neutral stance. Perhaps I should even be more positive than that?
If you have a strong view on the housing market, and a positive one, I do think the potential value on offer is very good here:
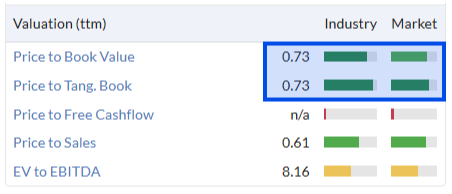
The balance sheet argument is a good one, and the EPS forecasts also suggest that it could be very cheap against earnings in a year or two.
So I’ll be happy to take this back up to AMBER/GREEN again at some point, maybe when there is a little more visibility on how the Spring selling season is going, assuming no downgrades to FY27/FY28 forecasts. Of course it might be too late by then! But for now, a one-notch upgrade seems reasonable to me.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

23 comments
Auction technology Auction Technology (LON:ATG) up 10% today with a potential higher offer at 400p up from 360p. Possible it will flush out a PE buyer.Issue seems to be a reluctant Board to engage
I know there was an awful lot of news yesterday but as it is a bit lighter today is there any chance that the DSMR team could have a retrospective look at the profit warning from Dunelm (LON:DNLM) yesterday. It was one of the biggest fallers on the day 18%+ and yet results were announced as being at the lower end of consensus forecasts. Perhaps it was the negative comments which did so much damage to the share price but such a dramatic reaction to what seems a relatively mild profit warning is worthy of further analysis.
Good morning ACounsell! Mark did take a look at Dunelm in yesterday's report (link for your convenience).
Thanks Graham - must have looked at DSMR analysis before Mark had time to review.
Character (LON:CCT) "Due to the mix and enhancements, adjusted PBT will more than double."
Why not just give an idea of the actual profit expected. These trading statements are very annoying sometimes. I'm guessing this translates to... 'we will not make an actual profit'.
Absolutely right, Compounder. Last year they made £1.1m profit (pre-exceptional items), so they are looking to make £2.2m+ this year. All well and good until you look back and see that they were making between £5-10m+ pretty consistently in prior years. I'm guessing that the toy market will always be a bit fad driven and unpredictable, but the bottom line is that right now Character (LON:CCT) is a lot less profitable than it used to be.
Spectra Systems (LON:SPSY) good to see this contract win in a new area of business for the company and supporting strength of their technology. Vaping duty stamps are to be required in the UK from October 2026. Unclear if this was in the existing forecasts, do any of the broking notes confirm?
Spectra Systems (LON:SPSY)
Spectra Systems (LON:SPSY) good to see this contract win in a new area of business for the company and supporting strength of their technology.
agreed - $50 mill is decent sized contract too - just the kind of stuff they need to keep things ticking over.
Vaping duty stamps are to be required in the UK from October 2026. Unclear if this was in the existing forecasts, do any of the broking notes confirm?
Good question - who knows - we might perhaps find out more when they sign on the dotted line and update. Note i would NEVER presume that any potential specific contract is ever factored in or not factored in or woiuld move the dial on signing. At the basic level the company will have an expectation ref revenue and profits - there may be many possible contracts and business wins - so they may not really have it in our out for most contracts. All that happens is that as contracts do firm up - they simply need to update overall position as contracts are signed or vanish from the scene and/or they do their periodic reviews. I suspect this contract perhaps might simply underpin te efuture rather than resulting in any instant upgrade. It will be useful though ref future years - having known contracts signed has make it easier ref future years forecasts - so least some scope that brokers might be able to be more positive ref the future compared to where we were before thius contract signing up - for companeis like this the market someotimes demands a nice rosy future to reward the shareprice.
what the market needs to see here is that overall they are back on track to growth post 2026 - really any useful updates need to come directly from company - or via brokers on their behalf - i await initital expectations ref 2027 numbers - thats probably te most important metric to me - when these numbers show up are they expected to be better than 2026 - thats the proof of the pudding to show that they are still moving forward overall. with p/s of 10 for 2026 - the market very much seems to be sitting on the fence at present - and i dont blame the market here.
I hold and i am comforted by contract won today
You might want to take another look at the contract details, rmillaree. It has been won as part of a consortium and Spectra Systems (LON:SPSY) share of the revenue is estimated at 15% of the total i.e. £5.76m or just over £1m p.a. So whilst it is good news, this is probably why the shares haven't moved today.
Spectra Systems (LON:SPSY)
thanks sparkler i completely missed that - doh very non material !!!
Johnson Service (LON:JSG)
Another member of my small cap portfolio. A good update in my view given that it mainly serves the under pressure hospital sector. Operating margins of 14% are impressive. Increased operating margins on better revenue, even if the latter is marginal is to be commended.
Not wholly comfortable with using debt to fund share buy backs though. Nonetheless another underappreciated UK small cap imo.
Thoughts anyone.
Turnover of @JSG at £535.6million was a bit below expectations of £540million.
Johnson Service (LON:JSG)
I hold here - its perhaps one of my weaker holdings. They seem to be a reasonably solid outfit certainly they seem to get the most out of what they do operationally albeit i suspect they are buying in profit increased (iks that a fair assessment?)- its just seems there aint much organic growth so i can understand why the shareprice is just dribbling along doing nothing. Once i see whats pencilled in for 2027 i will reavaluate.
Stocky doesnt seem to like whats up at the moment - the stock ranks have been falling for some time now - so holders have been warned by the system. Not exactly sure why as they seem to be making solid progress ref bottom line. Perhaps the fact the debt numbers on stocky moving in the wrong direction might be the issue here - i think perhaps stocky doesnt like company upping profits by acquisitions and also perhaps debt being used for buybacks. Hey ho i am weak holder and stocky seems to be saying its slightly sketchy.
I have held Johnson Service (LON:JSG) since 2017, fed it dog biscuits by doubling up and doubling down over time, now there may be just be glint of daylight in the trapdoor so I'm still hoping to come out wearing my shirt.
Polar Capital Holdings (LON:POLR)
Continues to be the pick of asset managers in my view. Its expertise in technology is a differentiator but where there is reward there is also risk, should the US tech prices deflate. Nonetheless a core holding for me at present.
Even after the share price rise this morning and Equity Development's further upgrade it trades on a p/e of around 10 and a yield of almost 8%. Their estimate also assumes zero increase in AuM in the final quarter which could be conservative.
Its ironic that Schroders (LON:SDR) who did so well just yesterday, hold near 5% of POLR
Its ironic that Schroders (LON:SDR) who did so well just yesterday, hold near 5% of POLR
It does rather look like the long awaited repricing of cheap UK fund manager and other financials is happening - M&G (LON:MNG), Aberdeen (LON:ABDN), Man (LON:EMG) , Jupiter Fund Management (LON:JUP) , Pollen Street (LON:POLN) , Rathbones (LON:RAT), Chesnara (LON:CSN) all well off their lows. Even Legal & General (LON:LGEN) and Phoenix group (LON:PHNX) showing signs of life.
You could have picked a basket of those up at a yield in excess of 9% less than a year ago.
timarr
Hi Timarr - Agreed and not forgetting Ninety One (LON:N91) which also reported today - but beware of the laggards - How can Premier Miton (LON:PMI) carry on with such a miserable record
Hi bohenie
I also hold Premier Miton (LON:PMI) and agree its performance is miserable. However, I do think these things go in cycles and their focus on small and mid-caps could very easily come back this year - or possibly next.
The main area of problems has been their European Opportunities Fund which contributed 79% of all outflows last quarter. That's partly due to the approach - mid-cap, innovative, healthcare and niche technology - which has been severely out of favour, but is now compromised by the significant underperformance driving redemptions and forced sales.
However, it is also due to poor decisions by the managers - which given the active mandate is clearly a massive problem. However, their holdings in semiconductor companies - ASM International NV (AMS:ASM), Soitec SA (EPA:SOI), Technoprobe SpA (BIT:TPRO) - and other holdings like RaySearch Laboratories AB (publ) (STO:RAY B) and Finecobank Banca FineCo SpA (BIT:FBK) - certainly could rebound.
As it stands I'd be amazed if they hold the dividend later this year, but I think it's worth a punt at these levels.
timarr
Then there's the global funds - disastrous. As I pointed out here earlier this week - you can look at the Top Ten list of holdings of a Fund Manager and think thats great - then look at the performance and its appalling. I just dont see PMI turning the corner anytime soon.
Ashmore was the outstanding riser among the asset managers yesterday. Emerging markets are gradually coming back from the depth. Infact, in 2025, after the gold mining shares, emerging market equity were the best performer, up around 45%.
I hold Ashmore (LON:ASHM) too. It's complex - you've got the Venezualan optionality in there too. I certainly wouldn't want to be overweight in it, but it's an interesting opportunity.
At some point it'll be interesting to see if City of London Investment (LON:CLIG) joins the party. The changes there are a step in the right direction, it's been a very dull albeit consistent performer.
But with fund managers eventually a rising tide floats all boats if they hang around long enough. I'd be surprised if we don't see some M&A in the sector soon.
timarr