Daily Stock Market Report (Fri 17 Jan 2025) - IGR, EVOK, MCB, CCT, EMAN

Good morning! We have a busier set of updates than usual this Friday.
1pm: all done! Have a great weekend everyone.
Spreadsheet accompanying this report (updated to 10/1/2025)
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Petershill Partners (LON:PHLL) (£2.9bn) | Q4 AUM Update | AuM raised in 2024: $32bn, ahead of guidance of $20-25bn. 2025 outlook: AuM raise of $20-25bn. | |
Big Yellow (LON:BYG) (£1.7bn) | TU | LfL store revenue +2% for Q3, +3% year-to-date. Confident in further modest EPS growth. | |
Spirent Communications (LON:SPT) (£1bn) | TU | Ongoing challenging market conditions. Full year adj. op profit to be similar to 2024. | PINK (Takeover planned at 201.5p.) |
Ninety One (LON:N91) (£910m) | Q3 AUM Update | AUM £130.2bn (Sep 2024: £127.4bn). | |
Johnson Service (LON:JSG) (£540m) | TU | Organic rev +3.8%. Op profit in line with expectations. 2025: well placed to mitigate higher costs. | |
DFS Furniture (LON:DFS) (£314m) | TU | Order intake up 10% in H1. Results for FY25 now expected to be first half weighted. | |
Evoke (LON:EVOK) (£309m) | TU | H2 sales growth (+8%) and adj EBITDA at the top end of communicated guidance. Ahead of market expectations. | AMBER/RED (Graham holds)
High-risk situation, high-reward if they successfully deleverage. |
M&C Saatchi (LON:SAA) (£218m) | 2024 Full Year TU | Revenue growth of 3.5%. PBT in line with expectations. | |
McBride (LON:MCB) (£176m) | TU | Trading in line. Annual dividends re-instated. | AMBER/GREEN (Graham)
Trading at a PER of 5x, seems reasonable to target something moderately higher than this. |
IG Design (LON:IGR) (£140m) | TU | Profit warning. Adj PBT now only expected at breakeven (from current expectations of $32m). | BLACK/AMBER (Graham)
Net cash and high NAV so I prefer not to take a RED stance. |
Character (LON:CCT) (£48m) | TU | FY25 in line with exp, despite difficult trading conditions. | GREEN (Graham)
Not trading at bargain levels and conditions remain challenging but I like the company's track record and financial strength. |
Everyman Media (LON:EMAN) (£46m) | TU | Profit warning. Box office performance in Q4 not as strong as anticipated. BoD now more cautious around 2025/26. | BLACK/RED (Graham)
Losses are pencilled in for at least the next few years and I don't have faith that meaningful profits will follow after that. |
Oxford Biodynamics (LON:OBD) (£2m) | Result of fundraising | Only £350k of the proposed £500k raised. |
Graham's Section
IG Design (LON:IGR) - down 61% to 56p (£55m/$67m) - Trading Update - Graham - AMBER
Commiserations to anyone holding this overnight, as it is down by over 50% today.
For a company that makes greeting cards, wrapping paper, and Christmas crackers, it can’t afford to have a bad Christmas. But apparently it did:
Challenging market conditions and retail trends experienced in H1 across a number of our markets have continued into H2, and they have more than offset the benefits resulting from [cost-saving] initiatives
Trading across both divisions since H1 has been impacted negatively over the important Christmas season, with DG Americas particularly affected, due to challenging retail conditions affecting customers
It sounds like a major loss of confidence at IGR’s customers, who themselves are struggling under the forces of competition. Key points:
The 4th largest customer of IGR’s American division has filed for Chapter 11 bankruptcy. “A number” of IGR’s American customers are in financial distress. IGR has made provisions of c. $15m to allow for its exposure to them (accounts receivable/inventory).
The sales performance of IGR’s products over Christmas has led to “a number” of IGR’s customers reducing or delaying forward orders.
Outlook
Revenue for FY March 2025 to be 10% below last year.
FY 2025 adj. PBT to be around breakeven, vs. expectations of $32m.
The plan to restore margins to pre-Covid levels is obviously not going to happen now. “Our aspirations will have to be re-planned and re-set”.
Most worryingly, there is no guidance for the years beyond FY25.
FY25 to include impairments at its American division. A new CEO has joined this division.
Comment by the Chair:
These developments and their impact on the Group are clearly very disappointing, and we will continue to strengthen our business model to better withstand the emerging market reality. Notwithstanding external factors, fundamentally, our business is robust and we remain focused on our strong customer relationships, and with the continued commitment of our strengthening team, we will re-map our path to stronger and more consistent delivery.
Graham’s view
The only bright spot is that IGR says it will still have “a strong net cash position” at its financial year-end, albeit below expectations.
However, they do not say what that cash position might be. Checking a broker note from Canaccord this morning, I see that they have not published any numbers for FY25, let alone FY26 and beyond. According to a note published in November, the net cash forecast for March 2025 was $105m. I think this is a post-Christmas seasonal high, but it’s still an interesting figure for a company with a market cap equivalent to just $67m.
We must write that cash balance lower by $15m for the provisions relating to distressed customers, and then write it lower again for the profits ($32m) that have failed to materialise. But perhaps IGR might still have net cash of $50m+ at year-end?
More fundamentally, what are we to make of this profit warning? This is a stock where, a year or two ago, I thought the turnaround plan made for an interesting investment opportunity, as it strove to restore margins to pre-Covid levels.
Today’s profit warning kills off the idea that we might see pro-Covid profitability again any time soon.
With impairments looming, it also provides final proof that IGR’s £90m acquisition in the United States was value-destroying. IGR raised money then at 694p per share - more than ten times the current share price - to finance that acquisition.
When I read about the US consumer over Christmas, I don’t find much evidence of doom and gloom. December retail sales were officially up 0.4% (give or take 0.5%), according to figures released yesterday. Unemployment is only 4.1%. The economy is growing. According to the National Retail Federation (AP), holiday sales over November and December were up 4%.
All of which is to say that IGR can’t point to the US economy or the US consumer as the reason for its woes. Instead, I suspect that the root cause is simply the fierceness of competition in a product category (wrapping paper, greeting cards, etc.) that is highly commoditised. IGR references “the very competitive US retail market” in today’s update.
With no forward guidance available, and since I think the root cause of IGR’s problems is that it’s struggling to compete, there is no chance that I can maintain the AMBER/GREEN stance that we've had on this one recently.
However, I also don’t want to be overly negative on it, because it may be trading at only a small premium to net cash and should achieve a result of around breakeven this year (before impairments), not a loss.
Therefore, it’s a decision between AMBER and AMBER/RED.
Checking the most recent balance sheet (Sep 2024), I see that it had tangible net assets of over $300m. The biggest items - inventory and receivables - will have to be written down to some extent. But still, that’s a lot of NAV for a company with a market cap of less than $70m.
I think the correct assumption must be that IGR will not be able to restore decent profit margins for the foreseeable future. However, I also think it’s possible that the stock offers some deep value at these levels, given the balance sheet value and net cash.
I’m therefore going to put this at AMBER for now, rather than anything lower. Existing holders have had a torrid time, but we must remain forward-looking and I’m not yet convinced that this is heading to zero.
Evoke (LON:EVOK)
Up 9% to 75.75p (£266m) - 2024 Post-close Trading Update - Graham holds - AMBER/RED
At the time of publication, Graham has a long position in EVOK.
This is “one of the world's leading betting and gaming companies with internationally renowned brands including William Hill, 888 and Mr Green.” I’m a reluctant shareholder since the pre-William Hill days, when it had a cash-rich balance sheet and the 888 ticker!
These days, EVOK struggles under the weight of an enormous debt load.
Key points from today’s update:
Q4 revenue up 13 - 14% at constant currencies (up 12 - 13% at actual exchange rates).
Online growth 18 - 19%
There were “operator friendly sports results” in Q4. This contrasts with Entain (LON:ENT) which suffered “customer-friendly” results in the US.
H2 revenue growth therefore c. 8% (previous guidance: 5 - 9%).
And there is great news on the profit front:
Strong cost control and an increasingly efficient operating model mean that adjusted EBITDA is expected to be at the high end of the previously communicated guidance range of £300-310m for the full year, and well ahead of market expectations.
Adj. EBITDA of £310m is of course a remarkable figure against a market cap of just £266m, but we need to consider the debt position.
The consensus EBITDA forecast was £294m, so we have a beat of 5% against that.
Continuing with the CEO comment:
While we were helped by some operator-friendly sports results in Q4, the significantly improved underlying momentum in the business gives me real confidence that the turnaround is working and we are well positioned to continue our growth trend into 2025.
2024 was a pivotal year as we started to implement our new strategy for success, radically transforming almost every area of the business, and moved decisively and at pace to position evoke for mid- and long-term profitable growth. We go into 2025 with improving momentum…
Graham’s view
I’ve tried to be objective about this, giving it an AMBER/RED in July after a poor H1 trading update (share price at the time: 79p).
The UK Retail division, i.e. William Hill stores, are a problem area and I remain concerned that they will drag the entire business down.
Net debt as of June 2024 was £1.7 billion. Shareholders such as myself will not be able to relax until this starts to meaningfully reduce, and this hasn’t happened yet.
Thankfully most debt does not mature until 2027, when €478m of senior secured notes expire.
Management’s plan is to grow their way out of the problem and to achieve a net debt/EBITDA multiple of less than 3.5x by the end of 2026. I guess if that is achieved, then refinancing should be possible at reasonable terms.
For now, the debt load creates a heavy interest burden which in turn impinges on the company’s ability to pay down debt. Credit rating agency Fitch has a negative outlook on their rating for EVOK, which currently stands at B+.
With net debt last seen at £1.7 billion and trailing EBITDA of £310m, we have a leverage multiple of about 5.5x. To get this multiple down to 3.5x by the end of 2026, they would need to (for example) pay off £100m of debt each year for two years, and grow EBITDA by 33% over that timeframe.
If they did, then we’d have £1.5bn of net debt and EBITDA of £400m+, and then the leverage multiple would be close to 3.5x.
Is that possible? I’ve been saying this for a while, but I still think so. I still think there’s a chance that the company can get through this narrow financial gap. These are difficult targets but they are not impossible.
Much will also depend on the attitude of lenders when the time comes to refinance, and general conditions in terms of interest rates and risk appetite.
I’m therefore inclined to leave this at AMBER/RED for the time being, to reflect the high-risk nature of these shares (Paul was RED, while I was AMBER/RED).
Fitch’s analysis makes for sombre reading and is available here.
On the bright side, if the leverage multiple does reduce to 3.5x over the next two years, then we should see a very nice recovery in the share price. But there is no doubt that it’s a gamble.
McBride (LON:MCB)
Up 18% to 120p (£209m) - Trading Statement - Graham - AMBER/GREEN
McBride, the manufacturer of private label cleaning products, is an example of what can happen when a company survives a debt scare:
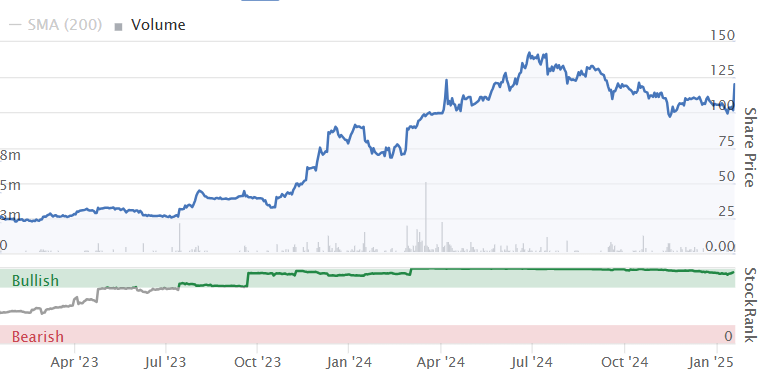
Today’s update is officially in line:
H1 adj. operating profit up 8% vs. last year, with full-year adj. Operating profit expected to be “in line with internal expectations”.
Zeus aren’t listed as a broker to McBride (link) but they do publish on it, and today they have upgraded their PBT and EPS forecast for the company by 4%, for every year out to FY June 2027.
They now suggest that adj. PBT for FY June 2025 will by £49m, rising to £52.4m for FY June 2026.
It would be much preferable if MCB put their expectations in the RNS or on their website, instead of forcing investors to play the game of chasing broker notes to see what the expectations actually are.
Continuing with today’s update:
Revenue up 2.9%, volumes up 5.9% (so average prices have fallen this year?)
Two new multi-year contracts with large FMCG clients over the past six months caused a surge in contract manufacturing volumes (up 69%).
Net debt at the end of year was £118m. Net debt to EBITDA only 1.3x. It looks to be in a safe place now.
Dividends: thanks to a new €200m credit facility (announced in November), MCB will be able to start paying dividends again. Details to be announced with full-year results in September.
Graham’s view: I was AMBER/GREEN on this at 119.7p in September and it seems reasonable to stay positive on it today as the company continues to trade well and make progress on a number of fronts.
Why not make it fully GREEN? Perhaps I should do that, but I tend to think that manufacturers (who don’t also own valuable brands) ought to trade cheaply.
For example Zeus, looking at MBC’s peers, suggest a price target of 180p which they say would be a PER of 8x. That chimes with my own view that a high single-digit P/E multiple would be a fair price for this type of business. So I do think there’s an opportunity from the current level (PER only 5x), and I am positive on it, but I’d be a seller if the PER ever made it to double digits.
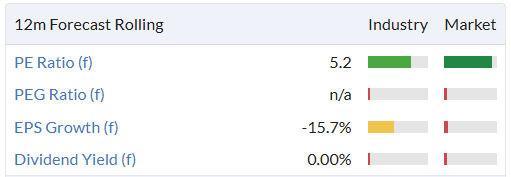
Well done to those who correctly called this and took a chance on it when the situation looked dire - they've cleaned up.
Character (LON:CCT)
Down 3% to 251p (£47m) - Trading Update - Graham - GREEN
I played with this idea of putting this on my 2025 watchlist, but instead gave it an honourable mention in my 12 stocks of Christmas.
Today the company announces an in line trading statement with respect to profitability for the current financial year, FY August 2025.
However, trading conditions “have continued to be challenging”. Sales and PBT this year are expected to be “at similar levels to those reported in the previous year”
Last year, sales were £123.4m and adj. PBT was £6.6m (actual PBT: £5.7m). Existing forecasts suggest something very similar again.
Aside from the difficult external conditions, the company itself seems to be in good shape:
Coupled with its strong stable of products for 2025, Character continues to benefit from a robust balance sheet, with a healthy net cash position and substantial unutilised working capital facilities in place.
Graham’s view: no complaints from me about Character, I like the company and I like the stock. The current £2m buyback doesn’t excite me too much as these aren’t bargain levels, but it doesn’t hurt:
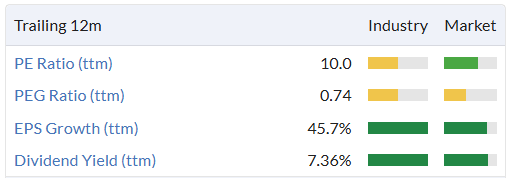
Character enjoys a StockRank of 90 and I’m going to leave this at GREEN, a reflection of its strong, tangible balance sheet, net cash position, long history of profitable operations, and its shareholder orientation as demonstrated by dividends and buybacks.
Everyman Media (LON:EMAN)
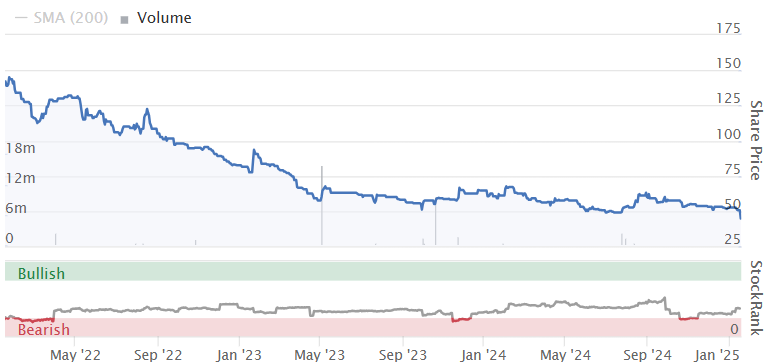
Down 11.5% to 44.7p (£41m) - Trading Update - Graham - RED
This full-year update (for a 53-week period) starts off ok, but it doesn’t mention performance against expectations:
Revenue is up 17.9% to £107.2m (but this includes new venues, so it’s not like-for-like).
EBITDA £16.1m (2023: £16.2m) (GN note: I consider this metric to be irrelevant for a cinema).
Market share 5.4% (2023: 4.8%)
Net debt falls from £19.4m to £18.2m.
Checking a broker note from Canaccord (thanks to them for publishing this), it confirms that these figures are below expectations. They also cut expectations for FY Dec 2025 and FY Dec 2026, both of which are expected to be loss-making.
The revenue forecast at Canaccord for 2024 was £108m (actual £107.2m), while the EBITDA forecast was £19.3m (actual £16.1m).
The “Current Trading and Outlook” section explains the poor trading in Q4 and raises concern around the outlook for the next two years:
Box office performance in the fourth quarter was not as strong as anticipated, the most notable underperformer being Joker; Folie à Deux. This was followed by congestion in the calendar on remaining blockbuster releases, with five in five weeks, leading to titles competing against each other negatively impacting the period.
Guest spend per head, whilst still in growth for the full year, softened during November and December due to the higher than expected proportion of family content.
As a consequence of increased uncertainty arising from the Autumn statement, the Board is more cautious around the outlook for 2025 and 2026.
Of course it wasn’t EMAN’s fault that Joker 2 flopped: it was the Director’s fault, who decided to make a superhero/musical movie. I’m one of the few people in the world who likes both genres, but I still wish he hadn’t done this!
Looking forward, EMAN “has confidence in the film slate for 2025” which includes the next installment of Wicked.
With respect to their balance sheet, “the Group's focus continues to be on controlling net debt and materially reducing leverage over the next two years”. There is a year-on-year reduction in net debt to £18m.
Graham’s view: I’ve been RED on EMAN (e.g. see here when I was RED with the share price at 60p), as this is another one where I think the company should have posted meaningful profits by now.
But it hasn’t done so, and instead distracts us with EBITDA numbers which I’m afraid I think are meaningless.
The company has suffered some very bad luck such as Covid and then the Hollywood strikes, and I’d love to think that performance could improve.
But at the end of the day, this is a loss-making, capital-intensive and indebted business with lots of fixed costs.
Losses are pencilled in at least until FY Dec 2026, and I don’t see why they won’t continue after that.
I hope they prove me wrong, but I’m afraid I don’t see any point in investing in this one.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

51 comments
everything (almost everything) is rising today but JUP is dropping. JUP is expected to rocket in a day like today.t . To me it is an ominous sign of worse to come.
Yep I bought it for a bounce couple of days back as it hit support but as you say it should be up today looks like volume is double the norm today so maybe one of the bigger holders dumping and looking for an exit.
I don't see any black swans with this one other than the death by thousand cuts scenario if something doesn't happen to make their active funds attractive to investors again.
I would just like to say that I appreciate this thread very much, even though I hardly ever comment, because I am not seeing it till later. Keep it up., please!
The reason this thread will eventually wear off is clearly visible.
Today we have some commentators, after the IG Design (LON:IGR) horrible update, that they seem they knew it!!
I first shared IG Design (LON:IGR) as an investment opportunity at 115p ( based on the numbers I had in front of me and the guidance from the management ) and that was the price I bought the shares. The price has doubled in a very short period of time and have exited (something that I have also posted here).
Recently after a profit warning I have bought back at 111p and used my profits from the original position (again something I have shared here).
Today we had another profit warning and this time is even worse. Management obviously LIED to us and I have sold everything. My overall gain is still 52%!!!
So to the commentators that seem to know everything AFTER the results and the trading updates , I will recommend that YOU STICK YOUR NECK OUT and deep dive on ideas and share them here BUT PLEASE do it BEFORE not AFTER.
So if anyone has anything to suggest that will make over 50% in 9 months please share this here-I might give you a good tip if you are right!
All the best
In fairness Yiannos people here will mostly make a private decision not to buy if they think something is a poor investment.
I think you and I have agreed on a few companies which we think are very poor and destined for future failure - but it is generally not well received on this board to be a Cassandra, particularly if it is a bulletin board favourite.
I didn't have a view on IG design before or after the profit warning so I wont pile in now.
Read again my post!
After the events comments that they knew everything is meaningless and pointless!
All the best
"After the events comments that they knew everything is meaningless and pointless!"
Not if it helps investors make a better investment decision going forward. IG Design didn't cease trading today. Its not as if it has gone bust and everyone knew this beforehand.
People will still be able to trade stock and some of the comments might help future decisions.
Yes - the thread is slowing dying. This is obvious. I think we will have to agree to differ as to why this occurring.
I am not sure you understand my point here.
Perhaps my limited knowledge of the English language and my poor writing skills do not help.
This thread was once a place where, the likes of Davidjhill, PlanetX, BenHazz, myself and many more , used to explain the investment case for different stocks, based on the numbers we had in front of us along with the management guidance of these companies. Most of the times we were correct and some others history proved that we were wrong!
This thread was once a place where I used to stick my neck out to explain to fellow commentators that many of PS picks will be a disaster BUT before events NOT after.
Now is a place for some to pass their free time basically saying and after the events are widely known : ‘I f…..g knew it!’.
NO ONE MENTIONED BY THE WAY the new all time highs for the FTSE100!
All the best
Totally correct mate, but as you say, your style isn't for everyone.
I like it - but if you don't, you don't - and you know that I suspect, which makes it harder for people to understand (first impressions and all that).
Does Yiannos have a 'light' version :lol:
Back to facts, rather that style, your picks on stocks are far better than a lot I have seen, (personally, I'd like to know more and have a beer when you're next in the NW).
Rather than pander to the brigade, Stockopedia need these alternative views. Give Yiannos a section, rather than tell Paul Hill he can't post anymore et al.
So if anyone has anything to suggest that will make over 50% in 9 months please share this here-I might give you a good tip if you are right!
Ok thats a tricky one - how about this binary investment that can return something approaching 60%
Nottingham Forrest to beat Southampton this weekend and Real Madrid to beat Las Palmas
oh dear like investing in shares there is no sure thing with betting on football.
Gambling is a fools game.
Not always - it is for many though :)
That made me laugh .... the wisdom after the event.
Clearly I don't understand the Quality score on stockopedia very well, how does IG Design (LON:IGR) quality section look like this yet gets a Quality score of 93? Would have thought this number would be <25!
I tend to agree with those here who have avoided IG Design (LON:IGR) on the basis of it being a low margin supplier of highly commoditised products. Whilst I recognise the bull case for Card Factory (LON:CARD) , being vertically integrated etc., it strikes me that it also is a producer and supplier of low margin, highly commoditised products. The recent expansion into the USA where so many British retailers have come a cropper, also has some parallels with IG Design (LON:IGR) 's forays across the pond.
I'm not saying that they are the same at all, and I'm not knocking Card Factory (LON:CARD) which I know is popular and widely followed, but for my tastes, these are both low quality businesses which have little to no sustainable moat around them.
I noticed just this week, that my local high street has gained a bright and shiny new Cards Direct store. I point this out purely for interest sake. I have no idea how it compares as a shop or from a business model perspective.
There are obviously similarities in terms of the products, but the big difference is IG Design (as a supplier to large retailers) will have minimal pricing power. I actually think Card Factory have a reasonable amount of pricing power for the simple reason that most shoppers aren't going to quibble about a few pence on a card and shop around for the best deal - I suspect they could easily raise prices 10-20p without much impact on sales.
IG Design (LON:IGR) Graham, while IGR will have a seasonal high net cash at year-end, this is highly seasonal, as the Interims showed this declined to $7.4m (as they are purchasing in the run-up to Christmas). Given the variability of cash according to time of the year, I am not sure I would consider net cash at March 2025 as freely available for other use.
yes James, good point and I think I noted myself that this was a seasonal figure. Of greater importance are the very large cash and inventory balances. Nice to hear from you !!
Thankyou Graham, will you be covering McBride (LON:MCB) ?
yes!
Edison update Card Factory (LON:CARD)
Valuation looks very attractive
CARD’s prospective P/E multiples remain at a significant discount to its long-term average multiple of 13.6x in FY15–20. We will await the publication of FY25 results before updating our DCF-based valuation of 200p/share.
https://www.edisongroup.com/re...
" P/E multiples remain at a significant discount to its long-term average of 13.6x in FY15–20" Shouldn't we be taking into account the increase in interest rates when looking at PE ratios v. a time when interest rates were around 0.5% v. 4.75% today?
Card Factory (LON:CARD) (I hold) still think this looks cheap, they traded well through Xmas got their targets. They are in my view the Greggs of their sector offer cheaper value for money products they make / source themselves have a great GP and think they could corner the market where other more expensive operators go bust + they not yet gone for online market yet.
I've held Card Factory (LON:CARD) on a couple of occasions in the past and it remains on my watch list. I do believe it is a well run business and has admirably navigated some difficult markets over the past few years.
Having been an hectic week, its only today I've been able to take a look at the latest trading update.
Total Sales for 11 months +6.2% (+6% LFL at the Interm 6 months to 31 Jul - 0.2% increase) vs Total Sales Nov & Dec (Xmas trading period) +4.7%
Store Sales 11 months LFL +3.9% vs Store Sales Nov & Dec LFL +3%.
Does this not suggest a slow down through Nov & Dec compared to earlier in the year? If so, could this continue?
I do like the business model, its move towards diversifying into gifts to increase basket value and recent M&A could be exciting (or a cash drain - these things are never risk free).
Increase to NLW and NICs still a headwind (despite the company stating they have a plan to mitigate this) along with current consumer sentiment, keeps this on the watch list for now.
I'm also left wondering if the potential for Royal Mails USO reform and fewer letter deliveries in the week will impact card sales?
Card Factory (LON:CARD) comments from Edison have signs of the teenage scribbler. Average multiple of 13.6x FY15-20 was in period of steadily growing estate size. If it gets back to a 10x rating that would be a fair mark for a discount retailer with little growth to come, imo. USA expansion is the great unknown and in light of IG Design (LON:IGR) update today comes with fair warning that it could be difficult. Glad I didn't join the trade on IG Design (LON:IGR) pre-Christmas. Commiserations to those that did.
Jeff Nairn raises a fair point that the Sept update flagged concerns over retail customer risk. Dare we say we should all have taken more notice, especially those commentating?
thanks for the support. Its easy to get carried away with the waves of enthusiasm for a popular stock and fall victim to confirmation bias, if you own it, or anchoring bias, if you have made money with it before - “broker/commentator X says its a temporary setback”, “Stockopedia is still showing a high score”, “ debt is down and the revised multiple is now less than it was last year.”
But often it helps to step back and ask yourself “whats a good reason not to own it?”
In the case of IG Design (LON:IGR), the answer was in that Sept update. PS made light of it in his review, probably because he’s more of a risk taker or had made money with it before ( I dont know). But the warning about customer risk was a dealbreaker for me.
I do this whenever eyeing up a potential investment. It doesnt require clairvoyance, just an ability to look behind the numbers, do a bit of research on the company and its markets, and not let yourself be swayed too much by “commentators” who can make a great case and pull out the numbers to back it up.
Back to the dayjob!
Would be interested to hear how you view on Ninety One (LON:N91) against the other asset managers Graham.
Its another one that looks cheap as chips but could get cheaper due to the outflows issue, I have a feeling they either bought or merged with Rathbones which has a pretty good rep in the industry.
The Phoenix, apologies I didn't get around to N91.
No worries Graham you do great work and who wants to be working past midday on a Friday enjoy your weekend.
IG design
Terrible update but thats what you get with a CFO acting as CEO. Untenable now has to go but wont.
However anyone know NAV looks very cheap now on asset basis even if breakeven only and write down of bad debt
- net cash
- hard tangible assets (buildings )
- stock (lets write down 50%)
whats our fag packet calculation of breakup value
#IGR - who are the buyers with the shares down 50%+ ? Speculators?
When IG Design (LON:IGR) last warned in September, PS found it "attractively priced" at 136p. You would now have lost half your investment in three months if you had bought after that warning and sold this morning.
Expecting trading conditions for a low-margin, discount retailer to materially improve in just three months and the shares to bounce back significantly is, IMHO, a triumph of hope over experience. despite Paul's praise of its balance sheet.
I don't hold, thankfully.
Quite a few picked it, Mark Simpson, was one of his Christmas gifts. Richard Croll also had it in his NAPs selection. It was also well rated on Stockopedia.
Bowl investing :-)
Sell on the first profit warning. They usually come in threes.
Jeff, great.. but back then PS did not have visionary forward looking abilities to foresee that the 4th largest customer of IGR’s American division would file for Chapter 11 bankruptcy!
It doesnt need visionary capabilities. There were 20 notable bankruptcies in US retailing last year and the US is a minefield for retailers and worse for their suppliers.
https://www.retaildive.com/new...
Tellingly, in September IG Design (LON:IGR) said:
"In addition, we were carefully managing our credit risk exposure, which weighed on revenues, as some of our US retail customers gave us cause for concern.”
That the company felt the need to put that in a TU back then speaks volumes, I think. That PS didn't give too much importance to it is also revealing.
But for me, its a deal breaker. Why bother investing in a company that is worried that some of its customers might go bankrupt at some point in the future?
Sure, you can try to discount that uncertainty but, for me, the game becomes gambling not investing.
I don't own IG Design.
PANMURE LIBERUM CUTS IG DESIGN GROUP TO 'HOLD' (BUY) - PRICE TARGET 60 (295) PENCE
Stable door, horse…
IG Design (LON:IGR) I've always struggled to understand why this seems to get such an enthusiastic following from various commentators - I spent a few minutes looking at it last year and quickly concluded that making wrapping paper/decorations was a purely commodity-like business with no absolutely no pricing power or differentiation. The big retailers are obviously going to squeeze their suppliers in a race to the bottom.
preceptive , I agree , I sold early for small profit, nearly brought back in recently glad I didn't press the button
"IG Design (LON:IGR) I've always struggled to understand why this seems to get such an enthusiastic following from various commentators"
I'm guessing that previous share price out-performance had a lot to do with this; going from 20p in 2009 to 800p in 2020. Whether you made money in this run or missed out many would hope it could do it again. Boohoo (LON:BOO) would be another example of this phenomenon..
IG Design (LON:IGR) I made money on it in both the internet boom post 94 and the 2003- bull market. I'd been out for some time except for a £1 a point just to keep it on the radar (showing a £90 loss! This was a residue of a much bigger position I had which I sold when it rolled over below the 50 day MA. I do think that this is of a size (T/O £700m) and history where it will come back, I think those sorts of businesses which aren't particularly cutting edge often have a collective knowledge through their employees which will help them through times like these. I'm not buying until there is evidence they have a handle on their issues though!
Listing Costs
We has been frequently mentioned here about the high listing costs on AIM/LSE encouraging delisting at the bottom end of the market.
I was staggered to see that AIM minnow Renalytix (LON:RENX) -market cap £38m - claiming that its reacquisition of “foreign private issuer” status in the US (which I believe was facilitated by its stock no longer being NASDAQ listed but only trading in the US on the OTCQB Venture market) would save the company up to £1.9m per year.
M&C Saatchi (LON:SAA) somewhat flowery language but the overall tener is positive. Trading in line with expectations is a good result given the current economic conditions and the shares are far from expensive.
It is a top five holding for Rockwood Strategic (LON:RKW) accounting for 5.4% of NAV. I have a more modest holding.
McBride (LON:MCB) Graham, small observation and I might be wrong but reading Zeus's note this morning they seem to be trading ahead of market expectations (but in line with internal expectations) hence the upgrades from Zeus?
Evoke (LON:EVOK) If you recall I did flag to you last month something was afoot here, let's hope it builds some momentum...
Thanks for that Burnt Onions, looking forward to covering EVOK today... hopefully I get around to MCB at some point. G
IG Design (LON:IGR) warns. Puts the Card Factory (LON:CARD) update into perspective! Hit their target. Fcst p/e 6.2, yield 5.9%
Value will out at CARD eventually.
Surprised that IGR had a 96 stock rank despite its troubles over the last few years.
IG Design (LON:IGR) is one of the turkeys of Christmas: https://www.stockopedia.com/co...
Safe Store Safestore Holdings (LON:SAFE) sinks £408K into share holding, surly he must have some confidence.