Daily Stock Market Report (Fri 17th April 2026) - ITM, VP., OPT, MGNS, SSIT, TBTG

Good morning!
The FTSE is set to open litte changed, at 10,600.
Focus remains on Iran: Trump spoke very positively last night about the prospects of a permanent deal that would reopen the Strait of Hormuz. But markets don't seem to believe him, with oil prices and other commodities remaining at elevated levels.
If company news is quiet today, I intend to catch up on some stories that were missed during the week - let me know if you have any requests!
I've run out of time for today, have a great weekend! Spreadsheet accompanying this report: link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Workspace (LON:WKP) (£718m | SR58) | Trading Profit after interest for FY March 2026 to be in line with market expectations. The decrease in rent roll and reduction in pricing in H2 will have a negative impact on portfolio valuation. | ||
ITM Power (LON:ITM) (£641m | SR26) | SP +42% The collaboration envisages the deployment of several hundred decentralised production plants for NATO armed forces, each with an electrolysis capacity of up to 50 MW. It will initially focus on the UK. | AMBER = (Graham) I acknowledge how exciting this announcement is, but the revenue and profit implications are impossible for me to guess at. For this reason, I’m leaving our neutral stance unchanged. I just don’t see how to value the company at this stage. But well done to holders. History shows that these shares can really take off - and maybe there is some real substance behind the hype this time? | |
Discoverie (LON:DSCV) (£607m | SR46) | Trading accelerated in Q4. Full year: orders up 9% CER and by 5% organically, growing faster than sales. “On-track to deliver another year of growth in adjusted earnings per share in-line with consensus market expectations” Pro forma leverage c.1.7x, “comfortably within our target range”. | ||
VP (LON:VP.). (£193m | SR49) | “In a challenging macroeconomic environment, Vp expects to report FY26 profits between £26-29m, in line with previous revised guidance.” Outlook: Board confidence in positioning and future performance. | AMBER = (Graham) The profit warning was still very recent, and it remains unclear where FY March 2026 profits are going to be within the range given. Therefore, despite the green shoots, I’m leaving our neutral stance unchanged. This is consistent with the StockRank: | |
Aew UK Reit (LON:AEWU) (£168m | SR61) | NAV of £171.97 million or 108.38 pence per share (December 2025: £173.47 million or 109.32 pence per share). NAV total return 0.96% for the quarter. “We are pleased to report a steady quarter of performance, with another period of positive NAV total return, and valuation gains seen across the Company's retail, industrial and office sectors…” | ||
Optima Health (LON:OPT) (£161m | SR76) | FY26 Adjusted EBITDA to be ahead of market expectations by c.10%. Consensus is £18.1m. | AMBER/GREEN ↑ (Graham) I will tentatively upgrade our stance on this by one notch, after today’s beat. However, I should say that debt-fuelled acquisitions, in order to hit revenue and adj. EBITDA targets always make me nervous. I much prefer companies that focus primarily on organic growth, margins and returns. | |
Eurocell (LON:ECEL) (£109m | SR70) | Appointment of Matt Worster as the company's new CFO, starting in the Autumn. Matt is currently Finance Director of Travis Perkins General Merchant and has been Director of Investor Relations at Travis Perkins Plc. | ||
Cora Gold (LON:CORA) (£78m | SR26) | Binding US$120 million gold stream, removes future funding requirement for the Sanonkoro Gold Project, enabling CORA to move forward with pre-production workstreams with confidence. Eagle Eye Asset Holdings will be entitled to purchase 30.44% of gold produced at a price equal to 20% of the prevailing spot price. Cora can still replace 50% of the stream with traditional senior debt. | ||
Fevara (LON:FVA) (£71m | SR58) | Exclusive five-year agreement with Oceana Minerals to distribute LithoNutri in Great Britain and Ireland. | ||
Metals One (LON:MET1) (£21m | SR5) | The creditors of Barbrook have approved a plan under which LBR will acquire assets of Barbrook including 2.1Moz of gold resource for ZAR 279 million (US$17.0 million). MET1 owns 30% of LBR. | ||
essensys (LON:ESYS) (£11m | SR27) | Revenue down 25% “primarily due to the continued downsizing of a single large strategic customer”. Adj. EBITDA £0.1m (H1 last year: £0.8m). | PINK (offer from Mark Furness’ concert party at 17p). | |
Zinc Media (LON:ZIN) (£11m | SR33) | The Edge has continued to perform strongly, resulting in the achievement of the final earn-out targets. £1.43m payable to the vendors, £0.34m payable in cash with the remainder payable in new Zinc shares. |
Backlog sections: MGNS, SSIT, TBTG.
Backlog
Morgan Sindall (LON:MGNS)
Up 7% yesterday, now trading at 4798p (£2.3bn) - Trading and Outlook for 2026 - Graham - GREEN ↑
There was excellent news yesterday from this Super Stock:
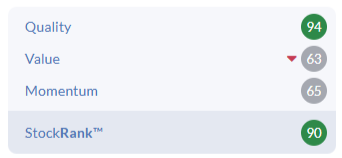
I note that Roland downgraded our stance on this from GREEN to AMBER/GREEN in February, at a market cap of £2.6bn. He noted that earnings were forecast to edge lower over the next 12-24 months.
However, that expectation has been turned on its head by yesterday’s update:
…the Group now anticipates that its full year results for 2026 will be significantly ahead of its previous expectations following strong trading activity and increased visibility for the remainder of the year from its Construction and Fit Out divisions.
Partnership House: modest growth expected here - it sounds like a downgrade. “Near-term consumer sentiment continues to remain subdued due to wider macro-economic events.”
Mixed Use Partnerships: profits in line.
Fit Out: this division has excelled. Profits to be significantly ahead of expectations and exceed the top end of the medium-target of £80-100m
Construction: margins here will be at the top of the medium-term target range (3.0-3.5%). Revenues will be towards £1.4bn “due to increased visibility for the remainder of the year supported by its high-quality orderbook and work at preferred bidder stage”.
Infrastructure: revenues are trending in line, with operating margin at the top end of the medium-term target range (3.75-4.25%).
So it’s not 100% positive, but it is overwhelmingly good news.
Average daily net cash: £445m, vs. £372m for the same period last year. Trending in line with expectations for average daily net cash this year of >£400m.
Graham’s view
I’m happy to defer to the StockRanks on this occasion, and go back to GREEN. This is also consistent with our method of upgrading our stance on stocks that beat expectations.
Roland isn’t here today, but I suspect that he’d agree with my decision. His downgrade in February was very careful, and based on a £2.6bn market cap. The market cap is lower today and yet prospects have improved.
This also passes some screens I like: one for Quality, one for Growth, and one for Value!
And what a nice trend this is for EPS forecasts:
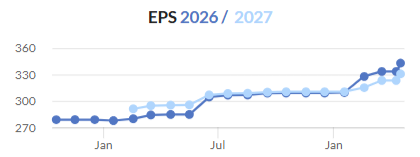
It’s a low-margin construction business, not the sort of thing I’m typically drawn to, but GREEN must be the logical stance for us now.
Seraphim Space Investment Trust (LON:SSIT)
Up 1% today at 180.35p (£428m) - Contemplating fundraising via an issue of C shares - Graham - AMBER
SSIT is “the world's first listed SpaceTech investment company”. We’ve not covered it in this report before, but there is a question from readers about recent announcement.
On Monday, it announced it is “contemplating a fundraising via an issue of C shares, available to both institutional and retail investors”.
It says that: a) SpaceTech is “the backbone of the next wave of global megatrends”; b) its investment manager is “the world's #1 SpaceTech investor”; and c) there is “strong momentum in the existing SSIT portfolio”.
All of which is considered to justify a fundraise, to “continue the strategy successfully executed since IPO”.
This led to a Circular posted yesterday, with a proposal.
Key points:
350 million C shares to be issued (current share count: 237 million).
The C shares will fund a distinct pool of assets until they are converted to ordinary shares.
The conversion ratio will be calculated according to a formula which is designed to avoid reducing the NAV of ordinary shares.
I’ve opened the official document and looked up this formula: it’s complicated, but I think the underlying logic is simple. When C shares are being converted into ordinary shares, there will be a calculation of the value per C share vs. the value per ordinary share at that time. That will determine the conversion ratio.
For example, if the value of a C share was somehow only half the value of an ordinary share, then a C share would be converted into half an ordinary share. This is my very rough interpretation of what is happening.
Each C share will have “a voting right equal to an ordinary share”. I would therefore expect C shares to be issued close to NAV per share, which was last reported at 142.3p (December 2025).
Graham’s view
This is a complicated fundraise, but I can see the logic for it.
Issuing C shares will reduce cash drag for shareholders who don’t participate in the fundraise. The ordinary shares will continue to have their own existing portfolio, periodically letting in new investments that have been funded by C shares, and C shares converting when that happens.
The negative effect of cash drag will be felt entirely by holders of C shares.
As for SSIT itself, I have no strong view. I will note very high concentration in certain positions as of December 2025:
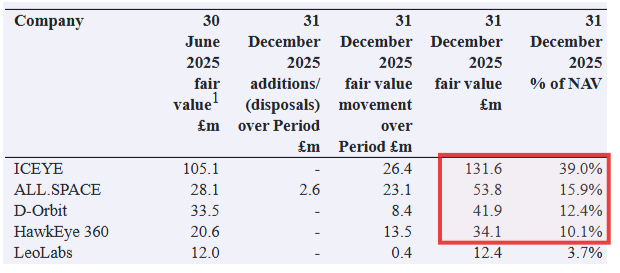
I’m in no real position to object to this, given the positioning of my own single-stock portfolio right now! But it’s worth mentioning.
I also note that the shares are trading at a significant (c. 27%) premium to the December 2025 NAV per share. I assume this is a reflection of not sentiment in the space sector right now, with SpaceX about to IPO.
With the trust enjoying a big premium to NAV and bullish sentiment, it makes sense for them to raise massive new funds while they can, potentially more than doubling the share count. But is this a sector where I would be hunting for value? No.
Beauty Tech (LON:TBTG)
307p (£340m) - Final Results - Graham - AMBER
I can’t see much on the StockReport yet for this one. It IPO’d on the LSE Main Market in October 2025.
Results for FY December 2025 are now out.
It’s nice to see a profitable, growing company joining us:
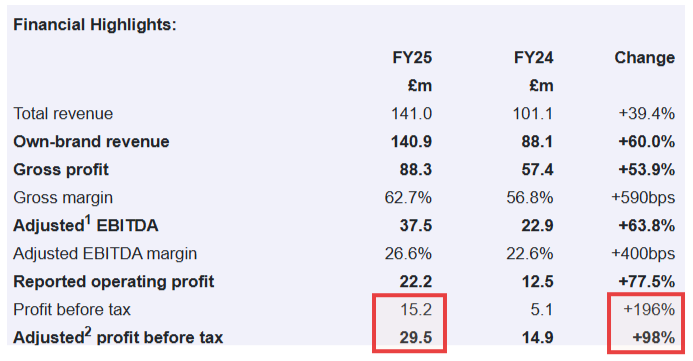
It sounds like the revenue growth was driven by a range of new product launches - so it might be difficult to repeat this every year.
Also ,there’s a gulf between PBT and adjusted PBT, but let’s not nitpick too much for a recent IPO.
They beat expectations and achieved their “third upgrade since IPO” - presumably expectations at IPO were deliberately set low?
Looking ahead:
Very encouraging start to Q1 FY26, with strong growth across the Group's core business and across all key markets and channels
Elimination of pre-IPO interest costs (£6.3m) and IPO-related exceptional items (£8.0m) provides significant tailwind to FY26 reported earnings and cash flow
Net cash is £41m, vs. net debt of £27m a year ago, so that should indeed boost 2026 earnings.
New guidance:
Year-on-year revenue growth expected to continue into FY26, with FY26 revenue in line with current market expectations but due to stronger margins, it is anticipated that profit will be ahead of expectations.
Existing market expectations are given: FY26 revenue of £160.0m, adjusted EBITDA £38.2m.
CEO comment:
Looking ahead, the structural growth drivers across the Group's three core addressable markets of anti-ageing, hair removal and hair regrowth, provide us with confidence in both the long-term demand for At-Home Beauty Devices ("AHBD") and The Beauty Tech Group's significant market opportunity.
Estimates: Cavendish have an adjusted EPS forecast of 25.4p for this year, rising to 28.1p next year. That puts the shares on an adjusted P/E of 12x for the current year. And the adjustments should be lighter this year.
Revenues are seen growing 13% this year - far more sustainable than the growth rates seen in 2025.
Graham’s view
I’m not too familiar with this one yet, and the StockReport is empty, so I’m going to chicken out and leave it on AMBER for now. It does look like a decent IPO, and hopefully it will be useful to have this in the archive when it reports in future.
Graham's Section
ITM Power (LON:ITM)
Up 42% to 133p (£919m) - Strategic collaboration with Rheinmetall - Graham - AMBER =
Even for those of us who have never bought German shares, it’s hard to avoid hearing about a giant like Rheinmetall AG (ETR:RHM). I think of it like Germany’s answer to BAE Systems (LON:BA.) .
Congrats to ITM shareholders for this deal:
The collaboration will focus on Rheinmetall's Giga PtX project, which aims to establish a Europe-wide network of decentralised synthetic fuel production plants for the NATO armed forces, designed to strengthen defence energy resilience, sovereign fuel capability and operational readiness.
The project envisages the deployment of several hundred decentralised production plants across Europe, each with an electrolysis capacity of up to 50 MW, capable of producing approximately 5,000 to 7,000 tonnes of e-fuel per annum per facility…
The collaboration will initially focus on the UK.
The CEO of ITM says “the Giga PtX project represents a repeatable deployment opportunity for large-scale electrolysers”.
The Head of Hydrogen Program at Rheinmetall says: “we are creating a scalable network that strengthens energy autonomy for Europe's defence forces.”
Financial implications?
The RNS does not attempt to give any new guidance. It doesn’t give any new financial details for this contract.
In theory, this partnership could see ITM selling hundreds of its hydrogen systems to Rheinmetall and NATO. It recently launched a standardised 50MW plant priced at c. €50m.
Given that the company’s total annual revenues haven’t yet crossed €50m, this would mark an explosive change.
Graham’s view
I’m sorry to any ITM fans, but I don’t feel able to make a high-conviction call on this one.
The historic financials aren't too exciting:
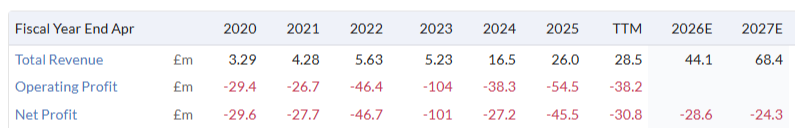
But today’s news is potentially transformational. And the timing is interesting: eight days ago, the UK government made a £40m equity investment into ITM, along with a £46.5m grant from the Department for Energy Security and Net Zero.
I do think the implications of this announcement are highly uncertain:
“The project envisages the deployment of several hundred decentralised production plants across Europe” - but how likely is this to happen? Might the plans change?
Will ITM be the only provider of hydrogen systems? How many other providers might there be?
Plants will have “an electrolysis capacity of up to 50 MW” - does this mean 50MW is the max, and that many plants could be much smaller than this?
What’s ITM’s expected profit margin at a 50MW plant and at smaller plants?
What's the expected timeframe for the rollout of these plants?
So from my perspective, even though I acknowledge how exciting this announcement is, the revenue and profit implications are impossible to guess at.
For this reason, I’m leaving our neutral stance unchanged. I just don’t see how to value the company at this stage.
But well done to holders. History shows that these shares can really take off - and maybe there is some real substance behind the hype this time?
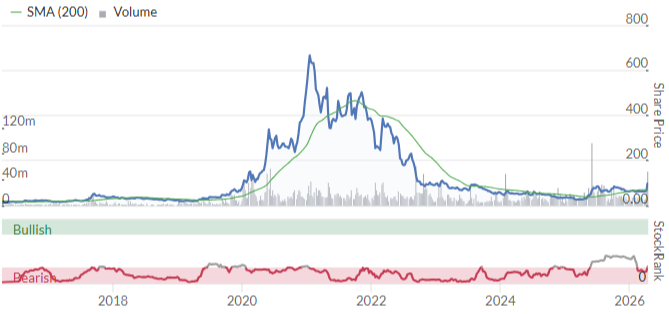
I also note that its FY April 2026 cash guidance is £210-215m, so there are no balance sheet concerns at this time.
Short interest: it's worth noting that the stock is heavily shorted (at least 4.4% of shares borrowed), and today's gains could involve some distressed short-covering. ITM's share price has doubled since last week! So it wouldn't surprise me if the funds shorting it are now rushing for the exits.
VP (LON:VP.)
Up 1% at 483p (£194m) - Trading Update - Graham - AMBER =
This equipment rental provider issued a profit warning in February, cutting adjusted PBT expectations from £37m to £26-29m.
That guidance is reiterated today.
As FY March 2026 is already over, perhaps they could have narrowed down guidance a little?
Looking ahead, they’re sanguine on the outlook:
Despite tough market conditions, the Group continues to see long-term drivers of demand across its core sectors.
I was neutral on this stock in February as, despite the profit warning, they were still profitable and there appeared to be decent scope for recovery, e.g. in the water sector as delayed infrastructure spending would eventually kick in.
It now seems that there are a few green shoots of recovery: I’ve highlighted them in bold below.
Electricity transmission continues to see growth and strong demand in both the UK and Europe. Rail activity is steady but subdued, with good visibility on future project pipelines. There are positive lead indicators in Water as we enter Year 2 of AMP8, supporting our confidence in an improvement in revenues for FY27.
Within the Construction sector, the Specialist Construction market remains supportive, particularly in London and the Republic of Ireland. Housebuilding remains subdued, but with stronger prospects as Homes England's Social and Affordable Homes Programme (SAHP) 2026-2036 commences.
Mid East conflict: higher fuel costs have been “largely mitigated through customer pricing”.
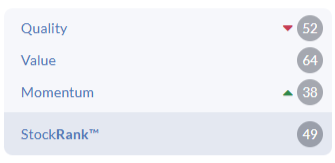
Graham’s view: the profit warning was still very recent, and it remains unclear where FY March 2026 profits are going to be within the range given. Therefore, despite the green shoots, I’m leaving our neutral stance unchanged. This is consistent with the StockRank:
Optima Health (LON:OPT)
Up 5% to 188.5p (£205m) - Full Year Trading Update Graham - AMBER/GREEN ↑
Optima Health (AIM: OPT), the UK's leading provider of technology enabled corporate health and wellbeing solutions, today announces an unaudited trading update for the year ended 31 March 2026.
Optima recently announced they were raising £35m of fresh equity to help them make a £100m acquisition (“People Asset Management”, or PAM Healthcare).
In that announcement, on 31st March, they included a trading update for FY March 2026. They said adjusted EBITDA would be “at least in line with consensus”.
But it’s actually quite a bit better than that. Today’s RNS says “Optima now expects FY26 Adjusted EBITDA to be ahead of market expectations by c.10%.” Consensus was £18.1m.
Their medium-term targets: £200m revenue, £40m adjusted EBITDA.
Cavendish estimates - thanks to Cavendish for covering this one. I don’t think they’ve updated their forecasts to account for today’s beat, but their forecasts do include the effects of the PAM acquisition. These estimates include:
FY March 2027 revenue £207.7m, adj. PBT £16.7m.
FY March 2028 revenue £231m, adj. PBT £23.4m.
At the current share price I calculate forward EPS as c. 15x for FY27, falling to c. 11x for FY28.
Net debt is seen falling from £63m (March 2027) to £46m (March 2028).
Graham’s view
I will tentatively upgrade our stance on this by one notch, after today’s beat.
However, I should say that debt-fuelled acquisitions, in order to hit revenue and adj. EBITDA targets always make me nervous.
I much prefer companies that focus primarily on organic growth, margins and returns.
Their interim results emphasised 17% revenue growth, but they didn’t make their organic growth rate abundantly clear. The headline growth rate included the effect of three acquisitions.
So I’m a little nervous about this one. But if they do hit their targets over the next two years, without making any other large, debt-funded acquisitions, then net debt will reduce and shareholders will be sitting pretty.
It’s a slightly risky call, but I’m AMBER/GREEN on this now.
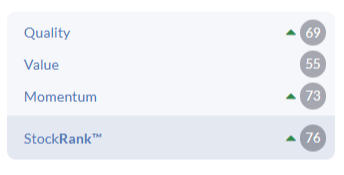
The StockRank is picking up, too:
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

55 comments
Cockney Rebel has been bullish on Seraphim Space Investment Trust (LON:SSIT) on his Substack page. Haven't read this weekend's update yet.
https://cockneyrebel.substack....
I've not yet listened to the John Baron podcast available on the iPhone podcast app.
https://tinyurl.com/2bdvr3vz
I don't own and would not buy now given the premium to NAV. Best to let the potential corporate action go through and see the lie of the land afterwards.
Most things ticking up seems the straight of Hormuz is now open all be it who knows for how long.
I think these are the top five Stockranks for the companies exhibiting and presenting in Birmingham next Wednesday...
Victorian Plumbing 81
Origin Enterprises 93
Polar Capital 95
S and U. 96
Serabi Gold 99
Do come and join the hundreds of investors and see great presentations and excellent networking opportunities. MELLOBIRMINGHAM — Mello Events
ITM Power (LON:ITM) to my mind last week's GB Energy announcement was truly transformational though in a different sense , my analysis from last week below explains a bit more.
My scoring system has a max of 25 (and min of -25 for bearish) . The GBE catalyst last week scored 22: in almost 1000 analyses thus far few have done this ( 80% of those make money with an EV of 33% passive return, active trade management is much higher )
like many I have traded this on and off over the years as it navigates the narrative pathway that many stocks in these "hot then cold "sectors follow. To me today was more "jam on last week's cake" rather than jam tomorrow . Arguably it's both and if I'd missed the move I know how my schadenfreude might skew.
Good news begets good news much like trending stocks tend to trend. It's a momentum thing
I added to a position last week so made almost 100% since : the short interest of 4.8% ( almost 14 days to cover) was another powerful source of stored momentum ;-). That's part of the powder keg in today's explosive move
Though if I were to be a cynic we have now a second or third order derivative story stock (renewables, energy crisis , AI data centres and A&D ) - it does a have a few quid on the balance sheet, a real product and an equity-backed seat at the Government table for contract awards . While I've trimmed on the rise as RSI hits nr 90 , I hold on the expectation of the alignment of these : good times ahead though a a lot in the price in a short amount of time . The physics of price momentum calls for some consolidation if not a pullback in shorter timescale.. The nature of this will be a measure on the transformation ( traders to investors, the transfer of capital to the more patient)
I tweeted the below last week and today's catalysts on X here
I publish this kind of stuff daily on runprofits.com .
Below is last week's catalyst analysis using my ACE ( Alpha Catalyst Engine - a multi agent >500 analytics rule based AI system : handbuilt and trained with 8.5 years of market data and a proprietary UK centric lexicon - so a glass box not an AI slop black box)
Your analytics engine might make for an interesting thread or webinar in its own right. How does it correlate with StockRanks, does it typically work best at shorter time horizons? From what you said it sounds like with active management results can improve suggesting it does.
re ITM Power (LON:ITM) ACE analysis
The short answer is that they are complementary owing to the different architectures. Stockopedia is fantastic for establishing a fundamental baseline. ACE, by contrast, is a temporal, event-driven system. It isn’t looking at what a company did last year; it is built to assess the real-time impact of a transformational catalyst today (it runs pre market)
... the longer answer
ACE uses an 'agentic' approach— multiple specialised AI agents working in a chain of custody running rules-based assessment in different frameworks.
They process nearly 500 distinct analytics in a rulebook I wrote including applying a bespoke financial lexicon to read the nuance of an announcement (this was developed by analysing price reaction to the actual words so words effectively become vector quantities: using 8.5 years of data so it parses the RNS speak into scores) . It then cross-references that against the state of the companies price at the time using a whole host of quants based on momentum, fundamentals etc and then calculates the delta—the difference between what the market had priced-in and what the catalyst now implies. That is the ACE scoring (it's a scalar offset from -25 bearish to +25 bullish) but the analysis agent also carries out qualitative analysis (the one pager above) to contextualise the score and provide a discretionary overlay. - for readers. That includes directional bias (Bull Bear Neutral) , conviction ranking and an assonance/dissonance gauge to model conflicting inputs (this is where the real proprietary magic happens and was the hardest bit to build ). The agents work in different environments to allow for degrees of generative heuristics: this is how you manage hallucinations. One of the agents is an auditor who manages an audit trail across the workflow and prosecutes any deviations from the rules enforcing a contextualised remediation : it operates with a "zero trust" bias and is hostile to the other agents. Bit like real life then
If it sounds complicated it's because it is .. but then so are markets though it is not intended to "solve" anything, just to better characterise then correlate and make money (the alpha)
I track the performance from the catalyst date over time : the expected returns scale directly with the ACE score (almost 1000 analyses). The results skew positive - it is intended to be predominantly for long-only execution and exhibit "fat tails" so the system is highly likely to capture those oversized, breakout moves that occur when a stock re-rates over a period of weeks / months. That is the alpha I am looking to capture
using ACE as an active, high-velocity overlay on top of a solid Stockopedia screen should make for a very powerful pairing. (ACE as a trigger) . I haven't done the correlation numerically but it follows by inference and observation . I store every analysis with the qual and the quant and do detailed analytics which I have on my site as a permanent record - correlation to Stocko could be backtested
I tend to trade on ACE signals using rules and then manage the position: truly transformational catalyst don't tend to mean-revert and can birth trends that last years - you just follow the trend until the bend in the end so I don't need another system .
One point, I used to be biased against low SR scores in the past ( I've had a Stocko sub since 2013) , on that basis I would miss early opportunities and pre qualifying stocks : now I am no longer dogged by the high SR bias and I am much more profitable but then I am both trader and investor. There's a horses for courses nuance needed
more here runprofits.com
I am a relatively new holder of Seraphim Space Investment Trust (LON:SSIT) and would be grateful if you would have a look at their announcement yesterday that they intend to issue up to 350 million C shares in the company . A couple of questions -how would this effect my existing investment and how could I subscribe for the new C shares . I haven't come across this type of transaction before.
ditto
Fred, at this stage is just a proposal in a circular. The exact process of subscribing for new C shares will be detailed at a later date, if it goes ahead. I've attempted to cover the big picture of how it will work above. Thanks for the suggestion! G
I am not a holder in Seraphim Space Investment Trust (LON:SSIT) but the bit I find confusing about issuing C shares is I think some of this money will be used to finance the ongoing development of existing holdings in the Ordinary. This is a bit odd especially if the financing is done on attractive terms. Then following the financing when its complete - the ordinary stock take on the investment at book value. Hmmm I don't know how attractive a deal this actually is for Ordinary stock holders although it obviously protects them from the cash dilution on the short term and removes financing risk from the existing book. It suggests to me not much appetite and with so many private clients on the list ; that the C deal is being done at NAV = 100 to get institutions on board and solves a financing issue whilst there is demand : BUT sets in motion a weird / complicated relationship to manage between C and Ordinary holders. My experience of C issues isn't that good so I think this raise puts me off Seraphim Space Investment Trust (LON:SSIT) somewhat actually although I guess it was done with the best intentions. Seems like banks get to raise some money whilst there is demand when the 25% premium would make it very difficult in the Ordinary shares.
I can add a chart view from a Minervini perspective which suggests that ITM has entered a climax run.Buying in after a 100% plus move in 10 days is chasing and carries a massive risk of a sharp 15-20% mean-reversion pullback.The deal will be transformational with the market now pricing ITM. as a National Strategic asset which makes traditional metrics such as P/E irrelevant,as it is being valued on Strategic Capacity.
In the short term take profits as the price is over 80% above the 200-day SMA and technically super extended. RSI(14) is showing its highest reading in 3 years pointing to the blow-off risk .Volume is roughly 23x the 50-day average .OBV is vertical confirming total institutional commitment to the long side.
ITM Power (LON:ITM) - wow - don't follow and don't intend to but something afoot.
Chartists call it a consolidation phase but to catch the 'breakout' of resistance is tough but Volume was indicating something happening, but only if watching closely. An Alert would not have captured the move.
I suspect if there is substance to the move then it will consolidate from here. How long is the question. Sorry know nothing about it and at an SR of 26 won't be doing so anytime soon unless have insider info. Good luck no hate.
Apologies. Just seen it involves hydrogen, not something discussed around the dinner table often but one of the industrial essentials. Maybe disrupted by supply (ship or blown up facility in the Middle East).
Typical of the things need to have some notes on so when the next ME blow up can get into oil, fertilizer, corn, blah blah and maybe hydrogen.
Maybe Linde (ETR:LIN) worth a look.
Thank you RDHOWARD, I'm still learning so thought it better to ask a dumb question rather than be dumb and stay dumb. Cheers
Something brewing at Science (LON:SAG) perhaps? Been rising past workforce so on no news...
Week not workforce!! Bloody predictive
I know it’s a bit simplistic but how can AI seriously take over the world when it can’t even sort out predictive text! It’s never been worse, and I don’t know if anyone uses HL but their new search engine for stocks is totally hopeless!
ITM Power (LON:ITM) has been a perennial jam tomorrow stock which is reflected in the StockRank. However, in recent years revenue growth has started to accelerate and was forecast to continue rapid growth even before today's announcement. The market seems to be viewing today's news as pretty transformational (up over 40% at the time of writing). I don't hold, but have followed this stock for a while. If you've got time it could be interesting to review.
I have held ITM Power (LON:ITM) for a couple of years as one of my high risk jam tomorrow names, but what has made it an exception to the usual names in this category is a very high net cash position. The prolonged loss making and lumpy news announcements have been much more bearable and, perhaps even more unusually, it has still got the fire power to bear the necessary capital expenditure to make good on its sales potential.
Catch up on Beauty Tech please if you have time
Geiger Counter (LON:GCL) worth pointing out that the bonus issue is well in the money this year and worth NOT missing ....5 for 1 at 37p is worth taking up....a week left to raise money needed.
Oh thanks RD - nearly missed this.
Swissquote have the wrong details so it's worth following up... assuming my details are right but the RNS and Dir announcement consistent with 37p.... free money, kinda.
Thanks RD. I owe you a pint! For anyone STUPID ENOUGH to use Barclays (yep that's me!) note that they have not got this recorded!!!! Needless to say I've flagged it. It is correctly recorded on HL and I've subscribed. Not the first time Barclays have made this mistake in my experience!
Fidelity did not have this recorded either...
Geiger Counter (LON:GCL) Can buy one for every five shares held on 9th April 2026 at 37p.
So only a thing if you already own shares on 9th April? (ie buying now does not qualify??).
Yes you need to be a holder - which is why it is called a bonus issue.
Yeah, I'm a small Geiger Counter (LON:GCL) shareholder and I've been looking at this. It kind of implies that as long as you are a qualifying shareholder as of last week that you can apply for more shares than the 1 in 5 you are automatically allocated the chance to buy. (Whilst qualifying this by saying you won't get any more than your allocation if the fundraising is fully or over-subscribed).
Are you thinking of applying for extra shares. Having read all the documents I can't see any downsides to the purchase with the shares at 75p today. Unless I'm missing something?
I'm not a holder of Geiger Counter (LON:GCL) now, but have participated in previous years. The only thing I found is the price dropped afterwards, once the short term traders disposed of their holdings, but it looks like there's plenty of room between the current price and issue price this year to still make a healthy profit on them.
No downside today which is why I joke free money but obviously people may sell the ordinary shares to take up the issue which could put downward pressure on the 75p..... but as we stand it is a no brainer to me.
Geiger Counter (LON:GCL) I hold in both ii and Hargreaves. I could only apply for 1 in 5 maximum - I couldn't see of a way to apply for extra shares, I didn't know that this was possible?
Yeah, the letter specifies the amount I am entitled to buy but also has a sentence:
"If there is an excess application available on the Offer and you apply for more than your basic Entitlement then please be aware that if the Offer is fully subscribed there is no guarantee that you will receive any or all additional shares applied for."
Which implies that you can apply for more shares than you are allocated - but there is no guarantee that you will get any or all of them.
I'm with SW for my ISA and on their acceptance form it asks you to put down the number of shares you want to buy.
My reading is that you can apply for more? But I could be wrong.
strange, I have just checked and ii and Hargreaves limit your subscription entitlement to 1/5th of your total holding and there is no option to subscribe for more. I cannot imagine this would be possible as everyone would be massively oversubcribing for sub shares considering the price of Geiger Counter (LON:GCL) and the 37p you pay for the subs.
Yes probably a bit of wishful thinking on my part. The wording is a bit disengenuos in the sentence I mentioned but looking at previous subscription offers - and I think this is the 5th or 6th annual one, they have just cut and paste the same document each year - so might be something to do with that. Might have had slightly different rules at some point in the past.
Still a great offer, I think they've made it sweet this year as two of the previous subscriptions were cancelled (2023 & 2025) as the current share price was less than the offer or too close to it... I'm sure they'll get plenty of takers for this years though - including me!
Still trying to figure out how to subscribe! It shows up in my HL account but the ‘deal’ tab is greyed out. Any idea how ‘not to miss out?’ Is there a date or does it automatically subscribe?
You need to click on the second tab in options in the Geiger Counter line.
Sorry, actions not options.
Request please for thoughts on the possible takeover approach for Intertek (LON:ITRK) yesterday afternoon. Management clearly see it as opportunistic and this was maybe the reason why they recently announced the prospect of splitting the business in half to unlock value. I hold.
Request please for thoughts on the possible takeover approach for Intertek (LON:ITRK) yesterday afternoon
It's just too low, especially given that it's one of only three global Testing, Inspection and Certification companies - £51.50 is simply running an offer up the flagpole. You'll need something in the region of £56 to get board approval, maybe even £60.
I was buying in the mid-30's recently: some of the valuation disclocations in the UK market are simply stupid, even allowing for that being in the middle of an outbreak of Trump Derangement Syndrome (Middle East version).
timarr
I'm sorry I didn't get around to that sparkler!
I'm so glad I joined Stockopedia to learn about MGNS from 2019 on. It's been a real success story for those who have stayed on the journey. I'd be very interested in an update, though I would naturally relent if you want to concentrate on others.
Andy, I did get to look at MGNS, thanks for the solid request! G
Thank you, Graham. Good news. Enjoy your weekend.
IDHC results impress again today.
Net profit up 29% (adj. 79%) on revenue increase of 37%. EBITDA up 61%. Improved margins on top of sales increases with prospect of continuing growth.
Not sure if you comment on this company but it seems worth considering?
All looks good , although one thing that struck me was the tiniest dividend i have ever seen at less than one cent USD 0.0085.
The Government are changing the rules again hitting renewables through removing Carbon Price Support ("CPS") with effect from April 2028. It looks like this will reduce power prices across the board. Greencoat UK Wind (LON:UKW) have put out an RNS this morning. I suppose long-term power prices had been edging-up a little, but that has now been taken away. Not much fun holding renewables of late. RPI to CPI last year. Never ending hits to their valuations!
I decided a while ago that the renewable ITs were uninvestable due to the constant change in regulations (and the opacity of how the NAVs are calculated)
Not sure I understand the Greencoat statement, they say they assumed a decline in their model, profit margin? then say 3p NAV decline in 2 years time. They don't help themselves with clarity. I hold.
£UKWS
based on text below it loks like this is a amangeable change - ok perhaps not non material if scrapping has been brought forward - but sounds like it was most expected - just accelerated somewhat - fair play to politicians if they are doing whatever they can to keep energy prices down - or even if they arent doing everything something is better than nothing.
The forecasts in the Investment Manager's valuation assumptions had anticipated that CPS rates would reduce significantly. Further, CPS was expected to become less meaningful to electricity prices in the longer run as UK renewable generating capacity expands and carbon emitting generators set the marginal price less frequently. Yesterday's announcement brings this forward.
from efficiency point of view if this is just extra hassle to calculate and bill everything - thats win win win situation for everyone other than the ones directly benefiting even then those that beenfit probbaly had admin hassles. Hopefully its positive signs that stuff like this can be removed without moving the dial - renewables need to stand on their own two feet sooner or later.
Good morning Graham, I don't suppose you would like to check out the long term incentive awards for Serica's CEO and CFO announced today? Such large figures do confuse me so.
The D Telegraph will ignore it, fail to drill, of course. Tee hee.
Surely nothing to see - representing 0.416% of the shares in issue ... I don't see a major issue here and the team don't appear overpaid to me. Vesting shares over a 3 year period with lock-ins that follow seem consistent with shareholders to me..... and you do want management incentives to be competitive.
Thank you RDH, that's cleared that up. I holdSerica Energy (LON:SQZ)