Daily Stock Market Report (Fri 17th July 2026) - BRBY, ALU, SNWS, EYE, NTBR

It's been a long time since I shorted anything. Buying a few out-of-the-money Tesla puts several years ago was the last time that I couldn't resist having a flutter on the collapse of something (it didn't work out).
But I must admit that when SpaceX IPO'd, I did spend one or two evenings looking at the option chain and checking how much it would cost to bet against the thing (spoiler: it was horribly expensive - the more volatile a stock is, the more expensive it is to buy options on it).
My failure to bet against it is already causing me to experience FOMO as I read headlines like this:
Short sellers notch $8.7 bln profit as SpaceX shares dip to IPO price
There are remarkable estimates of short interest being bandied about, such as "almost half of SpaceX's tradable shares, about 49% of the free float".
CNBC reports a different estimate, but one that is still very high:
"About 185 million SpaceX shares are now sold short, representing roughly 29% of the company’s publicly tradable float and about $25 billion in bearish wagers"
Part of the difficulty is that SpaceX free float itself is very low, at less than 5% of outstanding shares. The short interest has to be measured against an estimate of the shares that can be publicly traded outside of various lockup agreements.
What I find interesting is that the sources quoted by both Reuters and CNBC say that shorting is being driven primarily by speculators, not by people hedging their long positions.
I find that a little hard to believe, although legally it makes sense: all of those SpaceX investors who are subject to lockup agreements are not supposed to be selling the stock short, in order to lock in their enormous profits. It must be very tempting for them to do so.
Looking ahead, huge numbers of SpaceX shares will see their lockup agrements expire this year. I think I'll be scanning this option chain on a regular basis.
Overnight market movements:
The FTSE is down 0.3% at 10,525
S&P 500 is down 0.8% at 7,475
Brent crude (September) is down 0.6% at $85.50/bbl
Gold is up 0.4% at $3,990/oz
Bitcoin is down 1.8% at $63,000
Spreadsheet accompanying this report: link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Wise (LON:WISE) (£11.8bn | SR68) | Cross border volume +26%. Net revenue +25%. “Re-iterating our FY27 guidance: Net revenue growth around the middle of our 15-20% medium-term target range on a constant currency basis... Income before tax margin around the top of the 20-25% range.” | ||
Burberry (LON:BRBY) (£4.1bn | SR44) | Q1 comparable retail sales +5%. Total retail revenue +4% at constant exchange rates. Americas +12%, EMEIA minus 3%. “In the full year we expect to make further progress on our financial ambitions, including delivering revenue growth and margin expansion, in line with expectations.” | AMBER = (Graham - I hold) The trading update is nothing special - and the share price reaction reflects that. The reference to the “uncertain geopolitical and macro-economic environment and its potential impact on consumer confidence” is the type of remark that tempers expectations. While I’m still positive on the long-term outlook here, our colour rating is based on a shorter-term outlook. With the recovery still needing a few years to play out, and with plenty of short-term uncertainties, I’ll leave us on AMBER for now. | |
Bridgepoint (LON:BPT) (£2.8bn | SR41) | AUM +12.4% to $97.3 billion. Fee paying AUM +32.7% to $58.4 billion. H1 underlying EBITDA +77.6% (£227.3m). PBT £42.9m. “Looking ahead, we are making excellent progress in fundraising and there is a good transaction pipeline in place for the second half of 2026 and beyond.” | ||
Ninety One (LON:N91) (£2.2bn | SR66) | AUM improves from £171.8bn (March 2026) to £184m (June 2026). | ||
Smiths News (LON:SNWS) (£166m | SR98) | New long-term contracts with Frontline (the UK's largest magazine distributor) and Seymour (part of the Frontline Group and the UK's largest independent magazine distributor). Expands the distribution territories across all of GB from April 2030. Extends contract term through to April 2037. Incremental uplift in Smiths News' revenue of c.£105m per annum across the expanded territories of Great Britain from April 2030. An expanded national footprint is needed, as stated previously. | GREEN = (Graham) | |
Eagle Eye Solutions (LON:EYE) (£141m | SR61) | SP +8% The target to achieve an exit EBITDA margin run rate of 20% has been materially exceeded in H2, resulting in adjusted EBITDA for the year of £9.8m, materially ahead of previously raised market expectations. Has entered FY27 with strong momentum. | AMBER/GREEN ↑ (Graham) [no section below] I'm nervously upgrading our stance here, on the back of today's "materially ahead" update. Roland noted in January that the shares were trading on a FY27 P/E of 30x, but the share price is up by a further 44% since then. Checking the note from house broker ShoreCap, I see that today's update sees them raising FY27 and FY28 forecasts by a modest 2%. With new adjusted EPS forecasts of 11.7p (FY27) and 16.1p (FY28), the forward P/E multiple is now 43x (FY27), falling to 31x (FY28). This "AI-powered loyalty and personalisational platform" for retailers is enjoying the type of bullish valuation that befits an AI stock in the current climate, and who am I to argue? Current earnings are arguably not too revelant: if we value it on a multiple of ARR, it's only trading at 3.5x, which is not expensive in a SaaS context. So I'm comfortable with us being moderately positive here. | |
Alumasc (LON:ALU) (£83m | SR50) | Full Year Trading Update & Suspension of CEO & Changes in Leadership | Resilient overall performance. Revenue £107m (FY25: £113m). Underlying PBT £10m (FY25: £14m). CEO suspended by the Board pending an investigation into matters relating to her professional conduct. | BLACK (RED ↓) (Graham) In cases of possible misconduct, I think what shareholders probably care most about is whether they’ve been misled re: company performance. As a shareholder, you can financially survive a wide variety of executive transgressions, but you can’t necessarily survive that one. You don’t want to wake up one day and learn that you own a Patisserie Valerie. But there doesn’t seem to be any evidence of that here, at least not yet. I am still going RED today on this building products supplier, due to the accumulation of poor news. Today’s update also leaves a lingering uncertainty over what the investigation might find. |
System1 (LON:SYS1) (£41m | SR67) | BBSN posted a presentation on its website yesterday re: its offer for System1. System1 has consulted with some of its major shareholders. This consultation is ongoing but feedback to date has confirmed the Board's view that the Possible Offer materially undervalues System1 and does not represent fair value for System1 shareholders. | TAKEOVER | |
Getbusy (LON:GETB) (£34m | SR27) | Chairman steps down after nine years. Successor appointed with immediate effect. | ||
Amigo Resources (LON:AMGO) (£27m | SR88) | CEO appointed. He joins Amigo following an 8.5-year tenure at TerraCom Limited (ASX: TER), a producer previously included in the S&P/ASX 300 Index, where was Chief Commercial Officer and Chief Financial Officer. | ||
Itaconix (LON:ITX) (£16m | SR25) | A record first half with revenues at $8.3 million (+72% vs H1 2025). “Whilst re-order rates are yet to be firmly established, the Board now expects revenue for the year to 31 December 2026 to be no less than $14.8 million, ahead of current market expectations.” Continues to expect a small positive EBITDA for FY 2926. | ||
Fulcrum Metals (LON:FMET) (£12m | SR17) | “Since the publication of our Annual Report, we have continued to deliver against our stated objectives.” |
Backlog
Northern Bear (LON:NTBR)
110p (£15m) - Preliminary Results - Graham - GREEN =
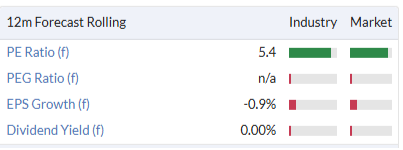
This group of building services companies has attracted a following among the nano-cap value investors, for obvious reasons:
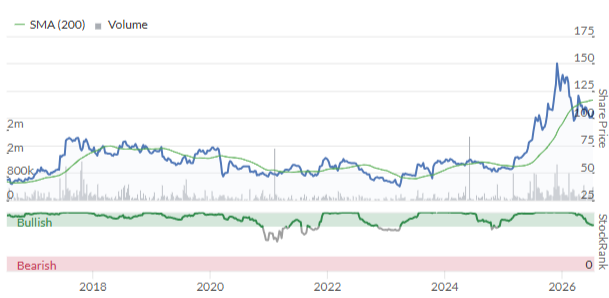
The shares have already doubled since early 2025:
FY March 2026 results were posted yesterday:
Revenue +10.2% to £86.1m
Operating profit of £5.1m (2025: £3.4m)
Adjusted operating profit £3.8m (2025: £3.8m)
£3.8m is a more realistic profit figure than £5.1m. Here’s the explanation for the difference between operating profit and adjusted operating profit:
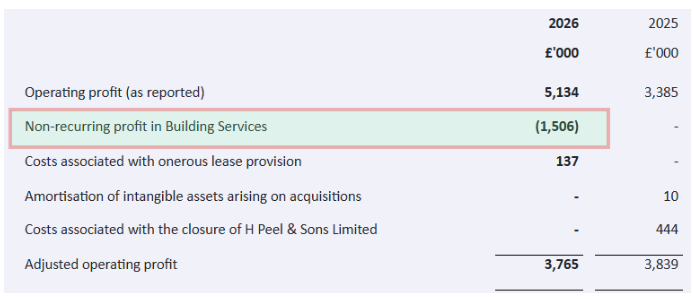
The “non-recurring profit” relates to some non-recurring contracts which the company has helpfully designated as such, so that we don’t expect them to occur again in FY27.
Net cash is £6.2m, which at this market cap is a significant number. But don’t take it for granted: it’s volatile. Management have acknowledged that they “saw strong advanced payments from our customers prior to 31 March 2026, particularly from our public sector clients”, and that this boosted the cash figure.
They also say, very transparently:
As we have emphasised in previous years' results, our net cash (or net bank debt) position represents a snapshot at a particular point in time and can move by up to £1.5 million in a matter of days given the nature, size and variety of contracts we undertake and the related working capital balances.
The lowest cash position during FY26 was £0.6 million net cash, the highest was £6.2m net cash and the average was £3.3m net cash.
If only every company was so transparent!
Dividend: it’s nice to see such a small company paying a dividend. There is a 5p special dividend on top of the 2.5p ordinary.
Outlook
Our forward order book remains robust and we continue to see a pipeline of opportunities across the Group, supported by the investments we have made in our businesses. While the operating environment remains challenging, we believe these investments have strengthened our market position and provide a solid platform for future growth…
Conclusion:
Given the political changes on a local and national basis, we are experiencing some delay in the decision-making process within both the public and private sectors.
We have made a stable start in FY27 and are trading in line with management expectations.
Graham’s view
I was GREEN on this last November at a market cap of £18m and a share price of 124p.
While I generally shy away from being too positive on companies with such small market caps (due to delisting risk), this is a case where I’m happy to make an exception.
It’s profitable, has a net cash position, pays a dividend, and is more transparent to investors than it needs to be or is typical for a company of its size.
Against that, this stock certainly should be cheap, given the sector. But it is. Adjusted earnings per share are 22p, against a share price of 110p, for a trailing PE 5x. I think this is still worthy of a positive view from us.
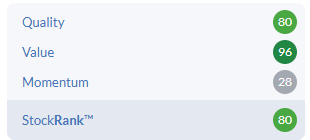
Stockopedia views it as Contrarian, which makes sense. The ValueRank is a tempting 96:
Graham's Section
Burberry (LON:BRBY)
Down 4% at £10.71 (£3.86bn) - First Quarter Trading Update - Graham - AMBER =
(At the time of writing, Graham has a long position in BRBY.)
We’ve been neutral on this turnaround story, as the market cap has seemed to already price in the company’s expected financial improvements:
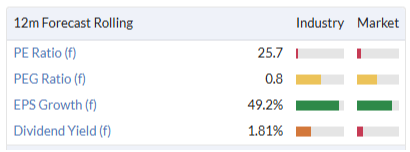
Looking forward to FY March 2028, for example, the P/E multiple is still quite strong at 19x (based on a net income forecast of £200m and EPS of 55.9p).
During a prior era of success, Burberry generated net income of c. £400m, but that sort of result is not expected in the near future.
Fortunately, the direction of travel remains positive. Today’s Q1 update:
Retail revenue +4% at constant exchange rates
Comparable retail sales +5%
There’s a wide disparity between geographies. With conflict in the Middle East, EMEIA (Europe, Middle East, India and Africa) comparable sales fell 3%. Americas, by contrast, are up 12% and Greater China is up 9%.
Within the operational highlights, these two points stand out to me (emphasis added):
Product and pricing strategy is working, delivering value for money in a luxury context across each category and good/better/best price tiers
Continued customer growth, led by Gen-Z up double-digit
“Value for money in a luxury context” is an important reference to positioning - the need to maintain luxury profit margins while still remaining within reach of the target customer base.
The reference to Gen-Z is also important - customers born between 1997 and 2012, who are still in their 20s. Double digit growth in that cohort means the company is staying relevant for the next generation of luxury shoppers.
Outlook:
As we look ahead, we are encouraged by the progress of Burberry Forward and will continue to build on it to drive performance and deliver sustainable long-term value.
In the full year we expect to make further progress on our financial ambitions, including delivering revenue growth and margin expansion, in line with expectations. We remain mindful of the uncertain geopolitical and macro-economic environment and its potential impact on consumer confidence.
Graham’s view
The trading update is nothing special - and the share price reaction reflects that. The reference to the “uncertain geopolitical and macro-economic environment and its potential impact on consumer confidence” is the type of remark that tempers expectations.
Personally, as a long-standing (long-suffering?) shareholder, I plan to continue holding this one. The forecasts out to FY29 suggest that net profits will continue to grow and exceed £250m by FY March 2029. FY29 sounds very far away, but that financial year starts only about 20 months from now.
Granted that much can go wrong between now and then, and there will inevitably be unwanted macro events during this timeframe.
But in general, when Burberry is performing well, I expect it to enjoy a P/E multiple in the region of 20x. So I’m hoping for a market cap of c. £5bn on profits of £250m+, or a share price in a couple of years about 30% higher than the current level, and with scope for profits to continue recovering towards historic levels.
And with the company profitable, that will also allow management some pleasant decisions on how to reinvest in the business over the next few years.
There’s no guarantee that any of this will happen, but I think the smoke signs are positive with positive comparable store sales and encouraging operational highlights.
The StockRanks are not convinced:
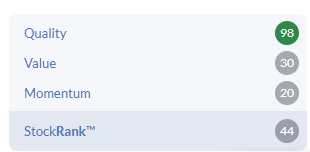
While I’m still positive on the long-term outlook here, our colour rating is based on a shorter-term outlook. With the recovery still needing a few years to play out, and with plenty of short-term uncertainties, I’ll leave us on AMBER for now.
Alumasc (LON:ALU)
Down 6.5% at 215p (£78m) - Full Year Trading Update & Suspension of CEO & Changes in Leadership - Graham - BLACK (due to suspension of CEO) (RED ↓)
Let’s get straight into the shocking piece of news here (emphasis added):
Alumasc (ALU.L), the premium sustainable building products, systems and solutions Group announces that CEO, Pamela Bingham, has been suspended by the Board pending an investigation into matters relating to her professional conduct. The Company is undertaking a full investigation, supported by its professional advisors.
The non-Exec Chair becomes Exec Chair “temporarily”, supported by Division MDs and the CFO.
This is a short RNS, concluding:
As set out in the trading update provided this morning, the Group continues to deliver a very resilient performance amidst a challenging market backdrop, and enters the new financial year with a significantly expanded order book. The Company will make further updates to shareholders in due course.
It’s important not to jump to conclusions, but it’s clearly a worrying moment for Alumasc shareholders.
Those worries are partly alleviated by an ok trading update, which says that performance is “broadly in line with the expectations set at the Q3 trading update”.
Full-year revenues for FY June 2026 have fallen from £113m to £107, and underlying PBT has fallen from £14m to £10m.
Net debt is modest at £7m, with a low leverage multiple of 0.5x.
Some colour is provided on each division - Water Management, Building Envelope, Housebuilding Products. Of these, the Water Management division has struggled the most in FY26:
The Water Management division has been particularly affected by adverse market conditions, and faced a tough prior year comparator that included significant revenues from its contract at CLK airport in Hong Kong. Excluding sales to the CLK project, divisional revenue was modestly behind the prior year, with lower UK revenues partially offset by an increase in overseas volumes.
Graham’s view
The good news is that regardless of the circumstances surrounding the suspension of the CEO, there doesn’t appear to be any particular impact on company performance. We already knew that the company was not doing all that well against prior expected performance.
In cases of possible misconduct, I think what shareholders probably care most about is whether they’ve been misled re: company performance. As a shareholder, you can financially survive a wide variety of executive transgressions, but you can’t necessarily survive that one. You don’t want to wake up one day and learn that you own a Patisserie Valerie.
But there doesn’t seem to be any evidence of that here, at least not yet. Performance is “broadly in line” with downgraded expectations.
I’m still going to mark this story “BLACK” as the suspension of a CEO is at best a serious distraction. The best-case scenario is that employees and senior management (and possibly customers and suppliers) are distracted, until it’s resolved.
A more typical outcome is that there’s an expensive and unexpected change in senior management.
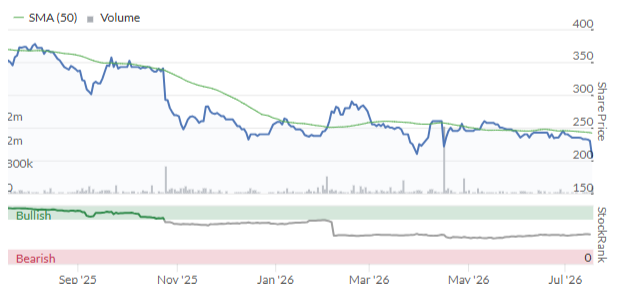
We were already AMBER/RED on Alumasc after an April profit warning. I am going RED on this building products supplier today, due to the accumulation of poor news. Today's update also leaves a lingering uncertainty over what the investigation might find.
This is one Contrarian stock that I’m not interested to bet on:
Smiths News (LON:SNWS)
Up 3% at 69p (£171m) - National Contract Awards - Frontline and Seymour - Graham - GREEN =
More good news from Smiths News. It already made two similar announcements to this one, and now we have another.
It has secured new long-term contracts with Frontline (“the UK's largest magazine distributor”), and Seymour, (“part of the Frontline Group and the UK's largest independent magazine distributor”).
I’m slightly confused about the distinction between these two companies, or whether there is any distinction. Checking their respective websites, I am going to treat them as the same entity, as I don't think there is any real distinction to be made.
Some details:
The agreements with Frontline and Seymour (the "Contracts") include an expansion of the distribution territories in which the Company is appointed as the exclusive national wholesale distributor for Frontline and Seymour titles across all of Great Britain (effective from April 2030) and an extension in the contract term of the Company's appointment through to April 2037.
This is similar to the prior announcements from Smiths News. Those ones related to News UK and Associated Newspapers.
There's also some great news on the revenue uplift and the market share that’s involved:
The Contracts together are expected to represent an incremental uplift in Smiths News' revenue of c.£105m per annum across the expanded territories of Great Britain from April 2030. Combined, the Frontline and Seymour portfolios account for over 60% of the UK magazine market.
That’s an enormous chunk of market share and the revenue uplift involved is material. Smiths News revenues are running at around £1bn annually.
Graham’s view
The revenue uplift from all of the contract announcements made here so far are set to generate a collective revenue uplift for Smiths News of over £300m, or 30% on the existing revenue base, when they go into force.
It won’t be free: the company is going to have to spend big on expanding its distribution network, and it hasn’t given us guidance yet on how much that is going to cost.
It's also possible that some contracts may be lost. But there is a qualitative difference between the new contracts and any old contracts that might be lost: the new contracts are on a truly national basis, which Smiths News hasn't achieved before.
Far from being a cigar butt stock that is on its way to extinction, these announcements make the company seem like a growth business with some exciting capex opportunities.
And yet it’s only trading at around 7x earnings:
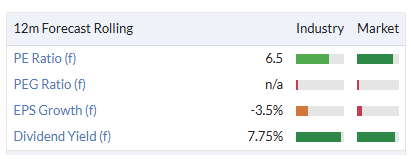
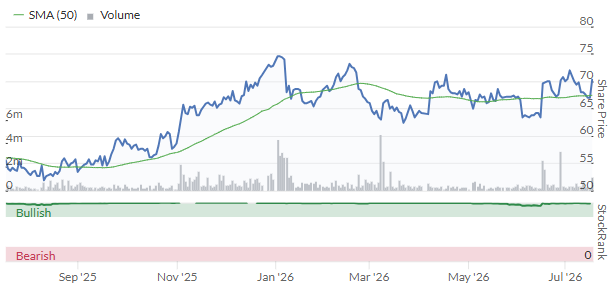
Deaf to all of arguments about the inevitable decline of newspapers and magazines, the StockRank is 98.
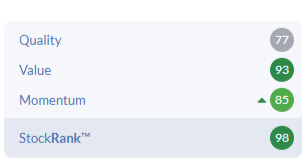
I was GREEN on this before, and today’s announcement only cements my stance.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

66 comments
Thanks for the update on Smiths News (LON:SNWS). I was impressed by a presentation at Mello a few years back and has been on my watch list ever since.
Seems we have to wait until November to see the impact of these new contracts on the bottom line ?
As previously announced, key to delivery of all four contracts secured to date will be the establishment of an expanded national footprint. Guidance around the implementation costs, early-life transition costs, benefits of network expansion, as well as dividend and financing arrangements, remains unchanged from our announcement on 17 June 2026. The Board expects to provide further guidance on the financial effects of all contracts in due course and, in any case, at the time of its preliminary financial results on 4 November 2026.
I belong to the Chartered Institute of Management Accountants and had stopped reading the online monthly magazine. I was very surprised to see it brought back into paper copy for all members and have started looking through it again when it gets delivered. Maybe print is not dead yet ?!
Experienced and successful investors generally take and view any price movements on options expiring week (especially during the third week of the month!) as pure noise.
Gamma hedging, liquidation and rollovers take centre stage!
Space Exploration Technologies (NSQ:SPCX) experienced a massive OCT $100/$150 bullish risk reversal…….
I do not hold, but I disagree with the opening statement of today’s morning report.
All the best
Another else been using https://shorttracker.co.uk/?
Just saw today that its now been taken offline!
What other website is good for quickly looking up short positions of UK companies?
Another else been using https://shorttracker.co.uk/? Just saw today that its now been taken offline!
This is an effect of the new FCA rules which mean only aggregated positions are published rather than individual short positions - so the FCA public short positions report where shortracker got their data from has been taken offline.
You can get the aggregated daily report at 12.00 daily directly from the FCA.
I'm sure we'll all agree it's worth the FCA spending their time on this rather than, say, trying to improve the liquidity of the UK stockmarket.
timarr
That's a shame! A pity they've removed the granular data.
For anyone else interested, here's the direct FCA link to the daily updated Excel file... https://www.fca.org.uk/publica...
Would be good if a website took the daily file, and for each company, built a page with the historical data and charted. Looks like I need to see how to build an AI agent to do this retrieval daily and extract into a database for my own use... annoying.
And what a wonderful page they've replaced it with
Alumasc - Is the Chair the same Vijay Thakrar who was Chair of Treatt (a sad story) who also made a very poor CEO appointment?
That's a good point, Heron, I hadn't thought about the same Chair at both companies. Sad end for Treatt and not a good look for Alumasc (LON:ALU) after just a few months in the job for the CEO. Hopefully, the issue (whatever it is) won't be too damaging to the underlying business.
I would like to sincerely thank all those who took the trouble to reply to me yesterday. Everyone was so positive my heart is overriding my head and I'm going to stay for now, hopefully reducing the risk profile a bit.
Wow, Funderstruck, hope I'm still as actively involved as you in 10 years time. Thanks to to Ken Mitchell for your comments re Investment Trusts, everything that increases my knowledge is always welcome, and I've always admired your dedication through what was/is obviously serious illness. Thankyou all and good luck for the coming years
Slow to catch up on your contribution yesterday- because at 86 that’s the way I run my portfolio. My state pension and my private pension look after most daily needs, topped up occasionally with dividends from our old faithfuls, Chesnara (LON:CSN) and Legal & General (LON:LGEN) (though mostly these are reinvested). Top up with mainstream Investment Trusts and Smartgarp unit trusts from Artemis; and a few decent long term promising individual shares like Rotork (LON:ROR) and Craneware (LON:CRW)! and you have a low maintenance hobby portfolio that keeps the mind active but you are not checking hourly, or even daily. But you are keeping in touch with the. Commercial world around you. This you can continue even when your body no longer allows you to walk the hills (as I used to).
Thanks scrooge, know what you mean about the walking. Think I've decided to move towards your approach thanks to all the encouraging words on this great site
Norfolk Oldboy.
I’ve just done a reply for you on the July Investment Trust thread, showing how simple it is to understand mainstream Investment Trusts. Here’s the link for the July Investment Trust thread and the many posts there:-
https://www.stockopedia.com/...
Thanks Ken, appreciated. I'm aware of the separate IT board you, Charles and several others keep up to date, which is what spiked my interest in the first place. Read it regularly. Pity Stocko don't seem to want to support them much. But I'm gradually learning.
Someone has been adverting here about a new forum similar to the one here.
I was very positive about it but when you look at the details then you understand that the whole thing is a total disaster.
How can I own a share when I have a negative view about it?-:)
AVOID!
All the best
Well Yiannos there are several answers to that one... I will put on a postcard and give to the next passing pigeon to deliver
Simple said my rules based investing means sometimes I follow the rules, even if I feel negatively about the results of the rules...
Rule #1 of Fight Club, Don't talk about Fight Club
Tommy
Yes nice answer as always!
Come back with an answer that will benefit investors.
Someone was a holder of Plexus Holdings (LON:POS) and I have explained many times that there is no investment case……like these companies I must have wrote about over 50 different cases alarming fellow investors with detailed analysis.
If I cannot do that in a forum, what’s the point? For reading all others how much they love their holdings?
I have answered to you without needing a pegion. Much quicker and makes more sense!
All the best
Interesting situation at System1 (LON:SYS1)
Bid from Brave Bison (LON:BBSN) was c317p but now trading at 338p. BBSN issued a deck on their takeover bid, but IMO it was a shoddy job and not any new substance.
Can't be because of hope of a competing bid, as BBSN has a 28% stake, can block.
Guessing market believes either BBSN will come back with a much better offer. Or investors think SYS1 is worth much more organically. Mgmt keep reiterating trading this year going well so far...
Personally, I don't think BBSN have the financial power, either cash or their own shares, to up their offer meaningfully closer to 400p or higher. I'd be a seller at a 400p+ offer but not any lower. Think that's where the shares will end up organically later this year, after the next HY results confirms strong growth and recovery.
(I hold in the Boon Fund)
Some fun remarks by redditors:
And:
Has anyone else noticed changes on the IG platform? You used to be able to get quotes prior to deciding whether to execute and it was really helpful for 'testing' the market. Now its all done via orders and you just have to trust they will get the best price for you. Really ticked off about that.
No, when did that happen? I got quotes today, same as usual.
You are talking about UK shares?
Just tried it again, same as usual. Got quote to buy Shoe Zone (LON:SHOE 62.51p
I don't use the App could never get on with it.
Oh just wait for the account migration email you will get! They are rolling it out now. I just had to sell some shares and you now dont know the price that they will execute at. You have to leave it in their hands.
edit: the option for 'Order Type' is now only variations of the 'limit'. The ability to get quotes will be removed.
Place every order as a limit order and you will not get any surprises, although of course this is a little more faff and hit or miss in terms of whether your deals will go through.
What type of IG account / plan do you have?
Thanks boring - standard isa account. It was just handy to know what price you were getting previously and to have that short window to execute either way. Particularly when its a fast moving market, I can imagine a time when there is bad news and you have to exit and now it has to be left in their hands to get the best price. Probably now means I need to get L2 access to view the supply / demand side rather than seeing what the market would take either way via quotes. Nice work IG. I will give it a few weeks, but might be time to find a new provider.
I've now done digging into whether IG offers L2 data.
And interestingly, I found that it does... and it does for free!
If you login on the website on a computer, and go into Settings. There's an area called Data Feeds where you can opt in to L2 data. For me, its showing as £0 for LSE and Aquis!
And then if you go into My Workspace where you see details of your portfolio... if you open up any share... and then go to Deal, you should see this table below that has the order book. Seems like only partial order book? But still useful.
I dont see that option in my settings - but I think there is a form to fill in to request it to be added. Thanks, I will see if I can get that added.
Edit - found it on the 'my ig' homepage. Thanks
Yes IG are doing a phased migration of accounts to what I think may be an IG branded but Interactive brokers account with no RSP offer.
I'll be leaving.
I'd be very interested to hear any views Graham might have on it, especially as I think he is both client and shareholder.
I do use limit orders, quite a bit and often get filled, at below the mid price, if buying. But on some shares, it only is available, on the current day, not good until complete.
Another annoying thing on quotes, was if you accept the price, often it did not complete, because the price has moved.
Not seen any emails.
This is what they say in the email
"What's being removed?
As part of this upgrade, the following features will no longer be available:
Request for Quote (RFQ) orders
You’ll no longer need to use quote orders for UK stocks. Our limit and market orders now connect you to more venues and counterparties, including market makers, so you can access competitive prices automatically, all in one place."
The reality is with smaller stocks, the only option they give you is now to limit (shoezone is limit only) whereas other shares you have the option for limit / market / stop-market.
Oh crud. I opened a Trading 212 account recently and they have this thing where you can only invest a certain amount of your money, to account for volatility.
It sounds like IG are going to be doing the same thing.
Good news from Swindon today in respect of Smiths News (LON:SNWS) which, despite the Naysayers, I have held since 2011.
p.s.I I note that in April 2022 I did bed & ISA at a massive loss, in part to reduce a Capital Gains charge and same again in April 2023 at a small capital gain offset by selling losers.
Comment deleted
Thanks for the report Graham / All - can I ask which platforms you have used to short shares in the past? I’ve recently started using SpreadEX to go long on shares - I’ve not yet had the bottle to go short - but are the views SpreadEX is good or are there other platforms that I could consider?
JARVIS
I have received an email saying that I am entitled to redress required by the FCA for misleading T&Cs re interest on cash for the period 1st October 2019 to 31st December 2024. During that period I had an x-o account (moved to ii when Jarvis pulled out of retail).
If anyone here also had an a/c and has changed address or email since it is worth following up.
Jarvis - I received this letter and responded (though I am not sure what they did wrong to me). They sent me £379. That’ll buy me a decent case of claret!
So I agree- worth following up!
Can I suggest that a separate discussion be opened for those with technical issues?
Then the specific issues can be recorded there with supporting evidence, along with which browser and OS are being used in case it affects one client configuration more than another.
The more evidence there is for issues, the greater the chance of getting them fixed (both by weight of numbers and supporting info to enable issues to be reproduced).
(And the more that the DSMR is focused on investing).
Good idea Richard but one that should have come from Stocko staff. The void in communication exacerbates the situation. For the record I am a Stockopedia evangelist who wants to see its full potential realised.
I've set up a discussion thread here:
https://www.stockopedia.com/co...
Not really sure we need a discussion for technical issues…anyone who has a technical issue just needs to use the support procedure : https://www.stockopedia.com/le...
You might well be right but I see a lot of messages saying that issues have been reported via the green button and heard nothing back. Nor does anybody know which issues have already been reported.
Stockopedia technical support staff ought to have incident/problem management under control but again, there are complaints about lack of responses so I'm just trying to find a way to help reduce the volume of complaints in the DSMR as well as, hopefully, supporting evidence for getting things fixed.
The irony being that I get very few issues myself, but I'm hardly a 'power user'.
But I must admit that when SpaceX IPO'd, I did spend one or two evenings looking at the option chain and checking how much it would cost to bet against thing (spoiler: it was horribly expensive - the more volatile a stock is, the more expensive it is to buy options on it).
I heard somewhere that only 1 in 6 new issues are above their IPO price 6 months later. So statistically, it's the way to bet, were it not for the price of doing so.
Data centres in space? Never going to happen. My mate who worked as a CTO confirmed this. Data centres require ongoing maintenance. You can't just set and forget.
Moonbases? Colonies on Mars? Musk needs to cut back on the puff-puff.
And yet he seems to prove time and again that he's worth backing.
So was Mr Ponzi for a while.
Is Musk's reputation based mainly on the technical achievements of the Tesla car, which has fallen behind his Chinese and arguably some European competitors? Or Starlink, which showed great foresight? Against these are a raft of costly failures, which he bails out by merging them ultimately with these two - if his companies had proper governance, he wouldn't have been allowed to do this.
I’m saving up for my Optimus robot. I’ll still drive till I can’t but housework.
I think timing is the most difficult issue. After 6 months the price may well be lower, but most of us would either get a margin call before then or our bottle gives in as the price fluctuates!
getting a lot of errors and having to force reload the page re. searching, news, price moves etc.
know others have had issues before so flagging it for visibility!
The site. I am a big fan of Stocko, but credibility of the offering from a technical perspective is poor currently. As an illustration searching on GGP just now the profile summary produced is that for Victrex (a stock I had been researching before moving onto GGP).
Profile Summary
Victrex plc is a United Kingdom‑based materials company. The Company manufactures and sells high‑performance polymers and polymer solutions. It develops polyetheretherketone (PEEK) and polyaryletherketone (PAEK) based materials, and produces semi‑finished and finished components, including thermo...Read more
Alumasc CEO suspended along with a profit warning - she has not been in the job that long!
For interest and those thinking of investing in China by trust or etf. ”More than 9.4 million investor accounts applied for shares in the blockbuster initial public offering (IPO) of ChangXin Memory Technologies (CXMT), with retail demand reaching about 212 times the shares initially available online.” https://www.scmp.com/tech/arti...
Yet more issues on the site this morning, and no response to the green button message that I sent yesterday.
It’s getting silly now.
Graham, can you have a word, and get someone to at least explain what’s going on?
Agreed. Every morning is turning into a battle to get Stockopedia to give you the information you need when you need it....
As England found out against Argentina, difficult situations require clear communication and strong leadership.
really bad
The Raven, I've passed on your message to someone who can help! I'm sorry I don't have the answers. G
Thanks Graham. (Just seen your message as I was on a flight yesterday afternoon/evening)
Sorry that you are having issues with the site. I know how frustrating it is to keep running into the same problem, and rest assured we are not happy with it either.
To be clear about where things stand: we've identified the root cause. It's an issue in the application server our platform runs on, which surfaces during sudden spikes in traffic and can leave parts of the site slow or returning errors until the affected processes are restarted. It's intermittent by nature, which is part of why it's been stubborn to pin down.
A permanent fix for this is being worked on at the source, but it isn't in a stable release yet. What I can tell you is what we're doing in the meantime: we're actively applying changes on our side aimed at reducing how often this happens, limiting the impact when it does, and responding quickly, in and out of hours, to restart the affected components and get things back to normal as fast as possible.
It's a genuine priority for the team.
Apologies again for the disruption.
Thanks Oliver (Just seen this as was on a flight yesterday afternoon/evening)
Northern Bear (LON:NTBR) I hold
A lean list of RNS's today, is there a chance you could revisit yesterday's results for Northern Bear please?
yes, I'm intending to cover the backlog, happy to take requests. G
Took me a while but I eventually got around to NTBR! thanks for the request, and have a good weekend! G
Northern Bear (LON:NTBR) I hold
Much appreciated Graham. I think your appraisal is very fair and aligns with my own view which is reassuring. Have an enjoyable weekend yourself.
EAGLE EYE SOLUTIONS: FY26 UPDATE BEYOND ALL EXPECTATIONS
Trading SMASHES upgraded market forecasts
ARR SOARS +31% to £44.5m | EagleAI revenue +34%
Adjusted EBITDA £9.8m – £2.8m ahead of consensus
Net cash +31% to £16.1m , zero debt, strong firepower
Recurring revenue hits 87% > predictable, high-quality earnings
MASSIVE H2 MOMENTUM:
• Wins: Subway, easyJet, top UK health & beauty retailer + French grocer POC
• Renewals: 5yr Woolworths, 2yr Auchan; expansions with Asda, Carrefour, Morrisons
• Global OEM partnership live , first contracts secured, set to drive growth in FY27
• NRR stays elite at 111% , customers spend more year-on-year
OUTLOOK: FIRMLY BACKED FOR DOUBLE-DIGIT GROWTH IN FY27
On track to hit medium-term targets: £100m+ revenue & 30%+ EBITDA margin
Wise (LON:WISE)
Morning all and Happy Friday!
A few thoughts after yesterday evening’s Q1 FY27 trading update and earnings call.
Wise appears to have carried its strong FY26 momentum into the new financial year.
Operationally, the investment thesis continues to play out broadly as expected.
Wise continues to attract more customers, those customers are moving more money, and—perhaps most importantly—they are entrusting more of their everyday finances to the platform.
Customer holdings have now exceeded $41 billion, reinforcing the gradual shift from being simply a low-cost international transfer service towards becoming a broader financial infrastructure business.
One broader trend that continues to encourage me is the increasing diversification of the business.
Revenue is becoming less dependent on cross-border transfers alone and increasingly reflects customer balances, card usage, account activity and other services.
That feels consistent with management’s long-term ambition of building financial infrastructure rather than simply offering a cheaper way to send money internationally.
Over time, a broader mix of revenue should also make the business more resilient.
The earnings call itself added a few encouraging points.
Business customers continue to outperform consumer growth, with Wise Business volumes growing 39% year-on-year.
Management also highlighted particularly strong momentum in North America, where both business activity and card usage continue to accelerate.
If Wise can keep moving up the value chain from consumers to SMEs and, over time, larger enterprises, the addressable opportunity becomes ever larger.
Wise Platform also continues to make encouraging progress and is remains one of the most underappreciated aspects of the investment case.
Emmanuel Thomassin commented that it now represents around 6% of total cross-border volume, compared with around 5% previously.
He again described Platform as “the best way to acquire customers”, emphasising that by integrating with banks and enterprises, Wise can reach millions of end customers through a single partnership.
On pricing, management again reinforced what I consider one of the defining characteristics of the business.
Emmanuel reiterated that price reductions are made from a position of strength. As the network becomes more efficient, Wise deliberately shares those efficiencies with customers through lower prices.
That aligns with Nick Sleep’s concept of Scale Economies Shared, where economies of scale are reinvested into the customer proposition rather than simply expanding margins.
If volumes continue to grow while take rates gradually decline, it’s not evidence of a weakening business. Instead, it is management executing the strategy they have consistently articulated for years.
Belgium remains the principal uncertainty in the investment case, but there was no new information in either the trading update or the earnings call of any note. My view remains unchanged and I’ll continue to monitor developments as they emerge.
One thing I’d have liked to hear more about was new Wise Platform partnerships. Following the full-year results, management had sounded optimistic about the pipeline, but there were no major announcements this time.
However, commentary remained positive, and I feel this is more a question of timing than directional change.
The growth engine appears intact, the strategic direction remains consistent, and management continues to prioritise strengthening the network over maximising short-term profitability.
Overall, I came away from both the trading update and the earnings call with my long-term investment case reinforced rather than changed.
The growth engine appears intact, management continues to allocate capital rationally, and the strategic direction remains entirely consistent with what they’ve been communicating for several years.
So why the market reaction?
My suspicion is that parts of the market still struggle to value deliberate take-rate compression.
If you believe lower prices are evidence of competitive pressure, the update looks disappointing.
If you believe they’re the result of falling costs and a conscious decision to reinvest efficiency into the customer proposition, then the same update looks rather different.
I think the question is exactly as you say below, revenue is continuing to grow and looks impressive but profit is not running with it our ideally running ahead of it with operational gearing kicking in, great if that comes back in the future, but if this is a slowing or continued decreasing pattern with others following into the market and eating the side dishes is PE of 21 right?
I think that’s the key distinction.
I don’t think the update actually showed Wise becoming less profitable.
They reiterated guidance for an IBT margin around the top of their 20–25% target range.
The debate is really whether management should allow operating leverage to expand margins further, or continue reinvesting much of it into lower prices and growth.
That’s a strategic choice rather than evidence that operational gearing isn’t there.