Daily Stock Market Report (Fri 17th October 2025) -Risk-off, DUKE, PFC, TON, EMG, SHI

Good morning! It's another sleepy Friday in RNS-land, but I'll try to pick out the most interesting stories for you.
Signing out for the week, have a great weekend everyone!
Risk-off: despite the paucity of company news, that hasn't stopped markets from swinging and the FTSE is down by 1.5%, led lower by the banks. Asian markets were weak overnight.
Barclays (LON:BARC) s is down by a remarkable 5.5%.
Perhaps I should remind readers of the 3-year chart for Barclays, in which this 5.5% fall is just a blip:
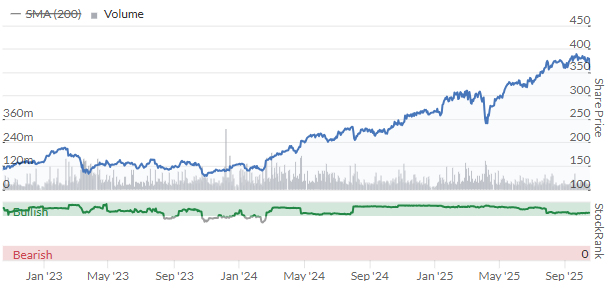
Despite this incredible 3-year return, the stock is still only trading at a PER of 8x.
As always, investors want a tangible explanation for today's movement, and the media is providing it: fears over credit exposure at regional banks in the US. A US car parts company ("First Brands") and a used-car dealership that provided financing to people with poor credit ("Tricolor") went bankrupt recently, with financial repercussions for their banks and other counterparties.
On top of that, the market is trying to digest President Trump's threat to impose a 100% tariff on Chna, and of course the ongoing geopolitical tensions rumble on (Ukraine-related news has been particularly loud in recent days).
If anyone wants my opinion - this is just typical noise in the markets. Of course we could have a 2008=style banking collapse on Monday that could make me eat my words. But we could have that any time. I don't see why I should be more worried today than I was last week. First Brands and Tricolor actually filed for bankruptcy last month, not this month. And of course Trump is going to threaten tariffs - that is what he does. And the Ukraine issue is nothing new.
Here's a simple hack that I do with my own portfolio: I do not measure how much my portfolio or my individual shares have changed in value on a daily basis. I can see what they are worth every day, and if I can remember what they were worth yesterday, then I could work out how much their value has changed. But I have no interest in knowing that I am up 1% today, or down 2%, or whatever. That's not going to be useful information, because I'm not going to base any decision purely on daily percentage movements. And as I'm not going to base any decisions on that information, I prefer not to know it.
Someone who is making more short-term trades, or investing based on momentum, might need that information. But I think that long-term investors might not need it at all. Not knowing works for me, at least I can say that much. And I like to think that this hack helps me to mimic the truly great investors: those who forgot the password for their brokerage account, and were therefore prevented from tinkering with their portfolio.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Smiths (LON:SMIN) (£7.7bn) | Sale at an enterprise value of £1.3bn, being 15.1x headline EBITDA, to be paid in cash by Molex (part of Koch Industries). | ||
Pearson (LON:PSON) (£7.0bn) | On track to deliver on 2025 market expectations, exps being underlying sales growth 4% and adj. op profit £656m (depending on GBPUSD exchange rate). | ||
Man (LON:EMG) (£2.2bn) | SP +7% AUM grows from $193bn (June 2025) to $214bn (Sep 2025). Net inflows $10bn, investment performance $10bn. | AMBER (Graham) [no section below] This is the world's largest publicly-traded hedge fund, and sits in its own category separate to the more conventional active fund managers we track in this report. Today's update shows very strong inflows of £10bn that are driven by Man's "long-only" category, rather than the "alternative" category that we typically think of, when we think of hedge fund strategies. Long-only strategies saw net inflows of nearly $11bn in the quarter, which was over 10% of starting AUM - very impressive. Mark was cautious on this share back in April, for good reasons, but I think a neutral stance is fairer at this stage: earnings forecasts for FY25 and FY26 were on the decline then, but now appear to have stabilised. In term of the bigger picture, this share has never really interested me as a long-term investment, as I'm inclined to think that in the competitive world of hedge funds, firms are better owned by hedge fund managers themselves, rather than the investing public. In its favour, it has been a very solid dividend payer, and it currently yields 7%. The StockRanks agree with my neutral stance, giving it a mild 62. | |
Helical (LON:HLCL) (£254m) | “Significant activity across our exciting development pipeline, with construction progressing on our three live office development sites.” | ||
Duke Capital (LON:DUKE) (£144m) | £3.7m investment to enable Bay Broadcasting Limited to acquire Galway Bay FM. | AMBER/GREEN (Graham) [no section below] It’s a theme we’ve noted before that Duke’s investments are frequently designed to enable acquisitions by the companies that Duke is investing in - a feature which I do view as somewhat risky in comparison to funding organic growth. On the most recent occasion, the acquisition being funded was a care home. In this case, it’s a radio station in the West of Ireland. Duke has built a large position in Step Investments over the years, with total financing now of £15.2m. The Step portfolio has had one or two serious problems, but the radio stations have been pretty solid performers within it, as far as I can tell, and it has continued to pay what it owes to Duke. I should add that the price tag for Galway Bay announced today does not seem particularly expensive. We are AMBER/GREEN on Duke and I’m happy staying that way today. | |
SIG (LON:SHI) (£107m) | Full year expectations unchanged. LfL revenue in Q3 flat. Expectations: underlying op profit £31.6m (range £30 - 35m). Demand is "well below historical levels" and the company says it it "performing well relative to its markets". | RED (Graham) [no section below] We've been RED on this suplier of insulation and building products, due to poor profit numbers (i.e. losses) and a shaky balance sheet including significant financial debt along with heavy lease liabilities. The underlying operating profit forecast sounds very impressive at £31.6m, but the list of "Other items" excluded from it is long: amortisation, impairment, restructuring costs, cloud-based ERP implementation costs and "other specific items". So forgive me for being sceptical when it comes to what the actual bottom line might be! The company has a new CEO and I wish him well, but this is not a stock where I'm excited for shareholders' prospects. LfL growth year-to-date is 1% and only a major upturn in construction activity can fix this. | |
Town Centre Securities (LON:TOWN) (£54m) | “A year of continued resilience”. LfL portfolio valuation down 2.4% year-on-year. Net assets 266p (SP: 127p). Pre-tax loss £3.4m. | ||
Wishbone Gold (LON:WSBN) (£42m) | CEO: “Diamond drilling is now on double shift… we are ramping up activities to expedite exploration… results arriving soon from the first drill hole…” | ||
Petra Diamonds (LON:PDL) (£37m) | 10 for 17 fully underwritten rights issue, update on refinancing | £18.8m rights issue underwritten by existing shareholders. Bank debt extended to Dec 2029, Notes extended to March 2030. | |
Titon Holdings (LON:TON) (£10m) | SP -7% Underlying EBITDA and loss before tax for FY25 to be in line. Cautiously optimistic for FY26. | AMBER/RED (Graham) [no section below] I've become rather nervous about this one, given the lack of profitability in recent years, and also noticing that Harwood is a 28% shareholder - which can be a precursor to a delisting. Offsetting those negatives is considerable asset backing on the balance sheet relative to the market cap. This full-year update doesn't provide all that much comfort, even if it is officially in line: the company (which manufactures venitlation systems along with window and door hardware) remains loss-making on an underlying basis. On pure valuation grounds I do like the stock, given the balance sheet strength (including £3.5m cash and property valued now at £5.8m), but these nano-cap value plays require lots of patience and can be vulnerable to unusual risks, i.e. delisting. Therefore I think a cautious stance continues to make sense. | |
Petrofac (LON:PFC) (suspended) | No residual value to be retained by existing shareholders. | (Graham) [no section below] Way back in March, the plan was for existing shareholders to be left with 2% of the restructured company. Much legal wrangling and negotiation has taken place since then, and it turns out that existing shareholders will not be left with anything when all is said and done. We were RED on this prior to the suspension of its shares in May, which was the right call, but it was clearly extremely high-risk. |
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

40 comments
Thanks to everyone for your valuable input. Journeo (LON:JNEO)
Well I followed Graham's advice today, I was dealing with divorce stuff and associated house purchase this morning, logged on here to update the dividends coming in yesterday and today in various family portfolios and went OUCH
So I found my walking boots and went out for the rest of the afternoon, so it is now and ouch and I didn't make any rash or stupid decisions today, ok I probably have but just not selling stuff in fear for a change!
Hope everyone enjoys the weekend
Tommy
Moody’s analytics spokesman :
“We follow the trendlines on defaults and not the headlines; and these are coming down!”
All the best
But Jamie Dimon said, 'When you see one cockroach there are probably more '.
And?
Deleveraging under way and it will be ideal for a good wash out. I am looking at BTC around 90K to be convinced that this is over and VIX to touch 40.
This is a bull market but everyone forgets that bull markets and share prices are not linear.
As for the regional banks again everyone forgets that there are thousands and thousands of credits in the markets and some of them go to zero. In fact some of them will always go bust!
Remember that today is the third Friday of the month as well-options expire thus the extra volatility in the markets. Look out for the last hour of trading over the pond to get a clearer picture.
All the best
Useful insight-thanks
A pullback every now and then is needed
Needed John and adding further; it will always happen.
All the best
The spike in Vix overnight caused by re-emerging banking problems in the US is having knock-on effects in Europe. Vix at 27 is generically attractive and as a rule I would be be a buyer... but as last weeks spike highlighted, all is not well with positioning for such moves. I wouldn't put anyone off having a nibble but be prepared for choppy markets for some time...two 30% moves in a week suggest to me we need to be cautious for the time being. Nothing gained by being a hero today when there will be plenty more info that leaks out over the weekend. If things are really serious then the 2008 playbook of policy moves on a Sunday can't be ruled out... but with concentrated positioning in stretched markets im in no rush as the year end approaches. I think institutions will want to lock down what they have so price moves that look a bit odd may happen more often for a week or two at least. The closer we get to the year end the more comfortable I get with being able to look through random price moves....but a doubling of Vix in a week needs to be taken seriously. Hopefully it all passes and im just being old and grumpy. Good luck all.
I agree, some bargains ish out there, reticent to buy on a Friday when more bad news could appear over weekend
Random question: is now a good time to buy covered call ETFs?
Always respect your views RD I'm hoping it will be more akin to when a handful of regional banks went under (Silicon Valley) circa 2023 and they acted pretty quickly to right the ship.
Steppe Cements Q3 today. It's a very small cap and unlikely to be of much interest except to holders, we are and I added a few more this morning. Q3 Rev+17%, 9 month rev+28%, cement price +10% in Kazakh Tenge but -3% in USD as Tenge down 13% against the dollar. An inter company $27 million loan is to be converted into a listed bond yielding 8%. A tax dispute has been settled, and surplus cash is promised to shareholders this year. Stockopedia lists it as Super Stock, shareholders might think otherwise but I live in hope on this one. Someone asked if anyone was buying anything today, hence my comment.
Any views on Titon Holdings (LON:TON) ? I've seen a few funds but holdings here. But I don't see the appeal.
Anyone have any views on Journeo (LON:JNEO) I have a small pilot purchase it the moment but I noted a dip in price, could this be a buying opportunity but two director sales on the 15th October.
I've looked at it a few times but can't shake off a nagging doubt I've got.
My main concern is the SaaS solution. If they become the main system integrator for transport infrastructure pulling in data from their own and competitors hardware that's good news. If they can derive extra value from that data beyond 'where is my bus and how much behind schedule is it' and up-sell those insights that's beyond good. However, if (bigger) company x comes along and they are told to feed their data into that solution then it has the opposite impact. I'd like them to provide more detail on their software development road map so that I can see future R&D plans. The historic spend they declare tells me very little.
I'm also worried about cyber security. As transport infrastructure is so critical and potentially a big target I wonder how resilient their SaaS solution is perceived to be. Will customers eventually go for the easy option and pick a bigger supplier for all their critical infrastructure or will the landscape remain fragmented long enough to allow Journeo to become that bigger supplier. Or are they already there? I haven't had that answered to my satisfaction, hence staying out for now. However, the SP has done nothing but climb since I started looking early this year so I may be worrying for no reason. Until I get more clarity I won't be investing.
Journeo (LON:JNEO)
I looked into these sales Douglas and thought perhaps the exercising of their options might be influenced by possible changes to the taxation of the proceeds in the forthcoming budget. It isn't widely known that exercising an option makes one immediately liable for PAYE on the benefit hence the sale to cover the tax liability. It may be alternatively that they were just taking advantage of a decent rise in price. I haven't changed my holding.
Journeo (LON:JNEO)
i agree its often necessary to sell soem for tax - thats standard that one sells say 40-50% - however it looks like he chose to sell the lot whne he has really small holding.
Thats not a great look - i do get it though that some directors simply do their job and may not want to invest high % of their wealth in the company they work for. So for those that never have a material holding and for whom the awards are just like cahs bonus i am not reading too much into the fact they sell - as they seem clealry not interested in investing in the company.
Obviously its better for directors to have a holding that "hurts them" when share price collapses - i think that goes without saying somewhat.
I did speed read release so i might have got my facts partly wonky here.
Journeo (LON:JNEO)
I agree it always looks "iffy" when directors sell but the company seems very stable with about £15M cash and looking at Nick Lowes buying his timing is as poor as most of us. He paid over the odds in March 24 and was underwater for ages so I don't begrudge him a result now. It will all come out in the wash I'm pretty confident.
Journeo (LON:JNEO) is an outstanding small company. I suggest you look at the latest Investor Meet Company presentation if you have not already seen it. Mark Slater (son of Jim) has been a long term fan - and he is not easily pleased.
Re Wishbone Gold (LON:WSBN) I can see from a diagram on today's update that it has managed to surround Greatland Resources mine and my very successful investment therein. Looking back, after investing in the struggling Wishbone in 2011, I gave up on it at a loss in 2020, so good luck to it.
A few stocks on sale this morning, Anyone brave enough?!
Any in particular that you're looking at?
ME International (LON:MEGP) Journeo (LON:JNEO)
SDI (LON:SDI)
Synectics (LON:SNX)
TP Icap (LON:TCAP) I hold, topped up yesterday
International Personal Finance (LON:IPF) potentially could be interesting, currently under offer at 235p and fallen to 206p this morning
Crystal Amber Fund (LON:CRS) (I hold) Overall positive annual figures, although increasingly the run-off story will be about the outcome of the investment in Morphic Medic.
Black Friday? Well, it is October.
Does anyone know why the market is having such a wobble? I can't see anything.
No doubt due to falls in the US yesterday "Regional banking stocks fell sharply yesterday, as Wall Street fretted about the state of credit markets."
American banking sector issues, I read somewhere, cannot for the life of me remember where I read it though
Got it, it was on IG on the FTSE100 tab, under news. US regional banks.
Plus defence companies falling because of the Trump-Putin meeting and hopes for peace in Ukraine. Since defence contracts are mainly on long term contracts and NATO countries are still planning to raise defence spending because they know that Putin is not suddenly going to turn into a peace-loving hippy, a 3-4% fall doesn't make a lot of sense, but that's the current market for you.
I'm in agreement with you. The increases in defence budget which Trump is demanding and Germany is promising will have to be spent somewhere. I think that defence shares will continue to rise for a decade.
I've not followed the Petrofac (LON:PFC) story, but that is a pretty harsh RNS for any holders to receive (although I guess not a surprise...)
.
Ramsdens Holdings (LON:RFX) will now be joining Skillcast (LON:SKL) , Kenmare Resources (LON:KMR) and Time Finance (LON:TIME) at the next Yellowstone Adivsory Private Investor Evening on 19 November.
This is a chance to meet management teams and fellow private investors face to face in a relaxed environment. Listen to company presentations and then take the opportunity to ask your questions over drinks and canapes.
The event starts at 5.30pm in EC1
We still have a couple of places available so if you would like to attend please register below.
Register: Join Webinars & Events | Yellowstone Advisory