Daily Stock Market Report (Fri 19th December 2025) - SMWH

Good morning! I'm afraid we have some profit warnings to digest today, but we also have an impressive disposal by Strix (LON:KETL).
Today's Agenda is complete. Spreadsheet accompanying this report (updated to 24th November): link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our View (Author) |
|---|---|---|---|
SSE (LON:SSE) (£26.0bn | SR63) | £1bn,12-year bank facility from a large banking syndicate. Backed by a financial guarantee from the UK Government's National Wealth Fund to support four major grid upgrade projects under way in the north of Scotland. | ||
Atalaya Mining Copper SA (LON:ATYM) (£1.12bn | SR92) | A high number of dissenting votes were recorded at this year’s AGM. A director promises to attend more Board meetings, and the company says its new remuneration policy will have higher shareholder support. | ||
WH Smith (LON:SMWH) (£866m | SR47) | Revenue +5%, headline PBT falls to £108m (previous year: £144m). Dividend reset lower. Expects to deliver FY26 Headline PBT of £100 - 115m. FCA investigation. Profit warning: FY26 PBT guidance of £100-115m PBT seems low, e.g. after-tax net income guidance on the StockReport is £87.8m. Also the FY25 result has slightly missed expectations. The FY25 result is below the company-compiled analyst consensus figure (£110m) but consistent with the guidance they gave in November (£100-110m). | BLACK (RED ↓) (Graham) More bad news for WH Smith shareholders and I'm sadly and reluctantly going to have to be fully RED on this for the time being. In other circumstances, I might have been able to stay AMBER/RED but when you combine a deteriorating earnings outlook, a terrible balance sheet and an FCA investigation, I'm not left with much of a choice. | |
Applied Nutrition (LON:APN) (£618m | SR48) | An exclusive, three-year agreement. Morrisons will formulate, produce and sell Applied Nutrition branded meals and food products. | ||
Capita (LON:CPI) (£452m | SR76) | Four-year contract renewal with a major European telecommunications provider, valued at £62 million, commencing in January 2026. | ||
Caledonia Mining (LON:CMCL) (£346m | SR88) | The revised proposals (not yet enacted in law) should result in no change in the financial outlook for Caledonia's portfolio of assets in Zimbabwe provided the gold price remains below $5,000 per ounce. | ||
VP (LON:VP.). (£213m | SR69) | New CEO to begin in February 2026. Her most recent role was MD at Mitie Group plc. | ||
Strix (LON:KETL) (£93m | SR65) | £110.0 million conditional agreement to sell Billi on a cash free / debt free basis to private equity. £110m is equivalent to 47.8p per KETL share (current share price: 40.65p). Net debt balance will be c.£68 million before disposal. Disposal is “the optimal path to bring the Group back into a net cash position”. | ||
Proservice Building Services Marketplace (LON:PRO) (£66m | SR60) (formerly HSS Hire) | Revenue -14%. Loss before tax £6.2m. Now expects FY26 revenue of c. £260m (continuing operations, excluding THSC), and Underlying EBITDA of around break even. | BLACK | |
Nexteq (LON:NXQ) (£43m | SR77) | Buyback for up to 10% of the company’s shares. Commences today. | ||
Fusion Antibodies (LON:FAB) (£17m | SR14) | NCI has expressed an interest in continuing to use OptiMAL® and provided Fusion with a proposal to extend the collaboration agreement. Negotiations to continue into early 2026. | ||
Plexus Holdings (LON:POS) (£11m | SR36) | Sales £4.48m (2024: £12.7m). Adjusted EBITDA loss £1.1m. Pre-tax loss £3.3m. Cash £2.5m. The loss is “consistent with our strategic decision to reinvest in the rental model and strengthen our rental operations.” |
Graham's Section
WH Smith (LON:SMWH)
Down 4% to 654.39p (£828m) - Preliminary Results Announcement - Graham - RED ↓
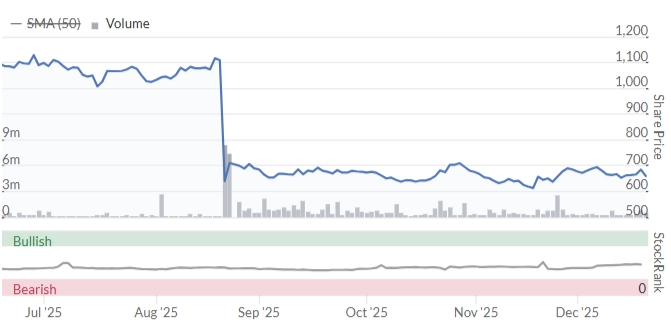
This stock has been in the wars. I turned AMBER/RED on it in August when it was revealed that the company had overstated profits in North America.
The stock has been treading water since then:
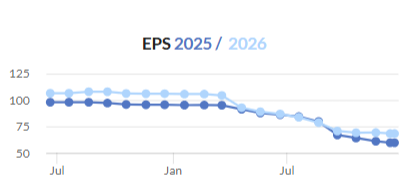
Earnings expectations have continued to slide since August:
I initially thought (and Reuters reported) that today’s headline adjusted PBT of £108m was below expectations. There is a company-compiled consensus figure of £110m.
However, today’s result is actually consistent with the guidance given in November of £100-110m of headline adjusted PBT, and is closer to the top of that range. So I don’t think the FY25 figure is a miss.
But there are other reasons for concern.
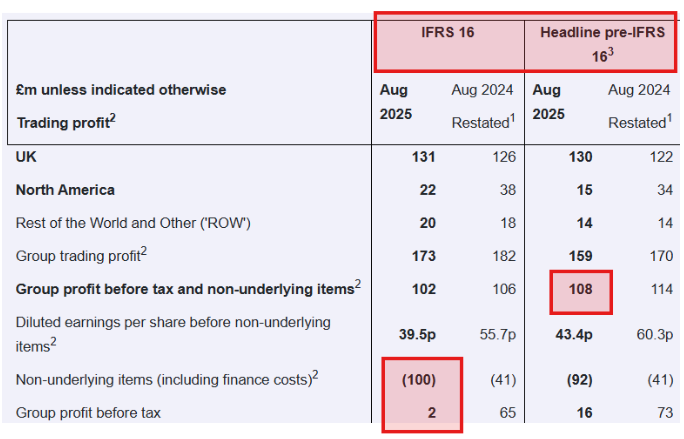
For a start, there are £100m of “non-underlying” items, resulting in a statutory PBT of only £2m. That’s compared to only £41m of non-underlying items last year.
It’s all rather complicated due to the company’s presentation of IFRS vs. “Headline Pre-IFRS 16” figures (treating leases as a debt vs. treating leases as an expense), along with other very heavy adjustments.
They continue to manage the business on the basis of pre-IFRS 16 analysis:
But given that the company has admitted that prior years were not recorded correctly, it’s clear that it has had trouble managing its own figures. So naturally, outsiders like us are going to struggle to get a grip on them..
FCA: the Financial Conduct Authority has started an investigation into WH Smith’s compliance with listing rules.
On 19th November, the findings of an independent Deloitte review were published, and the CEO offered his resignation on the same day.
The review confirmed that profits in North America had been overstated due to the company’s early recognition of supplier incentives. It was “a timing rather than an existence issue”, but still a serious one. It was blamed on “a target-driven performance culture”, “a limited level of Group oversight”, “weaknesses in the composition of the finance team”, and “insufficient systems, controls and review procedures”.
I wonder if there’s a risk of a large fine here?
FY26 outlook
Let’s pick out some of the key points surrounding the outlook.
13 weeks to August (roughly speaking, the final quarter of FY25): LfL revenue growth was 3%.
FY26: total revenue growth of 4-6% expected (not like-for-like).
FY26 Headline trading profit margin expected at 14-15% (UK), 7-8% (US), 5% (Rest of World). This suggests a small deterioration in margin in the UK, from 15.6% in FY26.
Recent like-for-like sales trends: +3% including +2% in the UK (“largely reflecting a softening in rail”), North America +1%, Rest of World +6%.
It sounds like the challenged UK consumer is having an effect here, with Rail passengers in particular not raising their spending in line with inflation.
The Group expects to deliver FY26 Headline Group profit before tax and non-underlying items of £100m - £115m.
This looks like a downgrade to me, considering that the StockReport suggests an after-tax net income figure of £87.8m for FY26 (which would require closer to £120m pre-tax).
Balance sheet
Finance costs are impactful with £26m of interest during the year charged on bank loans, overdrafts and convertible bonds, and that’s before we get into the notional interest charged on lease liabilities.
Net debt was £390m as of August 2025, mostly consisting of convertible bonds. That’s up from £371m the prior year.
If you include leases, net debt was £874m.
Funky Pigeon was sold for £25m, not really making a huge difference to the debt picture.
Non-underlying items: these are huge and they arise primarily due to £138m of impairments charged to PPE, leases, goodwill and other intangibles, offset by the sale of Funk Pigeon and a few other small items.
Putting it all together the balance sheet has net assets of £188m but this includes a frightening £447m of goodwill and other intangibles. Strip them out and the balance sheet is worth minus £259m.
Due to lease liabilities being higher than lease assets (after leases were impaired), modern accounting rules contribute to the size of this deficit. Under old accounting rules, net assets would be £290m and only minus £159m after excluding intangibles.
Graham’s view
I’m going to downgrade our stance on this to a deeper shade of red, considering:
The FY25 result is technically a miss against analyst consensus, although it is consistent with recent guidance.
FY26 guidance is weak against existing estimates.
The balance sheet is horrific and they carry significant debts.
It’s difficult to predict what the FCA might do after their investigation.
No permanent CEO: searching for a new one.
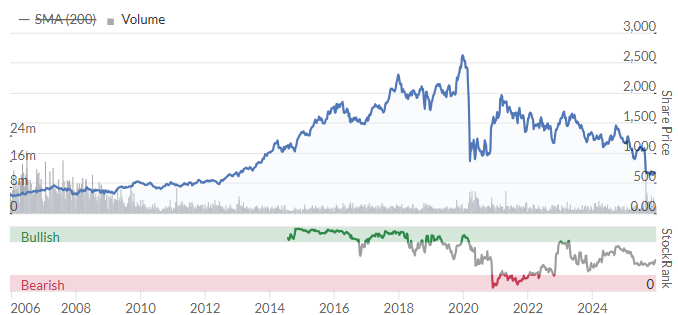
This all suggests that WH Smith is very high risk right now. Of course it could be good value here, but there is clearly the potential for more bad news, and momentum is against it - both in a business sense and in terms of share price momentum.
It’s a shame because this has been such a successful, profitable and cash-generative business in the past, and I’ve done well with this share before (a long time ago). I’d personally like to own it at some point, but the balance sheet and other problems mentioned above will keep me away for the foreseeable future.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

41 comments
In case it's of interest to anyone, I was just looking at how the share prices have performed on the DSMR spreadsheet by colour. I have compared the share price at the end of the last report date with the share price at yesterday's date. I have removed some rows where googlefinance did not bring back data or for anomalous annualise % movements. Below are the results. I think most are as expected except 'Green' and 'Red' but this may be where there has been a positive trade update (for green) on the day and the share price has risen a lot that day and then fallen back a bit (and vice versa for red). Also quite likely there are some errors in my workings!!
An interesting report. I thought when green was analysed a year ago it showed quite a good return. Not sure why this has declined.
Anyone have the details from the last time this was done?
P.S.
The top rank portfolio, those with a QVM rank > 90 has risen 19% for the last year. The NAPS portfolio has risen 31% and the FTSE All Share has risen 18%.
WH Smith (LON:SMWH) The Final dividend payment has been cut by 73%. If they cut the next dividend payment by the same percentage, then the 12 month yield would be 1.4%.
Warpaint London (LON:W7L) Good post by rldavies. W7L was a company I swore I'd never buy. It's been a Stockopedia darling some while back, which is a bit of a red flag for me. No-one wants another BooHoo or ASOS, or whatever other darlings we've seen touted around.
But actually, I bought a small position earlier this month at 199p earlier this month. Why, you may ask? Well, the company has a pretty good track record. There's no guarantees this will continue; and in fact the market is telling you that it thinks it won't.
BUT. The interest cover is good and the value score is 75. In more concrete terms the forward PE is 8.9. In the latest interims it said revenues were up 8%, and its gross profit margins were up 250bps. Cash and equivs were up 209%. Well, that sounds pretty good to me.
Admittedly PBT is down 41%, which ain't so hot. They have to write off a bad debt, which is painful. OTOH, they're rolling out into Superdrug, Tesco, Boots, and other stuff in Europe and US. Pretty good.
Dvivvie is nice, too, assuming things don't deteriorate and has to be cut.
My how sentiment has changed since July 2024. The share price was 590p. The Value score was 9. We should take this as a cautionary note. Never buy a share when the value score is below 20 (with perhaps rarest or rare exceptions).
I'm aware that I could look completely stupid on this in a year's time, but I thought it worth a little punt. Just my 2 cents.
Thanks very much Mark. A very cogent response, as the 20 likes vs my 22 shows. I cant disagree with your logic and your figures. They are definitely not going to go under and they have been very adept at what they do so far. Where you and I may disagree is that I think they have taken their eye off the ball with their acquisition, and perhaps some of the 'mistakes' I would call them which surfaced in the Sept figures may have arisen from that e.g. the customer going into administration. Were they watching the accounts receivable, the repeat or non repeat orders etc carefully enough?
Also, as I have indicated, I dont think that the list of 'wins' will amount to what thy are hoping for, or were perhaps indicating. Tesco is firm ground and they have a strong base there. Superdrug is very competitive territory and we will see what that will be worth in extra business. Boots is a big name new customer, but frankly this is small business - limited Xmas specials in a very limited number of stores. Warpaint London (LON:W7L) have never been very effective in converting Xmas business into repeat orders of their strong conventional branded products
It is the EU territory that most concerns me, with perhaps the exception of Italy where the e.l.s. competition is in another store group and platform. Yet again, even here in Tigota, here small number of stores, limited range. As for the other wins, small numbers in already well established competitive territory.
They have had to and sensibly turned east to their strength - the EU has consistently been responsible for the largest component share of their business for some time. so they have done the right thing. But I fear it is too little too late....and Germany, the largest sector market in the EU is absent, as is the significant market of Scandinavia.
As I say, I may well be wrong, the SP has bottomed out and they can lean on the figures you have quoted plus perhaps some more business in China (though not mentioned in H2 targets comments). Perhaps there will be a surprise in the contribution from the acquisition's brands, though I dont expect much so soon in profitable revenue from that direction, and I dont think they do either.
We will see.
No information from the company, and none expected before the new year. But my time is up with Warpaint Warpaint London (LON:W7L) -so this is MY commentary, i.e. it may differ from others.
I have just sold my final tranche of Warpaint London (LON:W7L) for £2.
My much larger tranche of Warpaint London (LON:W7L) I sold for £5.09 in January.
Subsequently, I wrongly bought back some in the meantime at much lower prices than my January sale price with the hope of picking up some trading profit as the brand recovered. I was mistaken.
Why did I hold on for so long to my final much reduced holding is a good question.
The answer is complex because I believed in part that some of the issues at the Interims in Sept were a one off. However, the inexorable fall in SP continuing since then together with a detailed review of the market possibilities in key markets (US potential), UK (W7L’s significant market from the first), and EU (often forgotten that it is the W7L’s largest in terms of total sales) have changed my mind. When we get more RNS information from the trading updates in the New Year, I believe that we may find that W7L is overpriced at £2, and predictions for H2 of this year may fall significantly short of expectations.
Evidence? As far as that open to us as private investors, there really is only amazon.co.uk which as we know from the past is a large and profitable element for W7L. I follow that closely, and the evidence shows that there is significant discounting going on across the board, especially for the W7 brand, right now in this key period leading up to Xmas.. There are widespread offers of 32% down to 16% available quite a lot of the range. Surprisingly, there is less on the second and lesser brand, Technic but this is less important anyway that W7. Also usefully on Amazon, there are extra figures for the numbers of a line sold in the last month etc for many lines. These have been less than I would have expected for some W7L lines, especially in gifting, very important at this time of year for presents.
Clearly, the Trump tariff situation has been unkind to W7L which was pinning much hope on the expansion possibilities in the much bigger market of the US, at least 10 x the size of the UK. After expanding their personnel investment in the US, that has now been cut back and in H2, there is only one store group taking more lines. Gone are the expansion dreams of moving up out of the deep discounters and getting the aspirational back-wall permanent fixture in the likes of Walmart. Sad but true.
Probably, the most important consideration in my deeper analysis has been the revelations I have found in examining the US company e.l.f. (standing for eyes, lips and mouth, for those who, like me, didn’t already know.) If you want to see what e.l.f. sales on Amazon in the US have been recently, go to amazon.com and you will be surprised. On the other hand, this is a company and a brand which has recently paid $1 BILLION (my capitals!) for Hailey Bieber’s skincare brand, rhode. In other words, this is a huge company by comparison………and, in my view, it is eating W7L’s dinner, and that of probably quite a few other UK brands too.
Why its impact on W7L could be disproportionate is that its pricing is still above but much closer to W7l’s …..and it wants more. In 2024, it claims it was growing at 10 x the growth in the UK market. And it has already been in Superdrug since 2017 and Boots from 2019. I mention these in particular because W7l mention these are significant support elements in its expectations for H2 this year; expansion in Superdrug, and some limited gifting opportunity in some Boots stores which as we know probably dont translate into ongoing sales of standard lines.
As for the EU, again key support elements for W7l in H2, this was the position of e.l.s. in key store groups there.
In e l.f.’s plans for 2025, there are major moves in Germany, Belgium and the Nordics. Germany is considered the largest cosmetics market in Europe, and e.l.f have launched its products in 1,600 ROSSMANN locations nationwide, marking its largest international retail launch to date. Notably, no action from W7L in this apparently very large market.
In the Netherlands, as well as Etos, where e.l.f claims to have been no 1 recently, ( which is claimed as one of the new ‘wins’ for W7L in H2 ). the e.l.s. brand further expanded into Kruidvat and Trekpleister stores in May 2025.
In Italy, e.l.f. is available in hundreds of Douglas stores across the country and also online through the Douglas e-commerce platform. The brand expanded its physical presence significantly with Douglas in autumn 2024, following an initial launch online and in selected stores in late 202. W7L is making inroads in Italy on a parallel track in Tigota, launching a range of products in 200 stores with a capsule collection going into an additional 400 stores From what I can see, Tigota has a huge number of stores in many towns and cities, and is similar to something between Superdrug and Boots in the UK.
In the Nordic region, e.l.f. partnered with SÆTHER as the exclusive distributor for the Nordic region, with launches anticipated in retailers such as H&M, Matas, Kicks, Vita, Sokos and Lyko. No mention of W7L there.
If you get the impression of a huge bulldozer working through western Europe, including the UK, you may.share my opinion too.
Of course, there may well always be space for smaller companies, managing their resources well as W7L have done in the past. However, the profitable growth path which many of us have enjoyed with W7L over the last few years may no longer be there and the effect on the bottom line and ultimately the SP may be very significant going forward. Additionally, smaller companies may well also be operating with smaller discounters….like one of the UK companies which clearly much to Warpaint’s surprise went into administration in W7L’s Q1. This had been a long-time trader with W7L and has left W7L with somewhere near a£1m loss in when the total effect is eventually totted up.
It is a sad situation, because it feels like I am losing am old friend - and I may be wrong..
If you have got this far, congratulations and I hope this research in depth will help you make up your own minds too.
Hi
In light of the recent postings about Seraphim Space Investment Trust (LON:SSIT) in the thread (I hold starter position).
Some impetus to space technologies and consequent investments. This posting on X summarises a new catalyst.
Regards
Howard
Well let's hope they put him on there and leave him!
Imagine the scenes :)
Haha ... I know we should not be political on here, but that was funny.
Was it announced before, or after, his new cannabis policy?
My guess would be "during".
Oh how we laugh.
briliant
"building a permanent lunar outpost by 2030". To do what exactly?
"Improve space weather forecasting" Expect low pressure with chance of light meteor showers, I would have thought.
"cislunar space". The jokes practically write themselves at this point.
Musk will do well. Turns out that the few hundred million on campaign support was money well spent. Bonuses all 'round!
Hi Mark
"building a permanent lunar outpost by 2030". To do what exactly?
There are many transformational and globally strategic opportunities a lunar outpost unlocks. As well as many technological innovations which will flow out of the whole space based eco system.
Global Strategic Outcomes
Technological Innovations
Transformational Technologies for the World
Regards
Howard
He's one hell of a salesman Musk all the talk of cutting £2 trillion through Doge and he ended up a million miles off when anyone with half a brain cell could see it was all pure fantasy.
I think the idea is you need some kind of base on the moon to stop at to then go further afield.... eventually.
Squander Earth's resources just to MAGA.
Maybe he ought to lead the expedition :)
Plexus Holdings (LON:POS) living up to its ticker. Another example of why jam tomorrow stocks are best avoided.
Plexus
In a year that everyone made good returns, Paul Scott lost money because of his bet on this one!
Think we've found the grinch.
Woo hoo someone who has given plenty of people here a winner has had a loser.
That's the spirit.
'Woo hoo someone who has given plenty of people here a winner has had a loser.' I was always too slow, worked hard for the crmbs left on the table. Others too perhaps, there were always some sour grapes being expressed.
Harsh, but fair !
He added more according to his podcast
An interesting comment on AI data centres in Kepler's latest research note on Sequoia Economic Infrastructure Income Fund (LON:SEQI) (I hold)
"The infrastructure referred to includes new economy industries and themes like the physical support for artificial intelligence and new and greener energy supply like renewables and nuclear. With loans being made on a three to five-year basis, there is a constant flow of money back into the portfolio allowing the managers to be flexible with their positioning. Having been an early mover in the data centre space and generating attractive returns, they are currently finding lending standards on new loans slip due to the artificial intelligence boom, meaning this allocation has been falling. Instead, the team have been investing further down the chain in the power supply and networks connecting these to the grid, taking advantage of the same trends via loans with better rates and covenants."
https://www.trustintelligence....
A closer look at monthly CPI data for the US is rather promising. It has played ball since March and bad numbers have only been marginally bad...the data was pretty strong in Q1 which augurs well for strong numbers dropping out... which is potentially positive. Staying in a month on month range of 0.0 - 0.2% I think signals not much to worry about...assuming no significant move in employment data. The outlook on this data alone to February looks favourable. The market needs something new to focus on.
Japan 10-yr treasuries have hit 2% today. Could have some global (mostly US) consequences as Japanese investors accelerate bringing money back home!
https://tradingeconomics.com/j...
DCC (LON:DCC) Tender offer. I have not previously had to consider a tender offer but my partner holds this company (which I suggested as a slow-but-steady bet) in her modest portfolio. They announced the result of the tender offer (which was announced on 17th December) today and the strike price is £51.70; this is below the price that she elected to sell at so I presume she will still hold her shares? Investopedia suggests that a tender offer is often made at a premium price and can expose the company to costs (referring to USA shares?). The SP today is £50.40. This is higher than yesterday (Investopedia suggests that a fall in SP is not uncommon after a tender offer). I would like to ask firstly if people think I made the right recommendation for her not to accept a lower offer and secondly if anyone knows why the company made this offer as the strike price seems to be close to where it was trading when the offer was made?
Is the Mkt following its usual counter-intuitive stance today. Following reduction of BoE rate yesterday - you might think this a plus for house builders as mortgages now more affordable yet it seems they are all marked down today
The problem as seen in the US this time last year is sometimes, rates down -> bond yields tick up not down....which weakens the impact of the cut. Hmmm so in opposition to US data ... UK investors still not convinced by inflation outlook. Currency not reacting negatively so probably all noise ...and UK housing reflecting changes in taxation rather than mortgage costs for now.
We are yet to see any significant progress on the big project which is the proven go-to for growth in the British economy - yes, I'm talking housing and the 1.5m new homes target. For all the talk of grey belts and brown fields, even with rose tinted glasses, it looks more like a cowpat to me.
I bought in on the sector too early with a mix of house builders Berkeley group (LON:BKG) , Cairn Homes (LON:CRN) and Vistry (LON:VTY), missing the recent dip to 90p at Springfield Properties (LON:SPR)
On the materials supply side it's Alumasc (LON:ALU) Breedon (LON:BREE), Brickability (LON:BRCK) , Topps Tiles (LON:TPT) and Victorian Plumbing (LON:VIC)
Positive exits included the bid for contractor Kinovo and sale of HSS [Proservice Building Services Marketplace (LON:PRO) ] on the announcement of their asset sale to Speedy Hire.
Whilst many of these have underperformed this year, or profits given back (ALU), the charts for many of them look ready for recovery. I am particularly interested to see whether the reincarnation of MFI at VIC will prove to be inspired, both in timing and by expanding their product offering.
Seems to me, US CPI data quietly looked very much onside ( With the lets lower rates crowd) but received little attention. Somewhat strangely suddenly the data can't be trusted...so it looks to me like the rate cut story lacks a little push. On the basis of this single data point CPI isn't something to be overly concerned about for now and net net should therefore support the case for lower rates. However, how much lower depends on many things, not least plans for tariffs and DOGE. The latter is very much out of the news since Elon stepped away and tariffs we will just have to wait and see. Overall my view is we aren't likely to learn so much from CPI and employment data for a while and the economy probably muddles along. This isn't too bad but expectations I fear are higher which is a problem for the market not the economy. 2026 could well be shaping up with less macro factors and more stock picking.
Seraphim Space Investment Trust (LON:SSIT) have announced their major holding, ICEYE have signed a €1.7bn joint venture with German government. See the investment trust board for more comment. https://www.stockopedia.com/co...
I don't know why they took 24 hours to announce this - RHMD announced it yesterday, providing a good buying oipportunity in Seraphim Space Investment Trust (LON:SSIT) .
A major disposal from Strix (LON:KETL) , £110M which will be enough to repay its debt and which exceeds its current market cap.
Yes, it's a good price for Billi but I wouldn't get too carried away. The proceeds might well exceed the Strix (LON:KETL) market cap but the enterprise value of the business was nearly double that. The company is selling the higher gross margin growing business and retaining the part beset by issues with cheap competition and US tariffs. Strix (LON:KETL) is financially transformed into a healthy net cash position, but do you want to own the residual business?
The US don’t own kettles so not sure why the company has mentioned US tariffs. Sounds to me like the issues are all Chinese competition related.
Remaining business is valued at ~3x EBITDA based on yesterdays SP and post disposal of Billi. Clearly too low even for a business that is largely ex growth. On top of that they will do a £10m buyback program and still have net cash of ~£30m to do a tender or special dividend. I think even at the current SP of 47p it is still 20-25% undervalued.
3x EBITDA sounds low, but this is roughly the equivalent to a cash-adjusted PE ratio of 7-8x - probably about right for this sort of business which is clearly struggling at the moment?
Capita (LON:CPI) .Announces the renewal of its contract with a European telecoms provider worth £62m. Starts January 2026. Doesn't mention the company name.