Daily Stock Market Report (Fri 19th June 2026) - PPH, REC, MRK, SYNT, LBG, CFYN

UK politics: the prediction market Polymarket is increasingly influential in mainstream media reporting. The latest UK politics predictions there include:
90% chance Andy Burnham is the next PM in 2026, now that he has won the Makerfield by-election.
Only a 6% chance there is no “next PM” in 2026.
Or in sport:
14% chance that England win the World Cup (the most likely outcome is thought to be quarter-final elimination, with a 24% probability).
56% chance that Scotland are eliminated in Round of 32.
Betfair Exchange has generally been my preferred venue for checking odds, but the sheer variety of events that are available on Polymarket is very impressive!
Bank of England: there was no change to rates at the Bank of England yesterday, as expected. Two of the nine members of the MPC wanted an immediate rate hike to 4%.
Overnight market movements:
The FTSE is set to open down 0.25% at 10,370
S&P 500 is down 0.4% at 7,465
Brent crude is up 0.8% at $80.50/bbl
Gold is down 1.7% at $4,140/oz
Bitcoin is down 0.5% at $62,800
Calling it a day there, thank you. Have a great weekend!
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Barratt Redrow (LON:BTRW) (£3.7bn | SR47) | The new CFO was most recently CFO of Britvic plc. Previously CFO of British Airways. | ||
| Cordiant Digital Infrastructure (LON:CORD) (£957m | SR91) | Full Year Results for the Year Ended 31 March 2026 | Aggregate adjusted EBITDA and revenue of the portfolio up 7.8% and 9.9% respectively. NAV up share increased to 146p, total return of 16.3% (or 12.3% excluding the impact of FX). Revenue visibility is supported by £952.1 million of contracted revenue. Outlook: "...well positioned to benefit from structural growth in demand for digital infrastructure, driven by increasing data consumption, cloud adoption and the development of AI. Near-term performance is expected to reflect recent customer churn and project phasing, with new business anticipated to support momentum as the year progresses." | |
PPHE Hotel (LON:PPH) (£837m | SR42) | Euro Plaza Holdings, which holds approximately 33% of the Company, is opposed to the Fattal Proposal. Fattal has informed PPHE it would not be prepared to proceed with the Fattal Proposal in circumstances where Euro Plaza Holdings is opposed to such an offer. Accordingly, the Fattal Proposal is not capable of being delivered in its current form. The Company received an indicative proposal from another interested party. This interest is at a very preliminary stage and is currently being assessed. | TAKEOVER (GREEN) (Graham) | |
Gulf Keystone Petroleum (LON:GKP) (£387m | SR85) | Gulf Keystone Petroleum Limited 2026 AGM Operational & Corporate Update | The Shaikan Field remains offline following the precautionary shut-in on 28 February 2026. Almost all capital projects have been slowed or suspended. Cash of $66m as at 18 June 2026. Ready to restart production and exports immediately once safe to do so. | |
Redcentric (LON:RCN) (£195m | SR55) | Proposing to return up to £90 million to Shareholders by way of a Tender Offer at a price of £1.60 per ordinary share. Shareholders will have a Basic Entitlement to tender approximately 35.3% of their shares. | ||
Synthomer (LON:SYNT) (£182m | SR66) | Agreement to divest Synthomer a.s., the operating company for its Acrylate Monomers business based in the Czech Republic “The transaction consideration comprises a cash generation sharing arrangement of up to €12m over three years, with no initial consideration at closing.” Rationale: "The transaction will therefore remove a cyclical and capital-intensive base chemicals business from the Group, improving profitability and cash generation, and further transitioning the simplified portfolio towards a speciality focus." | AMBER/RED = (Graham) This is an important tidying-up exercise, as the business being sold generated an EBITDA loss of €10m (£8.7m) last year. For context, the Group as a whole generated an adjusted EBITDA of £136.5m. Even if the subsidiary's performance in 2026 might have been a little better (it was supposedly operating at breakeven in the first four months of the year), it must be a good thing to simplify Synthomer as it grapples with its ongoing debt challenges. Checking its 2029 bond on Deutsche Börse today, I see that the yield has narrowed to just 15%. When I checked it in May, the yield was 27%! So lenders are feeling more confident here, which can only be positive for the equity. | |
Mobico (LON:MCG) (£139m | SR48) | Formal contracts have been signed with the five German Public Transport Authorities in North Rhine-Westphalia and adjacent regions. These contracts implement the structural changes to the RME and RRX contracts. | ||
Record (LON:REC) (£108m | SR90) | AUM +14%. Revenue down 4%. Profit after tax down 23% (£30.4m) “reflecting tax rate normalising”. FY27 has started with strong momentum, with focus on maintaining the foundations in Risk Management while continuing the momentum in Absolute Return and Private Markets. | BLACK (AMBER/RED ↓) (Graham) | |
LBG Media (LON:LBG) (£56m | SR65) | Buys 75% of Uncovered, “a UK‑based, Gen-Z native social‑first creative agency”. Initial cash consideration £26.8m. Earnout cash payment up to £7m. Put and call options to acquire the remaining 25% of the company. | AMBER ↓ (Graham) [no section below] Roland analysed this media group earlier in June, coming away with a mildly positive view on valuation grounds (P/E of 5 even before adjusting for its large cash balance). According to Zeus, the EPS forecast for the current year is 5p, rising to 7.2p for FY September 2027. The new acquisition, Uncovered, is said to be "the #1 TikTok partner in the EU". However, the deal financials make me nervous: LBG are paying nearly £27m, plus a £7m earnout, for 75% of a business that only made £2.7m of adjusted EBITDA last year (on £10m of revenue). Even with 50% growth expected this year, that's only £4m of forecast EBITDA, with an earnout also being owed to the vendors. And this deal empties the cash balance; LBG are borrowing from HSBC to help pay for Uncovered and to "take advantage of the Group's strong acquisition pipeline". We've seen this playbook before; I'm taking us down to a neutral stance on LBG. | |
Marks Electrical (LON:MRK) (£51m | SR60) | Revenue down 7.5%. Adj. EBITDA £2.5m as previously guided. Current trading is in line with market expectations, but “overall consumer confidence remains weak… we are taking a more cautious outlook for the year ahead on sales growth and gross margin.” | AMBER = (Graham) | |
Amigo Resources (LON:AMGO) (£36m | SR81) | Processing Licence No. PCL 0356/2026 was granted in respect of the Kabete Project. Approximately 1.1 kilograms of gold recovered during initial commissioning activities. Preliminary interpretation indicates encouraging correlation between micro-seismic results and previously identified geochemical target areas. | ||
Atome (LON:ATOM) (£32m | SR2) | ATOME notes the recent share price movement and confirms that discussions continue to progress with the Government of Paraguay and with ANDE, Paraguay's state-owned electricity supplier. | ||
Emmerson (LON:EML) (£27m | SR11) | The UK Intellectual Property Office has recently confirmed that Emmerson Plc's patent application titled Processing of Evaporite Minerals (Application No. 2315003.0) has been granted patent status. This patent provides IP protection for the core KMP process and its optimised derivative products. EML’s subsidiaries continue to seek compensation ($1.215bn) from Morocco. | ||
Caffyns (LON:CFYN) (£11m | SR36) | Revenue down 2%. New car deliveries down 11%. Used car sales up 4%. Underlying loss before tax £1.5m. “We faced significant trading headwinds during the financial year ended 31 March 2026 and have taken a number of actions to increase order take and reduce costs. These actions are delivering improvement." | AMBER= (Graham) It's the same story here as we've seen before: over a quarter of a billion pounds of revenues, but no profits. Motor retail is a tough business but Caffyns shareholders can at least reflect on some positives. The accounting pension deficit is now only £1.4m, and the balance sheet net assets figure remains close to £30m. This does not include a surplus in property valuations of some £10.7m. So we are talking about a £40m balance sheet vs. only an £11m market cap. In March, investor Andrew Perloff raised his stake to 22%. Value should be realised some day - the mystery is when. |
Graham's Section
PPHE Hotel (LON:PPH)
Down 20% at £16.10 (£674m) - Update on Strategic Review & Formal Sale Process - Graham - TAKEOVER (GREEN)
Very dramatic news here as it transpires that hotel group PPHE’s top shareholder Euro Plaza, owning 33%, is opposed to the planned takeover by Fattal Hotels.
Euro Plaza is the vehicle owned by PPHE’s founder Eli Papouchado.
Mr. Papouchado and his fellow shareholder, co-CEO Boris Ivesha (who owns 11%) were the ones who put PPHE into play last November, with the announcement that they were interested in monetising their stakes.
This kicked off a Formal Sale Process which led to a takeover offer from the Israel hotel group, Fattal Hotels, at £22 per share.
Fattal are also existing shareholders in PPHE, owning 4%.
The £22 offer was a nearly 50% premium to the PPHE share price last November, when this process began (c. £15). But it was also a 20% discount to PPHE’s official net asset value (£27.40).
The PPHE Board were happy to recommend a takeover at this price, and said that they believed it represented fair value. But they have now learned that Euro Plaza (i.e. Mr. Papouchado) does not consent to it.
How things stand currently:
Fattal is not going to proceed, given Euro Plaza’s opposition.
The £22 offer therefore cannot be delivered in its current form.
PPHE has received “an indicative proposal from another interested party”.
No further details are provided on this “indicative proposal”, other than “this interest is at a very preliminary stage and is currently being assessed.”
Graham’s view
Although the PPHE share price has been badly hurt by today’s news, I don't think that it should negatively affect our view of what this company is ultimately worth.
After all, Mr. Papouchado could have simply accepted £22 per share. He evidently believes that it is worth more.
Also, the new “indicative proposal” must be at a higher level than £22, or else why would the Board even bother to assess it?
I’m therefore going to stand over the claim that although PPHE is not worth full NAV, it is worth significantly more than the market has been giving it credit for. The market has often put it at a 50% discount to NAV, while an informed buyer (Fattal) were willing to pay a 20% discount..
At today's share price, it has given back the majority of the gains it made since last November:
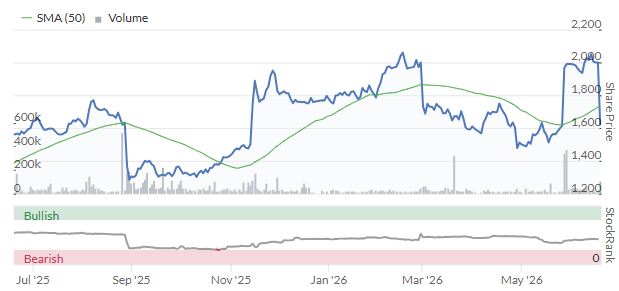
Personally, I’m therefore GREEN on this for value. Although it remains entirely unclear as to whether or not a takeover is going to be possible in the foreseeable future, as that depends on the view of the key shareholder. Given that he’s the co-founder of the business and still owns one third of it, he has every right to influence the outcome here.
Record (LON:REC)
Down 11% to 48.4p (£96m) - Annual Financial Report - Graham - BLACK (AMBER/RED ↓)
The market is not too impressed with the results from this FX specialist:
AUM +14%, boosted by exchange rates and other market movements.
Revenue down 4% (£40.1m), “due to mandate re-compositions and lower performance fees”.
Profit after tax down 23% (£7m), “reflecting tax rate normalising following prior year deferred tax credits.”
The final dividend is 1.45p. It’s not mentioned but this is a significant step-down from last year’s final dividend of 2.5p. And I don’t think the market was expecting it. So this is a surprise cut to the dividend.
Estimates: thanks to Panmure Liberum for publishing on Record today.
Their note confirms that the cut to dividend was a surprise move.
Other points of interest:
2026 earnings per share of 3.9p are below the 4.3p forecast
2027 EPS forecast gets cut from 5.1p to 4p
2028 EPS forecast gets cut from 5.4p to 4.8p
So let’s make no mistake: this is a pretty serious profit warning.
Using the new EPS forecast for FY27 and the latest share price, the shares are trading at 12x earnings.
At least the balance sheet remains strong and flexible with nearly £28m of net assets, which are almost fully tangible and highly liquid.
Outlook: focuses on the future and the need for a strong balance sheet to pursue their growth strategies.
"Record is a business in purposeful evolution… Private Markets strategies, in particular, offer the potential for longer-term, higher-margin and more scalable revenues as they mature. This is where our priorities are focused. These growth opportunities require continued balance sheet strength and disciplined capital allocation to support their full potential.”
Graham’s view
I’ve always had a great deal of respect for Record as an institution. But the difficulty with the investment thesis has been the lack of growth, and that remains the main issue today.
But they continue to look for new opportunities. The Private Markets strategies are described like this:
Private Markets includes strategies across areas such as Emerging Markets, Infrastructure Equity, Private Credit and Private Debt, designed in close partnership with our institutional clients… Private Markets strategies [...] involve a combination of longer lock-up periods, higher margins, or more predictable fee profiles, thereby improving earnings visibility over time. These solutions now contribute 28% of our revenue base…
Although the development of these Private Markets products has required patience and will be coupled with uneven revenue recognition in the early stages, this mix enhances the resilience and sustainability of our earnings base, while remaining aligned with our clients' long-term objectives.
Despite my fondness for the company, I’m going to turn AMBER/RED on it today, as today’s profit warning follows another one last November.
For what it’s worth, I do think that Record will continue to find success with its new strategies. But it’s difficult to avoid the conclusion that these efforts are to some extent merely replacing older revenue streams that are drying up. If the shares were obviously cheap then I could be more positive, but I don’t think that’s the case right now.
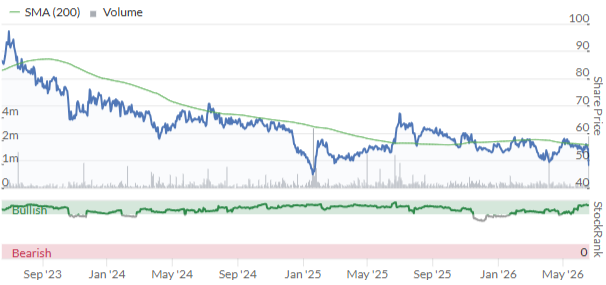
The 3-year chart tells a story of gradual decline:
Marks Electrical (LON:MRK)
Down 4% at 47p (£49m) - FY26 Financial Results - Graham - AMBER =
Marks Electrical Group plc ("Marks Electrical" or "the Group"), the online electrical retailer, today announces its full year audited results for the 12 months ended 31 March 2026 ("the year" or "FY26").
This is a revenue warning, but not a profit warning, as cost reductions are expected to keep profit forecasts intact.
Full-year results for FY March 2026:
Revenue down 7.5% “as we strategically reduced our marketplace presence, placing elevated focus on organic routes to market via the Group's main website and internal telesales.”
Adjusted EBITDA £2.5m (2025: £4.2m), as previously guided. Stronger in H2.
Pre-tax loss £0.5m (2025: £1.7m loss).
Net cash finished the year at £4.4m.
As announced yesterday, a CMA investigation has concluded with a financial penalty of £1.2m (reduced to £0.7m) and customer redress of £0.6m. The company was pre-ticking boxes at checkout for optional services such as appliance recycling. So the net cash figure will be under a little pressure.
Current trading and outlook: current trading is in line with expectations, but they are reducing forward guidance on sales.
We are well positioned heading into FY27 with positive trading momentum and a positive cash position. That said, overall consumer confidence remains weak with the level of UK inflation, interest rates and unemployment all impacting net disposable income along with concerns around the impact from the ongoing conflict in the Middle East on the cost of living.
Whilst we continue to target profitable growth, with the benefits of our rigorous focus in FY26 on efficiencies and operational cost controls expected to benefit the Group's FY27 adjusted EBITDA performance, we are taking a more cautious outlook for the year ahead on sales growth and gross margin.
Estimates: thanks to Canaccord Genuity for covering this today.
FY27 revenue estimate is reduced 8% to £108.3m, flat on FY26.
FY27 adj. PBT estimate is increased from £0.9m to £1.5m. The CMA settlement will be an adjusting item.
Graham’s view
I turned neutral on Marks in April and I will leave that stance unchanged today.
The themes in April were similar: company performance was predicated on margins and cost control, not sales growth.
As I said then, I have no issue with companies generating short-term performance via cost control rather than sales growth.
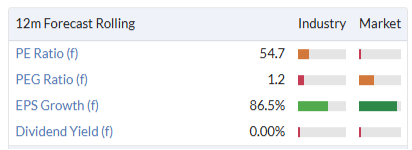
The market is patiently waiting for this to return to prior levels of profitability:
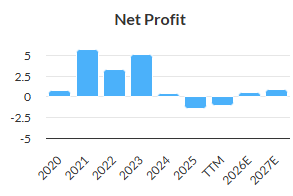
They’ve had a few very lean years:
I maintain an open mind as to whether they’ll succeed in achieving a profit rebound, so I’m neutral. At some point, they are going to need to find some sales growth. For now, they are treading water - and that’s ok.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

43 comments
I have just realised that Stockopedia have renewed my subscription at the increased full rate without any notice or time to consider other options. This is very poor practice IMO and I believe breaks direct debit rules. Anyone else had this poor experience?
Mine renewed at £295 Revs couple of weeks back , looking back on my sub history that's what i've been paying last three years not aware of any recent price increase.
Mine was also renewed without notice a few weeks ago - luckily I did want to renew the subscription, but I also believe it to be poor practice not to advise the subscriber in advance of what is, after all, a not inconsequential direct debit payment.
My subscription is taken from a credit card. As I understand it "Direct debit" with its notification rules refers only to bank a/cs. Credit card debits are made under a "Continuous Payment Authority" and I believe this does not have the same requirements and not telling you of increases is allowed albeit regarded as sneaky.
On the Today programme this morning it was stated that Burnham is receiving economic advice from Andy Haldane, who used to be chief economist at the Bank of England. Let's hope that his will restrain his Liz Truss instincts. He certainly backtracked pretty quickly on compensation for the WASPI women.
Thoughts on Record (LON:REC) appreciated, AUM up but everything else down, including dividend. Market not impressed.
Dividend payout was too high (92%!!). Always going to get cut I think... when something goes close to 10% yield it's in danger zone. Any write-up would be good
Hunter- as I understand it the dividend pay out ratio was maintained at 92%, whats happened is the EPS has dropped. Interestingly the FY27 EPS forecasts on Stocko are for 4.9p, if this forecast is still applicable/if it is hit/if the ratio is maintained at ca.90% again thats an 8.8% yield this time next year based on a share price of 50p today. The word "if" doing a lot of heavy lifting here!
Haha yes. They are changing their dividend policy though, and lets be honest.... it's not going up....so I think that forecast has to come down but dont know how much by
re: REC. GloucesterBob, I hope my comments were helpful! A nice business, I hope they return to glory some day. Have a good one. G
Graham, appreciate the update. Mainly hold for the dividend, with the hope they will creep back up, but following your write up may off load on Monday.
Record (LON:REC) - thanks Graham. The main drag appears to be the new Asset Management business that lost £1.7m and Absolute Return net outflows. The lower margin risk management currency busines is doing well. In AM Fund launches and deployment of funds is taking much longer than expected, reading between the lines. I had hoped that Absolute Return strategies would do well again like wehen they floated as these are very high margin, but this area is also struggling. It's definitely been disappointing with the new CEO so far. If the AM business does become successful it is a very high quality long-term income stream, so I will give them the benefit of the doubt. Absolute Return currency trades working again is thrown in for free, but no sign of that at the moment. I think its good value in the 40s, so will be holding longer term unless they continue to disappoint.
Why anyone wants to be PM is beyond me. It's career ending, and the pay is not even that great. May as well be remembered as being a decent mayor of Manchester.
Hubris.
Public Service is Noble? Clearly on on here today!
Yep. It may well be his time, but not the right time...
Power.
career ending?
they all earn an absolute fortune after...speech circuits, media, in business as consultants etc..
That's the kicker , I'm sure Prince Harry got an eye watering sum for letting JP Morgan put his name on their paperwork in the past.
Career ending! Somebody should tell that to Tony Blair.
If only.
Agreed the problems with 25-30 years of poor decisions in the West in general are now getting ever harder to hide and the electorate wants easy answers which aren't there hence we have gone through numerous prime minsters in record time.
Not to forget the PM pension for life. Even Lizz Trust gets it.
I think an ex PM can claim over £100K a year…Even Liz Truss.
They can claim EXPENSES for the continued running of their office, it is neither a pension or a salary. I am sure Mr Blair still manages a large expensive office - the rule is actually:- The Public Duty Costs Allowance (PDCA) and is currently capped at £115K per annum
We still have a few places available for the next Yellowstone Private Investor Evening on 24 June This is a chance to meet management teams and fellow private investors face to face in a relaxed environment. Listen to company presentations and then take the opportunity to ask your questions over drinks and canapes. The following companies will be presenting (Value report rating):
Cavendish: Julian Morse, CEO (Green)
Amcomri: Hugh Whitcomb, Co-Founder and CEO and Mark O'Neil, Chief Operating Officer (Amber)
Time To Act: Chris Heminway: Chief Executive Officer & Chief Strategy Officer (NA)
Doors open at 5.15pm and the event starts at 5.30pm in EC1
Register: www.yellowstoneadvisory.com/events
Cavendish (LON:CAV) Amcomri (LON:AMCO) Time To Act (OFEX:TTA
Having attended a few of the Yellowstone events in the past, I have to say that I am very grateful that they are doing this for private investors! Too often, meeting management is only for institutions or at events like Mello that take place once or twice a year. It is also a good chance to meet other investors too.
World Cup - Since we are off topic a bit this am..... I thought of going down to Ladbrokes and getting the odds on England beating Germany 4 -2 in the final after extra time!!!
Hi Graham, Morning all,
Graham, could you please addCordiant Digital Infrastructure (LON:CORD) to the list of companies reporting today? Our new FTSE250 company has finals out this morning.
Earnings of 20.81p on a share price of 124.5p gives a historic pe of just 6. Coupled with a nav of 146p means that for me, the shares are in the bargain basement. I hold, but would welcome your opinion.
Seems a pretty solid update for Cordiant. Looks reasonable value relative to NAV and the free cashflow of the underlying businesses . As an investment trust PE ratio is not a relevant metric so would ignore this.
That's done!
Yes, this stock is well under the radar, which is good and bad!
Andy Burnham Prime Minister and Ed Millibrain as Chancellor. ....
What will that mean for the markets????
Millipede will have his feelers in every strivers pocket
One might reasonably contend that his fingers have been there for some.
chaos, no policy, no strategy, just more socialism
Interested in the user of the word 'more' there John. What 'socialism' have we seen so far from this Labour government?
To me (my view) Socialism generally means, less democracy, more central control, more laws, mistaken liberalism, penal taxation, excessive spending on non productive assets, suppressing capitalism, less defence, appeasement (Iran), globalisation (open borders), wokeism (leftism), suppression of alternative views, identity cards!
i am more concerned about what it will mean for CGT
Did Burnham not say he would not increase CGT whereas Streeting wants it combined with Income Tax
Streeting has indicated that he wants CGT charged at the same rate as Income Tax.
He is forgetting that individuals who pay CGT have already paid their income tax. Essentially he wants to penalise those who have resisted instant gratification by saving some of their income.
Streeting is not a serious candidate in my view, whilst equality of opportunity is desirable, equality of outcomes is counter- productive to the nation's growth.
Gilt rates north of 6% maybe ?
gilts to 10%!
let's go!
no?