Daily Stock Market Report (Fri 1st May 2026) - SYNT, NWG, NRR, SRB, WTB

Good morning! Happy May Day - or Calan Mai, Beltane, Labour Day, or whatever you prefer to call it!
As it's Friday, I'll attempt to catch up on interesting stories we missed during the week.
Bank of England/ECB: there was lots of discussion yesterday about the need for rate hikes.
At the ECB, where rates are starting from a lower base, they considered hiking yesterday - but ended up pushing the decision back to June.
The Bank of England gave us a thought experiment - different inflation scenarios based on second-round effects kicking in from the oil supply shock.
No probabilities were attached to each scenario, but the one referred to as Scenario C was "likely to warrant a forceful tightening in monetary policy".
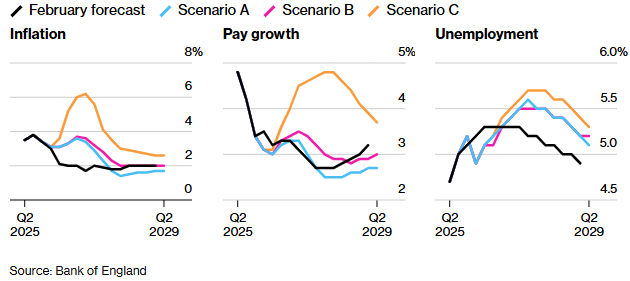
The consensus reads: "there is a risk of material second-round effects in price and wage-setting, which policy would need to lean against".
Markets are now pricing in two BoE rate hikes this year, although there is clearly the potential for more than that. Chief Economist Huw Pill wanted a hike yesterday.
The bottom line? Domestic stocks are unlikely to get a boost from rate cuts any time soon.
All done for today, have a good weekend! Spreadsheet accompanying this report: link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Natwest (LON:NWG) (£51.4bn | SR85) | Attributable profit £1.4bn, EPS +15.5% compared with Q1 2025. ROTE 18.2%. TNAV per share 400p (share price: 585p). “Based on our latest expectations for interest rates and economic conditions, we now expect income excluding notable items to be at the top end of our previously guided range of £17.2 - 17.6 billion.” | GREEN ↑ (Graham) [no section below] This ROTE return is excellent and I note that the full-year result was even better at 19.2%. We’ve been moderately positive on this one (see Roland’s coverage last year) but at that sort of ROTE I don’t know how I can avoid upgrading it. The P/E multiple is now 8x and it trades at a premium to book value, so it’s a little expensive in sector terms, but the earnings growth and returns appear to justify that. If it wasn’t a bank, I’d be very interested to buy a stock with this value-quality combo! The CET1 ratio of 14.3%, which has increased since Dec 2025, says that it’s still being run conservatively despite the strong returns generated. | |
Pearson (LON:PSON) (£6.5bn | SR73) | Underlying sales up 4%. On track to deliver 2026 guidance. £350m share buyback programme progressive well. | ||
Rotork (LON:ROR) (£2.5bn | SR39) | Q1 performance in line with expectations, full year guidance unchanged. Revenues up by a low single digit percentage on organic constant currency basis. | ||
Newriver Reit (LON:NRR) (£323m | SR70) | LTV reduced to “close to medium-term guidance level of <40%”. FY March 2026: Underlying Funds From Operations per share and EPRA Net Tangible Assets per share expected to be in-line with analyst consensus. | AMBER/GREEN = (Graham) [no section below] Roland reported on this retail REIT last month, noting that the <40% LTV target hadn’t been reached yet (it was 42.3% last September). That remains the case today, but NRR says it is “close” to hitting the target. The difference of an extra 1-2% in LTV doesn’t matter if the properties are performing, and that appears to be the case with funds from operations in line with consensus (i.e. around £37.2 million). Disposals are happening in line with book value, at least in the aggregate, implying that net tangible assets per share (107p) may be a realistic figure. With a share price of 75.5p, representing a 29% discount, I’m happy to leave our moderately positive stance unchanged. If I was investing primarily for yield, this would be high on my list of candidates for further research. The retail environment might be fragile but I don’t think NRR is taking on all that much financial risk. And it has borrowed cheaply: at less than a 200 basis point premium to base rate. | |
Serabi Gold (LON:SRB) (£252m | SR99) | Revenue of $155.8 million (2024: $94.5 million) reflecting higher production and gold price. Inaugural annual dividend payment of 5p. Net cash $42.1m. “Whilst our stand-alone strategy envisions growing the Palito Complex and Coringa into a consolidated +100,000 ounce per annum producer, we remain amenable to inorganic growth opportunities…” | AMBER/GREEN = (Graham) | |
Redcentric (LON:RCN) (£208m | SR58) | Successful completion of the sale of its entire data centre business for estimated £122.85m. Initial payment of £115.4m was received on 30th April 2026. Enables “a substantial return of capital to shareholders, significant debt reduction, and a sharpened strategic focus on growth opportunities within the remaining Managed Services Provider business.” Tender offer proposed for >£90m at 160p. | ||
Mkango Resources (LON:MKA) (£176m | SR10) | Pre-tax loss $17.8m. Cash $3.1m at year end. Subsequently raised net proceeds £11.7m. HyProMag Ltd (UK): Evaluation underway for a phased expansion of capacity starting next year. HyProMag GmbH (Germany): plant was officially opened by the German Federal Ministry for Economic Affairs on 28 April 2026. HyProMag USA: lease agreement in Texas signed in December 2025. | ||
MJ GLEESON (LON:GLE) (£134m | SR44) | Net reservation rates for the 11 weeks to 24 April were 0.88 per site per week (last year: 0.86). Excluding bulk reservations: 0.59 this year, 0.64 last year. New provisions for remedial works: £5.2 - 7.1m. Outlook: Adjusted PBT in line with market consensus. | ||
Shield Therapeutics (LON:STX) (£93m | SR27) | Net revenue $18m (Q1 2025: $7m). EBIT $2.5m (Q1 2025: $4.4m loss). | ||
accesso Technology (LON:ACSO) (£88m | SR85) | Following a “long-planned transition period”, a new CEO has been appointed. He joined as COO in Jan 2025. | ||
Pulsar (LON:PULS) (£54m | SR42) | Revenue £61.2m (2024: £62m). Adjusted EBITDA £10.4m (2024: £9.3m). Pre-tax loss £9.5m (2024: £6.7m). “We are at a clear inflection point in our cash generation profile, with a strengthened balance sheet and significant operational momentum...” | ||
Proservice Building Services Marketplace (LON:PRO) (£31m | SR34) | “As previously announced, FY27 is expected to be a transitional year and this is now set against an uncertain macro-economic backdrop… Given the potential volatility in the UK economy, the Board believes a prudent approach is required and therefore FY27 underlying EBITDA is expected to be between £9 million and £12 million.” |
Backlog
Synthomer (LON:SYNT)
Up 41% today to 97p (£159m) - Final Results - Graham - AMBER/RED ↑
There has been a stampede into this polymer stock today, although its results were actually released yesterday.
We’ve been RED on this, flagging it as a high-risk situation (e.g. coverage last month). But high-risk situations sometimes work out well.
The key news is around refinancing:
· Stable financial position to support delivery of strategy including divestments and earnings recovery
− Bank facilities refinanced with maturities extended to 2029
− Net debt: EBITDA covenants reset; security and guarantee package provided by certain group companies
Bank support is necessary considering the following:
2025 revenue down 10%
Underlying operating profit down 21% to £37.6m
Statutory loss £120m (last year: £87m loss).
And in terms of the debt burden:
Year-end net debt £575m, many multiples of the market cap.
Net debt:EBITDA multiple 4.7x
The required leverage multiple was 5.25x, so they passed that test..
New covenant tests:
The net debt:EBITDA ratios required under the covenant for year end 2026, 2027 and 2028 have been set at not more than 6.25x, 5.25x, and 4.25x respectively…
These are all higher multiples than what is typically considered acceptable. Anything above 3x is risky in most industries.
Also, the balance sheet provides little tangible support. Net asssets are £54m after excluding intangibles.
Outlook: “Q1 2026 in line with expectations and ahead of prior year; expecting robust Q2 2026”
And this is encouraging:
Full year expectations of year-on-year progress driven by self-help actions unchanged at this stage. Given the current conditions, risks are to the upside but longer-term effects of the Iran conflict remain uncertain
Graham's view
Normally I would be RED on a business with net debt standing at many multiples of its market cap.
However, Synthomer looks like it may be on a path to survival.
The largest shareholder - a Malaysian company called Kuala Lumpur Kepong Berhad - has helped to bail it out by buying £50m of its receivables. Its RCF lenders and UK Export Finance are also standing behind it.
But a word of warning: its €350m bond was still trading yesterday at just 63 cents on the euro, signalling that it's still viewed as high risk in the bond market:
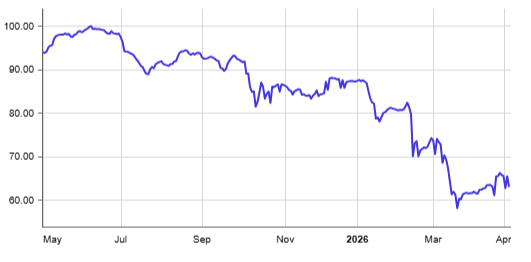
According to the Deutsche Börse website, the yield on this bond is over 27%.
Buyers of the common stock have seen this four-bag since the March lows.
But I think the bonds might also be worth a look: earning 27% until 2029 is not to be sniffed at!
I’ll upgrade our stance on this to AMBER/RED, reflecting that it’s still a high-risk situation, but one where most of the lenders remain supportive.
Whitbread (LON:WTB)
Down 5% since yesterday at 2280p (£3.8bn) - Preliminary Results & Outcome of Business Review - Graham - AMBER/GREEN ↑
A big shakeup is on the cards here.
Let’s focus on the Outcome of Business Review announcement.
Background: “in light of significant cost increases in the form of business rates and National Insurance, as well as the implied market discount to our inherent value, we've looked hard at the options open to us to maximise value creation…”
The main three planks of the plan:
Network expansion: Reallocating capital spend to the highest returning opportunities while growing rooms (£110m incremental PBT contribution by FY31).
Accelerated growth: Replace all 197 branded restaurants with a more efficient integrated restaurant offering. 110 of the restaurants to be sold as going concerns. A 100% integrated food & beverage offering will allow more rooms and a 15-20% return on capital, with £100m incremental PBT by FY31. Job cuts: 3,800.
Lower capex: £1bn capex reduction in total capex vs. the previous Five-Year Plan. Recycling £1.5bn of freehold property. Looking to grow on a leasehold basis from now.
The new target is £275m of total incremental PBT by FY31, compared to FY26.
For context, adjusted PBT in FY26 was £483m. So I think they are looking for compound profit growth of about 9% p.a.
The plan will turn Whitbread into “a higher-margin, higher-returning pure-play hotel business.”
Graham’s view
Here’s a summary of the financial changes to the Five-Year Plan. What’s striking to me is that the PBT targets haven’t changed all that much (in red):
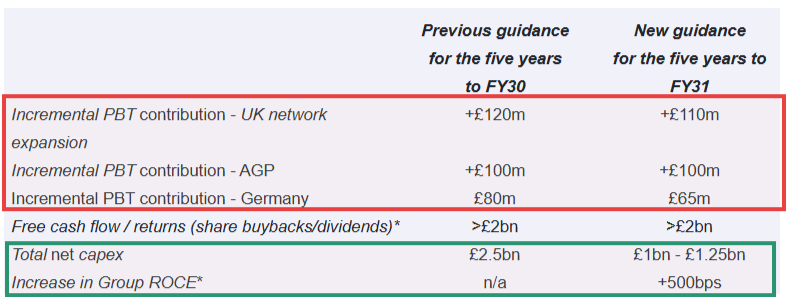
The really big change is in capital intensity: lower capex and higher ROCE.
The company calculates its own ROCE at 11% in FY February 2025 and FY February 2026, and is now targeting 15-20% by FY 2031. Investors should beware that the company's heavily adjusted calculations come up with much higher historic ROCE figures than Stockopedia does.
There is no change to the free cash flow forecast over this timeframe but I would expect higher cash flows and more cash available for shareholders in the subsequent years.
The plans should placate US hedge fund Corvex, who have been agitating for change (and Board representation):
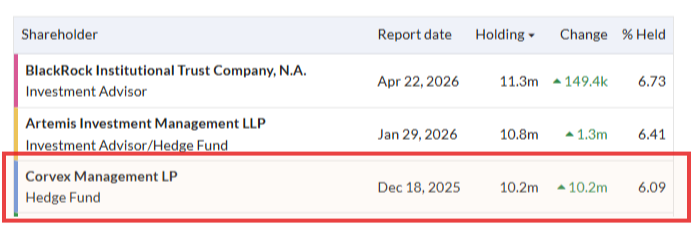
Revealing its stake in December, Corvex said:
“…following the recently announced UK Budget and changes to rateable values and business rates, we believe the Company should undertake a strategic review to assess its capital allocation priorities and overall strategic direction…
In particular, we believe the Board of Directors… should review the Company's current five-year capital plan, which contemplates approximately £3.5 billion of investment—an amount approaching the Company's current market capitalisation.”
That £3.5 billion total investment figure given by Corvex doesn’t match the net capex figure supplied by Whitbread itself (£2.5bn), but the overall point is understood. Either the market cap is too low, the planned spending will generate very weak returns, or some combination of the two.
I’m happy to upgrade our stance on Whitbread by one notch, to AMBER/GREEN, as it’s not particularly expensive here and ROCE should improve, freeing up cash for shareholders in the long run.
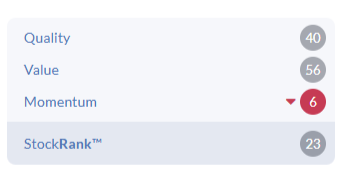
Historic performance is unimpressive, and the stock has been a dog, which is reflected in the StockRanks:
The new strategy moves Whitbread towards the Travelodge model: a simple restaurant with a limited, standardised menu. It's fair for guests and employees to have mixed feelings about this - but it makes sense for shareholders.
Graham's Section
Serabi Gold (LON:SRB)
Up 1.5% at 338p (£257m) - Audited Results for the year ended 31 December 2025 - Graham - AMBER/GREEN
Excellent results here, as expected, at an average gold price of $3,481.
The live gold price today: $4,576.
In February, Mark covered this one and gave us the following table:
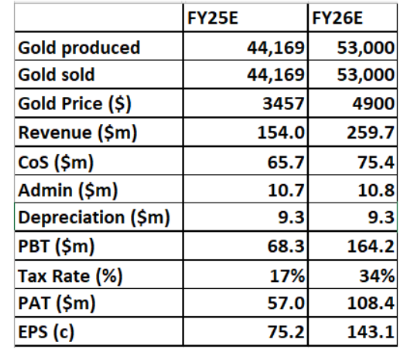
His numbers for FY25 are impressively close: actual revenue comes in at $155.8m, and after-tax profit (PAT) comes in at $53.9m.
For FY26, each $100 move in the average gold price changes the revenue and profit figures by $5.3m, pre-tax. Or maybe slightly more - production guidance is for 53,000 to 57,000 ounces.
Assuming that the difference converts cleanly to profits, there is a 1.6% change in PBT for every 1% move in the gold price.
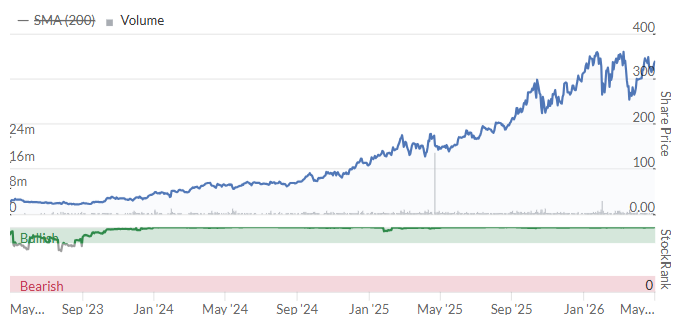
Which makes this a very effective bet on the gold price, as it has been for years now:
The All In Sustaining Cost in 2025 is $1,816, which I understand to be above industry averages - but very profitable in the current gold price environment.
Cash balance: $49.2m.
Inaugural Dividend: 5p per share, value $5.4m.
2026 shareholder returns: 20-30% of free cash flow to be returned via dividends or buy-backs.
Comment by the Chair: they are targeting 60,000 ounces of gold from 2027 onwards, with an aggressive brownfield exploration programme in Brazil:
…the Company drilled 38,400m which has already contributed to the growth of our consolidated M&I [measured and indicated] resource to 731,000 ounces of gold and Inferred resource to 653,000 ounces of gold. Whilst a significant discovery was made at Coringa, there were many additional veins which were drilled on both properties and incorporated into the updated mineral resource estimate. The results of the first year alone, reinforce the Company’s understanding of the wealth of brownfield mineralisation available near its mines and we therefore remain optimistic that the second year of our brownfield exploration programme will achieve the targeted growth range.
Graham’s view
I’m not going to rock the boat by changing our stance here.
We are AMBER/GREEN, but our stance is almost redundant - the main driver is the gold price.
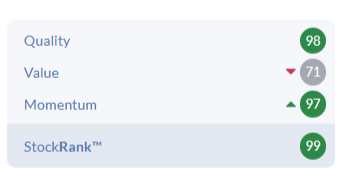
The StockRanks continue to love it:
I have personally only ever invested in one mining stock: Orosur Mining (LON:OMI). This was a long time ago - somewhere in the early 2010s, back when it was a gold producer in Uruguay.
I had done my research, and understood that the cash flow being produced was enormous relative to the market cap.
But I soon learned my lesson. The cash flow from successful production operations was reinvested into various other projects, including exploration.
If the cash had been delivered to shareholders, it would have been a successful investment. Instead, it was spent on various other projects, some of which worked, and some of which didn't. I sold and never looked back.
At least Serabi is promising to spend 20-30% of its free cash flow this year on shareholder rewards. That’s a solid sign of shareholder orientation. But if I was invested here, I’d be asking for even more.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

59 comments
Just one month to go until Mello2026 now and it is set up to be a cracking Mello.
The first 25 companies are on our website but plenty more are to follow. Keynotes & speakers will include Christopher Mills, Georgina Brittain, Lord John Lee, Max "Malcolm" King, Richard Staveley, Vin Murria and more.
Tickets are now on General Sale and moving fast! Use code Stockopedia25 for a 25% discount if you would like to join us:https://www.melloevents.com/mello2026
There will be plenty of fellow Stockopedia users to catch up with and talk all things investing.
Hope to see you in Chiswick on the 2nd & 3rd June.
Orosur Mining (LON:OMI) "But I soon learned my lesson. The cash flow from successful production operations were reinvested into various other projects, including exploration.
If the cash had been delivered to shareholders, it would have been a successful investment. Instead, it was spent on various other projects, some of which worked, and some of which didn't."
Yes Graham, a lot can go wrong with inestments in small gold miners and I'm thinking of Ariana Resources (LON:AAU) which I hold. It has done what you have described above. I can understand the need for a miner to get set up in a new discovery before the ore runs out at its current mine and hopefully Ariana will pull it off at Dokwe in Zimbabwe. It appears to me it finds it hard going there , those who have stuck with it may well lose out in the end. Bitten off more than it could chew? Luckily I hold a number of other gold miners, the stand-out being Anglogold Ashanti (NYQ:AU) which I hold by default after Centamin, another small gold miner this time in Egypt which was promising but was snapped up before realising its potential.
SRB, How much of a risk is the current lack of long term permit at Coringa?
Newriver Reit (LON:NRR) may have borrowed cheaply at 2% below base rate, but I think therein lies the risk - they'll need to refinance a large bond in a couple of years, probably at a much higher rate than the existing bond given 10y gilt yields now at 5%. By my calculations the additional interest costs could take a decent chunk out of earnings - something to at least be aware of if thinking about investing.
Bouden - just want to clarify for readers that NRR have borrowed at a margin of 175 - 190 basis points over base rate, i.e. at a margin of less than 200 basis points over base. Is that what you meant?
Yes thanks for correcting. However, the main point I wanted to make is the large 3.5% bond maturing in 2028 - they will probably need to pay a much higher rate when this is re-financed, depending on what happens to interest rates before then. Due to its size this may hit earnings quite hard, although I don't think it would put the dividend at risk.
That's the same reason I have reduced my exposure to aewu re financing next year
Probably a bit late in the day now but would be very interested to hear thoughts on Whitbread (LON:WTB) and their new five year plan. Did anyone look at this yesterday?
WTB
On a quiet Friday, it would be great to have some views on this company. As the foreign travels become less affordable in the next few months, may be the Premier Inn owner finds itself in a sweet spot for internal tourists!
And don't forget that if you hold 64 WTB shares then you qualify for free Premier Inn Breakfasts for yourself and another guest and up to 2 children.
Yes Whitbread (LON:WTB) looking tempting at these levels after what I thought were pretty good results.. I've heard a few people mention they won't be booking flights this summer as worried about possible cancellations due to fuel shortages - should be good for the likes of Premier Inn. I think the growth prospect in Germany also look very interesting - they say it's a very fragmented market and see it as a once-in-a-generation opportunity to dominate the branded budget sector.
I've covered Whitbread now, hope it's helpful! Thanks for the suggestion. G
Those of us who like investing in fund managers might be interested to see how well Polar Capital Holdings (LON:POLR) is performing. Daily fund sizes are publicly available through morningstar and other data providers so it's possible to track how their AuM is doing. For April my calculations suggest their AuM has increased by an astonishing 18.4% in one month, driven it seems by their tech exposure which has had a very strong April both in market performance and fund inflows. The fund size below was around £9bn at end of March and Morningstar is suggesting it's now £12.4bn
Clearly we might be in a tech bubble but then we've all been saying that for about 10 years!
You're right the performance of their key global tech fund has been absolutely astonishing recently, up 138% over last year versus sector returns of 45% (and as you say seems to have shot up by about 30% in April alone). Not sure what they're doing and if sustainable but providing no major pullback we should see a significant rise in AUM at the next update.
I appreciate the benefit of the colour coding used in the Stockreport even when it shows a rare bird -a value trap with a 94 value rating.
I love investing precisely because reading this in today's report made me smile. I'm a bit of a contrarian investor, so my initial instinct is I need to double down on domestic stocks now...
>>> Markets are now pricing in two BoE rate hikes this year, although there is clearly the potential for more than that. Chief Economist Huw Pill wanted a hike yesterday.
The bottom line? Domestic stocks are unlikely to get a boost from rate cuts any time soon. <<<
I bet that if we went back a few months before Iran, the opposite statement was "markets are now pricing in 4 rate cuts in this year. The bottom line? Domestic stocks will do well as rate cuts put more money in pockets"
----------
I've come to realise that in today's unpredictable world, the value of predictions (ie futures markets like the rates market) are become less useful.
Predictions are useful if the world or system is in a steady state.
But when we have a world increasingly not in a steady state (politically, technologically, climate) - are predictions becoming less accurate?
After all, I keep hearing grumbles from everyone that "last few years, its been one thing after another! When will it end?". And I think collectively, we still expect a world to "go back to a normal" steady state, but what if we've now transitioned to one that that has more permanent entropy?
I was lookin forward to the bank holiday weekend until I read the last paragraph in your ramble Boon sadly I fear you are right its looking like the world will be a more dangerous place for a while moving forward. Three old men representing the worst humanity have to offer at the wheel time and again we seem to still let these people into the ultimate power seats.
The worst aspect is that one of them wll leave an enabling self funding political legacy for the future .
In fairness, these aren't predictions as such - they're the BofE view about possible consequences arising from different scenarios. The issue is that there is less certainty now of what scenario is likely to happen.
Some things are predictable. For example that things are unpredictable which is a constant.
Personally i thought this went up a gear when Trump was elected. I moved to a very defensive portfolio in January last year.
I think he will only get worse and the Iran situation will deteriorate. So i am moving more into cash.
What's top of your list Boon? Jet2 (LON:JET2) is at the top of mine at the moment.
I have so many thoughts on Jet2 (LON:JET2) but can't comment as I work for a competitor/customer in package holidays.
Out of my current holdings, my highest domestic play convictions:
My list of shares that are below my buy price (but for one reason or other not bought yet):
In light of world events I feel I should increase my holdings in oil and gas. I have some holdings in North Sea oilers which are doing well, but would appreciate some others. Any suggestions welcome.
Maybe I should explain why. A friend has been working in the ME for many years. He says that Iran has 39 districts all of which function independently in a decentralised manner. Killing the ayatollah will not solve anything. He feels the blockade will continue, and they are in control over Hormuz. On this basis, oil price will remain high. The other issue is the Sunni/Shia issue relating to the relationship with the other countries in the area.
The world will find work arounds and marginalise Hormuz to the detriment of Iran. As fast as possible please - then they can go back to the Stone Age without outside help
Great response - thanks!
I'm curious as to why you rate THG (LON:THG) so highly? Warpaint London (LON:W7L) recently had a terrible Q1. THG is not profitable and I'm not a fan of adj. EBITDA .
On THG (LON:THG) I'm attracted as I think they can get to a profitable margin in the next year or two, both in Beauty and in Nutrition.
They own the largest online beauty eCommerce shop by a country mile in the UK. A smaller competitor closed recently (Beauty Bay) and there just isn't much competition; I expect them to be able to squeeze more margin easily, and they seem to have growth pat down too.
In Nutrition, MyProtein is the largest global brand of nutrition products.
So you take both - the largest in their categories - UK and Global - and there's some strong value that's not reflected in the market cap.
In MyProtein, there is a very strong growth engine, both D2C through their websites, as well as rapidly accelerating distribution through retail partners globally, and also licensing out the brand into more and more foods that are "high protein". Their margins have been depressed recently due to the high whey prices, but this is a function of a temporary squeeze in manufacturing, as protein has really taken off. More whey manufacturing is coming on-stream this year.
9% is the management target for EBITDA. They did 4.5% last year. Even my modelling at 6%, 7% (still falling short of the target) yields quite impressive operating profit, PBT, when combined with another 10-15% top-line growth in the next 1-2 years.
Finally, its been the subject of many bid approaches in the past 4 years; and given the market leading position of the two brands, I think a bid is very credible at some point.
Matt Moulding has also recently bought a big chunk of shares at the 31-32p mark, so another vote of confidence that this level is value.
Thanks, great context.
Essentially it's at the cusp of proper profitability (within the next couple of years), when the market is pricing it continuing to be loss making?
Also, why aren't you concerned by the debt load here? According to Alphaville they'll be getting a VAT refund in the late summer. I know they've disposed of several businesses. Are there any other assets they could sell to reduce the debt load? Or will they have to deliver any deleveraging purely through operating cash flow now ?
Net debt - at Dec25, was £233m on £76.6m EBITDA (4.5% EBITDA margin).
On a recent results call, they stated ambition to get it to half of that net debt number by year end (Dec26). From VAT refund, also FCF generated.
Seems credible - FCF I think they could do like £30-50m easily. VAT number announced already (can't remember, but big).
----
This year, if you take like 5-10% revenue growth, EBITDA margin improving from 4.5% to say even 5% or 5.5%, we're probably looking at EBITDA approaching £100m. And net debt will be just over that. And the direction of travel, for FY27, would be EBITDA keeps going up, net debt keeps going down (from FCF). So very comfortably at <1x leverage. In less than 12 months time.
That for me is the big disconnect; investors still barge-poling as prior history has been "high debt load" and "permanently low profitability". My central thesis is this year, its proven that the debt direction of travel is to safe, and profitability is something the company accelerates.
Volatility creates opportunity.
Rotork (LON:ROR) trading update pretty similar to Weir (LON:WEIR) actually but the shares have travelled quite differently over the last year or two. Today Rotork (LON:ROR) inline but also with H2 weighting and assumption that H1 delays will be recognised in H2. Any resumption in the North Sea would obviously be not too bad for Rotork (LON:ROR) but also more Oil drilling generally assuming delays implemented since Mid East do return. Seems like that will set the scene for H2 - trying to work out who is best positioned to manage delays and/or supply chain disruption. The pecking order of contracts and which will progress anyway will be pretty important. Since Rotork (LON:ROR) sits on a 5 and 10 year relative low there some weakness already baked into the price and so todays reaction suggests inline is enough....a decent starting point. (Im not involved).
Anyone any thoughts on Natwest (LON:NWG) results look good and outlook seems deent but off 3-4% at open ?
Market probably worried about a Windfall tax on Banks by the tax grabbers.
Could be but all banks globally are trading off on results no matter how good numbers are....suggesting the market is calling a top which "probably " means recession/slow down risk is out weighing higher for longer rates thinking IMO. (no position).
Ignoring windfall tax - do the banks stll benefit from being able to get uber cheap lending from the government ? thats always seemed like a ridiculous freebie to me when they are making bumper profits - perhaps charging fee on top is more sensible rather than "another bank tax"
lets be frank here the FCA does cover taxpayer for default - so i would say theer is some logic for banks having to pay more tax - over the years the people running the banks have been happy to play fast and loose with rules to benefit themselves **- perhaps banks are more straight laced now - but i kinda get it why they were being hit with stuff on top for awhile.
** the banks did close to zero proper checks before handing over goverment backed cash during covid - i know the money needed to be released quuicklly but would it have ben too much to ask in the subsequent 3 monthn period "can you supply proof of tunrover" ref recent claim so the fraudsters could have ben taken to task there and then - rather than being allowed to sail of into the sunset.
Ok sorry ot rant over.
As I recall, during Covid it was the government demanding that the banks should lend, no questions asked - and to persuade them, said they'd indemnify any losses. Reckless? Yes. But not by the banks.
Reckless? Yes. But not by the banks.
sorry the banks were completely reckless with taxpayers cash - plain and simple they perfoemed no basic subsequent checks - they were probably obliged under mlr rules to pay more attntion if i am being frank
you are right that it was the government demanding that the banks should lend - however.,
You have completely missed or sidestepped my point - there was eligibility criteria that needed to be met for people to be eligible for loans at levels they applied for.
i am fully aware banks hand to lend - one could only apply for funds based on prior turnover - so there was a limit of something like 3 times turnover.
so anyone who asked for more than 3 times their turnover was commiting an offence - i think my post was reasonably clear that once money was lent - sensible thing would have been to quickly establish eligibility therafter - thats not controversial and could have flagged up all the cheaters soon after (unless they doubled down by committing further fraud ) - that would have nipped it in the bud ref the fraudsters (and idiots who claimed more than the were eligible to) - to this day they are playing see no evil and here no evil ref these loans - trying to ask questions 6 years later -well thats not gonna get the money back for taxpayers.
Natwest not as cheap as it was - trading at around 1.4 tangible book value (which is how banks should be valued as year-to-year earnings can be volatile) against a wobbly economic backdrop probably looks about right to me. I would be interested if it got to around 1.2x book value (around 480p).
Thanks Bouden, RD & Trident for the replies , yes banks have had one hell of a run and given the pending economic backdrop and most of the charts its looking like the top was in 2-3 months back.
The upside there will hopefully be a better entry point to investors preferred bank stocks in the next 6-12 months.
For the time being there is still a juicy dividend return to offset some risk !
Trident, rightly or wrongly I swtched from HSBC Holdings (LON:HSBA) to Natwest (LON:NWG) this morning for this reason.
Quieter day so I'll throw in a small comment: the Q1 update from Shield Therapeutics (LON:STX) looks solid. There's a new Cavendish note. No changes to it's f/c as this was presumably expected, however the market seems to dislike it, marking it down sharply this morning, either folks expected more than the +54% ACCRUFeR revs increase, or it's the comments re US Medicaid (requiring prior authorisation for prescription approvals). Cavendish restates 23p target. I hold. After many wobbles, they seem to be consistently delivering and I for one would consider opportunistivally topping up despite this being an already chunky position.
Revs8 is the man to ask on this, but he expected a period of consolidation.Theres' is a high price minority product, it will never be a state health care staple but there is further scope
Thanks snowdrop. I was a holder and looking for a new entry point. See my reply to Mark above.
I was a holder. I believe this time of year causes weakness for Shield Therapeutics (LON:STX) .
No doubt on the long term growth of the product and new markets coming on stream but traders won't wait IMO. Loss of CFO was disappointing but could be an opportunity if they can find the right replacement who knows this sector.
Chart would suggest an entry price of maybe 6.3 to 6.8p. I am watching closely.
any chance of looking at Synthomer (LON:SYNT) ? no news recently but look at the chart!
Synthomer (LON:SYNT) final results were yesterday. Not covered in the DSMR.
EDIT. Stockopedia StockReport has the Final Results yesterday for Synthomer (LON:SYNT)
Yesterday on Reuters:
April 30 (Reuters) - UK specialty chemicals supplier Synthomer SYNTS.L forecast stronger second-quarter volumes and margins on Thursday as it capitalises on robust demand and pricing while Asian rivals grapple with supply disruptions, sending its shares as much as 33% higher.
Since the start of the Iran war, it has been able to pass on higher raw material and energy costs to customers and ship more of several base chemical products due to disruption at competitors, particularly in Asia, Synthomer said.
The conflict offered it "huge opportunities as well as challenges," the maker of polymers, such as latex used in surgical gloves, said.
"From the beginning of the Iran conflict we have seen a changed operating environment where many of our key strengths, our improved operating leverage and our 'in region for region' manufacturing strategy are proving to be beneficial," CEO Michael Willome said in a statement.
Synthomer, which has 29 manufacturing sites across Europe, North America, the Middle East and Asia, kept its 2026 outlook unchanged, but said it could potentially upgrade it if second-quarter trading conditions continued.
J.P. Morgan analyst Chetan Udeshi said gains in Synthomer's volumes and pricing power resulted from production cuts at some of its competitors and demand driven by fears of supply shortages and further price hikes.
Synthomer's coatings and construction solutions business that provides chemicals for primers and paints is also increasing its U.S. manufacturing to localize products previously only made in Europe, while boosting capacity in the Middle East and targeting growth in China.
Synthomer, which reported a 21.8% drop in continuing underlying operating profit in 2025, has also been cutting costs and looking to divest non-core assets to reduce debt and deal with the dampening effect of U.S. tariffs on demand.
Synthomer's shares surged to their highest level since October as the company said it refinanced its debt, extending maturities to 2029 from 2027. It also said its finance chief Lily Liu was stepping down to join Belgian metal recycling group Umicore UMI.BR.
($1 = 0.7417 pounds)
Synthomer stock soars as Iran conflict boosts Q2 outlook https://www.reuters.com/graphics/SYNTHOMER-HOT/byprnnewrpe/chart.png
Gutted that I missed the spike in Synthomer (LON:SYNT) as been on my watchlist. But I wasn't brave enough to trust the last management statement that "unlikely to be an equity raise for the debt refinancing".
Very surprised the banks have agreed, albeit it looks like they might have signed away security of the crown jewels against the debt facility, instead of having it unsecured.
The bull case here is clear.
- Recovery in speciality chemicals market, of which Synthomer is one of the top global players. The market has been in the doldrum for a few years.
- They've pivoted away from basic chemicals successfully, stemmed the losses arising from here. There's just too much competition in this space from cheaper producers.
- Iran has changed the global supply chain for specialty chemicals, and manufacturers that are closer to end markets (eg Synthomer) will benefit.
- They've now transitioned to cash flow positive, so the debt level is going down, not up anymore, so the 4-5x leverage is a high point and starts receding.
My struggle here has always been for me to understand how much of a differentiator / moat does Synthomer have in speciality chemicals? Its a fairly competitive global market with several big, well funded players too. Its not like Synthomer has dominance in this space. I've never been able to work out from doing my research here, so hence my still cautious stance investing.
Synthomer (LON:SYNT) My bet is that the disruption to Asian competitors caused by the Iran situation will save shareholders. I fully expect Cockney Rebel has piled in this week.
Any chance anyone can look at United Utilities strategic review yesterday. The shares rose despite an equity raise. The company are talking about the government Data Centres initiative generating significant new demand for water capacity which was not in previous plans
The survey findings
A few days ago I responded to an interesting survey Sam sent to all of us , the community.
I am very intrigued to hear the results. who are we and what do we like to read and hear most.
What do the community think of various aspects of every day activities on this site.
I am sure that the views are diverse but it’s good to know where are the consensus .
What is the most popular part and what the majority wish to be added or cut.
Serabi Gold (LON:SRB) : Stellar annual results posted today with the introduction of a dividend at 5p per share. A blockbuster growth and income story. I hold.
Serabi Gold (LON:SRB)
Slightly above the recently increased broker expectations for EPS and revenue too.
Net cash is also up substantially, and a small dividend is icing on the cake.
Still cheap on the current results and very cheap on a forecast basis. Even for a small gold miner.
I happily own.
A very muted response from the market.
Yes, but has been rising recently, and results were quite predictable, as production and gold prices are easy to establish for Q4 and we had figures already for previous quarters. The wild card was production costs for Q4, which were not known, but do seem to have gone up. Will be interesting to see the explanation and if it is a one off.
also worth noting that other gold stocks are down; as is price of gold down 1.5% to $4568 this morning.
Great preamble thanks Graham. Can you have a look at Newriver Reit (LON:NRR) when you get a moment please. The results require a couple of reads to figure out, due to lack of tables, too many acronyms and too few numbers prefixed by £…..