Daily Stock Market Report (Fri 21 Feb 2025) - CWR, VID, LIT

Good morning and Happy Friday! The Agenda is very short today.
My colleague Alex has published a new research piece on the value of broker price targets and whether or not they are worth following: here's the link. The answer did not surprise me! But it's great to see the verification.
12.30pm: Hanging up my pen there for the week. Have a nice weekend!
Spreadsheet that accompanies this report: updated to 14/2/2025.
I've updated this and found the following statistics.
In the first 15 weeks of the new format, we have given views on:
- 340 unique companies
- 92 companies at least twice
- 19 companies at least three times
- 5 companies four times! (BOO, FTC, SQZ, TIME, VLX)
Cheers!
The Week Ahead has been published by Keelan this time - check it out for a preview of next week!
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Standard Chartered (LON:STAN) (£27.5bn) | FY24 Results | Return on tangible equity 11.7%, up 160 basis points. CET1 ratio 14.2%, above target range. | |
Ceres Power Holdings (LON:CWR) (£156m) | Statement regarding Robert Bosch GmBH (yesterday) | Bosch ending its partnership with CWR and selling its 17% stake. No change to FY25 expectations. | AMBER/RED (Graham) It still has enough cash to fund its losses without external help for at least a few years, but not as long as I thought it did the last time I covered this stock. |
Litigation Capital Management (LON:LIT) (£79m) | Judgement delivered in class action investment | Invested $13.2m in a class action case that has been unsuccessful. Considering the merits of appeal. | AMBER (Graham) I think this is still trading at a discount to book value. Potentially interesting but difficult to analyse. |
Videndum (LON:VID) (£57m) | TU | FY24 was in line. Won’t meet March 2025 bank covenant. Banks “supportive”. Discussions ongoing. | RED (Graham) The existing equity is not secure. Bank covenants were already loose but the company still can't meet them. |
Ceres Power Holdings (LON:CWR)
Down 38.5% yesterday to 81p (£156m) - Statement regarding Robert Bosch GmbH - Graham - AMBER/RED
We probably should have covered this yesterday, but better late than never I hope!
I looked at CWR in January, taking a neutral view as the company had cash and short-term investments of £102m, which I figured might be enough to fund it through to profitability.
I generally take a negative view on unprofitable start-ups, but the main reason for that is the risk of dilution when they run out of funding.
For a fully-funded start-up, I can take a more relaxed view. I still greatly prefer to invest in established, profitable businesses, but I don’t feel the need to be negative on a company that is trying to establish itself, if there is little risk of dilution.
So I took a neutral stance on CWR.
Unfortunately, that was too optimistic as yesterday’s news shattered confidence.
One of the attractions of CWR is its blue-chip partnerships with companies like Bosch and Shell.
The partnership with Bosch is now dead as the German engineering and technology company has decided to focus on hydrogen from now on, instead.
Bosch says:
Bosch is realigning its activities and investments in stationary hydrogen technologies. In future, the technology company will focus more on technologies for hydrogen production…
Against this background, activities related to the industrialization and series development of systems for decentralized energy supply based on solid oxide fuel cell technology (SOFC) will be terminated.
The partnership with CWR will be terminated by Bosch “in an orderly manner while fulfilling its contractual obligations”.
The explanation given is that “the market has developed differently than expected in the recent past”. I'm afraid that chemistry was my worst subject at school, and I’m not going to be able to explain why hydrogen has a better outlook than solid oxide fuel cells.
Shareholding: the news is extra painful for CWR as Bosch is their second-largest shareholder. This stake will now be considered as a “non-core financial investment”, and possibly sold.
The Bosch representative on the CWR board has resigned with immediate effect.
CWR says that the Bosch decision does not change expectations for FY December 2025. As pointed out in the comments yesterday, this may be due to Bosch fulfilling its contractual obligations for the year, but estimates for future years should see an impact.
CWR’s CEO comment:
Whilst Ceres is disappointed that Bosch will discontinue its operations relating to the industrialisation and preparation for production of decentralised power-supply systems using Ceres' solid oxide technology, we recognise that this decision is part of a broader revised strategic direction from Bosch and does not reflect its confidence around Ceres or our technology.
Graham’s view
This may surprise readers but I’m not sure I want to take a very negative view on CWR today!
The reason is simply that £102m cash balance which it held at the end of 2024.
The company’s financial losses have been enormous, however, so I do need to try to understand how vulnerable the cash is to drying up.
I also think the decision by Bosch is damning in the sense that Bosch will have an intimate understanding of the industry dynamics at play. If they don't see a compelling opportunity here, I fear that they might be right.
But let's get back to the finances.
CWR is forecast to make an accounting loss of £28m in 2024, £23m in 2025, and £17m in 2026.
I will use the forecast accounting loss as a proxy for cash flow. But note that CWR burned through cash of £38m in 2024 despite an estimate for the accounting loss of only £28m. So cash flow can be much worse (or better) than cash performance.
The forecast losses for the next two years add up to £40m.
Historic earnings momentum hasn’t been great:
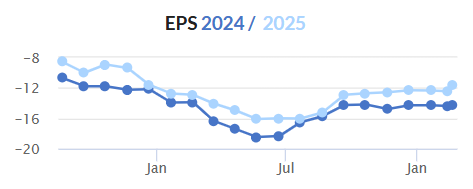
Combine that track record with the loss of the Bosch partnership, and I think it’s reasonable to assume that the losses over the next two years will add up to materially more than £40m. I don’t know how much higher they might be - shall we say £50m? And who knows what the cash performance might be over that timeframe!
Therefore, while I don’t really want to downgrade my stance on CWR, I feel obliged to.
If its accounting losses are worse than existing forecasts and if they do convert to negative cash flow, half of the cash balance would be gone in two years.
It does still have time to improve performance and I'm also sure there is every chance that investors would want back it again, if necessary, to extend its journey to profitability.
However, as I no longer have confidence in CWR being able to fund its losses without external help for an extended period of time, I’m going to move my stance on this lower, to AMBER/RED.
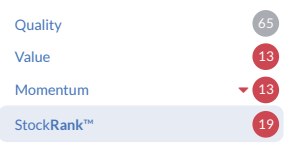
The StockRanks got this one right, while I didn’t. Here is CWR’s StockRank as of two days ago:
Videndum (LON:VID)
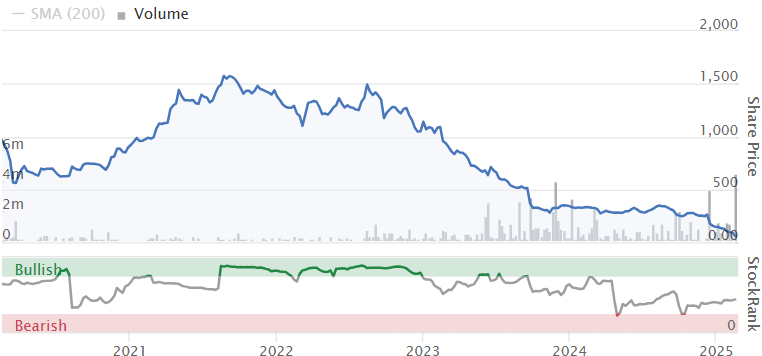
Down 33% to 41.7p (£39m) - Trading Update - Graham - RED
The risk of VID getting into financial difficulty was apparent from previous company announcements, so I hope that the only people left holding it are those who can afford to withstand this sort of share price volatility.
In September, on the day of a profit warning to go with the interim results, I noted that the previous annual report included a going concern warning. The leverage multiple was still very high, and banking covenants had been relaxed to weaker levels.
In December, we had another profit warning. Net debt was rising and the covenants for Dec 2024 were relaxed even further. The company said it was working on an extension or refinancing of the facility (due to expire in August 2026), and was now seeking amendments to the Feb 2025 and March 2025 covenants. The company went into cash conservation mode: cutting costs, merging divisions, and raising prices.
This brings us to today.
The good news is that FY24 results are in line and the amended Dec 2024 covenant was met.
And the February 2025 covenant test has been waived altogether.
The bad news is that the March 2025 covenant test has not yet been waived.
The company acknowledges that it will not be able to pass this covenant.
So without a waiver or further amendment, we could be looking at a technical default on the March test.
Remember that this facility expires completely in August 2026:
The work required to refinance the Revolving Credit Facility, set to expire in August 2026, continues and our lending banks remain supportive of the Company.
Restructuring is ongoing with a new 2025 cost-saving target of £15m (previously: £10m). But there are also restructuring costs of £15m. So we might not see much of a benefit in the short-term.
Exec Chairman comment: I’m fully negative on this share, so let’s counterbalance that by posting the Exec Chairman’s comment in full.
"The gradual improvement in our markets has continued. We are seeing improving signs, particularly in Cine and Broadcast, in terms of quantity and quality of projects and enquiries. These should start turning into stronger order momentum once we get past the traditional doldrums of January and early February. While we are not planning on a strong uptick in orders and revenues as we drive the business forward, we are gaining increasing confidence that the direction of travel is for improved strength in revenues as we move through the year.
"There is still work to do, but I am confident that we are on the right path - building a stronger business, well positioned to capitalise on the market recovery".
Graham’s view
The company says that its brands are “leaders in defensible niche markets”. That may be true, and perhaps current management can turn it around. It has apparently been unlucky - affected by Covid, the Hollywood strikes, and perhaps some poor decisions by previous management. Maybe with all of these events out of the way, it can move on to better times?
However, while the company’s finances are in disarray to such an extent that it cannot meet very loose bank covenants, it’s an automatic RED from me.
If someone really liked this business, it might make sense to buy fresh equity from the company at a deep discount, or to buy the debt off the banks, if either of those options became available.
But as things stand, with £100m+ of net debt excluding leases and unable to pass covenants, the existing equity is not secure.
My main surprise today is that the share price has reacted so negatively to this announcement - is it really surprising that VID won’t meet its March covenant, or that the banks are taking their time in approving a waiver?
Litigation Capital Management (LON:LIT)
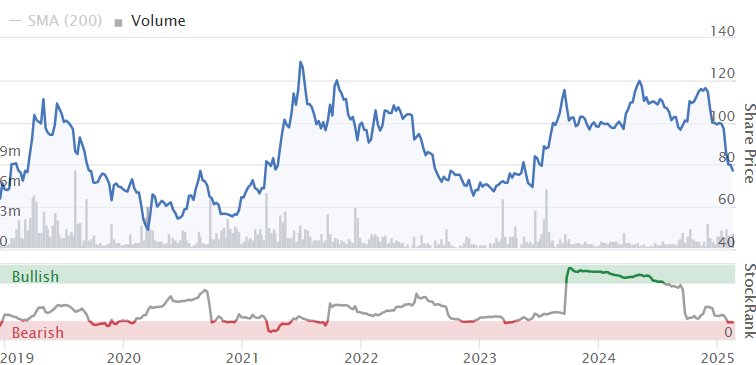
Down 14% to 66.9p (£76m) - Judgment delivered in class action investment - Graham - AMBER
LIT is “an alternative asset manager specialising in dispute financing solutions internationally”. Its headquarters are in Sydney, Australia and it has offices in various other locations including London.
It can be compared with Manolete Partners (LON:MANO) and Burford Capital (LON:BUR).
Today’s news is that a case in which LIT invested $13m (Aussie Dollars) of its own capital has been lost. That’s just under £7m.
They do have a right to appeal, and are considering the merits of it.
I don’t think the specifics of the case are very important to us. It was a class action lawsuit on behalf of the shareholders of an Australian company.
CEO comment:
… It is an unusual outcome that the court found that the financial statements in question were misleading, but that this did not result in loss for the shareholders in Quintis. Our focus now is on assessing the Judgment and determining the best course of action alongside our legal team. We remain committed to our disciplined approach in managing risk and capital across our portfolio."
I tend to stay away from this sector. Companies like this can sometimes have very large exposures to particular lawsuits. When they work out, it’s terrific, but I don’t know if I’d be able to sleep at night!.
This attitude kept me out of Burford, which has multi-bagged for its long-term shareholders.
I think it’s reasonable to value them relative to book value. LIT had net assets of $188.9m (£95m) as of its most recent year-end (June 2024).
Since then, it published a trading update in January 2025 which said that its aggregate wins and losses in H1 had realised $52m from cases in which it had invested only $14m.
However, the uplift in terms of balance sheet gains would only be $4m, as these cases were already valued on the balance sheet at $48m.
I was wondering if the valuation of the Quintis lawsuit on LIT’s balance sheet might have been substantially higher than the $13m invested in it, in anticipation of a win.
However, according to broker Cavendish, responding to today’s news: “At most, this will lead to a $13.2m write-down from the investments made from its balance sheet”. That sounds reassuring.
Cavendish also says that LIT’s concentration risk with respect to individual cases is “now reducing as its co-investment model matures”.
Graham’s view
With some back-of-the-envelope calculations using the full-year results (to June), the H1 trading update (to December) and today’s update, I think that LIT’s balance sheet might now be worth c. $165m (£82m). I’m not sure of course, but something in that ballpark seems about right, after taking into account the loss announced today.
Net debt was $40m as of Dec 2024.
I’m on the fence between AMBER and AMBER/GREEN. I think that a discount to book value is still on offer, even after today’s news. LIT’s peers seem to be trading at a premium to book. And LIT’s overall track record seems pretty good.
But at the same time, it’s not easy for me to trust the valuations of legal cases.
To be careful, I think I’ll stay AMBER for now. I would be willing to upgrade my stance if a larger gap appears between the share price and book value.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

50 comments
On the subject of Mining Stocks I have kept a careful record of my wins and my losses because Mining is a very risky business and some great Investors like Robbie Burns the Naked Trader never touch them.
I currently hold Fresnillo (LON:FRES) Newmont (NYQ:NEM) Sylvania Platinum (LON:SLP) and Ferrexpo (LON:FXPO)
All 4 are currently showing losses. Historically Ferrexpo (LON:FXPO) has been my biggest winner of any share I have ever bought. Fresnillo (LON:FRES) can rise and fall very rapidly.
Newmont (NYQ:NEM) is a bargain at the current price of $48.12 in some experts opinions especially with the USA spending trillions of Dollars more than it earns from taxes.
Eventually large budget deficits normally result in a financial crisis at some point that is when Gold will fly and why some Governments including China are buying up gold.
this is possibly why Newmont didn't budge up on Friday: https://x.com/Spread_Bet/statu... If it was a tech stonk it would be up 20% on that earnings beat.
Renold (LON:RNO) - does anyone have any insights as to why this has tanked c20% in the last 10 days? Tariffs related?
Renold (LON:RNO) I've been wondering the same. Renold does have some moat in the terms of the quality of the chains they produce. Their client list typically are willing to pay a higher price as the cost of outages due to poor quality chains make them a false economy. Maybe it's more a case of some people getting bored and selling out to the next spoken about stock? I Hold and intend to keep holding until there is some news to go on.
Renold (LON:RNO) stock price hasn’t really recovered from the highs of June 2024. I held at that time and seem to recall an issue with the behaviour of management with regards to use of finances. Awarding high bonuses to themselves.
Yes there is a big issue with share options that Paul Scott uncovered: https://www.stockopedia.com/co...
Also there is a large pension deficit.
The author of 'Richer Wiser Happier' has just recorded a 2 hour interview with Terry Smith which is on Youtube (search 'Winners Keep Winning Terry Smith').
An entertaining and informative listen about Terry's path through life and his investing philosophy....
yes, watched this last week!
william green's podcasts and interviews are a great watch
I'm afraid that chemistry was my worst subject at school,
Alas, I wasn't allowed to do chemistry in school. I had to do woodwork instead. I managed to make a small bookrack at the end of it, the sole output. Someone drilled a hole in it at one stage. At the end of the year the teacher wanted to charge me 50p to take it home, but I declined. Every penny a prisoner; a saying I learned from a Scotsman.
I do remember having a chemistry set where you put two different metals in a U-tube, pass electricity through it, getting hydrogen at one end and oxygen at another.
So when I heard of CWR I thought to myself "Hmm, that sounds energy-intensive, and hence expensive." Checking on the well-tempered folk on ADVFN I found that there were actually two ways of producing hydrogen; with folks slinging insults at each other for being clueless n00bs at not knowing the distinction.
Anyway, I didn't think any of that matter because it isn't making any money.As they say on Dragon's Den, "And for that reason, I'm out."
Talking of Dragon’s Den, did anyone see the two brothers last night who have developed a spices/sauces business from nothing, absolutely inspirational and impressive young men, one in particular! Perhaps the U.K. isn’t the basket case we hear when you see stories like this! Well worth a watch. They were the final presentation if you can’t watch the whole programme.
Hi Graham, if there's time today I wonder if you'd be able to give your views on the Indivior results yesterday please? Thanks, Pete
Altyngold (LON:ALTN) Pan African Resources (LON:PAF) Serabi Gold (LON:SRB) Fresnillo (LON:FRES) Metals Exploration (LON:MTL) (I hold).
Miners carry risk. The mines themselves have an uncertain future, they tend to be located in countries with an uncertain political future and they are dependent on the future price of the commodity they are mining. Against this they reduce overall risk because these types of risk are very different to the risks other shares have that an investor will have in his or her portfolio.
But a mini porfolio of the shares above diversifies the individual mine risk and the political risk, leaving just the risk that gold or silver will go down in price. Balanced against this these shares have on average a forward PER of only 9 and the outlook since Trump was elected looks very gloomy which means that central banks and others are loading up on precious metals.
From both a risk and return perspective this mini portfolio has a lot to offer. Do you concur?
I agree and find better to hold these than pay Van Ect Gold Miners EFT .5% + charges
Epitychia, "From both a risk and return perspective this mini portfolio has a lot to offer. Do you concur?" Yes. I opted for Serabi Gold (LON:SRB) Metals Exploration (LON:MTL) Central Asia Metals (LON:CAML) Would be interested in which other miners people here are keen on.
Only hold Serabi Gold (LON:SRB) out of those 3.
Not keen on Metals Exploration (LON:MTL) is based in the Philippines.
I also hold Pan African Resources (LON:PAF).
Golden Prospect Precious Metals (LON:GPM) - an investment trust focusing on junior gold miners. Personally find it too risky and complex to hold individual miners so happy to use GPM to get a basket exposure. They seem to know what they're doing an have a good track record - it's also on a c20% discount which I suspect could close if the rally in goldminers continues.
only there is no reason to hold this fund when it charges a chunky yearly fee!
1.25% management fee - I don't think outrageous for a specialist fund that's also fairly small. This sort of thing could easily rally 50-100% in the blink of an eye if the sector takes off, so 1.25% is neither here nor there.
Will look at GPM but at £41m don’t have much firepower .
Royal Gold (NSQ:RGLD) 8bn, Wheaton Precious Metals (LON:WPM) 25bn streamers so risk diversified. There are smaller.
Hold Silvercorp Metals (ASQ:SVM) Canadian, but operates mines in China. China has a lot of cos on the US exchanges, as opposed to an ETF.
Avoid most outside North America. Barrick having issues in Mali. Africa does itself no favours.
I am a holder of Central Asia Metals (LON:CAML, Anglo Asian Mining (LON:AAZ) and Kenmare Resources (LON:KMR) - profitable and dividend paying. My silly moon shoot is Andrada Mining (LON:ATM). I'd be interested if there are subscribers here with views on Andrada Mining (LON:ATM) - tin price doing well but Lithium at recent lows, funding tight but manageable, partnership with the worlds leading Lithium miner...
There are broker notes at Research Tree for Andrada Mining (LON:ATM, with TP's of 27p to 34p but it's difficult to give much credence to them. The substack blogger "The Oak Bloke" (well worth a follow IMO if you like potentual deep value and soec situations) has written reasonably forensically on it on a couple of occasions.
FWIW I'm have a punt on Thor Explorations (LON:THX)
I like it but the main producing mine is in Nigeria and the governor where the mine is situated is as corrupt as can be - has been blaming Thor for doing environmental harm and hiring unauthorized workers and not paying its due taxes. Basically pressing them for handouts. I'm not racist but would you trust this guy to treat you fairly - https://x.com/Osun_State_Gov - first impressions are that he looks like a nasty character who is shady as hell. When he started accusing Thor on twitter and I defended the company the people who replied were even more sleezy - some who replied had porn posts on their twitter! That's the kind of political climate Thor is facing and its holding it back.
Bensummers
Thanks for the insight – hadn’t realised the local politics were quite so iffy. I’ll keep a very close eye on it though might be best for me to stick with gold bullion and Ishares Physical Metals (LON:SSLN.
Agreed i prefer to stick Ishares Physical Metals (LON:SSLN) as you normally find gold miners tank with the market if we get a big shock where bullion doesn't ,the trade off is you get decent divi's from the big miners but nowt from bullion.
I also hold a number of miners for the same diversification reasons, and their reduced correlation with most other shares and also bonds. In my case, I hold Pan African Resources (LON:PAF) , Fresnillo (LON:FRES) and Hochschild Mining (LON:HOC) . In addition, I hold Capital (LON:CAPD) Anglo American (LON:AAL) and First Majestic Silver (NYQ:AG) for similar reasons and the relatively limited other options on LSE. On balance I also tend to prefer miners that pay at least a dividend.
There is also Cerrado Gold that has a mine in Argentina and is very much undervalued. Not only that but they also have a very promising iron ore development project in Canada and are just about to acquire Ascendant Resources - check here to see it discussed: https://ceo.ca/cert
And another one left out is Anglo Asian Mining - listed in London - AAZ - which is not just a gold play but also a copper play. Is just recovering from from a crisis from last year but the story is promising and the way management handled the crisis and mitigated the stoppage reflects very well.
The only mining company I own is Adriatic Metals Adriatic Metals (LON:ADT1 - silver miner. My bugbear with Stockopdeia is that they do not provide forecasts.
the problem with this is its unproven, still ramping up and keeps diluting shareholders.
Adriatic Metals (LON:ADT1) Yes, impossible to value this one unless you are a mining expert which i am not.
Its proven.
Its followed by numerous analysts.
I hold Fresnillo (LON:FRES) and would direct you to macro voices last week with Jim Bianco and also, Grant Williams with Adam Rozencwaig.... we aren't there yet but the weak dollar / strong commodities case is building strength IMO.
Fresnillo is as solid as can be and trading at big discounts to its USA major equivalents. If you believe in silver and like Mexico as a mining jurisdiction its the place to be. When Silver trades at $50 the leverage here will be magnificent.
yeah my view isn't v intelligent tbh... I like Gold and Silver is Gold on steroids. It's a speculative asset mainly influenced by US investors. I still believe gold:silver ratios hold which offers 20% or so catch up at some point.... but even if silver just hangs out up here for a while Fresnillo (LON:FRES) will do well. Im not much of a fan of Mex but it's probably ok for now.
These ideas being floated around revaluing US Gold and also devalue dollar make me very interested.
Without hopefully sounding thick RD if the US revalue their gold holdings will that push the overall gold price up a lot, a little or minimal effect ? in your opinion.
The USDebtClock.org website gives some useful ratios and valuations e.g.
My favourite is Minerals and Financials Investments (MAFL). Looks to be well undervalued against the various different investments it holds.
I agree. I like Metals Exploration (LON:MTL) best from your selection because of quality management, cash generation, low debt, and production growth over the next 3 years.
saving with no interest
I just heard on a AJBell p0dcast that some 230 bn cash is sitting in bank accounts with zero interest rate. No wonder the banks are making good profits.
STAN Since it is on the agenda, I thought I'd add my 2c. Shares are up 4.7% in early trading, so the market is liking the results.
It's worth pointing out that it's trading on a PBV of 0.7, with a book value that's likely to increase.
Bragging time. I bought these back in Jun 2022 at 633p. It shows you how much money you can make in large caps if you can get it right. In hindsight, buying the shares was "obvious". Banks were really hated and trading at huge discounts to PBV.
Instant profits weren't available though, and one had to ride out the poor sentiment caused by the collapse of Silicon Bank. That was quite nerve-wracking.
I've noticed that big banks in America seem to be in a much better position than the regionals. The big ones are subject to stringent regulations, whilst the smaller ones have less controls imposed on them. So the the big banks can be sluggish, but the smaller ones are more prone to doing something dumb. When this happens it's the big banks that mop up the small banks.
I hold, and still think there's plenty of juice left in the tank.
Well said, Mark! And well done with Stan. I don't want to start another big-cap-mid-cap-small-cap debate, but I think a lot of people underestimate the amount of volatility, and the opportunities available, in larger companies. Just because there are more City analysts and fund managers looking at a company does not mean that it is priced correctly!
Many thanks. I think a certain amount of patience is required as the shares don't usually come good straight away (although they can). There's also the possibility that the shares could stay cheap for a decade. Nobody wants that! So I think diversification is necessary. No idea is so good that it can't go horribly wrong. Banks, by their nature, can go horribly horribly wrong.
The best opportunities are likely to be in cyclical companies. Oilers a few years ago, for example. It's a question of "what [sector[ does everybody hate?" It's not something where I can come up with ideas on a regular basis. You have to let the disaster come to you rather than the other way around.
I'm much more into quality these days, but I've set aside a small amount for recovery plays to see if I can figure it out. And I might have a go at some value plays where I think the odds are very good.
No way am I as good as someone like Paul Scott or your good self who has a good feel for value.Hi Graham, Mark
I did note this about large cap volatility the other day and rather upset the poster I was replying to who was arguing - fairly I think - that small caps can be fundamentally misvalued (and therefore can be analysed) while large caps tend to exhibit volatility due to special situations (and therefore can't).
A quick glance at the FTSE 100 and we can see JD Sports Fashion (LON:JD.) is down 45% in 12 months, Taylor Wimpey (LON:TW.) is down 30% (most of the large cap housebuilders are down over 20%) while there are 5 stocks (International Consolidated Airlines SA (LON:IAG), Rolls-Royce Holdings (LON:RR.) and 3 major banks - Barclays (LON:BARC), Standard Chartered (LON:STAN) and Natwest (LON:NWG)) up over 50%.
Not sure how much of that was predictable, but clearly the banks were very cheap at one point and worth an educated investment. Possibly the same is true right now for housebuilders?
Personally I can't bring myself to invest in banks. I don't mind investing in things I don't understand but I don't want to invest in things their managements don't understand.
timarr
Maybe banks will be cheap again, if they get hit by a windfall tax. Maybe Reeves try to save them from paying out compensation to car buyers, so she can tax them?
I also don’t invest in banks. Stopped doing that when seeing how clueless about their businesses the Bank bosses were in enquiries after the big 2008 banking crisis. That didn’t stop some of them getting further Chief Executive jobs! If they can’t understand their business can any of us?
As for broker buy and sell advice;I’ve ignored it for many years. Armed with the same information on a share their views can range from ultra bullish to sell and with wildly different target prices too.
Sometimes their new target prices are ludicrous….like Deutsche Bank or whoever, downgrades their target price from 295p to 290p. Then there are the useless “underweight or overweight”advice. What does it mean? Ditto “add” or “reduce.” Not easy to do if not already holding. But the main reason for ignoring them is because they are so often wrong. Years ago there was an Investors Chronicle survey of all the broker buy and sell advice over 1 year. Their SELLS went on to go up more than their buys! And the buy with the most buy advice British American Tobacco (LON:BATS) ended up being the worst performing share that year.
As for the case for buying large Companies. They can and often do just as well as small Companies, especially so if using my favourite tactic of buying high quality big shares at bombed out prices near the depths of bear markets when most advice is to stay away.
I could give many examples of those I’ve bought and missed out on but here are just 5 examples.
Anglo American (LON:AAL) crashed to just 220p at the depths of the great Mining bear market at the end of 2015. Within a few months it had gone up over tenfold to £24! It was big enough to stay in the FTE100 even when at 220p. I bought at that low but goodness knows why, sold shortly after for a 10% gain. What a miss.
Marks and Spencer (LON:MKS) has given us two bites of the oversold cherry in recent years by twice more than doubling in no time. The first saw a gain from under £1 to £2.40 before an update (when I sold on my sell on bad news rule) suggested the gains had been too fast. I didn’t dream there woukd ever be another opportunity below £1 but there was in October 2022. Marks and Spencer (LON:MKS) recently quadrupled from that low and I’m running for free having taken the stake out and some of the profit.
Next (LON:NXT) is the bell whether retailer with such clear updates that are a model so many other Companies should follow. They also under promise and over deliver time and again, so buying the occasional big dips is almost a no brainer. E.g at just £46 in October 2022 and now more than double at £102.
Centrica (LON:CNA) is another. Again doubled since the October 2022 fall.
Aviva (LON:AV.) fell to just £2.20 in the covid crash and that buy opportunity lasted well in to the stage where Governments and Central Banks were throwing everything at it. Again share has more than doubled and the annual yield near that low is around 15%.
For shares and Countries I don’t understand then Investment Trusts are the answer. E.g India Capital Growth Fund (LON:IGC) soared from under 40p to almost £2 and is now back to £1.60.
For Natural Resources CQS Natural Resources Growth and Income (LON:CYN) soared from 54p to 192p now.
Like so many, I like investing in smaller companies too ,and can’t resist the odd risky fun punt, but isn’t it wrong to dismiss quality big Company shares, or any potentially exciting investment opportunity? Better to widen the horizons than narrow them, not least because one section of the markets might do far better or far worse than another.
e.g the AIM market has been a distaste area for those investing almost entirely in AIM shares. It’s down 26% over 5 years and even more since it started in the last century.
The Aim market has served me well over the last few years with Keywords studios being my most successful. You just need to be selective....and lucky...but that applies to the main market too.
I wasn’t saying don’t buy AIM shares and I’ve done well with a few too, including a quick triple on BUMP when Paul Scott posted that it could multi bag or go bust. Pure fluke but just a couple of weeks later it fell to a bid at triple my buy price.
My point was questioning the wisdom of investing too narrowly, like almost entirely in AIM shares. Also if an index does as badly as the AIM index has for so long it’s going to be much harder to invest successfully than if opting to invest in indexes, Countries and sectors (e.g US tech) that are doing very well overall. That’s pure common sense surely……or am I missing something?