Daily Stock Market Report (Fri 21st August 2026) - HTG, BTG, SPR, MTL, SPI, PPH

Anthropic IPO: Bloomberg confirms that Anthropic “expects to match or beat” SpaceX’s IPO size.
When Space Exploration Technologies (NSQ:SPCX) hit the market in June, I thought that its overwhelming size might become a headwind for US equity markets. But the major indexes show no sign of slowing down yet. The S&P 500 (which doesn’t include SpaceX) has reached new highs:
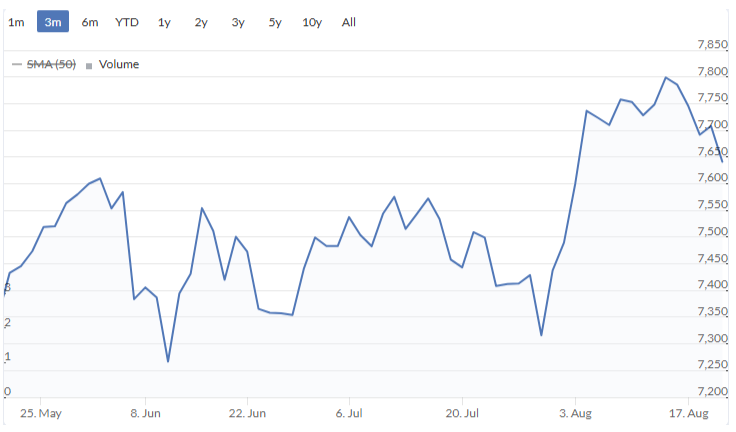
With the market having digested SpaceX so easily, the AI giants are now on the way.
SpaceX raised $86 billion in total; if reports are to be believed, Anthropic is likely to raise even more than this.
As for the valuation it might achieve, the IPO markets on IG* currently suggest that Anthropic’s Day 1 Market Cap will be c. $1.97 trillion, using the midpoint of the spread. That’s just shy of the $2.1 trillion achieved by SpaceX on its first day of trading. Exciting times!
(*I'm long IGG.)
Overnight market movements:
The FTSE is unchanged at 10,765
S&P 500 is unchanged at 7,650
Brent crude (November) is down 0.6% at $91.50/bbl
Gold is up 0.7% at $4,550/oz
Bitcoin is up 3.7% at $75,300
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Spire Healthcare (LON:SPI) (£951m | SR72) | “Toscafund has confirmed to the Board that its due diligence has concluded and that it continues to work towards the announcement of a 250 pence per Spire Healthcare share recommended offer.” | TAKEOVER (Graham) [no section below] | |
Hunting (LON:HTG) (£720m | SR87) | “The Directors anticipate continued year-on-year growth into 2027 given Hunting's diversified portfolio. Dependent on the timing and outcome of the KOC (Kuwait Oil Company) tender, it will have a maximum adverse impact of c.$10m on current 2027 EBITDA consensus.” | PROFIT WARNING (AMBER/RED ↓) (Graham) Hunting is a highly reputable, well-diversified organisation with a long and proud history. In many ways, this is a blue-chip stock. However, there’s no getting away from the downgrade today - and we already considered it to be fully valued. I’m therefore taking a moderately negative stance on this one today. | |
PPHE Hotel (LON:PPH) (£659m | SR22) | Sale of the freehold site to a US real estate developer for the purchase price of $33.5m. The sale proceeds were used to repay the associated debt of $6.75m. | GREEN = (Graham) [no section below] With takeover talks having collapsed here, these shares continue to trade and we can continue to speculate on what they might be worth. I'm fascinated by the fact that Eli Papouchado, the largest shareholder (through Euro Plaza Holdings), turned his nose up at a £22 per share offer. I've long suspected that PPHE might be worth something closer to net asset value, which according to real estate accounting rules is c. £27 per share, rather than the much lower levels at which it typically trades. With a current share price of only about £16, I am going to stick to my guns and stay GREEN on this one. Acquirers were apparently willing to pay £22; I think it's worth our while staying positive here. | |
| Metals Exploration (LON:MTL) (£454m | SR66) | La India Development Update | SP +4% First gold production at La India (Nicaragua) remains on track for December 2026. US$27 million equipment loan completed with a local Nicaraguan bank - an initial US$20.2 million drawn down. | AMBER ↑ (Graham) [no section below] Mark was moderately negative on this in April at a share price of 13.7p, after a 20% cut to production guidance. I'll put us back on neutral today on the grounds that Mark himself thought that the shares were not necessarily expensive at that price, and today's update is encouraging. La India (Nicaragua) has some pretty impressive resource estimates: 66,000 ounces at a high grade (9.9 grams/tonne), and vastly more estimated to exist at lower grades, including 194,000 ounces at medium-grade (6.2 grams/tonne). Total indicated and inferred gold is some 2.3 million ounces, although only a fraction of this might be mined economically. With La India on track, there is also positive news from the Philippines with gold production at MTL's Runruno mine now forecast at the upper end of the 2026 production guidance. MTL is trading at 5x earnings according to the StockReport and while I tend not to pay the P/E multiple much attention when it comes to mining companies, it seems reasonable to at least be neutral on this one. |
BTG Consulting (LON:BTG) (£176m | SR77) | In Q2 2026, the number of UK businesses in 'critical' financial distress increased by 9.0% year-on-year to 53,756. Leisure & Cultural Activities +27.1%, Hotels & Accommodation +26.5%, Sports & Health Clubs +21%, Food & Drug Retailers +18.4%. | AMBER/GREEN = (Graham) We’ve been moderately positive on BTG and I see no reason to change stance on it today. The valuation is reasonably full for a professional services business but deservedly so, in my opinion. Today's Red Flag Alert provides the company with some nice PR while also giving us some interesting insights into general business health. | |
Knights group (LON:KGH) (£150m | SR78) | FY25: Moore Barlow delivered revenue of £42m and profits distributable to members (ie pre-partner drawings) of £12m. Draft accounts for FY26 show revenue of £45m and profits distributable to members of £13m. Total cash consideration of £27m, of which £18m is paid upfront. | ||
Springfield Properties (LON:SPR) (£127m | SR91) | SP +4% Seeking the approval of shareholders for the repurchase of up to 5,957,372 shares, with flexibility to extend up to the full Buyback Authority limit of 11,904,240 shares. The Concert Party will not be obliged to make a mandatory offer for the entire company. | GREEN = (Graham) [no section below] Like so many housebuilders, Springfield are trading at quite a chunky discount to book value, despite trading profitably. The problem with all "deep value" investments is time - how long to wait until a catalyst appears? A buyback is one of my favourite such catalysts and Springfirled are now looking for permission to buy up to 12 million shares - 10% of the existing share count. That's a meaningful amount and a vote is needed because of the Adam family's shareholding (Chairman Sandy Adam is the grandson of Springfield's founder). A buyback could increase the family's percentage ownership of the company, and this would ordinarily trigger a mandatory takeover offer from the Adam family. SPR's shareholders are being asked to approve a waiver so that a takeover offer will not legally required. I'd be very much inclined to approve this! The company reported a net cash position of £1m for May 2026, and it made a land sale recently for £12m. About half of that land sale cash was used to settle an acquisition from several years ago, but the rest is presumably available for this planned buyback. With annual forecast after-tax profits running at c. £10m, this buyback looks to me like it's probably an excellent use of surplus cash. | |
Real Estate Investors (LON:RLE) (£54m | SR45) | Sale of £10.7m at 92% of Dec 2025 book value. “The completion of scheduled sales in Q4 2026, combined with the conclusion of sales in our legal pipeline will repay the Company's entire debt in full, allowing us to commence capital returns to our shareholders.” | ||
Corero Network Security (LON:CNS) (£37m | SR18) | CNS announces AI-Augmented Cloud-Assist for SmartWall ONE™, extending its automated DDoS protection with cloud-delivered AI analysis, threat intelligence, and policy optimisation. | Reach announcement (non-regulatory press release). | |
Amigo Resources (LON:AMGO) (£35m | SR86) | MoU with the State Mining Corporation of Tanzania establishes a strategic collaboration framework to evaluate a significant graphite tailings recovery and beneficiation project in Tanzania. | ||
Tekcapital (LON:TEK) (£9m | SR43) | Innovative Eyewear has developed significant new features for its smart eyewear products, delivered via the Lucyd app for iOS and Android. In particular, the Newscast widget allows users to create custom, generative AI news reports to be read out on Lucyd eyewear. |
Graham's Section
Hunting (LON:HTG)
Down 13% at 412p (£624m) - Graham - PROFIT WARNING (AMBER/RED ↓)
Hunting are specialists in “the global manufacture, trade and rental of high quality equipment for the energy industry.”
Their advanced manufacturing capabilities are also used in the Aerospace/Defence, Telecoms, Medical and Transportation industries.
We’ve been neutral on it (see Mark’s coverage here), arguing that it’s priced about right and also noting some soggy EPS forecasts:
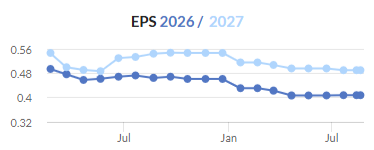
Today’s interim results bring a fresh downgrade to forecasts. Let’s fast-forward to the key sentence outlining the problem.
Kuwait Oil Company “has provided a verbal indication to all vendors that it will now re-run the OCTG tender process, which was originally issued in April 2026.”
OCTG stands for “oil country tubular goods”. Hunting won orders worth over $200m from Kuwait in recent years. However, the most recent orders have been disrupted by the conflict in the Middle East, and now they have to run the tender again:
As previously guided, Hunting's earnings profile for 2026 will be weighted towards the second half. The KOC tender process delay will have an impact of c.$10m on 2026 EBITDA, resulting in a revised 2026 EBITDA guidance range of $138-141m, slightly below previous guidance. Projected year-end total cash and bank position is broadly unchanged at c.$50-$60m as working capital investments in H1 unwind.
So 2026 is going to be “slightly below guidance”.
2027 is where the bigger impact lies:
The Directors anticipate continued year-on-year growth into 2027 given Hunting's diversified portfolio. Dependent on the timing and outcome of the KOC tender, it will have a maximum adverse impact of
c.$10m on current 2027 EBITDA consensus.
Prior consensus was for 2027 EBITDA of $165m.
So let’s call that a 6% downgrade to next year’s profit forecast.
H1 results
The results for the H1 period to June 2026 are not too exciting: revenues down 6%, and adjusted PBT down 21%. The sales order book is also significantly lower year-on-year:
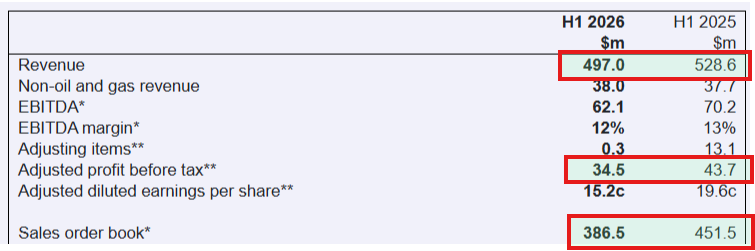
On the bright side, let’s give the company credit for posting results with almost no adjusting items.
The soon-to-retire Chief Executive seems happy with strategic progress:
Today's results demonstrate the benefits of the transformation of Hunting's portfolio and our ability to capitalise on the structural growth opportunities in the end-markets we serve. In particular, the strong margins delivered from our Subsea product group, following our strategic repositioning in this area over the past seven years, are strengthening the quality of our earnings into the long-term, a key deliverable of our 2030 strategic ambition. We have also seen encouraging momentum in our Perforating Systems product group, as our technology offering continues to be embraced by the industry, with record international sales supporting the Group's overall results.
The company balance sheet is very large with $863m of net assets, of which only about $100m is tangible.
In that context, and considering the large EBITDA numbers, the latest net debt figure of $51.4m, including leases, doesn’t worry me very much.
Graham’s view
Hunting is a highly reputable, well-diversified organisation with a long and proud history. In many ways, this is a blue-chip stock.
However, there’s no getting away from the downgrade today - and we already considered it to be fully valued.
I’m therefore taking a moderately negative stance on this one today.
If peace and harmony break out in the Middle East, then I agree with it that activity in the region will “rapidly recover”. So that’s something to look forward to - although when it might happen is anyone’s guess.
Until then, we have a large industrial stock that needs a new CEO and is earning pretty average returns.
BTG Consulting (LON:BTG)
Up 1% at 110.4p (£176m) - Latest Red Flag Alert for Q2 2026 - Graham - AMBER/GREEN
We have the latest quarterly Red Flag Alert from BTG Consulting, i.e. Begbies Traynor. It provides a nice bit of PR for an insolvency practitioner while also giving us some insights into the financial health of businesses across the country.
This is quite an interesting report. Some headlines:
The number of businesses in “critical” financial distress is up by 9% year-on-year to 53,800.
Consumer facing industries under the most pressure, e.g. Leisure & Cultural Activities and Hotels & Accommodation in distress up 27% year-on-year.
Number of businesses in “significant” financial distress up 1.1% to 674,000.
So the growth in “significant” distress is very mild, but there’s an escalation when it comes to “critical” distress.
As for winding-up petitions, they increased by 15.7% in 2025 vs. 2024.
Comment by Ric Traynor:
"Against a backdrop of ongoing geopolitical challenges, there appears to be no relief in sight for distressed UK businesses. Whilst the extent of the impact is still unknown, the escalation in winding-up petitions is an ominous sign…
"Rising energy prices are likely to push inflation higher again this autumn, squeezing consumers just as borrowing costs remain elevated…
"Sadly, when confidence and spending remain subdued, I expect the resulting shockwaves to be felt across many other industries later this year and into 2027."
We should bear in mind that insolvency practitioners have an incentive to talk down the economy! Bad news for them is good news for everyone else.
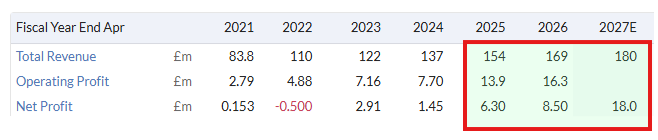
But I do tend to trust this Red Flag Report; it has been published for many years and it rings true. The rise in insolvencies in recent years has coincided with very strong trading at BTG (mostly organic growth, I think):
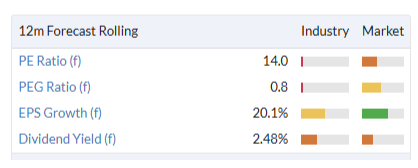
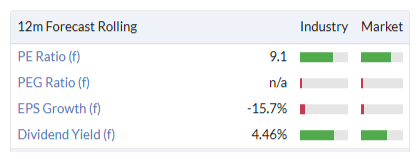
We’ve been moderately positive on BTG and I see no reason to change stance on it today. The valuation is reasonably full for a professional services business but deservedly so, in my opinion:
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

40 comments
On BTG Consulting (LON:BTG) .... they also have a substantial property advisory and auction arm. So now they are more diversified than before, when they were only an insolvency and advisory practice.
Their property arm deals in commercial properties. Should do well with rising rates, stagnant prices, and tight funding liquidity in the commercial property industry. It's not in a distressed state, but it's clearly struggling, which will be a boon for BTG's property arm.
As they always say with cyclical shares. When times are good, the PE should be low. When times are bad, the PE should be high. We're still in "bad" times when it comes to insolvencies and property distress. So the PE of this should really be c15 times to c20 times. Yet it is much lower at like 9x PE. Can one really say the opposite - that the economy is so bad (so a "good" time for BTG) at the moment that we're seeing masses of insolvencies and commercial property in distress?
Hence why I hold. Investors have forgotten that now is a "bad" time in the cycle for BTG, it really should trade at like 15x instead of 9x. And it's the perfect anti-cyclical protection in a portfolio. Better than cash.
(I hold in the Boon Fund)
That shows the closed stocks but it doesn't retain information on any dividends paid historically
You don't need to keep one share active to retain this information - it will be stored with the closed holding. I would suggest adding "Total Gain" field to your portfolio table, this with show the sum of unrealised, realised and dividend gains for all positions - including your closed ones.
Thanks Oliver!
Thanks Graham Tony
Springfield Properties (LON:SPR) - I'm a shareholder. I've always thought that Springfield Properties are operating in probably the least risky area of the UK for Housebuilders, in terms of unknown site conditions etc. They are primarily focused on low to mid range housing in the Mid to North East corner of the Scotland, (i.e. above the Central Belt running from Glasgow to Edinburgh.) Predominantly green field sites, few brownfield sites with resultant contamination issues and little in the way of existing services to deal with etc. Another consideration is that facing bricks are rarely used in this area of Scotland, (no suitable clays for production & the widespread use of rendered finishes). In my experience of 50+ years in Construction (London & the South East), the supply of facing bricks can be a major factor to programming and cost - inconsistent supply, shortages of specified bricks, significant cost increases when supplies run short & high energy costs for production. Springfield should therefore manage to forecast margins on their developments more accurately than perhaps other house builders in the South. (i.e. Vistry!!)
thanks Tony, I'll endeavour to make a short comment on this as it's outside my wheelhouse. all the best.
Thanks for the much appreciated daily report Graham. After some tidying of shareholdings this morning perhaps anybody might be kind enough to advise how equity names may be deleted from a folio once all shares in the company are sold. I have experienced no difficulty in adding, but remain with several showing nil shares, since I have been unable to discover the process for myself.
Saltash - tick the box next to the appropriate company you want to delete from your Folio, this will highlight the Trash Bin (in red) (next to the word "Compare" above your list of companies and then just click on the red Trash Bin and you're done...
"just click on the red Trash Bin and you're done"
This works and also deletes the history associated with that holding, such as any dividends and the profit/loss on sale. If it's a real portfolio, that's probably information that you'd want to keep...
if you want to keep the history always retain 1 share of each sold holding - bit of a bodge but does maintain a record
Funnily enough I have done this so I can kick myself for bailing out too early on Prysmian and Siemens Energy to name a couple.
Does that not muck up the folio performance though?
Better to have closed positions, then you can always see the history, if you want.
There's an option underneath the list of company names, Bob, to show closed positions. If you uncheck that box it should have the desired effect.
Yes, Many thanks indeed.
do you have "Show closed position(s)" ticked at the bottom of the portfolio listings?
If so uncheck it and it'll hide nil positions but retain your historic transactions.
Doh! Just seen Whitbourne's response
Gamma Communications (LON:GAMA) possible bid: https://www.stockopedia.com/a/...
Gamma Communications (LON:GAMA) now have two private equity companies under a PUSU notice, so some healthy competition!
Morning Graham , noticed MTL ,one of Ed's annual selections ,a couple of years ago ,was'nt on list. It's an update on the new La India mine ,and comment on Runruno 's current production. I know you downed your coloured warning system ,after a couple of setbacks, at Runruno .However this mornings RNS seems to put that behind them [except for some international deliveries, which they say won't affect gold pour] Basicly Runruno mine ,is the cashcow to bring La India mine into production. Runruno is looking likely to finish on a high ,as higher grades are going thro' ,just as gold seems to be doing rather well [wonder if that is down to recent US debt figs. ?] . The 'replacement' mine La India seems to be going ahead at pace ,with production still forecast for late H2 . This will be a much larger, annual production ,than Runruno ,so fingers crossed for no setbacks. The photos seem to confirm progress too. Tony
Metals Exploration (LON:MTL) Good to have confirmation that they think La India remains on track, but I am not sure anything else changes much. Presumably the lift in the share price is a response to the higher gold price. Higher grades at Runruno are nice to have, but surely don't change anything at this stage. Management information to date has been that there is no prospect of significant further production from Runruno beyond the end of the year.
Metals Exploration (LON:MTL) Grid connection to ENATREL is completed and available for operations. That was always a concern - now removed. I'm surprised there hasn't been more discussion about this stock.
ST , My thinking ,about share price is it's more to do with La India ,on schedule . A new mine often has unexpected delays ,and at this moment ,and again the pictures confirm ,we are on schedule for first gold pour Dec. As predicted by management. Runruno is set to expire H1 next year [slightly after original plan , due to a couple of incidents last year ,which delayed operations ,but of course the gold ore ,was waiting for mining to catch up.] It will then be returned to a 'natural' state.
La India is the future ,and where ALL effort is concentrated to bring a continuous income ,from gold ,hence the upbeat reception this morning. The improvement in gold production ,and price ,is a +tive to pay for La India ,without extra loans .The new loan facility appears to be for new Caterpillar plant.
I came to MTL after Ed's jan 24 selections about 3p then ,so a VERY satisfied customer ,with Stoko subscription more than paid for. I have traded a bit on news since then , but have topped up with the Condor buy -seems 'a VERY good buy '??
Of course they have additional possibilities after La India is established ,and I guess that will pay for those to be exploited ? Cheers Tony
Dissapointed to see Metals Exploration (LON:MTL) not covered. Its very high value rank got me interested in the share originally. It’s 5 bagged since then and still looking cheap with la India coming into production. I see the next 5 years been very lucrative here if you can be patient. Short term it’s looking just as good. This is a massive holding for me, and I’ve broken all the rules on this one but I’m confident in the team, should be 25p-30 back end of next year easily.
I've written a short comment on MTL now, Mhar91. I'm not a mining analyst but I've done what I can to get it discussed in the table! Apologies for the delay in getting it up. G
Thanks for your response Graham, great work it’s much appreciated by all users!
Government finances are perplexing - what to add in / take out of gross national debt affects the number and therefore an idea of what is / is not manageable ... in terms of cover of interest. One podcast argues we are there and yet another makes some adjustments and presents the opposite view. Therefore it's easier to just focus on the market mood - which would appear to have soured - and moves this week to support long bonds had a quite a market impact. One day yield falls were significant but these by and large reversed yesterday. If we take a step back and just plug the numbers into a spreadsheet and ask where are we? MOVE is 74 ...nothing to see? Inflation expectations remain at 2.3% as measured by the difference in conventional yields and the same duration TIPS yield. Term spreads - the difference between longer term yields and short are there but nothing outrageous ---2-10s spread = 50bp and 2-30s =105 pretty much the same as the last time I looked. You could argue nothing to see yet the Treasury and markets seem to be nervous.... the 30 year yield is nudging 5% and this seems to be an obstacle for markets....which suggests that as they move higher then interest charges on debt push debt higher and are therefore unsustainable. So even in a world where the Treasury cheats and issues Bills (short dated) - the market likes to think the whole situation is financeable in 30 year debt. Furthermore this would appear to be difficult at north of 5%....so the Treasury steps in ....with a small order Vs the size of the market. Contrary to previous wobbles fiscal policy is being raised in the debate.... which has underpinned growth so far. This game could have long time to run - but 1% movement days in currency ie. $ - should catch your eye....trouble may be brewing. I haven't done much yet but have an eye on lightening the load just to have a little more firepower ahead of a month or two that could well be more volatile. On a more positive note the volatility should suit TP Icap (LON:TCAP) and IG group (LON:IGG) IMO.
I have sold some holdings and have 20% in cash (some in short dated gilts for tax reasons as outside a shelter). I may increase cash further. Trump is likely to do something stupid (or is it stupider) before the mid-terms. And impossible to guess what this could be. His attack on the Fed to cut rates seems to have dried up. Such a shame his father stopped this genius musician from pursuing that career ( according to the oracle of trump).
It's just a shame his father didn't stop, full stop. :-((
His maximum stupidity and incompetence will be clearly revealed AFTER the midterms.
Once these elections are over, he will be entirely free from any political pressure.
All the best
False news, they are all ganging up on me!!
If you're right on that Yiannos it really will be time to run for cover. Let's hope for a change you're wrong.
Anthropic (ANTH.PVT) is preparing to publicly file paperwork for its initial public offering (IPO) as early as the end of the month - according to Bloomberg
I wonder why the rush is their exit liquidity concerns
They want to get it done before the bubble bursts.
The need to pay Nvidia so that Nvidia can pay them so that they can pay Nvidia so that Nvidia can pay them so that they can pay Nvidia so that....
yep - and the same thing went on in the dot com boom. Sooner or later companies or joe public are going to have to buy these AI products and in volumes to justify these valuations, it will be quite a bill! The alternative is ............
Bubble,bubble, anyone with a pin
Think there is a typo: "Anthropic’s Day 1 Market Cap will be c. $1.97 billion, using the midpoint of the spread. That’s just shy of the $2.1 trillion" Should be $1.97 trillion I reckon.
2026 is the year for me when we all started talking about Trillions!
indeed!
“Hyper scale” is another often used term to describe the volume and size of data centre deployments - I think the clue is in the root word - “hype”and there are a lot of players in the supply chain with vested interests willing this to happen