Daily Stock Market Report (Fri 24 Jan 2025) - ZTF, IOF, BMY, BRBY, REC, BEG

Good morning everyone,
I'm writing to you this morning while Storm Eowyn is having a blast. Good luck to everyone affected!
Megan and Mark have kindly provided us with a few backlog sections to get us started.
Podcast: our weekly podcast has been published, this time featuring Ed, myself and Lawrence. Ed discusses the findings of his new article - "The Jump - what to do when share prices react to Trading Statements".
Here are the links:
Spotify, Apple Podcasts, YouTube, and Amazon Podcasts.
1pm: this report is complete, have a nice weekend everyone.
Spreadsheet accompanying this report (updated to 17/1/2025)
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Severn Trent (LON:SVT) (£7.4bn) | TU | In line. Accepts Ofwat’s Final Determination for 2025-30. Dividend growth to match CPIH. | |
Burberry (LON:BRBY) (£3.7bn) | Q3 TU | Q3 LfL store sales -4%. After festive period, now more likely H2 will broadly offset H1 loss. | AMBER (Graham holds) |
Paragon Banking (LON:PAG) (£1.6bn) | TU | Full year guidance reiterated. | |
Renew Holdings (LON:RNWH) (£718m) | TU | Rail Sector is behind exps, so FY 2025 will be below exps but still ahead of 2024 (adj. profit £70.9m). | |
Bloomsbury Publishing (LON:BMY) (£533m) | New agreement with Amazon | New long term supply agreement. Reiterates confidence in consensus expectations. | AMBER/GREEN (Graham) Last-minute deal agreed, terms unknown. Valuation somewhat full here? |
Begbies Traynor (LON:BEG) (£148m) | Latest Red Flag Alert | “Critical” financial distress climbs by 50% q-on-q. Hotels, Leisure and Retailers the worst affected. | AMBER (Graham) There could be a wave of insolvencies this year, especially in certain badly-hit sectors exposed to the consumer, higher rates and tax rises. |
Quadrise (LON:QED) (£103m) | Result of Placing and Subscription | Raises £4.5m with an upsized placing, £1m also expected from a Retail Offer. | |
Record (LON:REC) (£95m) | Q3 TU | New equity fund launched. Neutral net flows. Performance fees are helping, revs now slightly ahead. | GREEN (Graham) No major changes to forecasts. I like the value here even if growth may be limited. |
Pulsar (LON:PULS) (£70m) | TU | FY Nov 2024: ARR +£2m at constant currencies to £61.7m. Adj. EBITDA £9m, in line. | |
Works co uk (LON:WRKS) (£12m) | H1 results | LfL sales down 0.8%, in line with exps. Adj. EBITDA loss. Current trading in line. |
Backlog
Zotefoams (LON:ZTF)
Up 7% to 317p - Trading Update - Megan - GREEN
The ‘news’ section of Zotefoams’ corporate website helps explain why the wind has been knocked out of the company’s share price since management announced that it is pausing the active hunt for a commercial partner for its new recyclable packaging. Every one of the company’s latest news stories are about the excitement around ReZorce - the product which is now being shelved.
But this morning’s trading update is a good reminder that there is a lot more to the company than ReZorce.
In the year to December 2024, Zotefoams is set to announce revenues of £147.8m, which is 16% higher than the previous year and marginally ahead of previous guidance of £145.5m.
Strong sales growth has largely been driven by the footwear division, where the company sells its specialist ‘High Performance Product’ foams to the sports industry, where it is used in trainer orthotics. Sales in the HPP division were 37% higher at £80m.
In the industrial markets which Zotefoams serves, including construction and personal protection, demand has been slower, meaning polyolefin sales have been marginally lower. Polyolefin is a synthetic product used in many different industries, which has long provided the backbone to Zotefoams’ sales. But 2024 is the first time the company will report higher sales from its newer ‘High Performance’ foams, which are also sold at higher margins. Operating margins have ticked rapidly upwards at the company over the last five years (from 10% in 2019 to 16% in the last 12 months) thanks to this evolving product mix.
It is worth noting that the company has benefited this year from especially strong demand from Nike, as appetite for fancy new trainers tends to soar in an Olympic year. So it may be that the product mix rewinds slightly again in 2025.
In 2024, the company is set to report adjusted pre-tax profits of £15.6m, up from £13.1m last year and ahead of the previous £14.9m expectations. The adjustments are largely related to amortisation costs on acquired intangibles and an impairment MuCell extrusion (MEL) division (which is mainly the ReZorce development project).
There is a brief comment on the leverage in this trading update, which is expected to fall to approximately 0.9x (from 1.2x at the end of 2023). At the last count, net debt stood at £44.6m after first half net cash outflows.
Megan’s view
This is an interesting business with a good footprint across multiple markets. It’s relatively capital intensive, which isn’t really my cup of tea. But it’s being well managed (the decision not to embark on an expensive rollout of a new product without a commercial partner was a very sensible one).
The share price has fallen to a more reasonable level now that the hype of ReZorce has been removed. I see no reason to change Roland’s previous stance. GREEN
Iofina (LON:IOF)
Down 3% to 21p - Trading Update - Mark - AMBER
This company that produces iodine from the brine produced by oil & gas wells has had record production:
The total H2 2024 production of 358MT was within our forecast range. When combined with H1 2024 crystalline iodine production of 276.1MT, total production for the year was a record for the Company, up 13.4% to 634.1MT compared to 2023 production of 559.3MT.
And pricing has been strong:
The company has benefitted from a strong spot raw iodine price in excess of H1 2024 levels and is currently above $70/kg. Prices are anticipated to remain at these higher levels throughout H1 2025 due to the continued robust global demand for iodine. IPBC product sales have performed particularly well for Iofina Chemical in 2024, significantly surpassing 2023 levels, driven by strong interest from customers.
However, delivery problems mean they actually report a miss:
Consequently, the Group expects to report adjusted EBITDA for 2024 in the region of $7.5m, below the forecast range of $8.5m-$9m. The Company projects that without these unexpected delays, the Group would have met its forecasted adjusted EBITDA target range.
This appears to be a genuine timing issue, as they say:
The recognition of delayed sales in January 2025 has given the Group a stronger start to the year than previously forecast.
Looking more generally at the company, I see their revenue growth has been impressive:
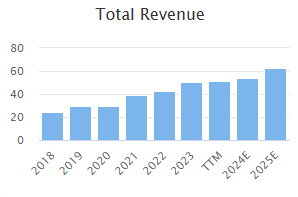
But it is not matched by EPS:
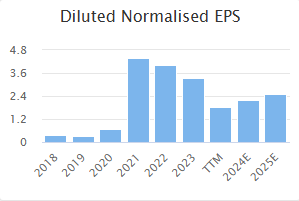
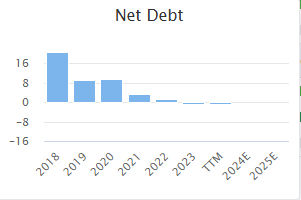
This may be commodity pricing, but I also understand they had to renegotiate long-term supply agreements with suppliers of brine as they were too favourable to the company. Still, if they achieve 2025 forecasts, excluding the impact of the extra shipment, the P/E of around 10 is modest for a growing company. The lack of dividends suggests this growth requires capital. However, internal cash flow and an earlier raise mean that the company is debt-free:
Mark’s view
A miss for pure timing reasons can give a potential opportunity. However, like any commodity play, I think investors will need to do quite a bit of work modelling production and pricing before being able to conclude that this is cheap.I don’t think this has been covered by DSMR before, so I remain neutral until I can do more work on this particular market. AMBER
Graham's Section
Bloomsbury Publishing (LON:BMY)
Down 0.5% to 651p (£531m) - New agreement with Amazon - Graham - AMBER/GREEN
Something dramatic happened between BMY and Amazon.com (NSQ:AMZN) last night.
At 5.51pm, Amazon published an announcement in its News section (emphasis added):
Our contract to sell Bloomsbury titles was scheduled to expire last year. We extended the contract under its current terms several times in an effort to reach an agreement, but despite our best efforts over the last seven months, Bloomsbury has refused to engage in a good faith negotiation to discuss a new contract to sell their titles in our store. Unfortunately, the latest extension expires at midnight on the 23rd of January and after that time, Amazon will no longer be able to sell Bloomsbury print books in the UK, Europe, and Australia, or Bloomsbury Kindle books worldwide.
Later, the announcement was edited to add:
UPDATE: As of 10.30 p.m. on 23 January, an agreement in principle has been reached between Amazon and Bloomsbury, and Bloomsbury books continue to be available for our customers.
Which leads to the following RNS from BMY:
Bloomsbury Publishing Plc (LSE: BMY), the leading independent publisher, has reached a new long term supply agreement with Amazon.
The Board reiterates confidence in consensus expectation.
Graham’s view
My interpretation of this is that BMY has compromised in its negotiations with Amazon. The extent of the compromise is unknown, but what we do know is that it won’t have much of an effect on immediate trading and therefore on the results for FY Feb 2025.
I’m a little concerned by Amazon’s statement that its previous terms with BMY were “far out of sync with other publishers who sell books through our store”. Does this mean that BMY has been enjoying abnormally high but unsustainable levels of profitability through its trade with Amazon? Perhaps because Amazon was desperate to keep Harry Potter available in the past, but is now prepared to negotiate?
Amazon walked away, declared it publicly, and then a deal was abruptly reached. So again, I’m left with the conclusion that BMY must have compromised, to some extent.
This might not be the most popular move but I’m inclined to moderate our stance on this one to AMBER/GREEN, as the market cap of over £500m seems somewhat full to me, given the balance of risks and uncertainties.
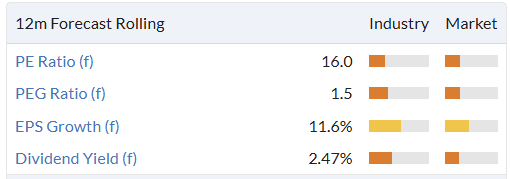
It’s wonderful to be the publisher of Harry Potter, and I don’t wish to downplay it, but if that is the main attraction here then I’m not sure how I could justify a more premium valuation than BMY is already trading at. Finding the next JK Rowling or Sarah J. Maas won’t be easy. A better argument for these shares might rest on management's ability to make clever acquisitions using the cash thrown off by its past successes.
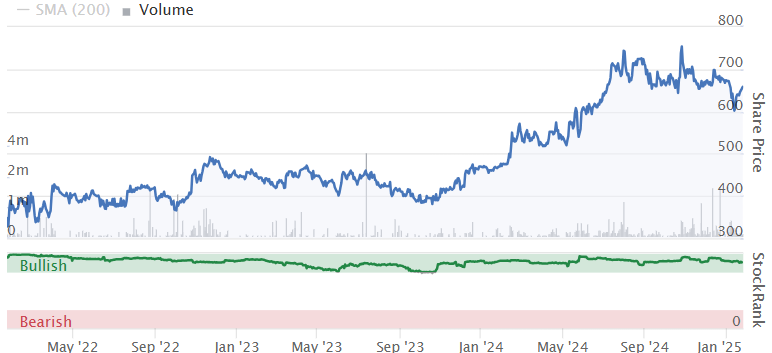
Consensus expectations for FY25, according to the company, are for revenue of £334m and adj. PBT of £39.6m. Advisory firm h2radnor were forecasting adj. PBT of £39m as of last October. BMY has been doing a good job of raising expectations over time:
Burberry (LON:BRBY)
Up 12% to £12.00 (£4.3bn) - Third Quarter Trading Update - Graham holds - AMBER
At the time of writing, Graham has a long position in BRBY.
I had a look at this in July last year, on the day of a serious profit warning. It let go of its CEO that day, and immediately hired a new one.
Roland followed up in November with a look at the company’s interim results.
Today we have the Q3 update to the end of December, and fortunately it’s providing a brighter perspective.
Firstly, comparable store sales are down by only 4% for Q3 (vs. Q3 last year). In H1, comparable store sales were down by a far more concerning 20%.
Total retail sales for Q3 are down 7%, made up of:
Comparable store sales: down 4%
Increased selling space: up 1%
FX headwind: down 4%
Next, a look at sales by region. Asia Pac has been a big worry, but we see the following improvements across the regions:
Asia Pac: down 25% in H1, down 9% in Q3.
Americas: down 21% in H1, up 4% in Q3.
EMEIA: down 13% in H1, down 2% in Q3.
How did BRBY do this? Various actions they’ve taken are provided, including a brand reset, enhanced visual merchandising (mannequins are back!), and reuniting their creative and commercial teams in London.
Outlook: this is very impressive in the context that the consensus forecast was for a £66m full-year loss for FY March 2025:
As previously communicated, we are acting with urgency to stabilise the business and position the brand for a return to sustainable, profitable growth, supported by strong cash generation and balance sheet strength. We are confident that our strategic plan will improve our performance and drive long-term value creation.
While we recognise we are still early in our transformation, we are encouraged by the response from customers and partners over the festive period. In light of our Q3 performance, it is now more likely our second-half results will broadly offset the first-half adjusted operating loss, notwithstanding the uncertain macroeconomic environment.
The adj. operating loss in H1 was £41m, so we can look forward to an adj. operating profit approaching that figure for H2. So there has been a huge rebound in profitability in H2 vs. H1.
Graham’s view
As a shareholder here for many years, the thought has of course crossed my mind that I should have cashed out at higher levels.
Two -year chart:
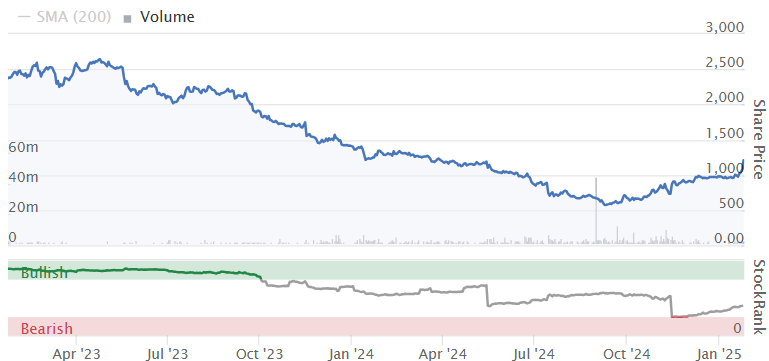
It’s a recovery play and the current valuation (£4.3bn) suggests that the market does see this returning to something that resembles the profitability of the past. Today's new guidance, implying a big rebound in H2, does suggest that this is possible.
Indeed, the share price has doubled since September - a nice reminder that there is no shortage of dramatic moves in the big-caps!
Personally, I continue to believe in BRBY’s brand strength. There has been a generalised slowdown in luxury spending and I think that is the main driver here, although clearly there have also been some internal struggles and disagreements over how to respond.
Gucci is a brand that I like to check when reviewing BRBY. Gucci's Q3 revenue (to Sep) was down 16% on a like-for-like basis. When results are announced, I’ll be curious to see if it also enjoyed a big improvement in the quarter ending December.
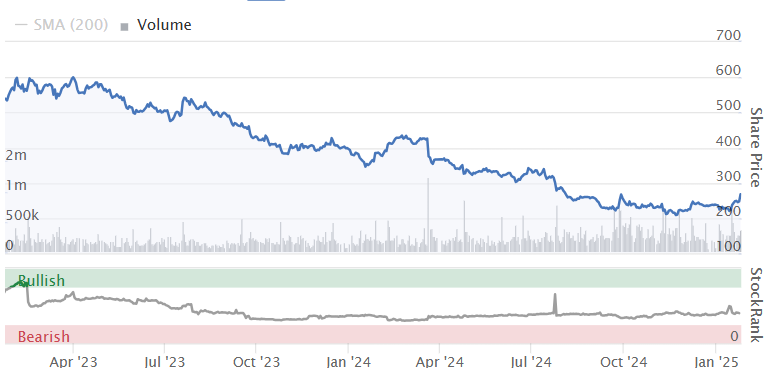
Gucci’s parent company Kering (KER), like BRBY, has had a very rough few years in terms of its own share price movement, highlighting again that there are problems across the sector, not just for BRBY:
I’ll leave my stance unchanged at AMBER today as I acknowledge that this is still a recovery play. While BRBY might generate a modest profit in H2, the current market cap does already price in the return to meaningful profitability, which isn't guaranteed although I do think that it's more likely than not, in the next few years.
For patient investors who are willing to wait it out, I do think the stock remains a reasonable hold. And so AMBER seems fair enough to me.
Record (LON:REC)
Up 8% to 51.3p (£102m) - Third Quarter Trading Update - Graham - GREEN
This update was eagerly awaited following the slide in Record’s share price in recent weeks:
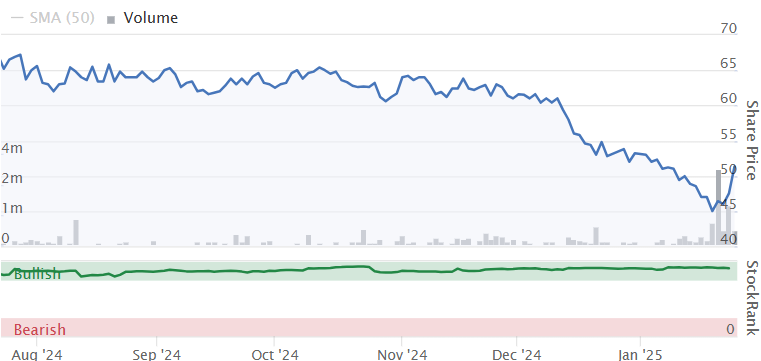
Thankfully, some of the fears appear to have been unfounded following this morning’s positive update.
The shares are now down by only about 10p vs. where they were in early December.
I was GREEN on this one in November, at 62p.
Today’s update:
Fee rates “broadly unchanged” (fee erosion is an issue for currency hedging providers).
Performance fees of £1.3m in Q3 bring performance fees up to £2.9m year-to-date.
The result is that revenue is trending “slightly ahead”:
With management fee expectations for the full year unchanged and with £2.9m of performance fees recognised for the nine months ending 31 December 2024, we now expect revenue to be slightly ahead of previous expectations.
Net flows are almost a wash, with growth in the new category “Hedging for Asset Managers” offset by small outflows from the hedging products:
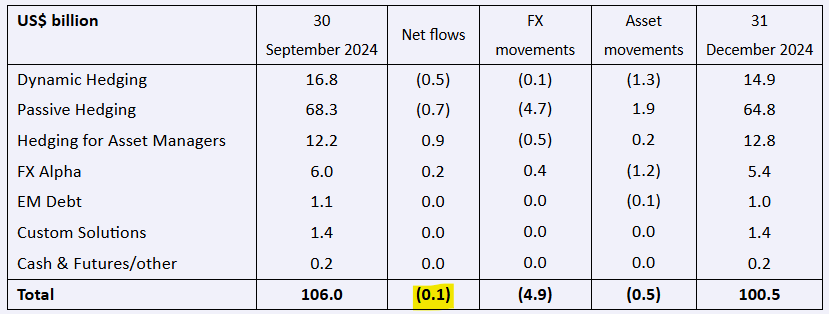
Estimates: Panmure have made no changes to their estimates beyond the addition of this year's performance fees. They had assumed £1m of performance fees in total for H2.
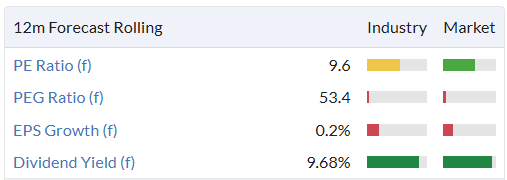
Therefore we have an EPS estimate of 4.9p for the current year (FY March 25), and little change is anticipated for the following years (4.8p of EPS for both FY26 and FY27).
Graham’s view
There are few fireworks here - just some slightly higher performance fees than might have been predicted.
Someone must have been worried about this update, but it has turned out to be a non-event.
I don’t see any reason to change my GREEN stance.
It’s not the most exciting share or company that we cover here, but it has reliably generated profits for many years, has a very strong balance sheet that includes surplus cash, and is diligently trying to grow some new income streams that will complement its existing ones. Maybe they'll succeed, maybe they won't. But with a heavy dividend yield and a cheap-ish earnings multiple, I still like it.
Begbies Traynor (LON:BEG)
Unch. at 92.6p (£148m) - Latest Red Flag Alert Report - Graham - AMBER
Some dramatic numbers here with the number of UK businesses in “critical” financial distress up by 50% in a single quarter.
Worst-hit sectors, said by Begbies to be “in worrying states of financial health”::
Hotels & Accommodation up 84%
Leisure & Cultural Activities up 76.5%
General Retailers up 48%
Food & Drug Retailers up 37%
The definition of “critical” financial distress is when a company has an outstanding CCJ of over £5k against it, or faces a winding-up petition.
Begbies also classifies companies in “significant” financial distress. The number of these rose less sharply: only up 3.5% quarter-on-quarter but still up by 21% year-on-year.
The quote from a partner at Begbies Traynor is suitably depressing:
As we start a new calendar year, there is very little to be excited about. Across nearly every sector, there has been an unprecedented level of growth in the number of firms who are at serious risk of entering insolvency in the next 12 months. The fact that the distress is being felt across almost every corner of the economy highlights how difficult the outlook is for UK businesses right now.
She goes on to say that borrowing costs are will be “structurally higher for the foreseeable future” and that the current position will be exacerbated by tax rises and the higher minimum wage.
Ric Traynor says “I fear 2025 could end up being a watershed moment where thousands of UK businesses 'call time' after struggling to survive for years”.
Graham’s view
Begbies is not a disinterested bystander but I tend to trust their analysis as they do have their finger on the pulse when it comes to insolvencies.
For me, this report is another reminder that we need to stay extra-focused on balance sheet health this year, as the tax rises from April are likely to have a big impact. Also, companies that need to refinance in 2025 need to be analysed with great care.
The simple solution is to focus on stocks that are in rude financial health, so that refinancing is not a concern, and tax increases will not be fatal.
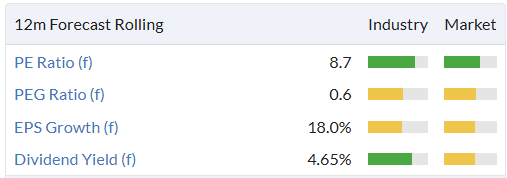
When it comes to BEG I was neutral on it in December at 99p and while there is a chance of windfall profits if a wave of zombie firms decide to call it a day this year, that would only be a temporary phenomenon. I continue to believe that it’s fairly priced around current levels.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

78 comments
Hi Silver Moon, I like the new name! I'll have to make sure I check out the full year results in March. Nice TU yesterday. G
Everplay Group may well come out to play, I'll hold a little longer.
Team17 (LON:EVPL) Is it suspended today? If so why, it is only a name change.
Seems to available now.
Anyone else having problems on the IG platform?
yes unstable - my watchlists were down
Thanks, at least it their system not mine.
Watchlists work but l have nothing in my positions, so l can't sell anything. Search often does not work, not available it says.
Here you go Graham. Could be a good investment.
Saw this on Lords of the Rings. It didn't end well.
Looking forward to seeing you all
David
Hoping Renew Holdings (LON:RNWH) will be reviewed, most viewed and biggest faller today. Looks overdone the fall, will it bounce like Sanderson Design (LON:SDG) did?
Delays caused by elections and change in Government?
Sorry Rusty2, I didn't get to RNWH!
As a long term subscriber to Stockopedia I thought I would look back on the performance of my Portfolio in 2024.
Overall I was down £4k or 0,8% . My best performer was Rolls Royce which when sold in October showed a 61% return.
My dividends for the year were £18,860 plus £12,250 from Pinewood Technologies (LON:PINE) which was a special situation.
My poor performance in 2024 was due largely to 5 Holdings which had a very poor year including my second largest holding Serica Energy (LON:SQZ) . The other 4 were Sylvania Platinum (LON:SLP) down 47%, a very cyclical stock, Sanderson Design (LON:SDG) a real disaster,Entain (LON:ENT) down 31% and Burford Capital (LON:BUR) down 13% but now well up during the last couple of weeks.
I know averaging down is unwise but I am sorely tempted to add to Sanderson Design at 45p.
Seems way oversold to me.
Thank you to all subscribers for your invaluable comments which I read every day without fail.
I am holding Sanderson Design (LON:SDG) I have held it may years, when it was Walker Greenbank formely. It is a decent, co and I don;t see any sign of disaster, just muted trading. Perhaps a CEO a bit distracted, but I'd hazard to guess in 5 years this will have returned
averaging down, and averaging up , in my mind , are the two most profitable trades. True to my believe I topped up Serica @144 today.
Well, conventional wisdom says you are wrong, yadi. Averaging down often results in serious underperformance for the simple reason that you are sticking to your belief that you are buying a good stock despite the market telling you otherwise. You have to be very sure that your rationale is still sound and clearly understand why the declining share price might be temporary.
Admittedly the numbers on Stockopedia are telling us that Serica Energy (LON:SQZ) is cheap, but clearly the market doesn't believe these numbers and must be betting that a dividend cut is on the way.
Well Serica Energy (LON:SQZ) is above the 50DMA and 130DMA, so what does that tell you? So if you bought at 160p and topped up at 140p that is bad but if bought at 125p and topped up at 140p that is ok then?
Some of share price fall is because it paid out large dividends, 23p in the last 6 months.
Can't agree with you there, sparkler. SQZ is like the vast majority of oil shares on the UK market. Unloved and unwanted because of the green agenda. It's had a few operational issues, but nothing out of the ordinary for an oil stock.The company has just reiterated its commitment to shareholder returns. The divi is rock solid - all IMHO of course. I added this week as well. That yield is just too, too tasty.
Costain (LON:COST) is down severely compared to peer Galliford Try Holdings (LON:GFRD), so maybe investors have got wind of some contract delay or cost overrun. I sold, just in case.
Edit: Now i see a possible explanation, namely read across from Renew Holdings (LON:RNWH). Thanks, DWitt199
Renew Holdings (LON:RNWH) states "...trading within the rail sector has been impacted by the slow start to the Control Period ("CP7")".
Costain (LON:COST) also has a CP7 "Service Partner Framework contract with Network Rail" and highlighted it at the Interim presentation:
Van Elle Holdings (LON:VANL) is down around 5% on a read across. It did warn in its preclose statement for 6 months to end Oct. that "Workload has been subdued in Rail, as the sector transitions from CP6 into CP7". The results are next Wednesday (29th).
Van Elle Holdings (LON:VANL)
The company acknowledged the challenging conditions in its December update
"Market conditions have continued to be challenging across all sectors. Workload has been subdued in Rail, as the sector transitions from CP6 into CP7, and Highways continues to experience project delays. The impact of the Building Safety Act has caused delays to start dates of taller residential schemes however encouragingly the new build housing sector has continued to recover, with a strong pipeline of work planned for delivery throughout the second half of the financial year."
However unlike Renew Holdings (LON:RNWH) it continues to expect to meet market expectations for the FY25, albeit second half weighted.
Extract from trading update 12 December:
"The Board continues to expect results for the full year in line with market consensus1, and as previously communicated, anticipates profitability being second half weighted....
Company compiled analyst consensus for FY2025 underlying profit before tax is £6.0m."
Also, since mid December, Rockwood Strategic (LON:RKW) has increased its holding from 5.95% to 9.24% and Peter Gyllenhammer acquired 4.24% of the shares just over a week ago.
I would further add that Directors have spent over £100,000 in the last month or so.
On the basis that the company hits its earnings forecast the shares are very cheap on a whole range of metrics, which show a swath of green on the stock page together with negligible net debt.
Posted by a biased holder of a full size position with an average purchase price of 38p.
Bloomsbury v Amazon
Such a pity that Bloomsbury crumbled under Bezos bully boy tactics .
I wish they would have told Amazon where to shove their hardbacks .
They could equally have called Amazons bluff and dragged them into hand to hand combat .
“We dont respond to blackmail tactics employed by huge corporations with questionable tax policies that sees profits transferred away from the UK economy and not into the fiscal budgets of our chancellor to help pay for our doctors nurses and teachers
Not only are the existing practices of amazon questionable at best they then seek to renegotiate our commercial contract which effectively transfers margin from bloomsbury to amazon and reducing both our shareholder % returns but by extension yet more tax is diverted out of uk economy .
In 2022 anazon paid x % of their uk revenue to our coffers whereas bloomsbury paid 3x .
This transfer of wealth coupled with the clear bully boy mafia style press release of amazon attempting to strongarm us means that our commercial relationship is terminated with immediate effect
Bloomsbury maintains a strong worldwide distribution network of independant retailers and wholesales who all pay fully domiciled tax and we are proud to now have the chance to enhance their offerings by offering our world renowned collection not on amazon “
- That would have made my year though probably wiped a few quid off my pension
I do wonder if donald trump was bloomsbury ceo what he would have done .
REF : Donald Trump.
He would have probably bankrupt it, as he did with his companies!
Its about volumes and marginal costs, its a win win. There is more to taxable benefits than CT, employment, rents, transport to name a few, overall Amazon probably adds more to UK coffers than Bloomsbury
There is more to taxable benefits than CT, employment, rents, transport to name a few, overall Amazon probably adds more to UK coffers than Bloomsbury
huh - surely if 50 million books per year are beingh sold - thats always going to be better done by uk firm paying proper taxes compared to an entity whose sole aim is to extract as much cash out of the uk as quikcly as posible paying as little tax as possible. It seems absurd to suggest we the uk get any benefiu whasoever from Aamzon if the alternative was a uk company paying "proper taxes" and recycling their earninsg in thne uk.
we should charge these charlaton overseas entities extra to allow them to to take money from anything in ten uk - we know their soel goal is to suck all the cash out then uk paying minimal tax as possible.
anyone who cannot see the plain simplicity of this situation and how stupid we are allowing cash to be extracted to china and american companies - its the recycling of monies earned that keeps the economy ticking over. I dont need an economist to tell me these us and china firms take as much as they can and give as little back as they can - dont pay their fair share - shoudl be taxed very highly and we would be better of withn replacement that paid fair taxes.
Have you seen the answersd given by aamzon executives when questioned by uk members of parliament - their reponse have ben a joke from what i have seen.
in principle i am 100% for a free ecomomy but we are being taken for fools here.
heck get an uber and they will likely pretend they are a tour operator and not a taxi firm ! they only pretend to be a tour operator as their multi year scam of pretending to an online app and not an transport company was eventually closed down.
Ok rant over
Agree with the sentiment but any chance we had of asserting our authority in such matters is severely limited.
Messrs Reeves, Lammy and Bailey went cap in hand to China - so I would expect that the Shein floatation has been rubber stamped.
Donald Trump has threatened retaliatory action if we continue to target Big Tech.
Also some comment today from one of the biggest Private Equity in the US that the UK is too difficult to do business with.
We are in poker game where we have jack high and everyone else has a strong hand.
I dont think the Americans on the Cinese and too interested in how we tax others - heck its not as if they dont put their interests first.
I would agree that as a group the politicians in charge seem quite happy taxing regular workers at far higher rates than these huge companies that really have such a stranglehold of the real cashflow.
Poor micro businsess often need to pay google or facbook just to get their customers through the door - and that money can legitimately depart then uk with no vat being accounted for - where uk competitor has to pay vat over to hmrc - how could that ever be allowed ? . That situation is beyond crazy when they need to remove winter fuel payments for people on not much more than a couple of hundred quid a week.
Hey ho its almost as if they the decision makers are in the pockets of these large corporations.
The problem is big business in the US and China is now intertwined the Governments of these countries.
Pushback against the business and they take it as being anti US or anti China. I dont know how you hit the sweet spot of taxing/ restricting US and Chinese business without ruining further trade discussion or attracting sanctions in return.
This sort of thread has popped up about a dozen times in the last couple of years. Its the type of sitiuation that no one disagrees with - but to which there is no easy solution.
We could have bluffed our hand a bit better, instead Reeves and Starmer chose for a two month period prior to the budget to talk our economic prospects down.
Its one thing having a weak hand but telling everyone round the table you are drawing dead is a not a good idea.
i dont doubt you are right to a certain degree
ultimately though post brexit we can set out own rules that are not obviously unfair (ie google must account for vat to uk authorities if they have sales from non vat registred uk business - that would just be vat neutral)
its not about screwing these companies over just ensuring they pay a fair level of taxes
If i was in charge i would be running a level playing field and dealing with consequences if they arose. Look at apple they got backdated bill from ireland but they didnt up sticks and leave - i very much get teh feeling its a no lose gamble for these companies - all cash they get (perhaps exception of soem amazon stuff) is so proitible you could easily take an extra 20-30% and it would just be a rounding figure on their annual results !
We do nowt but add an extra 6% corp tax onto companies based in the uk!
So the fact there may be resistance deosnt mean soemthig cant be acheived - heck with trump all you gotta rprobably do is give him a nice pr bone and he is probably happy plenty of way to sort that out.
Not even sure its shoudl be up to the politicians here Jim Harra has to be the worst head of hmrc ever - try and comprehend this statement making any sense on any level - i guess if you dont look you dont see !
HMRC has found “no evidence of fraud” in a case where 12,000 Chinese companies changed their addresses to a flat in Cardiff.
Jim Harra, the permanent secretary at HMRC, told MPs on Thursday that it was an “odd” and “curious” incident, he said there has been “no fraud perpetrated on HMRC as a result of this and it’s not clear that it was an attempt to defraud us”.
https://www.independent.co.uk/...
Maybe a savvy UK entrepreneur should start a marketplace startup and then take away business from Amazon.com (NSQ:AMZN). Good luck with that.
Bezos bully boy tactics is the right description. The Amazon book store is famously a long tail business in which the vast majority of sales come from quite a small number of titles. I cannot imagine that they would have wished to carry on for very long without being able to sell the Harry Potter and Sarah J Maas titles.
My point is this
It is entirely within the gift of any company to tell amazon to get stuffed
I was under intense pressure at px from my sales team to list on anazon to grow sales
Luckily or unluckily i was a 90% owner with a black and white on the spectrum brain and just told them no, “i dont agree with the way they do business and thats the end of it “
No CEO of a public company probably has this in their gift but you only have to dance with the ones you want fo dance with .
What I was suggesting was that Bloomsbury should have told Amazon to get stuffed. I bet their titles form a significant percentage of the Amazon book sales.
SRT Marine Systems (LON:SRT)
I attended the SRT AGM yesterday and posted my notes here:
https://www.stockopedia.com/co...
for anyone who follows SRT or is just interested to know more about the company
Bloomsbury Publishing (LON:BMY) like others I'm not quite sure what to make of today's announcement. I must admit I was hoping for an ahead of expectations trading update by now in order to justify the current valuation - they tend to set expectations very low and then upgrade towards the end of the year. Last year we had an update in December and another in February, but nothing so far this year (today's update suggest they are at least in line), Current forecast are around 37p - I would like this to be nudged up to around 42p to keep me interested.
Begbies Traynor Red Flag report overnight for Q4 2025 makes salutary reading - more details here on their site: summary below which I generate using AI for the TL;DR
Their headline is a bit more hyperbolic " Historic jump in number firms in critical financial distress/..."
Based on their Report - sector bullish /bearishness does reflect this - the lower left quad being the Dogs (below both 50 and 200 MAs ) while the Upper Right are the Stars (above both )
Most bearish are Renewables, Ind Materials, Retailers, REITS, Grocery. Beverages ,Food Producers (ABF's update yesterday underscores this ) Ind Support, Utes
Plot: median of names above and below 50 and 200 MA averages : coloured by bearish red to bullish green and bubbles sized by MCAP) click to enlarge
Here's an expanded View of the Lower Left Quad
Plot: Expanded Lower Left Quad median of names above and below 50 and 200 MA averages : coloured by bearish red to bullish green and bubbles sized by MCAP) click to enlarge
And a look inside the Retail Sector as a relative strength representation of names : these are sized by MCAP and coloured by Bearish (red) to Bullish (Green) -
of the 39 names - 75% are bearish with a lot of clustering in the Dog zone lower left quad
Plot: median of names above and below 50 and 200 MA averages : coloured by bearish red to bullish green and bubbles sized by MCAP) click to enlarge
Overnight the GfK Consumer Confidence was a big miss -22 on an expected -18 : 0 being neutral and >0 being optimistic : so a bit dire
For contrarians and mean reversionists, we could be close to the darkest hour before the dawn?
UK Business Financial Distress Report: Q4 2024
Key Findings
Sector Analysis
Consumer-facing industries hit hardest:
Key sectors in significant distress:
Regional Impact
London leads in both critical (14,326) and significant (182,250) financial distress cases.
Expert Insights
Julie Palmer, Partner at Begbies Traynor:
"Unprecedented level of growth in firms at serious risk of insolvency. Consumer-facing industries particularly strained due to rising costs and higher wages."Ric Traynor, Executive Chairman:
"2025 could be a watershed moment where thousands of UK businesses 'call time' after years of struggle."
Economic Factors
Outlook for 2025
Experts predict continued rise in insolvencies due to:
The absence of reduced tax burden and strong economic recovery paints an uncertain picture for UK businesses in 2025.
I post this stuff on X https://x.com/runningprofits
As a follow up I was going to post a few snippets of news today. As there is no good news I will pass.
Seems like a lot of potential work for Begbies in the near future. I wonder at what stage (if ever) it will filter down to improve shareholder return
Costain (LON:COST) down 5% today. Heavy selling, but I cannot find any news to justify this.
Read across from Renew Holdings (LON:RNWH) possibly?
No, but my spreadsheet which records info from the Stock Report tells me the 50dMA is going in the wrong direction. I hold Costain (LON:COST).
Renew Holdings (LON:RNWH) In today's TU they say they referred to CP7 rail slow start in their FYR on 26 Nov 2024. I cannot locate this reference. Could anyone else please find??? Thankyou.
Renew Holdings (LON:RNWH)
KBR said:
In today's TU they say they referred to CP7 rail slow start in their FYR on 26 Nov 2024. I cannot locate this reference. Could anyone else please find???
It is in the CEO's review section
" Whilst we note that the start of CP7 has been slower than expected, we remain confident that this will normalise through the control period as we have seen historically."
The question as a holder is whether this mild profit warning is just a minor blip in the growth trajectory, or something more fundamental. I favour the former as profits are still expected to be ahead of 2024, the group is well diversified with water doing well and they are confident in the order book.
There must be some doubt about the credibility of management as they clearly underestimated the risks of the transition to CP7 in the November results announcement, but is this sufficient to justify today's share price fall? I don't think so and intend to continue to hold but it would be good to hear any counter arguments.
Renew Holdings (LON:RNWH)
Hello DWit199. Thankyou for that reply . However on reading the CEO review I still cannot see any reference to CP7 being slower!!!! Hope you can assist further. KBR.
Renew Holdings (LON:RNWH)
However on reading the CEO review I still cannot see any reference to CP7 being slower!!!!
It's in the fourth paragraph of the Rail section of the CEOs review.
"We have continued to selectively expand our Rail client base outside of Network Rail and overall, we commenced CP7 in a significantly stronger framework position than at the start of CP6. Whilst we note that the start of CP7 has been slower than expected, we remain confident that this will normalise through the control period as we have seen historically."
Hard to believe that a short sentence hidden in a long report could have such significance. The Renew share price has been in decline since the results in November so quite a few people did work it out.
Link to article
,Renew Holdings (LON:RNWH) Thankyou so much DWit199. Must read every word of complete document . However it was pretty well concealed in the full sentence. However not a acceptable excuse for me!!! KBR
Renew Holdings (LON:RNWH) (I hold :( )
From the FYR 26 Nov 24:
"We have continued to selectively expand our Rail client base outside of Network Rail and overall, we commenced CP7 in a significantly stronger framework position than at the start of CP6. Whilst we note that the start of CP7 has been slower than expected, we remain confident that this will normalise through the control period as we have seen historically."
The CP7 period is 2024-2029.
From the TU 24 Jan 25:
"As indicated in the Group's final results announced on 26 November 2024, trading within the rail sector has been impacted by the slow start to the Control Period ("CP7"), which commenced in April 2024. This lower-than-expected level of activity has continued in recent weeks, as has been widely reported. Consequently, trading in the Group's Rail sector is now behind management expectations.
Given the ongoing challenges with delay and deferment in our Rail activities and more recent uncertainty over timing of the commencement of a number of renewals programmes, the Board anticipates full year trading will be below market expectations1 albeit adjusted2 operating profit is still expected to be ahead of prior year (2024: £70.9m). Having operated in this sector through previous control period transitions, we believe that this situation will normalise as we move through the cycle."
Maybe I am being gullible but if the 23% fall is all due to this:
1
I would have expected any loss of income due to cancellation of HS2 to be reflected in the Nov 24 outlook.
2
The 2025 update stated that CP7 income is being *deferred to later in the cycle, not lost*. Engineering projects have a lot of complexity and dependencies. The TU tells me that the mgt can see now that work they expected to bill before sep 25 will now be billed post sep 25 - in the next FY.
As such (and please disagree) if you were planning to hold for the long term (or until 2029) I would read this as some income has been deferred, and if I had some cash, would top up rather than dump.
I see this as a company which is well run and has diversified to position itself to benefit from both the promised UK infrastructure spend and European energy transition, with lower risks than those that come from being a prime contractor on large civil engineering contracts for new infrastructure.
Reassuring comments on environmental, as well as good progress on integrating recent acquisitions.
In Environmental, activity levels in Water are ahead of expectations and we anticipate strong momentum through the transition to the new control period AMP8 which commences in April 2025. In the period we were appointed by Affinity Water to two new major 5-year frameworks, further strengthening our position ahead of the next control period. Forecast trading in our Energy and Infrastructure sectors remains in line with management expectations.
The integration of our recent acquisitions, Excalon and Full Circle is progressing well and trading at both is forecast to be in line with expectations for the full year. In line with our strategy, the Group continues to review an active acquisition pipeline.
I was happy to reach into the cutlery draw first thing and grab some more shares at under 700p, close to my October 2023 entry price.
Good morning Graham, I noticed Team 17 has become Everplay Grouo with the ticker of EVPL. Have you any thoughts on this dog of mine?
Team17 (LON:EVPL) there are no share prices, on my platform it is suspended. On folios the valuation is nil.
Shares have been rising but beware the name change.
Friday thought about missed large cap opportunities - sorry if this is a bit rambling.
So I've been watching Burberry (LON:BRBY) for a few months now, thinking about buying it if there were obvious concrete signs of a turnaround. I don't often buy £1bn+ market cap companies.
What I've found interesting is how much the share price went up off the back of a new CEO coming in. If you bought near the bottom you'll be up 100%+.
At the interims revenue was down -20% with Q1 & Q2 as bad as each other. The only bright spot was Japan where the economy has been more resilient in recent years. So my conclusion was the new CEO had their work cut out and why invest now when this might take time. They told a good story that they'll focus on their core outerwear products again - makes sense.
Today's Q3 update looks better as the group retail revenue is now -7% rather than -20%. So the share price is up c.14% while we type.
BUT they are only due to break-even this year. And even going to 2024 results it trades on 15x p/e now. The ATH is c.2500p so it could double again yet but that was off the back of the pandemic when the rich were spending more of their excess cash on luxury goods.
Of course, turnarounds rarely go completely according to plan so there might be another buying opportunity yet. But I feel like I've missed something a lot of other investors have obviously seen. Is it that Burberry (LON:BRBY) as a share is just prone to a lot of speculation? Is it that large caps just move a lot faster? Did other investors have access to data that I don't or were they looking at other luxury goods companies around the world to spot trends which Burberry (LON:BRBY) would likely benefit from as well?
Maybe even if I knew why I might not have felt comfortable buying shares given the poor interims performance. But I think it can be useful to learn from 'missed opportunities' as much as investing mistakes. Would welcome any views!
Sorry if this is a bit rambling.
Hi TortoiseInvestor. I've watched Burberry (LON:BRBY) with some fascination also and my take for what it's worth is that it's a perfect illustration of Buffet's view of the market being akin to a manic depressive.
The SP got well ahead of itself on the elevation strategy (flogging tat at eye watering prices) of the previous management whilst ignoring the enormous capex required to fit out all the fancy aspirational stores (and take over tube stations - https://cpp-luxury.com/burberr...) and also ignoring the fickle tastes of fashionistas and the rapidly deteriorating outlook in one of its core markets of Asia.
Once the reality began to dawn on investors that actually there probably aren't enough gullible rich people prepared to pay thousands for a pair of check underpants, and that the ongoing capex was rapidly creating an enduring burden on the balance sheet, Mr Market went into a rapid depressive downer and marked the SP down, overcompensating to the down side.
Now that a new mid-market specialist has been installed as CEO (Joshua Schulman - ex Coach), Mr Market is hyper-optimistic that he can stem the bleeding and turn Burberry into the next Michael Kors or Coach and drive huge volumes at slightly less eye-watering prices. I for one, remain a little skeptical but I imagine that in the mid to long term, Mr Schulman will engineer a creditable turnaround but is unlikely to perform the kind of miracles Mr Market is now banking on.
As the turnaround takes shape, I guess the SP will oscillate between hope and despair and eventually settle on a realistic valuation somewhere in the middle. In the meantime, it looks like a great share for traders and a terrible one for long term value investors. Good luck to holders but there appear to be better ideas available at the moment which are not dependent on a complex turnaround strategy that has no guarantee of success.
Hi Tortoise investor
Re Luxury stocks.
I do not hold any at the moment but have done in the past.
What I have noted is that luxury as a sector rising steadily COMPAGNIE FINANCIERE RICHEMONT SA (SWX:CFR) kick started it with their Q3 sales update (16/01).
Since then other luxury stocks have gained momentum.
Today Burberry (LON:BRBY) further added momentum.
This might suggest a wider sector rise.
This is sector watch list as I type ...
Regards
Howard
Hi
Adding to the previous post for the luxury sector rising. This 1 month view of some players ...
Regards
Howard
Really helpful analysis - thanks Howard!
Couple of thoughts on this sector, it is by a country mile my biggest exposure and I have long term holdings in LVMH Moet Hennessy Louis Vuitton SE (EPA:MC) and Hermes International SCA (EPA:RMS) that today make up 20% of my total. I traded out a bunch of LVMH above €700 in early 2024 with appalling timing given it went to €900 in March. and rotated it into my favoured pick Hermes, adding steadily on dips. It is the sector standout performer at the mo, but the results period is upcoming, LVMH next week and Hermes in early Feb. That's when you'll know for sure what's going on, and where in the world.
For sure there's been big action on Burberry (LON:BRBY) over the last period, as has been the case in the sector overall, I had this one open in spreadbet but closed it last night and missed the extra on top today - so you're not alone in "missing out" on this one.
But in my simple opinion Burberry is/has been a trade opportunity, and I don't see it as a long term investment proposition. In this sector the real action has taken place since 2021 - see my chart below. It started picking up 2016-2019 but then discounting 2020 the real ride started for lux stocks. But have a look at how they stack up since 2021 - there will always be price swings in this sector, but for me unless there are real signs of downturns I will comfortably keep holding and building.
I don't think you've missed any particular data, but if this is a sector you want to get into you do need to keep a tight eye on the general market trends, and global disposable incomes. China has been a big driver for lux stocks, but the US now starts to become a bigger factor. Wild swings in price happen as general economy news is mapped onto lux companies by analysts - but the key is always what is happening within the company itself.
Personally I wrestle frequently with the concepts of trading and holding - is Hermes too good to be true at current levels and should I risk trading out for a while and waiting..... Or do I sit it out and wait for the next 3 years to pass ? There's no single answer to this as it is absolutely tied to one's financial position, risk appetite and plan timelines. One thing's for sure, at €2700 a share Hermes International SCA (EPA:RMS) is not one for everyone.
Related to this there is an interesting strategy originally by Benjamin Graham that John Huber wrote up a while ago, buying large (mega) cap stocks when they are out of favour. Clearly it won't work every time but I have started it recently, so far to modest success. LVMH a while ago, ASML more recently. I have pondered others at various points (Nike, TSMC, Meta) and failed to act, regretting all but Nike (so far). I'm not sure Burberry would be 'quality' enough for me to use in that context but the other luxury names certainly are.
Thoughts on Ben Graham's "Unpopular Large Caps": A Still-Effective Strategy
Graham's "Unpopular Large Caps" Part 2: Thoughts on Diversification
Certainly has worked in the US, buy Apple (NSQ:AAPL) Alphabet (NSQ:GOOG) Meta Platforms (NSQ:META) Microsoft (NSQ:MSFT) Shopify (NYQ:SHOP) even NVIDIA (NSQ:NVDA), when they are down, also the Stockranks were down also. You don't have to go back very far, about 2 years. I kept buying Alphabet (NSQ:GOOG) when it was falling, it soon went back up, now over 100% up from $90. The others have doubled also.
Want to thank Graham and the team for this last month or two and particularly for this weeks output given the avalanche of companies reporting. Good to see the message board waking up from the winter slumbers as well, we all have a part to play in keeping this place vibrant.
Renew Holdings (LON:RNWH) has confirmed what is in the public domain a delay in delivering railway projects which has impacted on revenue but less so on profit.
Looking long term, I do wonder how much of an impact on these companies bottom line when the government nationalises the railways from 2027?
Will the government invest more to upgrade the rail infrastructure and create more lines like the Cambridge to Oxford link?
Will similar companies like Renew Holdings (LON:RNWH) benefit from Nationalisation? Since the shares have dropped by 20% this morning, could this be an opportunity?
https://commonslibrary.parliament.uk/when-will-my-local-train-operator-be-nationalised/#:~:text=The%20government%20is%20bringing%20most,expected%20to%20finish%20in%202027.
Renew Holdings (LON:RNWH) Nationalised industries over the years are slowly starved of investment.
Record (LON:REC)
Interesting flat AuM movement for Q3. The shares have fallen @25% since the interims which suggest they should rise this morning - but anything could happen.
Small position
A
Not bad quarterly results at all from Record (LON:REC). They have now upped their revenue guidance for the year, due to the increase in performance fees (as i flagged on 15-11-24, not to blow my own trumpet :) ). These should drop straight through to the bottom line.
I expect revenue to be around the £47m for the year. Assuming there hasn't been a large increase in costs, which they haven't indicated in any trading updates or interim reports. I think PAT should be in excess of £10m around 10% greater than current forecasts.
The shares appear to me to be undervalued especially as they aren't reporting huge net outflows like other fund managers. The nature of their funds means uncertainty (e.g. UK and US elections in Q2/Q3 of 2024) could result in net inflows/negligible outflows in the final quarter.
Just my two penn'orth (i hold)
thanks for covering Iofina (LON:IOF) Mark, great to see some 'resource' style stocks show up in here.
I quite like this one as a GAARP idea, and jurisdiction-wise I think they will benefit from the trump thing.
Demand for their products always seem to be more than they can produce, and with the continuing reinvestment of capital rather than dividends they continue to expand production capability YoY.
Hi
I commented on IOF last October on the back of its good Q3 update. I have followed the company for a number of years and the management team has done a solid job getting the business to where it is today. The risks for this type of investment are obvious, but I agree with Antehelion that it may benefit from Trump's energy policies.
I have traded it a few times since 2020, most recently at the end of last year. Could be time to go in again.
Thanks for covering the stock Mark.
Zotefoams (LON:ZTF) analysis:“This is an interesting business with a good footprint across multiple markets”
Megan, I love a day that starts with an excellent pun!
Zotefoams (LON:ZTF) Like the humour: footwear division and a good footprint.
Very downbeat red flag report from BEG this morning, headlined “Historic jump in the number of firms in critical financial distress”
Zombie business's have kept going for years with the low interest rate. They need clearing out to make space for more dynamic, robust entrants.
Whilst we are in a higher interest period I think it is the new tax levies and minimum wage increases that is applying additional and unsustainable pressure for some businesses (ridiculous timing when you think about it). I don’t know if you have run a business yourself but this kind of indifferent sounding comment on what will be a tragedy for many sounds a bit like our smug Chancellor, if you’ll excuse me for saying.
I never understood Sunak's generosity during covid, when business failure would have been more expected and therefore socially acceptable.
Bloomsbury Publishing - BMY - another oddly worded RNS (like CMCX yesterday). Reading between the lines, I'm guessing the new agreement with Amazon is on worse terms that the existing agreement. As a shareholder I had been wondering why it had sold off recently...
I didn't see it as odd. New agreement reached and expectations unchanged.
possibly not but it was extremely short and not very positive in tone. Ignore me!
It is odd - BMY usually put out clear statements with fresh news If this was simply a renewal on existing terms why the RNS. - if it is better or worse - why not say so.
It seems the deal was not a foregone conclusion - see e.g. https://www.therowlinglibrary....
(from 23 Jan). I was not aware of any of this behind-the-scenes wrangling at all.
From the Bookseller:
"Amazon informed Bloomsbury that they would no longer sell Bloomsbury print books in the UK, Europe, and Australia, or Bloomsbury e-books worldwide from midnight. We have been in discussions with Amazon over terms since last summer. At no point during these discussions did Amazon say that they would take such action. We learned about this at the same time that Amazon issued a public statement and was contacting Bloomsbury authors and agents. We have now reached agreement with Amazon in order to ensure the continued availability of our titles on Amazon."
Presumably Amazon.com (NSQ:AMZN) tried to strong-arm @Bloomsbury Publishing (LON:BMY) into a worse deal. Will have to watch to see if brokers revise forecasts. Worrying, although muted price response suggests no immediate danger likely.
As Graham notes, there is only a month to go until FY25 year end, but what about the likely impact of a less generous Amazon deal in FY26?
Let's see what the brokers say.
Many thanks to Jeff and Welwichia for this explanation which demonstrates strength and spirit of the STOCKO community.
Seconded!
If you're a Bloomsbury Publishing (LON:BMY) shareholder, remember to use your discount:
"For investors with 1 or more Bloomsbury shares (including if held directly or via a nominee), we offer a special discount of 35% (off RRP) on all books published (print only) by Bloomsbury."
BMY. Now sold. This looks to have been badly handled. I can only see negative impact - and other retailers may also look to exercise their muscle accordingly.