Daily Stock Market Report (Fri 24th April 2026) - BRCK, ASC, DIAL, FOXT, DOM

Good morning!
We had several hundreds of viewers watching last night's webinar, and participating with comments and questions - I hope you enjoyed it!
Turning to today, as it's Friday, I'll attempt to catch up on interesting stories we missed during the week.
Have a great weekend! Cheers.
Spreadsheet accompanying this report: link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Mondi (LON:MNDI) (£3.7bn | SR42) | Market conditions remained challenging resulting in an underlying EBITDA of €212m including €8 million of forestry fair value gain (Q4 2025 €214 million, including €1 million of forestry fair value gain). “These pressures persist into the second quarter and we are taking pricing actions to mitigate their impact. While there is an inherent time lag, we expect these measures to take full effect in the third quarter.” | ||
Computacenter (LON:CCC) (£3.6bn | SR95) | “We now expect to deliver a much stronger performance in the first half of the year than previously anticipated… we now anticipate delivering full-year results comfortably ahead of market expectations.” | ||
Serica Energy (LON:SQZ) (£1.06bn | SR71) | Planning to arrange fixed income investor meetings. A new 5-year senior unsecured bond issuance may follow, to repay the Reserve Based Lending debt. Production has increased significantly, Q2 average so far 49,100 boepd. Guidance for 2026 remains unchanged. | ||
Redcentric (LON:RCN) (£190m | SR50) | “The proposed capital reduction will create additional capacity to deliver further returns to shareholders while maintaining a strong balance sheet.” | ||
Record (LON:REC) (£106m | SR80) | Positive net flows $1.4bn. AUM falls from $115.9bn to $114.6bn (negative asset movements/FX movements). Average fee rates “broadly unchanged”. Earnings expectations for the full year unchanged. | ||
Cyanconnode Holdings (LON:CYAN) (£28m | SR18) | FY March 2026: expects revenues >£20m (FY25: £14.2m). “The Company continues to make steady progress with several long-term prospective projects in the APAC region and the Middle East. These opportunities are moving closer to order stage…” | ||
Celsius Resources (LON:CLA) (£24m | SR30) | Trading of CLA shares to be restored on the Australian exchange. Dispute is ongoing re: the acquisition by Sodor, Inc and its affiliate of shares in Makilala Mining Company and the mineral processing company for the MCB project. | ||
Manolete Partners (LON:MANO) (£22m | SR64) | Strong H2. FY26 revenue £28m in line with expectations. Net debt £11.5m. £4.7m exposure to debtors who have not paid. May make £1.5 - £2.0m provision. Expects “adjusted realised profit before tax” of £1.9m before any adjustment for these debtors. | ||
Light Science Technologies Holdings (LON:LST) (£16m | SR24) | FY November 2025. Revenue £8.6m (2024: £12m). Loss before tax £0.89m (2024: £0.03m). Cash £0.7m. Raised £6.6m post-period end. “The enlarged Group is strongly positioned to capture a greater share of value chain…” | (Graham) - These results are very late, but the company has been busy in recent months with fundraising and acquisitions. |
Backlog: BRCK, ASC, DIAL, FOXT, DOM.
BRCK (LON:BRCK)
Up 4% to 50.58p (£163m) - Graham - GREEN =
There was lots of news from Brickability - now called “BRCK” - yesterday evening.
3.57pm: “Response to Rule 2.8 Announcement from Atlas”
The Board of BRCK Group… notes the statement made by Atlas Holdings… earlier today confirming that it does not intend to make an offer for BRCK.
At the end of March, there had been a “non-binding indicative proposal” from Atlas to buy BRCK at 65p, rejected by BRCK’s Board.
There followed a period of due diligence and consultation, to see if an improved offer might be made and accepted.
The end result: the two sides are walking away from each other.
4pm: Pre-close trading update
BRCK Group expects to report another year of revenue growth at approximately £645.0 million, an increase of c.1.2% over the prior year (FY25: £637.1 million). Furthermore, FY26 Group adjusted EBITDA before share based expense is expected to be c.4.4% ahead of the prior year at approximately £52.3 million (FY25: £50.1 million).
This announcement is in line with expectations.
Net debt is £60.5m (leverage multiple 1.15x)
It wasn’t all plain sailing:
Many of the Group's businesses were impacted by the continued challenges of the housing market during the second half of the financial year and, as widely reported, adverse wet weather also negatively affected the beginning of 2026, the final quarter of the Group's financial year. In addition, some of the secured projects within the Contracting Division were impacted by continued delays in the receipt of Building Safety Regulation… approvals to commence works.
THE CEO says: “we are exceptionally well-placed to capture significant value from the enduring structural demand across our end markets.”
Graham’s view
I covered the offer from Atlas here, noting the large premium (50% to 60%) over the prevailing share price
Based on the cheap earnings multiple and the interest from a reputable private equity outfit, I was comfortable upgrading our stance on this by one notch, to fully positive.
After an in-line update, there is no need for me to change stance today.
The private equity buyer has walked away for the time being, but they were willing to pay 65p. So if their analysis is right, then fair value is likely to be a good bit higher than that!
A reminder of some of the value metrics here:
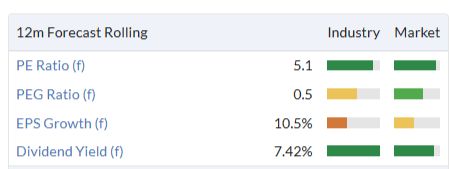
Net debt of £60m is significant but the leverage multiple of 1.15x tells us that it should be a manageable amount of borrowings.
It’s not a sleep-soundly-at-night type of stock. Leverage plus cyclical housing market demand is not the type of combination which I’d want to bet heavily on.
But there’s a price for everything, and this seems to be priced for shareholders to do well - probably.
I always seem drawn to these stocks categorised as Contrarian by the algorithms.
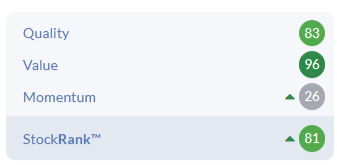
The only weak point is Momentum - and that seems to be picking up:
Asos (LON:ASC)
Up 2% to 254p (£304m) - Interim Results - Graham - RED =
We already got the H1 trading update here.
Yesterday, the results were published.
The main point is that FY26 guidance is unchanged.
This is all copied and pasted from the trading update:
GMV to show an improving trajectory throughout the year, 3-4ppts ahead of revenue
Gross margin improvement of at least 100bps to 48-50%
Adjusted EBITDA of £150m-180m
Broadly neutral free cash flow
Net debt is up by £19m year-on-year, reaching £295m.
That gives a leverage multiple of 1.8x forecast adj. EBITDA (using the midpoint of the range).
Ordinarily, a leverage multiple of 1.8x is considered OK.
But that assumes we are talking about a profitable business.
Adjusted EBITDA is positive (£64m in H1, £150-180m for the full-year), but adjusted EBIT is negative.
And if the results aren’t shielded by adjustments, they are truly awful: the H1 pre-tax loss is £138m.
ASOS is forecast to remain loss-making for the foreseeable future, although adjusted EBIT may turn positive next year, if the forecasts are to be believed.
CEO commentary
I like the CEO’s goals:
ASOS has the ambition to be the most inspirational destination for young fashion lovers on the planet. This ambition is built on three core pillars: our capacity to provide the most relevant product to our customers; providing the most inspirational shopping experience; and underpinning this with an efficient and flexible operational model. It is the combination of these three pillars that differentiates ASOS and will turn us into the reference of the online fashion market.
In addition to their own brands, they “a broad and carefully curated selection of established and emerging brands from around the world, making us both a destination for leading brands and a platform for discovering new brands and new fashion.”
The turnaround is in full swing, with some improvement in the trend for Gross Merchandise Value - although it’s still declining for now, down 9% year-on-year.
The focus is on creating a more efficient operating model, controlling costs, reducing inventories, and fundamentally changing the relationship with their customers: “moving from a promotion-led model to one centred around excitement, with customers engaging with ASOS to discover something great rather than hunting for a bargain.” Moving up the value chain, in other words - not easy when catering to a young demographic struggling with student loans, etc.
Graham’s view
As I said last time, I agree with the logic of avoiding head-on competition with Shein and Temu, as that’s unlikely to end well.
If they were approaching this with a clean slate, I’d be encouraged.
The problem is the balance sheet - how long can they afford to be unprofitable while they evolve?
The latest debt picture:
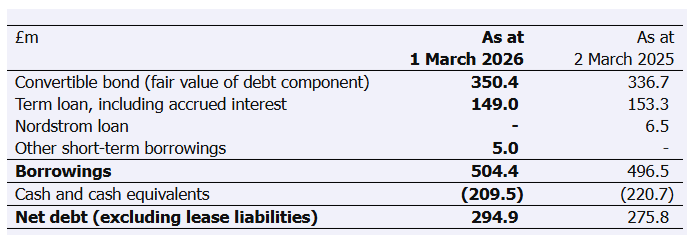
I’ve checked the footnotes: the convertible bonds have a conversion price of £79.65, so they aren’t going to get converted (the share price would have to increase by 3,000% to exceed the strike price).
There are about £250m of these convertible bonds left outstanding, with some of them having been repaid in the last two months. They charge 11% interest - a hefty burden for a business in the middle of a turnaround.
In conlusion, I’d rather be a bondholder here, rather than a shareholder. I’d say the bondholders have a decent chance of getting their money back, e.g. with the help of an equity refinancing next year.
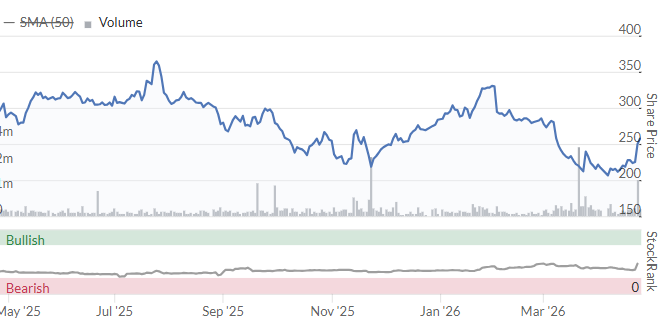
But as I don’t think the equity is safe, I’m staying RED here at a £300m market cap.
Diales (LON:DIAL)
Up 23% this week to 27.2p (£14m) - H1 Trading Update - Graham - AMBER ↑
This describes itself as “the leading global professional services consultancy to the construction and engineering industries”.
Yesterday’s H1 trading update was “at least in line with expectations”:
The Group expects to report revenue from continuing operations of £23.7 million (H1 FY25: £21.6 million) and deliver a 43% increase in underlying operating profit from continuing operations in the region of £1.0 million (H1 FY25: £0.7 million). On the basis of current trading, the Group expects to deliver FY26 results at least in-line with market expectations.
Cash has improved from £3m (Sep 2025) to £3.9m (March 2026).
CEO comment:
"The Group has entered H2 FY26 with increasing confidence as our transformation strategy gathers pace. For the last four years we have consistently enhanced our profitability, expanded our talent base and deepened our presence across key markets. Despite ongoing geopolitical pressures creating uncertainty for many of our clients, demand for our specialist expertise remains robust.
Estimates at Equity Development are unchanged.
FY Sep 2026 revenue £44.4m, adj. PBT £1.5m, adj. EPS 1.9p
FY Sep 2027 revenue £45.5m, adj. PBT £1.7m, adj. EPS 2.1p
Graham’s view
It’s been a long time since we last looked at this one.
We were a little negative on it before, which no longer seems appropriate for a Super Stock that’s performing “at least in line” (i.e. potentially ahead of expectations).
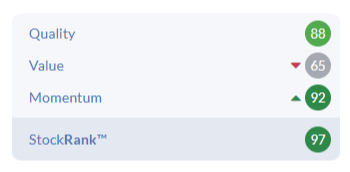
However, it is still a consultancy business, and I’m not sure why it should deserve a particularly high earnings multiple. With adjusted EPS of about 2p, it’s trading at 13-14x earnings. That does seem rather aggressive to me, for the sector.
Perhaps this is a little too cautious, but I’m only going to upgrade our stance by one notch, to neutral.
Foxtons (LON:FOXT)
Up 3% at 43p (£124m) - Q1 2026 Trading Update - Graham - AMBER =
Let’s get an update on the London property market from Foxtons.
Overall revenues are lower, dragged down by weak Sales:
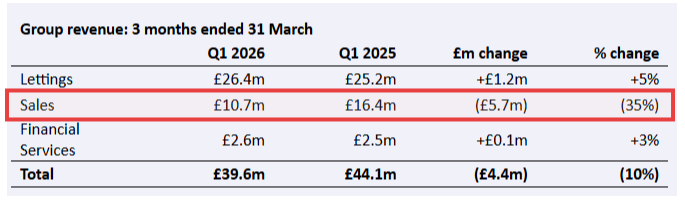
Lettings: the 5% growth is largely from acquisitions. “A pipeline of further acquisition opportunities exists and is currently being worked on.”
Sales: this is the standout movement, driven by the impending tax changes in the corresponding quarter last year, which made for a difficult comparison, plus “a more challenging market backdrop”:
Sales revenue declined by 35% to £10.7m (Q1 2025: £16.4m), reflecting an exceptionally strong prior‑year comparator that benefited from elevated transaction volumes ahead of the 31 March 2025 stamp duty deadline, as well as a more challenging market backdrop in Q1 2026.
They note that compared to two years ago, Sales revenue was slightly higher this quarter.
With mortgage rate increases and lower mortgage availability right now, Foxton “is taking action to reposition the Sales business to current market conditions”.
CEO comment: “Our strategic focus on recurring revenues has ensured that Foxtons has delivered a resilient performance despite recent market headwinds.”
Graham’s view
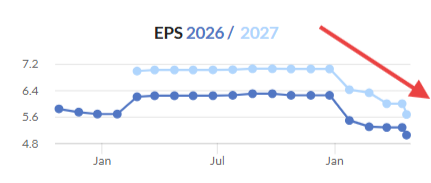
This share has already de-rated considerably over the past year, with a really poor share price performance in 2026 year-to-date:
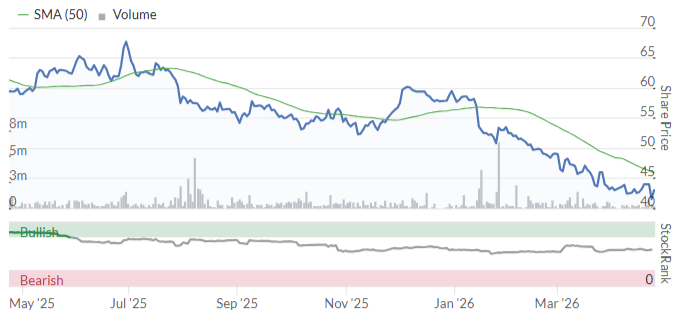
I turned neutral on it in January, when forecasts were downgraded at Panmure Liberum (although the trading update itself did not explicitly cut guidance).
Yesterday, Panmure left forecasts unchanged. But I think staying neutral here continues to make sense.
The shares are cheap:
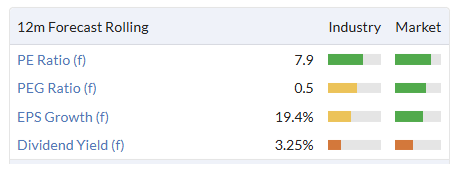
But that’s for a good reason:
This isn’t a quality compounder, and I think it’s priced about right here.
The bigger point is about the housing market, and the implications for other companies we follow here. London is seeing a slowdown that goes beyond just the instability caused by tax changes in Q1 last year.
If conditions improve, hopefully Foxtons will be one of the first companies to give us a sign of recovery.
Dominos Pizza (LON:DOM)
Up 4% this week to 198.2p (£763m) - Q1 Trading Update - Graham - AMBER ↑
This was an AGM update for Domino’s.
As a counterpoint to the gloom from some consumer-facing stocks, there was no drama here:
System sales +5.8% (like-for-like +4.5%)
Orders +2.3% (like-for-like +0.9%)
They are now selling Chicken - “Boneless Bites, Tenders and Wings” - under the name CHICK ‘N’ DIP.
And at this early stage, they’re on course to meet expectations for 2026:
Despite the well documented macroeconomic backdrop, our costs are hedged for the current financial year with some costs hedged into 2027 and we do not currently foresee any supply-related issues. The Board currently expects to achieve our earnings expectations for the full year.
Graham’s view
We’ve not spent much time on this share over the years - it has been too large, and too mature, to be of interest to small and mid-cap adventurers.
But the market cap is now well below £1 billion, with the share price around the levels it first reached in 2011-2013. That's a lot of optimism that has been squeezed out of the valuation.
5-year chart:
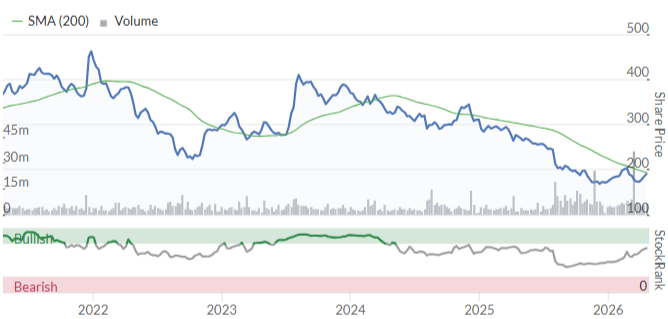
Perhaps it's worth looking at again here?
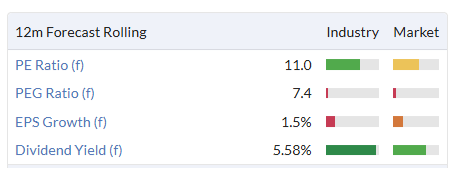
Stockopedia categorises it as my favourite style - Contrarian.
For a quality biz, this is a cheap rating:
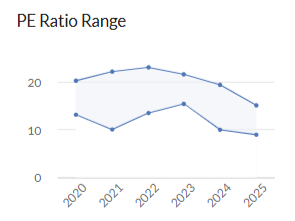
And near the bottom of the range in which it typically trades:
Checking the archives, I see that Roland was moderately negative on this one last September, at around the same market cap. He noted that the leverage multiple was 2.3x.and that profits were expected to fall again in 2025.
I see his point, and I won’t suddenly turn us positive on this share. But surely there’s no need for us to be bearish on it at this level?
Net debt was £285m as of December 2025. Leverage was within the company's target range of 1.5x - 2.5x.
This one is starting to look interesting to me. I’m taking us back to neutral.
Have a great weekend everyone, see you on Monday!
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

65 comments
BoE are partly responsible for pushing up asset prices with their QE policy that should have been a one-off re-capitalisation of bank balance sheets but carried on way too long! BoE, FCA (previously FSA) and the Treasury have zero credibility IMO when it comes to calling the markets given their complete lack of activity around the RBS acquisition of ABN Amro in 2008 and their general lack of understanding of what was happening on UK bank balance sheets at the time.
I would much rather listen to Jeremy Grantham of GMO. His recent 50 minute interview on Master Investor is excellent and well worth listening to in full.
https://tinyurl.com/yns6686n
hVIVO (LON:HVO) Now we know why hVIVO (LON:HVO) sold off yesterday after good news. NED wanted out because not standing again at AGM. Sold approx £200k worth.
Has another 2M shares that he might sell in the future but hopefully not straight away.
Just to clarify it’s William O’Neil who used the gap as a confirmation signal while Zanger saw it as a strength signal.Its only here because it’s not time sensitive
For LSE:CCC (Computacenter plc), the analysis as of the market close on Friday, April 24, 2026, confirms a massive Stage 2 "Power Gap" Breakout. Following the Q1 Trading Update released at 07:00 AM today, the stock has exploded through all-time highs on record volume. This move satisfies the Mark Minervini Trend Template and represents a high-conviction "Institutional Footprint" as the market digests significantly upgraded 2026 guidance.
Whole Analysis LSE:CCC (Computacenter plc)
Computacenter has transitioned from a consolidation phase into a vertical momentum leader. Today's surge is a textbook Dan Zanger-style "Gap-and-Go" fueled by a combination of hyperscale demand in North America and AI-related infrastructure projects in the UK.
Technical Analysis: The 1-Day Chart (Last 10 Trading Days)
Today's price action represents a definitive decoupling from the FTSE 250 average. The stock gapped up at the open and "walked the bands" all day, closing near the top of its intraday range.
Date (2026)
Price (GBX)
% Change
Volume Signal
Apr 13
3,118.0
+0.85%
Support test at 50-day SMA
Apr 14
3,164.0
+1.47%
Pocket Pivot (Low-cheat entry)
Apr 15
3,162.0
-0.06%
Constructive Churn
Apr 16
3,222.0
+1.90%
Institutional Nibbling
Apr 17
3,278.0
+1.74%
Breakout of multi-week base
Apr 20
3,398.0
+3.66%
Power Reversal (New High)
Apr 21
3,458.0
+1.77%
VCP Tightness
Apr 22
3,450.0
-0.23%
Pre-update de-risking
Apr 23
3,342.0
-3.13%
Shakeout (Normal Reaction)
Apr 24
3,698.0
+10.65%
Q1 TRADING UPDATE POWER GAP
The 10 Best Indicators & Signals
Weiss Wave Strength: Dominant (9.6/10)
The Weiss Wave shows a "Buying Tsunami." Cumulative volume on the "Up Waves" since the March annual results is 5.4x larger than any selling volume seen in Q1. This signals that the float is being permanently removed by "Strong Hands" (insiders and large-scale growth funds).
Fundamental Review
Conclusion: Buy/Sell Recommendation
Verdict: BUY (Stage 2 Momentum Leader)
Computacenter is currently the strongest "Special Situations" tech leader on the FTSE 250. Today’s high-volume gap-up is a definitive entry signal for the next leg of the 2026 growth cycle.
Recommendation: BUY. Do not wait for a full gap-fill; the institutional "Tidal Wave" is too dominant.
Who is Michael O`Neil?
Thank you to all that joined us at MelloBirmingham
For those who could not make or missed out on our Birmingham event, our Chiswick event is just five weeks away.
Early Bird tickets are only available until midnight tonight before prices rise to General Sale. Secure your ticket before Saturday and save up to £40.
The line up of speakers and companies is already first class for investors attending and we have more to come...
https://www.melloevents.com/mello2026
I watched part of the webinar last night and the rest now. I think that worked pretty well and Ed and Graham make viewing both enjoyable and informative. I think if you have time having these from time to time would be useful and welcome. Thank you
I just watched the webinar and agree with other positive comments. Would be great if we could have a tab that included all ahead of expectations trading stocks that we could refresh from time to time. Ditto for profit warnings too actually.
Seconded!
I just put a cryptic note on my Sharescope charts, which i prefer, but use Stocko for all else.
Serica Energy (LON:SQZ) The TU today says production significantly increased - but maintains 2026 guidance. Are they expecting problems (again) later in the year...?
No - I think production is expected to increase hopefully absent last years problems and additions from M&A ....
Hopefully just Serica Energy (LON:SQZ) being suitably circumspect after last year's trials and tribulations with the FPSO in particular.
Sorry folks, this is a Stocko admin post. I’ve reported on the green button that I’m getting ad hoc delayed notifications (news and price). It’s been happening since early March and most of the time they’re current, but too often others are days late. Is anyone else having the same issue?
Yes l have had a few that were days late but not recently.
Get too many 404 errors.
For anyone wrestling with google finance this morning - at the top left click beta and it returns to classic and all back to normal. On your phone you need to click on the settings button and do the same to switch back to classic and access your watch lists again. thank you google for the 15 minutes hassle - always a pleasure.
I agree, the new Google Finance beta is horrible! Took something that worked well, and messed around with it.
Guess a Google Product Manager has anxiety about his or her career and desperate to justify their role...
Webinar was brilliant, we like to have more of it. Thank you Ed and Graham.
For those who missed it, here is a list of Top Ten :
MTI, SLP, Keller, Ramsden, AEP, Curry,YU, Vodafone, Eco-animal, Ithaca.
It'll be interesting finding out what was said about Ithaca Energy (LON:ITH) , I still hold a few shares but jumped ship earlier this week in favour of Harbour Energy (LON:HBR) .
Hi Silver Moon. I held Harbour Energy for a while but was put off by the BASF overhang and the risk it could keep weighing on the share price until it’s fully cleared, which might take quite some time. As you'll know, BASF recently dumped 80m shares via an accelerated bookbuild at around 273p and are now in a 90‑day lock‑in, though they can still sell to LetterOne. They still hold roughly 35%, so I’d expect more selling once the lock‑up expires. They do score well on the Stocko ratings, but I’d be interested in your take on how you see the overhang playing out.
Hi Peter, I just look at the overall prospects of each and compare. Things may take a while to play out while I get on with other investments.
I don't think it was covered unless l missed it, not all the 10 shares were covered. Some others were.
I think they ran out of time. Would have liked to have more info on the chosen 10.
Yes, the top 10 came near the end. I do hold a few of those already. Sold Yu (LON:YU.) a while ago when it was over 1900p.
I have just downloaded the report on the top 10 and it answers all the questions.
Hi Silver Moon. Link to the pdf download. Ithaca at the end: TopStocks-April2026.pdf
Hi Peter T.
Thanks for linking the pdf. Is that something that gets released every month? If so where can I find it?
Thanks in advance
Hi JamesS. No, it was issued by email to accompany a webinar Ed and Graham did last night. I assume it was issued to all those who signed up for the webinar. The webinar was recorded so is probably on Stocko somewhere but I've included a link below.
10 Results Season Opportunities
Cheers Peter T, your link was a good read and can be saved in my desktop. The reason I sold Ithaca Energy (LON:ITH) is that the share price seems to be peaking, surely it can't rise a lot higher although the dividend is useful. I try to buy low and sell high, Ithaca gave me 100 % in one portfolio, a 112% return in a second and Harbour Energy (LON:HBR) fits my buy low strategy, sort of. As they say, there's nothing wrong in taking a profit, god knows I've taken plenty of losses. Sentiment plays a large part in the stock market, gut feeling plays a large part in my own investing so we'll see how it goes.
Both ith and hbr set for fste100 entry in june with house builders departing
That's interesting davidallen, a Sunday morning going-over Mark Simpson's screen of the 15th for cheap growing companies throws up Ithaca and Harbour to appear as two peas in a pod:
I remain convinced in my choice, I could have sold one of my dogs to add to Harbour but it's better to crystalise a gain than to crystalise a loss.
Thanks Yadi - it was fun. We want to do more of these.
Apologies as in the slides presented there were a few market cap errors ! We have updated the slides attached on the webinar page though. https://www.stockopedia.com/ac...
Sarah Breedon deputy governor at The Bank of England has said the markets are too high at the and are set fall. However, she declined to say when or how far the markets will fall. When the market, at the moment needs a calming influence. These comments are not helpful, especially as they are vague in nature.
Indeed - predicting markets will fall 'at some point' reminds me of the Roger Bootle criticism, namely that he successfully predicted 15 of the last 4 recessions.
That said, markets seem to be in denial about the (very low) probability of a quick resolution to the ME crisis, so Breedon has a point.
She made no reference to the Middle East. The article is on the BBC.
The last line of that BBC article: "I'm not saying it will happen today, tomorrow, in 12 months' time. It's ensuring that if it happens the system is resilient."
So for now, business as usual?
an economist/bank governor making a prediction? must be a day ending in y
an economist/bank governor who has never ran money or investments making comments about the stock market? must be a day ending in y
and so on and so on!
One explanation for apparently high stock markets could be they are discounting an expected bout of inflation. In other words, telling us not that stocks are cheap but that today's money is expensive.
BRCK (LON:BRCK)
Ok this company has managed to do everything that annoys me all in one update.
I just want simple clarity not a bunch of jumbled up words (pot kettle black perhaps?).
What do they expect year end profit will be ? How does that compare with expectations and what’s the score entering the new year compared to where we were before today?
Reading the update I haven’t got a scooby do - or even a shaggy or scrappy do either.
I can’t even work out whether they want to say they have met expectations or they haven’t ?
If company is talking gibberish I have to presume it’s not a great update - so over to the brokers to see where the hatchet falls - this gets a nil points from me.
The once thing they did update on is the net debt - that’s down a smidge - is a smidge enough for a company making 50 mill ebitda - one would need to see the year end financials - pretty sure there are some chunky deferred acquisition payments still to be made - imho the company does need to evidence that it it’s making some decent profits where customers are paying - imho quoting ebitda is meaningless nonsense to help me work out the all important bottom line.
No sign in pick up yet ref stuff that is slow going due to stuff beyond their control.
You are right! Not sure what the current situation is withBRCK (LON:BRCK). Revenue is in the right ballpark, but the use of EBITDA muddies the waters.
If it gets close to expectations it will be a good outcome given the performance of its peer group.
I also don't like it when companies fail to give a clear trading statement, rmillaree, but I think on this occasion the criticism is misplaced. The very first line of the trading update says "Revenues and profits ahead of prior period and in line with market expectations". You also get a revenue number and EBITDA, as well as the debt.
What should alarm investors more, I think, is that management failed to provide sufficient information to Atlas to enable them to undertake full due diligence. Maybe there are good commercial sensitivity reasons for this, but I would be concerned that management is hiding skeletons in the cupboard.
BRCK (LON:BRCK)
"Revenues and profits ahead of prior period and in line with market expectations".
ok when they say profits - what profits do you think they are referring to?
imho they only mention ebitda in this update - ebitda can be a highly nonsensical figure - you can chuck almost anything in below that line.
i want confirmation the adjusted/underlying profit is x and it would be nice to have some useful comments ref how much they have blown this year on non underlying expenses - or confirmation that overall they are on track to meet brokers forecasts ref bottom line numbers - those forecasts exist and have been sidestepped.
Note it would have been super super easy to cross reference expected underlying profits like most sensible companies do - the notes at the bottom of the page confirm the yardsticks being used and there is no reference to anything other than ebitda.
look at creightons yesterday - they had no prpoblems referencing the real world profit figures rather than the nonsense that is ebitda.
do you seriously want your company managers to live in an ebitda only world - i for one dont as it aint real and thats why most sensible companies dont use ebitda only. Is it an increasing trend being part of the ebitda only univerrse? - perhaps - thast just sad on any level though if they completely sidstep the real bottom line figures till we are 4 months past the end of the year and then we find out that £5 mill has gone down then pan on dubious exceptional costs of reorganisation.
Note i am not a conspiracy theorist here - i have no reason to believe they are specifically hiding anything - its just if you dont have anything to hide why hide it - if other companies can cross reference real bottom line numbers imho there is no excuses.
What should alarm investors more, I think, is that management failed to provide sufficient information to Atlas to enable them to undertake full due diligence.
i kind of share your concerns - do you think they should give full access to their inner secrets though before formal bid has been made ? i agree its not a great position at face value - but i really dont know enough to know whether this should be re flag or whether the board are rightfully not wasting their time on possible chancers. On the balance of probabilities bearing in mind debt aint really coming down despite decent profits being made - i would agree that its potentially a red flag. based on where shareprice was before bid update imho the offer wasnt terrible and certainly valued the company materially more than the market. Until deal is done though we dont know if it would ever have happened anyway.
Fair points. I absolutely agree about EBITDA vs actual profits and, like you, I pay much more attention to the latter . I suppose I have just got so used to companies using the EBITDA measure that I don't notice when the underlying profit number is missing from a trading statement.
Also agreed that any comments on why Atlas thought they were being given insufficient information are pure speculation, but whatever the reason it is still unsatisfactory.
There is "highly extensive, accelerating, and transformative" (Google AI words) consolidation among building materials suppliers in the US which Europe/UK has still to catch up with. I think this provides useful context as to why there was a bid now and why management rejected it.
In terms of valuation for an acquisition I think EBITDA makes sense as the interest will driven by the acquiring group accounting policies/strategies as will DA and probably the T too :)
Probably worth 6-8x EBITDA based on other sales (Google AI) compared to 4x for FY26/FY27......so I can see why management are holding off.
The Beeb reports this morning:-
"Stock markets are too high and set to fall, says Bank of England deputy"
Pinch of salt?
The BOE is only saying this because everything else is suffering and would like the agony shared around.
They possibly meant to say "interest rates are expected to go up" , "inflation is expected to go up", "growth is expected to go down" (all mostly true) and so its stating the obvs....
... but never forget its the bank of england, run by economists. It has an immense power to get predictions wrong.
Bizarre comment for banker to make. Maybe inexperience. Or maybe she is learning from The Donald and has taken out a CFD on the FTSE100 prior to making her statement?
Argh, I would have liked to watch the webinar, but glad that several hundred were able to. I don’t recall seeing the invite, so I can only assume I missed it on route.
Sod's Law meant I missed it too, my wife being brought home by ambulance a day early than expected at precisely the wrong time in the day. Still, Oliver will let us know when the recording of the webinar is available.
It is already available, l watched it last night, as l missed it, live.
I wonder if I could ask a favour Rusty2, and that is if you could ping the link out here as a catchup works for me, but I just can't seem to find it. Thanks in advance.
Did you not get an email? Your replay.
Here is a link: https://www.stockopedia.com/ac...
No, no emails. I appreciate the link (thank you).
At the bottom right of the home page (see pic) is a list of all/any upcoming webinars. If you click on the the link 'See All', you will end up on a page that has links to all previous webinars, including last night's.
I've suggested to Sam at Stocko he might want to post the links to the recording on the DMSR.
its on stock youtube channel
Computacenter (LON:CCC) not a lot of detail in the RNS, but it did contain the following words, "comfortably ahead of expectations".
I had to read it twice to check I hadn’t missed the numbers. A trading statement without any figures! One assumes only the brokers will get the numbers.
They also said "significantly ahead of the prior year and well above our expectations".
Hi Graham. Thank you for last nights webinar. Much to think about.
BRCK (LON:BRCK) several announcements late yesterday including the termination of takeover talks and a trading statement from the company. Will you be talking a look?
Morning Revs8 - sure, I'll cover that one! G
The webinar was excellent. I did wonder what are your favourite screens for signposting further value analysis? I like Keller (LON:KLR) a lot in the concluding list
Thanks djlcollinge! I've been a believer in the Magic Formula by Joel Greenblatt for many years. The silly name only adds to the charm!
Thanks for the response Graham. Learnt so much last night. Have a great holiday.