Daily Stock Market Report (Fri 24th July 2026) - RSW, FNX, TSTL, MGNS, WISE, VCP

Tariffs are back on the agenda, with the Trump administration imposing them very widely - to its top 60 trade partners.
The Supreme Court struck down Trump’s dramatic initial set of tariffs last year; the new ones are more modest at 10%-12.5%. The UK is included in the long list of countries affected.
Countries that prove they are successfully prohibiting the importation of goods produced with forced labour will be subject to the lower 10% rate, while all others will be subject to 12.5%.
Canada has received special treatment, but not in a good way: earlier this week, it learned that many of its goods would face a 50% rate (including wine and hockey sticks).
Tesla missed earnings forecasts last night, and its stock fell 14.5% (a big number for a trillion dollar company!).
The FTSE is down 0.3% at 10,600
S&P 500 is unchanged at 7,400
Brent crude (October) is down 0.8% at $93.50/bbl
Gold is down 0.6% at $4,030/oz
Bitcoin is up 0.3% at $65,300
Spreadsheet accompanying this report: link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
HSBC Holdings (LON:HSBA) (£262bn | SR74) | HSBC agreed to sell HSBC Life (Singapore) Pte. Ltd. to Allianz for S$2.7 billion (US$2.1bn). | ||
Antofagasta (LON:ANTO) (£35.7bn | SR75) | As of yesterday, Los Pelambres has resumed operations and the Group's full year production guidance range remains unchanged. | ||
Reckitt Benckiser (LON:RKT) (£31.4bn | SR85) | Agreed to divest its Russian Hygiene business to Arnest Management LLC. Russia Hygiene represented c.1% of Core Reckitt's Net Revenue in the year ended 31st December 2025. | ||
Wise (LON:WISE) (£11.2bn | SR54) | SP -7% U.S. Office of the Comptroller of the Currency decided to deny Wise's application for a national trust bank charter at this time. | GREEN = (Graham) [no section below] It took Revolut five years to get a UK banking licence. During that time, the business evolved very significantly and it gradually learned how to navigate the regulatory environment. During this time, regulators also learned to trust Revolut. The same I suspect may eventually be true of Wise in the United States: it will grow and mature, and learn how to navigate banking compliance (especially anti-money laundering). Its management teams will also evolve and be better-equipped to earn the trust of regulators such as the US Office of the Comptroller of the Currency. Today's news is a setback to rapid growth ambitions, but does not affect any of the company's existing licenses. | |
Renishaw (LON:RSW) (£3.6bn | SR71) | Record quarterly revenue in Q4 of approximately £243m, 27% above the prior year and 18% above Q3. FY2026 adjusted operating profit to be approximately £152m and adjusted profit before tax to be approximately £167m, 31% above the prior year. | GREEN ↑ (Graham)
On balance, I’m fine with upgrading our stance on this to fully GREEN today. It’s certainly expensive and if I was looking purely at valuation, I’d leave our previous AMBER/GREEN stance unchanged. However, in StockRank terms, it's a High Flyer, which on average is a winning style. It has a MomentumRank of 97, and has just raised its guidance for the second time in a row. EPS forecasts have been trending upwards for a year. So on the basis that “the trend is your friend”, I’ll put us GREEN on this for the time being. When performance has stabilised again, I’ll probably want to take us back to a more measured positioning. | |
Burford Capital (LON:BUR) (£685m | SR13) | ICC International Court of Arbitration tribunal issued an award in favor of one of Burford's counterparties in an amount exceeding US$600 million. If the award were to be paid in full today, Burford's entitlement would be more than AUD$250 million, with all of the return accruing to Burford's balance sheet and no participation by Burford's investment funds. The case remains subject to significant litigation and collection risks. | ||
Discoverie (LON:DSCV) (£677m | SR58) | The strong trading momentum experienced in the fourth quarter last year continued this Period with Group orders up 31% organically and Group sales up 6% organically with a book to bill of 1.15. The positive outlook continues with full year adjusted earnings tracking ahead of the Board's expectations. | ||
Victrex (LON:VCT) (£632m | SR95) | On 31 July 2026, Ian Melling will step down as Chief Financial Officer and as a member of the Board. An orderly transition is underway. | ||
Team Internet (LON:TIG) (£110m | SR40) | Trading for H1 2026 was in line with market consensus. Revenue $179.1m (H1 2025: $263.9m). Adj. EBITDA $19.5m (H1 2025: $24.6m). | ||
Victoria (LON:VCP) (£83m | SR52) | SP -10% Underlying revenue down 6% (volumes down 9%). Underlying EBITDA £92m (FY25: £114m). Underlying operating profit £7.3m (FY25: £29.5m). Statutory operating loss £153m after impairments, provisions, etc. “The Board remains conscious of macroeconomic factors outside of its control and therefore we currently expect to deliver at least £115m EBITDA in FY2027.” Net debt £1,063m. | RED = (Graham) [no section below] Management have put their best foot forward today with impressively-written commentary, but I believe that ownership of this company is going to end up in the hands of its creditors, one way or another. The recently-announced refinancing transaction was very positive for the equity, in the sense that it saw owners of preferred shares accept conversion of their preferred shares into equity at an enormous (400%) premium to the share price. Senior secured noteholders (maturing in 2028) have also agreed to extend their notes out to 2031 and to take some equity. When the lenders are being forced to compromise, it follows that the equity is deeply compromised. Fitch gives Victoria a credit rating of CCC-. | |
Home Reit (LON:HOME) (£76m | SR22) | Smith Square Partners LLP this week issued proceedings regarding a purported unpaid contractual debt of £1,623,600. HOME intends to vigorously defend the Claim. | ||
Aoti (LON:AOTI) (£70m | SR39) | Centers for Medicare & Medicaid Services has indicated that topical oxygen therapy is reasonable and necessary for the treatment of diabetic foot ulcers that have failed to heal. Will finalise this determination within a year. This will dramatically expand the US addressable market. | ||
Nexteq (LON:NXQ) (£28m | SR76) | H1 trading was in line with management's revised expectations and the outlook for FY26 remains unchanged. | ||
Neo Energy Metals (LON:NEO) (£25m | SR24) | 70%-owned South African subsidiary, Neo Uranium Resources Beisa Mine Proprietary Limited, has signed a site access and contractorship agreement with Sibanye Gold, granting Neo Energy access to the Beatrix 4 Shaft Mining Area to begin a fully funded assessment programme. | ||
Kendrick Resources (LON:KEN) (£25m | SR15) | SP +8.5% “Continuity of mineralisation over impressive mineralised widths and associated excellent grades remains a key feature of the TK carbonatite complex. We will continue drilling with three rigs with the aim of generating sufficient data to produce a mineral resource estimate for TK in the shortest possible timeframe.” |
Backlog
Fonix (LON:FNX)
Up 8% this week at 169.7p (£166m) - Graham - AMBER/GREEN =
Thank you for the requests to cover this one.
It’s not one that I usually look at. The last time was in July 2025 (share price around 210p), when I lowered our stance on it to AMBER/GREEN on the basis that it had reached a high P/E multiple (20x) and had also slightly missed estimates.
The company provides messaging and payment services to major media organisations and charities, and to various digital services. It says it is “the largest SMS and Carrier Billing mobile aggregator in the UK”.
One of its major contracts is with ITV, providing live services for I’m a Celebrity, Love Island, Britain’s Got Talent, etc. It’s also active now in both Portugal and Ireland, and is making efforts for future full launches in Switzerland and France. Another unnamed country is targeted for launch by the end of FY27.
Some key points from yesterday’s trading update for FY June 2026.
Gross profit and adjusted EBITDA “slightly ahead of market expectations”
Adj. EBITDA +11% to £16.2m.
Total payment volume up 8% to £303m.
The “large majority” of revenue is of a recurring nature.
Dividend: the dividend will be increased to pay out at least 75% of adj. EPS, in line with their dividend policy, but the exact amount is not confirmed yet. A £2m share buyback was carried out in May.
Outlook:
Fonix enters FY27 with positive momentum across its core UK and Ireland markets, and an expanded international footprint from which to accelerate growth….
Product innovation remains a key driver of growth. The Board anticipates a significant ramp-up in RCS [GN note: rich messaging] activity from the end of H1 FY27, alongside continued rollout of PayFlex [GN note: an SMS-based payment service]...
With five international markets now live, piloting or in build, and an accelerating product roadmap, the Group is building strong momentum for future growth, and the Board looks to FY27 with real confidence.
Estimates: the RNS helpfully lets us know that market expectations for gross profit and EBITDA were £20.5m and £16m, respectively.
At Cavendish, there were small upgrades to FY June 2027 and FY June 2028 estimates on the back of this update:
Gross profit estimates raised by 2% (FY27 £22.8m, FY28 £25.2m).
Adj. EPS estimates raised by 3% (FY27 12.4p, FY28 13.8p).
Graham’s view
The stock is trading at around 14x current-year earnings, which I think is fair for the business in its current state.
While it does earn extremely high returns (ROE, ROCE, etc.), this is a sector where providers are typically reliant on a small number of relationships with major customers. The most recent annual report from Fonix said that 3 customers provided more than 10% of revenues. Perhaps a reader has more detailed information than this, but that fact alone says to me that it’s fair to note the potential for very high customer concentration.
I previously owned shares in a much less successful Irish premium SMS company, Zamano, which later went bust after regulations changed and disrupted its business model. So I do know from experience that this can be a tricky sector for a variety of reasons. Technology and regulations change quickly, providing both opportunities and risks.
All of that being said, Fonix is an example of a company succeeding in the space and the real wildcard is international expansion: if it succeeds in France, Switzerland, Portugal, etc., then it’s clearly going to be worth a lot more than it is today. Growth will also help to reduce the customer concentration risk that exercises me so much.
So I’m staying AMBER/GREEN on Fonix today. Fairly priced for now, in my view, perhaps even a little cheap, with upside available if its growth ventures succeed.
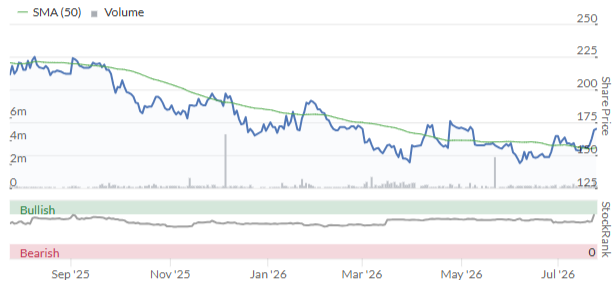
Tristel (LON:TSTL)
Up 4.5% this week at 397.1p (£191m) - Positive Trading Update - Graham - AMBER/GREEN =
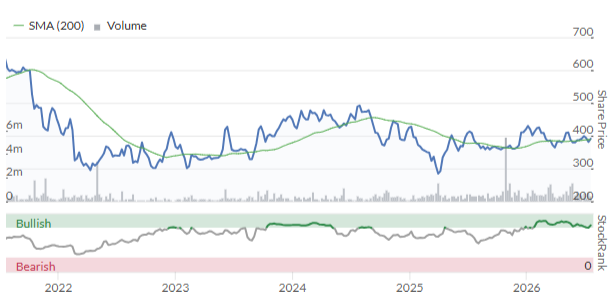
This has been an important stock for many private investors over the years, as it multi-bagged for those who got in early enough.
It has stalled over the past five years, however:
The company manufactures its own disinfection solutions for healthcare settings (medical/pharma).
This week’s “positive trading update” for FY June 2026 was… positive:
Revenues up 10% to £51.1m (FY 2025: £46.5m)
Adjusted EBITDA margin remains comfortably above the 25% target
14% growth in adjusted profit before tax which is expected to be no less than £11.5m, marginally above market expectations (FY 2025: £10.1m)
The company’s cash balance rose by a few million pounds during the year to £16m.
Interim CEO comment:
We are delighted to deliver another year of significant growth with strong demand for our infection prevention products globally.
"We continue to meet our performance targets of delivering double-digit revenue growth each year, and maintaining adjusted EBITDA margins of at least 25%. We remain debt-free, cash-generative, and confident in our ability to continue to sustain this momentum in the years ahead.
"We are very excited to welcome our new CEO, Chris Lee, to the Company on 1 August, and we look forward to his contribution to the business as we drive further growth and overseas expansion in the new financial year."
The previous CEO left to take up the prestigious-sounding role of President at a US multinational.
New CEO Chris Lee joins from a medical device manufacturer based in the Cotswolds. His career background includes 18 years at Johnson & Johnson.
Estimates: thanks to Singers for covering this one. The adj. PBT result is 4% ahead of their estimate, “consistent with a company that has built a track record of underpromising rather than delivering dramatic upgrades". Sounds like Tristel has been managing expectations very sensibly.
Consistent with that idea, EPS forecasts have been very stable:
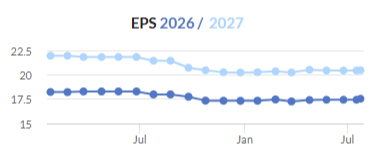
Singers have left their earnings forecasts unchanged:
Revenue: FY June 2026 £56.2m, FY27 £61.4m.
Adjusted PBT: FY June 2026 £13m, FY27 £15m.
This implies revenue growth of 10% in the current financial year, with adj. PBT growth slightly stronger at 13%.
Graham’s view
It’s difficult for me to criticise any aspect of the performance of Tristel, but it’s equally difficult for me to get too excited. Disinfectant is not supposed to be exciting, I suppose!
Stockopedia’s computers like what they see, calling it a High Flyer:
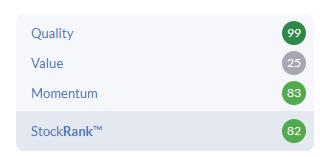
The company has recently started expanding in the United States and while the total sales figure there is still just 1% of the company’s total, that does provide an interesting growth opportunity that has been highlighted by the company.
Roland was AMBER/GREEN on this in March when the market cap was almost identical to what it is today. On balance, I'm inclined to leave that unchanged today.
It is a little expensive, but it has the performance and the prospects to back that up.
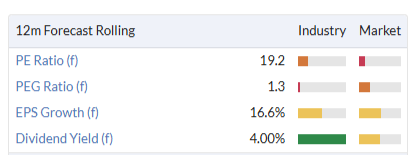
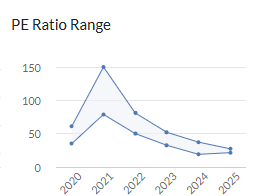
The explanation for why the share price has stagnated for the past several years is simple once you look at the historical P/E ratio: it was overheated, and needed some time to grow into this valuation, which it is still doing. Perhaps the share price is almost ready for the next leg upwards?
Morgan Sindall (LON:MGNS)
Down 4% this week at £45.28 (£2.2bn) - Interim Results - Graham - GREEN =
I turned GREEN on this construction stock in April, after a "significantly ahead” trading update..
Yesterday’s H1 results maintained those higher expectations:
Record first half results and remain confident in maintaining current expectations for 2026
Highlights:
Revenue +8% (£2,562m)
Adj. PBT +21% (£116.1m)
Actual PBT +22% (£116.1m)
Very clean results, in both H1 periods this year and last year, is a huge green flag for me (and I think unusual in a complex sector such as construction/regeneration).
Comment by CEO John Morgan:
Our Fit Out and Construction Services businesses delivered excellent results and made a significant contribution to Group performance during the period, while our Partnerships businesses faced a more challenging macroeconomic environment.
The medium-term fundamentals for Fit Out remain strong and in Construction, we have continued to benefit from ongoing government investment commitments. As a result, we have increased the medium-term targets for both the Fit Out and Construction divisions.
Despite the challenging housing backdrop, the strength and breadth of our diverse operations, together with the visibility provided by our high-quality order book for the remainder of the year, we remain confident that our full year performance will be in line with our current expectations.
The divisional breakdown confirms terrific strength in “Fit Out” and “Construction”, while “Partnership Housing” went in the other direction:
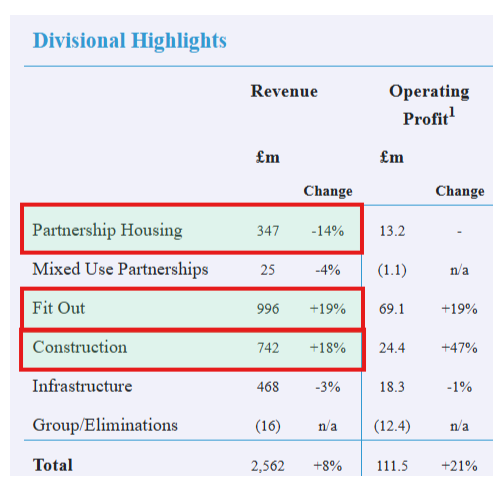
It’s very much a tale of three divisions, as there are some significant positive changes in the medium-term expectations across two of them, while Partnership Housing experiences some temporary difficulties:
At the midpoint, Fit Out’s medium-term operating profit target has increased from £90m to £115m.
Construction now has an operating margin target of 3.5% to 4% (previously 3% to 3.5%)
Partnership Housing is now expected to see “slightly lower” operating profit this year, compared to last year (actually I’m impressed that profits haven’t fallen more, considering the dropoff in revenues).
Looking for an explanation of the drop-off in Partnership Housing revenues, I find:
During the first half of the year, challenging economic conditions continued to prevail within the private housing market, adversely impacting consumer confidence. Despite this, the division continued to invest and develop its long-term partnerships with local authorities and housing associations…
Demand for contracting with the public sector remained strong and continued to represent two thirds of the divisional revenues in the first half of the year, partially mitigating the impact from lower open market sales within mixed-tenure activities.
It’s clear that the result would have been much worse without the company’s public sector exposure, offsetting the weakness in the private housing market.
Outlook: in line, as stated at the top.
Looking ahead, as each of the Group's standalone businesses experience varied conditions in their end markets, the strength and breadth of the Group's diverse operations, together with the visibility provided by its high-quality order book for the remainder of the year, the Group remains confident that its full year performance will be in line with its current expectations.
Graham’s view
This is not the type of stock I’m drawn to, but I think I need to stay GREEN on it for the time being.
EPS forecasts are moving in one direction at the moment:
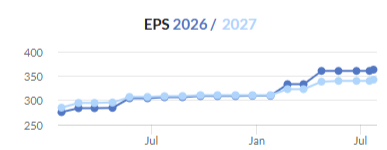
But what also stand out for me are the very clean accounts, the net cash, and the diversification across a range of construction-related activities.
Additionally, its exposure to public sector spending is serving to partially protect it from economic turbulence.
This is another stock which I do not consider to be at “bargain” levels. But there is enough business momentum and there are enough positive features, to keep my GREEN stance unchanged for the time being.
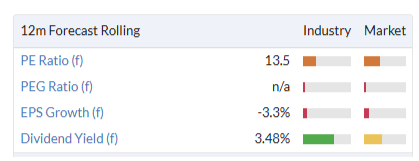
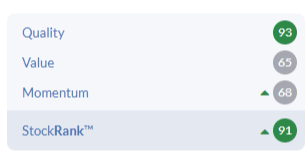
This is consistent with Stockopedia’s calculations, which give it a StockRank of 91 and call it a Super Stock.
Graham's Section
Renishaw (LON:RSW)
Up 6% at £52.30 (£3.8bn) - Trading Statement - Graham - GREEN ↑
The last time we looked at this was an upgrade in April.
We summarised the news then as follows:
Upgrade to FY2026 guidance: now expect revenue of £775m to £805m and adj PBT of £145m to £165m (previously £740 to £780m & £132 to £157m).
Today’s update continues the good news:
We saw accelerating growth throughout the year, culminating in record quarterly revenue in Q4 of approximately £243m, 27% above the prior year and 18% above Q3. Demand remained strong from customers in the semiconductor and electronics manufacturing equipment sector, and from the aerospace and defence sector.
New revenue guidance is £815m (up 14% from FY25). This is above the top end of the range given in April.
New adjusted PBT guidance is £167m, also above the top end of the range that was given, and up 31% from FY25.
Graham’s view
Renishaw is “a global provider of manufacturing technologies, analytical instruments and medical devices.” They help customers “to measure and manufacture with greater precision and efficiency”.
Engineering is not really my area of expertise, and it’s difficult to summarise Renishaw as they have offices in so many locations: 36 countries.
What is clear is that their exposure to certain rapidly growing sectors is paying off handsomely at the moment. It looks to me as if Renishaw is a downstream beneficiary of the tech boom: not an AI stock in its own right, but a company that does well when there is very high hardware demand.
One feature that stood out to me in today’s guidance was that adj. PBT (£167m) is higher than ad. operating profit (£152m). This usually signals a strong balance sheet, and my suspicions are confirmed when I check the half year report: the company reported cash of £241m, with negligible borrowings.
Some more positives:
Fully organic growth, no acquisitions needed.
Results have been reasonably clean; there were some adjustments in H1 this year but the prior financial year saw adjusted PBT of £127 convert to actual PBT of £118m.
On balance, I’m fine with upgrading our stance on this to fully GREEN today.
It’s certainly expensive:
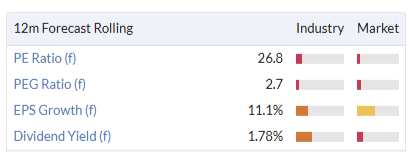
If I was looking purely at valuation, I’d leave our previous AMBER/GREEN stance unchanged.
However, in StockRank terms, it's a High Flyer, which on average is a winning style. It has a MomentumRank of 97, and has just raised its guidance for the second time in a row. EPS forecasts have been trending upwards for a year:
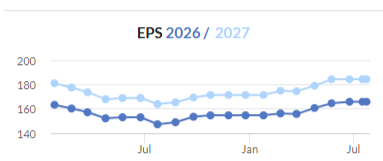
So on the basis that “the trend is your friend”, I’ll put us GREEN on this for the time being. When performance has stabilised again, I’ll probably want to take us back to a more measured positioning.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

40 comments
Victoria (LON:VCP)
It has all the traits of being run by an ex Investment Banker.
As Ernest Hemmingway said when asked how did he end up Bankrupt? His reply: 'Two ways. Gradually. Then Suddenly!'
The old question about Wall St was: 'Where are all the shareholders yachts?' I suspect Geof is one of the few Victoria (LON:VCP) shareholders who has one.
Hi guys, I watched the webinar on Stock jumpers yesterday. Thanks.
The irony is that the only 'stckjumper' today was Morgan Sindall (LON:MGNS) 77 - 91 and it dropped 5%!!!
Have a good week-end all.
Looking at the Stockport it appears MGNS has been in the 90's for a long time? (albeit it might have dropped to 89 and then jumped to 97 in a single day).
What are you talking about ??? 22nd July stockrank 77 - 23rd July stockrank 91
IG group (LON:IGG)
One of the best platforms where you could ask, get a quote and filled immediately…….now it’s completely gone.
Another setback for UK stocks!
All the best
IG group (LON:IGG)
Any IG users here, I can't get a sell quote on anything although able to put a limit order in???
Same. But on the buy side trying to buy Yu group. I think it's the way the free trading apps are going. As T212 is similar. You place the order and don't get a quote and it goes through when it goes through. Small caps can take all day sometimes.
I know it is yesterdays news but there was a trading update from Tristel (LON:TSTL) that slipped through. Revenues and profits up again 10% - with the growth coming from international sales (US?). The brokers (thankyou Walbrokpr) seem to like them too. Current price £4.00
Cavendish view: (BUY, TP: 560p) Cavendish remain positive on Tristel, noting significant growth opportunities, particularly in the US, that are expected to support continued double-digit revenue growth and strong margins. They believe the current c4% dividend yield is attractive, given the expected growth and profitability of the company.
Singer Capital Markets view: (BUY, TP: 477.1p) SCM leave their P&L forecasts untouched but roll forward the cash beat. They lift TP to 477, offering ~30% TSR upside from current levels. With the group still debt-free, compounding at double digits, and about to hand the CEO baton to Chris Lee, they view this as a reassuring update.
Investec view: (BUY, TP: 504p) Investec continue to expect sustained demand for Tristel's innovative device disinfection products, which they view as offering an attractive combination of superior user-friendliness, sustainability and cost efficiency. Investec reiterate their Buy rating.
Stifel view: (BUY, TP: 460p) Stifel forecast +12% growth for FY27 with continued operational leverage driving +16% Adj.PBT growth supporting 28% Adj.EBITDA margins. Overall, they continue to like Tristel's profile as a high-quality compounder seeing the current 17.5x FY27 PE as undemanding. They reiterate Buy.
Thanks for mentioning it, I decided to add Tristel to the report. Cheers. G
Growth at Discoverie (LON:DSCV) caught my eye. I hold. Orders up 36% - wondering if the growth is not AI data centre related. If it is, the share could fly as the next 2 year's growth is already baked in, especially so if it gets the attention of AI meme gang.
Sadly it looks as though Wise (LON:WISE) is making life too difficult. The timing of today's news isn't great with the investigation still an overhang. In the meantime the fundamental results were good enough to see the shares spike 15% and for a while I was thinking the market was over the fuss. Maybe todays news is also not much to worry about but it doesn't help and leaves Wise (LON:WISE) failing the sniff test and it would be no surprise to anyone to see more regulator interference...which may cost them margin. Time will tell but I move on for now....
Wise (LON:WISE) will be able to buy back more shares (at the lower price) in their recently announced buyback. Every cloud and all that!
Wise (LON:WISE)
Sadly it looks as though Wise (LON:WISE) is making life too difficult
100% agree
would i be correct in thinking that they had these Multi-State Consent Order issues whilst having an active application for a licence - i am no expert but looking on from the outside when you apply for a banking licence surely you want to be seen to be cleaner than clean with regard to "what we have been doing recently" - ok i get it that one perhaps still proceeds on hope it will be overlooked if you are righting teh ship - but i would kinda expect - if you arent up to scratch - you withdraw your application - you put your house in order fisrt and "evidence that fact" you then reapply so that you have the proof you are doing it right at teh time you apply - rather than tring to say highlighted failures should be overlooked.
It cant help that they are also being prosecuted in Belgium for money laundering offences.
I very much get it that its inherent in their activities that they will have a hard job keeping clean and lean at the same time - thats the problem though it aint easy to keep it clean and lean - wise are very much evidincing that right now.
Even if you look at the following text - its somewhat surprising the fed would ever have given direct access in the fisrt place to an unisured trust bank - i know no detail but i find it hard to believe they have been particularly hard done by here by recent charges
Our original application was conditioned on obtaining direct access to master accounts at the Federal Reserve. With the Federal Reserve generally pausing account access for an uninsured trust bank
thats without mentioning then US kinda like to look after their own dont they - Wise may now be a listed US company - but i would kinda expect that the sort of corrupt way things work in the US wont aid them. perhaps a conspiracy too far
Wise (LON:WISE)
Having spent a fair bit of time reading around this yesterday evening, my current view is that the picture is more nuanced than the initial headlines suggested.
The OCC rejection appears to have been driven by a combination of historical AML/compliance concerns (including the 2025 Multi-State Consent Order) and an application that was submitted over a year ago, rather than any immediate operational issue.
Wise has since invested heavily in compliance, although regulators understandably need evidence over time that those improvements are embedded before extending further trust.
Operationally, nothing has changed.
Customer growth, volumes, holdings and revenues all remain very strong, and the existing licensing framework continues to support the business.
The more I read, the more I think there are really two separate questions:
The Belgian investigation remains the biggest uncertainty for me, because its eventual outcome will either reinforce or undermine the narrative that Wise has genuinely “grown up” from a compliance perspective.
A couple of analysts I respect remain constructive on the long-term business despite recognising that this is a genuine setback rather than a trivial headline.
My own conclusion is that this feels more like a delay to the destination than a change in the destination itself, albeit with a slightly higher execution risk than I previously assigned.
On that basis, I was comfortable adding modestly to my own holding yesterday.
Whether that proves to have been the right decision is unlikely to be apparent over the next few days or even weeks.
I suspect the next 12–18 months will provide a much fairer test, but based on the evidence currently available I felt the long-term risk/reward remained attractive.
WISE was looking for direct access to FED payment systems (Fedwire, Automated Cleaning, and FedNow). This is part a long-term programme to develop direct access to in-country local payment systems (a.k.a. Local Payment Methods LPMs). It improves transaction speed and reduces costs by cutting out the intermediary ('Correspondent') bank.
Denial will mean that they will not be able to reduce costs but won't adversely affect their competitive position. Their FY26 average take rate was reduced to 0.52%, and to 0.5% last quarter so already very cost competitive. A deliberate policy of price reduction to grow market share - that is driving their top-line growth, 31% FY26 but constraining their profit growth.
Just to clarify, the Bank of Belgium is investigating WISE not prosecuting them. This was due to a large number of inquiries from other country's Financial Intelligence Units amounting to an aggregated c. €0.5bn. This is 0.23% of their annual turnover $243 bn albeit we don't know over what period the crime inquiries were collated. As we know financial crime is rife and growing such that this is not out of line with market average fraud to turnover figures.
Mr Market is currently brutal on any apparent bad news, and I suggest that both these events are bumps in the road rather than of structural concern.
Impressive Q4 update from Renishaw (LON:RSW) this morning. Mostly down to uplift in orders from electronics industry customers. Looks as if next year estimates will be being upgraded. (I hold.)
Fonix (LON:FNX)
Morning Graham and team
I don’t expect that you will get an opportunity but should you do so I would be interested in your views on yesterday’s trading update. Not the easiest company to understand but it appears to be making reasonable progress exporting its technology to Europe.
All the best
Fonix (LON:FNX)
plus one for wanting comments on Fonix - the sotcky summary seems to make very pleasant reading on most points - looks like their has been decent in uptick on the back of this update in both eps expectations and the stocky ranking - is it heading for a fables green rating ? - outlook statement seems chipper enough.
perhaps the only issue is should we be expecting telecos to be trading on p/w of 13 plus ? - its not a sector where i would expect high ratings - in some respects though every sector will have companies that outperform the average so if they can grow profits organically at above inflation rates well thats enough innit whatever the sector.
I dont hold at present but on an initital glance it looks a fairly dependable company.
The Board remains confident in the Group's strategy and its ability to deliver sustainable gross profit growth and long-term value for shareholders. With five international markets now live, piloting or in build, and an accelerating product roadmap, the Group is building strong momentum for future growth, and the Board looks to FY27 with real confidence.
I would not have thought of Fonix (LON:FNX) as a telecoms co. It’s basically a tech/software provider that has successfully established itself in a niche (I hold).
Seconded
I reckon an overhang atm
Thanks very much for the request Jonno, FNX is now up! G
Thank you Graham.
Have just logged on and look forward to reading your views.
Best wishes
Cavendish have upgraded their EPS estimates for Jupiter Fund Management (LON:JUP) this morning from 11.6p to 12.8p for FY26 and from 14.6p to 15.7p for FY27.
But this is based on AuM only growing by 2.8% for the rest of the year.
Interestingly I've been looking into what caused the Jupiter Fund Management (LON:JUP) performance fee outperformance last year.
As a reminder, core profits actually fell last year due to their new pricing model. However, they had a massive boost from performance fees which were £120m in FY25 versus £30m in FY24. Cavendish don't expect such strong performance fees this year which is why this share is expected to have a lower EPS this year despite rising AuM. Clearly there's unpredictability around performance fees.
I checked the FY25 annual report and it looks like last year's performance fees were largely due to performance in its Global Equity Absolute Return fund (GEAR) which alone generated £95.7m in performance fees during the year (see image).
The fund achieved 16.6% return in FY25. It's currently up 3.1% YTD.
According to Jupiter's website, the GEAR fund performance fee is: '20.00% of any returns the Fund achieves above the average Bank of England Base Rate, provided the Fund’s share price is above the High-Water-Mark. A technical description of the performance fee can be found in the full Prospectus. The Performance Fee (if any), will crystallise, become payable at the end of each Performance Period ending on 31 December. If a Shareholder redeems all or part of their Shares before the end of a Performance Period, any accrued Performance Fee with respect to such Shares will crystallise on that Dealing Day and will then become immediately payable.'
So perhaps it's worth closely monitoring Jupiter's GEAR fund for any future performance.
Yes their GEAR fund is huge (about £9bn AUM last time I looked) and is really a hedge fund, with a market neutral strategy. I suppose that's why it's able to charge these huge performance fees. Performance seems to have been very good in recent years, if a little lacklustre this year. Definitely worth keeping an eye on this fund as it is clearly a key driver of JUP's profits.
Any thoughts on Victrex (LON:VCT) board clearout? Not often you see a new CEO booting out so many of his colleagues in one go.
Given the direction travel of the company over the past few years it's good to see such affirmative action by the new CEO. I wish him well.
The problem is, it becomes a binary result determined by the fortunes of the CEO. If he is good and lucky great, if he is bad and unlucky oops!
Seems there are quite a few Layer 8 errors today. All good here though :)
Working fine for me too, including RSW. VPN issue?
AI sourced valuation for Tesla. Massively over priced.
Automatic trading being led by the AI which escaped the sandbox? Oo-er!
site down again if you want to click into a company !! Pathetic
All working for me!
wasn't before had red banner come up and could not click into RSW
All working fine for me, apart from I have had an unwanted banner at the top of the screen on mobile for the last 2 days....laptop is fine ... anyone know how to delete please? Many thanks indeed
Working fine for me
It’s working ok here as well.
Impossible for me to do any research on here today. Becoming rather tiresome.