Daily Stock Market Report (Fri 25 April 2025) - PIN, EVOK, AGFX, OMG, MCG, REC

Good morning! We've reached the end of this four-day week.
I see that the S&P 500 is now only down by 5% year-to-date. A couple of weeks ago, it was down 15%. I'll chalk this up as a win for buy-and-hold!
President Trump has said that the current 145% tariff on China "will come down substantially - but won't be zero". I have my fingers crossed for a major U-turn by Trump, under pressure from many of his own supporters.
We are all done for the week, have a pleasant weekend!
Companies Reporting
Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
| WPP (LON:WPP) (£6.0bn) | Trading Update | Guidance reiterated. Q1 revenue less pass-through costs -2.7% LfL. Full-year guidance flat to -2%. | |
| Pantheon International (LON:PIN) (£1.26bn) | Monthly Performance Update | £20m of share buybacks so far, £50m allocated. NAV per share 501.2p, down 0.5% for the month. | GREEN (Graham holds) There's a small drop in NAV per share caused by currency movements. I've become a huge fan of this in recent months and am open to the idea of adding more. |
| Mobico (LON:MCG) (£362m) | Proposed Sale of North America School Bus | SP down 41% Upfront net proceeds £275-290m. Earn-out up to $70m. FY24 adj. op profit at lower end of guidance. | RED (Graham) [no section below] We haven't looked at this since November and unfortunately it has gone off the rails today. There is a mild profit warning on adjusted profits ("lower end of guidance"), a further warning that there will be "a significant statutory loss" for the numbers that aren't helped by adjustments, and a disappointing sale of the School Bus business vs. analyst estimates. £275-290m will be received for deleveraging but the outstanding debt pile was nearly £1bn as of the June 2024 interim results. Superficially this stock is cheap against EBITDA and adjusted earnings, but real profitability has been very difficult for the company to achieve ever since the Covid era. Given the dismal track record in recent years and the apparent continuation of this record, I'll slap this with a RED colour for the time being. |
| Evoke (LON:EVOK) (£216m) | Trading Update | Q1 adj. EBITDA significantly up y/y. Last 12 months adj. EBITDA >£330m, in line with guidance. | RED (Graham holds) The market is pricing in an equity raise and I don't disagree that this may be required. Evoke's debts start to mature in 2027 and then most of them fall due in 2028. |
Record (LON:REC) (£108m) | Expectations for full year revenues are unchanged. AUM up $0.4bn to $100.9bn. Net outflow $0.7bn. | GREEN (Graham) [no section below] As noted in January, I like this company even though its growth is very modest (if any). The slight increase in AUM in Q4 (to March), helped by exchange rates, masks some modest outflows. Performance fees remain small but continue to boost the overall result. With a strong, liquid balance sheet and an enviable track record of profitability, I'm a long-term fan here. References in today's statement to the company taking "no market or counterparty credit risk ourselves" are perhaps motivated by recent events at Argentex. The two companies have very little in common, despite both provide currency risk management | |
Oxford Metrics (LON:OMG) (£60m) | H1 in line. Revenue H2 weighted (“normal seasonal pattern”). Net cash £41m. | AMBER/GREEN (Graham to do) I think the glass is half-full with an impressive cash pile and continuing operations that have been profitable. It's all down to management to invest the cash wisely from here. | |
| Argentex (LON:AGFX) (suspended at £52m) | Update re: Possible Offer and Bridge Funding | IFX may offer 2.49p per AGFX share. Discussions at an advanced stage. "The most attractive immediate proposal for Argentex shareholders". £6.5m bridging loan at 15% included. AGFX CEO leaves the company with immediate effect. | NO COLOUR (Graham) [no section below] I don't see any point in putting a colour on this as the shares are suspended and there is little prospect of them trading again. Investors representing 58% of AGFX's shares have undertaken to support this potential offer and so it looks set to proceed if can get done before AGFX runs out of cash. AGFX shareholders have lost over 90% of value in a week, with effectively zero warning. This must go down as one of the most shocking collapses we've witnessed from a company that appeared credible. |
Naked Wines (LON:WINE) (£57m) | FY March 2025 in line. Rev c. £250m. Net cash £31m. FY26 guidance to be given in summer. |
Pantheon International (LON:PIN)
Up 1% to 278p (£1.27bn) - Monthly Performance Update - Graham - GREEN
(At the time of publication, Graham has a long position in PIN.)
I added this to my portfolio recently.
For reasons that aren’t very important (specific to my personal circumstances), but which I’d like to mention in order to help explain my decision to buy a trust, I was looking for an investment with the following characteristics:
Lower-risk than buying stock in a single business
Can still provide equity-like returns
For tax reasons, returns are to be generated through capital gains as much as possible, with as little income as possible.
I could have simply added more Berkshire Hathaway, but I already have enough of that. After a reasonable amount of searching, I decided to invest in PIP.
Pantheon International Plc (the ticker is PIN, but they refer to themselves as “PIP”) is a FTSE-250 investment trust, overseen by $55bn private equity firm Pantheon Ventures.
Income seekers can look away now: PIP has never paid a dividend and has no intention of ever paying one.
It has a net asset value of 501.2p per share or £2.3bn, according to today’s update.
However, it is currently trading at just 278p, with a market cap of £1.26bn. That’s a 44% discount!
Valuations are based on the numbers given by the underlying private equity managers to whom PIP has allocated funds. So it is reasonable for investors to be concerned that these valuations are uncertain.
The way I make sense of the valuation is 1) I check the average earnings multiple on which the valuation is based, 2) I check to what extent the portfolio is able to make sales at a premium to book.
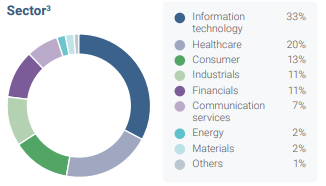
I think that on both accounts the stated net asset value appears pretty reasonable, although the impact of the recent trade fiasco on NAV is hard to quantify. 53% of PIP’s portfolio is in tech (33%) or healthcare (20%) with only 13% in consumer and 11% in industrials. My guess is that the first two of these sectors will do better in a high-tariff environment than the last two.
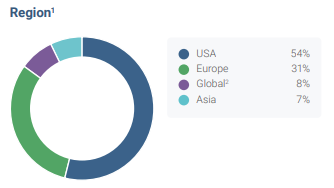
A slight majority of PIP’s investments are in the US:
I should do a deeper dive into PIP for you at some point in the future. For now, here are the highlights of today’s monthly update.
They start by acknowledging the discount:
The Board of PIP recognises that the discount on PIP's shares continues to be wide and this has been further exacerbated by market volatility.
They have allocated £50m to buybacks during the current financial year (FY May 2025), and £20m has been spent so far.
Today’s update shows a small (0.5%) drop in net assets per share for the month, primarily caused by foreign exchange movements which caused a 1.7% hit. Before currency movements, valuation gains were positive.
Balance sheet
PIP does use a small amount of leverage. Net assets as I’ve already stated are £2.3bn, but they have total private equity assets of £2.49bn. The ratio of net debt to NAV is 7.3%. Personally, I quite like this use of leverage. I think they can afford it, and it means that they never suffer any cash drag.
Diversification
Diversification is satisfactory: the three largest holdings in PIP’s portfolio are each worth a little more than one percent of the total portfolio. Everything else is worth less than 1%.
Diversification across PE managers is also pretty good: the manager with the largest percentage of PIP’s portfolio is Insight Partners, and they only manage 6.5%.
Graham’s view
I’ve become a really big fan of this in the last few months, and I’m open to the idea of adding more of it (it’s currently 4% of my portfolio).
I think it’s giving me access to a diversified range of high-quality private equity funds and private equity investments that have a good chance of providing strong returns, similar or maybe better than the major stock market indexes. PIP’s track record is 11.7% annualised NAV growth since 1987. The cherry on top is that the package is available at a very steep discount to NAV.
My own track record as a private investor is that PE-related shares have been my most successful investments. Volvere (LON:VLE) and Berkshire Hathaway (NYQ:BRK.B) have both been “baggers” for me, and are by far my largest holdings. Perhaps PIP can be the next one?
Evoke (LON:EVOK)
Down 1% to 47.4p (£220m) - Graham - RED
(At the time of publication, Graham has a long position in EVOK.)
This is a hair-raising situation where the company’s viability is seriously in question.
I gave it a RED in March, despite continuing to hold it as a stale bull. Its full year results were terrible, including huge losses and adjustments.
Even worse, the leverage multiple remained unacceptably high at 5.7x. Net debt was £2.1bn.
Today’s update strikes an optimistic tone. Here are some of the key points.
Revenue continues to grow at a modest pace, +2% at constant currencies. This is “in line with guidance” but the full year growth rate is expected to be “consistent with the mid-term target of 5-9%”. So improvement is expected and needed from here, in order to hit forecasts.
Adj. EBITDA last year was £312m, as the company beat guidance (which had already been upgraded) of £290-300m.
Today, the company says that Q1 revenue was “significantly higher year-on-year”, and that adj. EBITDA over the last 12 months is over £330m. This is also in line with guidance.
UK & Ireland online: I noted a very large fall in active players (-21%) as the company has dropped its previous marketing plans and focused on serving a smaller pool of more valuable customers. Average revenue per user is up 26%. Overall revenue down just 1%.
International: revenue +14% at constant currencies, boosted by an acquisition but seems to be doing well.
Retail (includes William Hill): revenue down 6%, some positive noises here:
The outlook for the remainder of the year is more positive with the roll-out of new machines completed together with the expected benefit of planned improvements across the sportsbook and overall in-store experience.
5,000 new gaming cabinets have been rolled out here.
CEO comment excerpt:
…While Q1 revenue was below our 5-9% annual growth target, Adjusted EBITDA is significantly higher year on year, with LTM Adjusted EBITDA reaching more than £330m. This reflects the Group's significantly more efficient operating model and our clear focus on creating value through sustainable, profitable growth.
…Whilst the UK&I Online and Retail performance was behind where we wanted to be in Q1, we have moved swiftly to improve some of the underlying drivers of the performance and have been seeing stronger trends in April…
Graham’s view
As I’ve said before, I probably should have sold this one already.
Overall, I agree with its StockRank categorisation as a Value Trap:
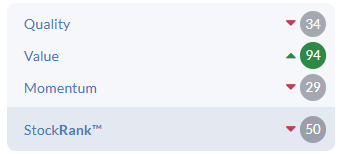
The notional P/E multiple of 3.3x is not real, given the plethora of adjustments that the company makes and of course the heavy debt load making this first and foremost a question of whether or not the existing equity can survive at all.
I still believe in the quality of the company’s assets: I like (and occasionally use!) the 888 online brand. William Hill is also a fine brand even if the quality of the retail business is no longer what it was. Mr Green also has a substantial audience.
So it’s a question now of whether adj. EBITDA can convert into enough real cash flow to start paying down the debt and achieve a reasonable leverage multiple.
According to the company’s current (downgraded) plans they are targeting leverage below 5x by the end of the current year, and then below 3.5x by 2027.
I have little faith that they can achieve this, but if they did then there is a good chance that the equity would be awarded a normal earnings multiple, and we’d see a substantial recovery.
The problem with being late in hitting their leverage targets is that it might cause trouble when it comes to refinancing. Their debt facilities start to mature in 2027 (€582m note) and then most of it matures in 2028. Their credit rating at Fitch is B+ (i.e. junk), with a negative outlook.
So the outcome here might very well depend on conditions in the debt markets in a few years - will banks and bondholders be happy to let them continue working away at this as they are, or will fresh equity be needed?
At the current market cap, investors are pricing in an equity raise and I can’t disagree that there’s a strong possibility this will be required.
Oxford Metrics (LON:OMG)
Unchanged at 48.4p (£60m) - H1 Trading Statement - Graham - AMBER/GREEN
Oxford Metrics plc (LSE: OMG), the smart sensing and software company servicing life sciences, entertainment, engineering and smart manufacturing markets, provides an update on trading for the six months ended 31 March 2025 ("H1").
We have a nice “in line” update today, although with an H2 revenue weighting that the company says is normal.
There is also pleasant news on the tariff front: they do not anticipate “a material impact” from tariffs at this stage.
Their motion capture technology is used in the life sciences sector, in entertainment, VR, etc, and they also have a new “smart manufacturing division”. Here is the update on business:
Momentum during the first half has continued across both divisions. Vicon secured new contracts across all main markets and in March, launched markerless motion capture. Vicon Markerless empowers creative and previsualisation teams to bring ideas to life with greater speed and ease than ever before. The build out of our smart manufacturing division has progressed with a number of new contract wins and the appointment of a new managing director, Dr Simon Gunter, to drive forward initiatives to capture more of this growth market.
Graham’s view
The major question - as highlighted by Roland in a brief section in February - is what the company might do with its cash pile. Today’s update informs us that this currently stands at £41m.
One thing they have been doing with it is buying back their stock on a regular basis - it looks like they have been authorised to buy back up to 10% of their shares.
Checking some of the history here, I see that the big cash injection happened in May 2022, when they sold their “infrastructure asset management division”. That deal took place under the previous CEO.
Three years later, I don't see much evidence that the current Board have been great capital allocators, but it might be too soon to tell.
The chart suggests that investors have not been overly impressed by developments:
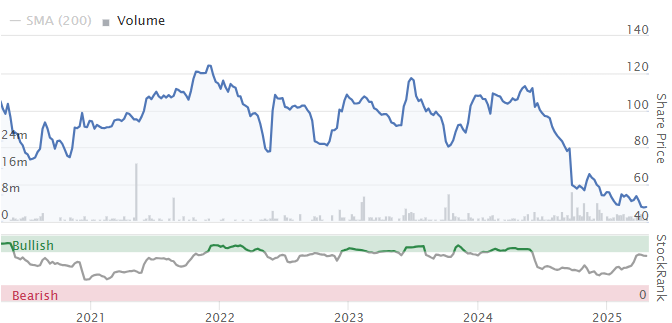
While some of the cash is being returned to shareholders via the buyback, it looks like most of it will likely be spent on the smart manufacturing division, including on M&A to build out this division.
Overall, I’m inclined to leave our AMBER/GREEN stance unchanged as the cash does still cover two-thirds of the market cap here. Additionally, we’ve had profits from continuing operations for each of the last two years, according to the FY Sep 2024 results.
I think the glass is half-full, but I’m very unsure as to what the outcome for shareholders might be. It's all down to management to invest the cash wisely from here.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

72 comments
OMG what could they invest their cash pile into?
Oxford Metrics (LON:OMG) Could the latest tariff talk on movies made outside of USA have a knock on affect to OMG. Certainly could affect movie production in the UK and therefore affect Oxford Metrics (LON:OMG. Ofc the tariff may be dropped next week.
RWS Holdings (LON:RWS) What is this rubbish. I want to make money. Crock of what …
RWS Holdings (LON:RWS)
A suggestion
the writers that hold a share shouldn’t been analysing it as well for the subscribers.
Another writer should be doing this.
RWS Holdings (LON:RWS) are not going to be able to maintain the dividend. If they do they are going to go bust later on.
All the best
I'm happy enough with them analysing it as long as they declare their position. The ones that hold it have done the most research probably and can give the most thorough analysis and insight - just have to read it knowing they may have a serious bias as holders.
That said I looked at RWS yesterday and today and couldn't bring myself to take even a small position, hope to be proven wrong in the future but it looks like a very sharp knife to try to catch
RWS Holdings (LON:RWS) are not going to be able to maintain the dividend. If they do they are going to go bust later on
Dividend needs to halve (at least) to avoid collapse. The structural issue looking forwards is that it looks unlikely that revenues can ever accelerate again as AI eats into its market. It’s possible margins could improve by using AI of course. And perhaps the company becomes the language translation equivalent of Smith’s News, generating decent cash flows from a shrinking product set, but on a cigar butt PER.
A bull point to add in for RWS Holdings (LON:RWS) - Benjamin Faes, Chief Executive Officer Did buy £670k’s worth of shares yesterday, he must have considerable faith in the business to invest that much of his own money
Or he has more money than sense
That could well be the case, the directors at Argentex (LON:AGFX) didn't seem to have much clue
-:)
Wow - That is taking incompetence to the next level….
If I were them I would totally scrap the dividend and go into survival mode asap
They are covering 4 to 5+ companies a day and you want the person familiar with the stock not to cover it?
As long as they declare it, we will benefit from their prior knowledge and take our own view on whether bias has clouded their analysis. If the current batch of stocko writers are in the pump & dump game then they need to do a better job to earn their Ferraris.
You'll no doubt want the FCA to regulate this website next (and I will demand GIPS standards every time a writer has the temerity to call share price movement "performance").
I’d add Barclays Smart Investor (smart in name only) to the list of those organisations who provide inadequate service to customers.
I hate to admonish you Chris. Adding Smart Investor to your list is not good enough. In my, unhappy experience, they should be top of the table!
Not available on Stockopedia yet but Marks and Spencer (LON:MKS) have just released this . I went to my local M&S foodhall yesterday and my conclusion was that as they were not accepting contactless payments their customers thought it Ok to take product without paying! IMO they are getting taken to the cleaners.
MARKS AND SPENCER GROUP PLC
CYBER INCIDENT - FURTHER UPDATE
Marks and Spencer Group plc ("M&S") is providing a further update on the cyber incident reported on 22 April 2025.
As part of our proactive management of the incident, we have made the decision to pause taking orders via our UK & Ireland websites and apps and some M&S International operated websites. The M&S product range is available to browse online, and our stores remain open and ready to welcome and serve customers.
We continue to manage the incident proactively and the M&S team - supported by leading experts - is working extremely hard to restore online operations and continue to serve customers well.
We previously informed customers that there was no need to take any action. That remains the case, and we will let them know, if the situation changes.
We remain grateful for the support that our customers, colleagues, partners and suppliers have shown during this time and will provide further updates, as appropriate.
-Ends-
Thought I’d flag Panthera Resources (LON:PAT) to readers as an interesting gold miner litigation play that is in the process of re-rating. Has been one of the biggest risers on AIM this week with more to come IMHO (I hold). This is well worth a read: Panthera Resources – multi-bagger legal claim? - Undervalued Shares
Just wondering peoples thought: I am attempting to Bed & SIPP 3 stocks and one trust with my provider Hargreaves Lansdown (LON:HL.^C25) - in previous years it's been instant - this year a page popped up stating it could take up to 4 days... I spoke to a young chap on the helpline and he and he confirmed it could take 4 days and nothing has changed since last year. I don't know about others but I'd of thought they can promise to make the trades in at least one day, max 2 ?!?
When l did it a few ago it took about 4 days, l lost a load of money, as the prices changed, said l would never do it again. Complained to HL but they just pointed to their rules. Although you save a bit on fees, you can lose out on prices. I would rather have control.
I hardly use HL anymore.
Unfortunately, HL no longer provides the quality service it was once known for. At the back end of last year, the waiting period for drawdowns and tax free cash became ridiculous. The list of products that can no longer be bought via their execution only platform (due to their interpretation of cost disclosure rules) grows ever longer. It does not surprise me that you are experiencing a delay with a simple Bed & SIPP. As I pointed out in a recent complaint, their arbitrary service levels and attempts at customer protection are not exactly customer focused.
Other providers are available but switching is a pain. In the meantime, my compensation income from formal complaints continues to grow and in last twelve months has exceeded the dividend income from some of my holdings.
Happy Friday everyone!
Simon
In the meantime, my compensation income from formal complaints continues to grow and in last twelve months has exceeded the dividend income from some of my holdings.
Yes Simon I suggested to one of HL's staff recently that instead of me asking them to send me an UFPLS withdrawal form it would be easier and quicker if they just sent me the compensation in advance and forget the form.
New owner, where have all the old staff one? doh!
I've been a big user of HL for about 7 years. But during that time, I've found their platform has continued to worsen and I've sworn a few times to abandon it, but through my laziness, I'm still with it. In terms of technology, it's fallen a long way behind the smaller more-nimble platforms, e.g. they don't have stop-losses available on US stocks and their FX fees are steep.
I do an annual check of the other platforms and honestly - and depressingly - still think HL is the best for me! Amazed at the lack of improvements in the space both in terms of tech on these platforms and also in the fee setups they've all gone for.
Recently transferred most of our holdings to AJB from HL. So far I'm pleased with the move. HL were / are getting pretty poor. Glib copy and paste apologies for any complaints raised and SFA is ever done about it. Good riddance.
I've just done 4 sets of Bed & ISA transactions in some accounts at Interactive Investor. Instructed late morning yesterday, they were done by close of play today, which I view as acceptable.
Last year I seem to recall they took longer, but I may have made the requests closer to the start of the new tax yr. I do agree that it is better to avoid volatile stocks because you can become a hostage to fortune.
I have to say ii's in-specie transfer functionality is excellent - it is pretty much instantaneous provided both accounts are at same address. They also let you choose whether to transfer at market value or at book value (book value being what you want if transferring to a spouse) and also permit the in-specie transfer of partial holdings - you just tick the stocks you want to transfer and type in the nominals. I guess that since both holdings are in the same nominee account it is just a SQL edit for their database.
In fact it is the efficiency of the in-specie transfer function at ii that persuades me not to dump them and head over to Interactive Brokers (IBKR don't offer convenient in-specie transfers but are much cheaper on FX).
The 1.5% FX charge at ii really annoys me (yes, you can withdraw in foreign currency and convert elsewhere, but I've not found a way to duck the SWIFT fees so not worth it for small amounts), but as I tend to reinvest in foreign currencies I very rarely pay it.
With large amounts I withdraw the foreign currency and convert elsewhere.
well no, no Bed&SIPP transactions today...
I guess I'll just make the transactions myself and charge HL the extra costs... I don't know about anyone else but I do not like having 4 bed&SIPP transactions pending over onto a new day for obvious reasons. I wonder if their Helpdesk is open over the weekend.... ? I think I probably would like to change providers... but it's the hassle of the whole thing, so I think they've captured me for now with my laziness, I think I'll start looking at what different providers to HL can offer though.
Also while I'm here Mobico (LON:MCG) that's a hefty drop !! sorry to all follow holders :-(
I was too busy yesterday to reply but I'm with HL and have never used their bed and ISA/Sipp service for the simple reason that I want to have control of the price I sell at and buy at. You can sell and buy back as you would with any other stock transaction but it depends on the size of the trade and the spread.
I have found it best if it is a large holding to ask to speak to the dealing desk. A dealer will get you a very minimal difference between sell and buy price and do it as you wait. You will pay a manual dealing fee on each trade and a spread that amounts to about £40 for the market maker's turn. In some cases that has saved me hundreds of pounds so it's worth doing the math before you decide how to proceed.
Don't bother speaking to the help desk about bed and ISA/Sipp as they probably haven't even heard of how a dealer can do it for you and will try to steer you to their standard process.
well in that case @rwh3ue - I will speak to the dealing desk but I fear that might not be as simple as you make it sound anymore... last couple of years the Bed&SIPP has worked well at HL - the same price selling was the same price buying in the SIPP with tight spreads this happened for several transactions not long after the order was made !?!?
Hi Graham, hope you're keeping well! Do you know if there will be further coverage of Mobico, they are apparently releasing final results next week, market not liking the update today. Best, Michael
Hi Michael! I imagine we probably will take a look at final results, given the dramatic move today. Myself and Roland will both be working on the report on Tuesday, when results are scheduled. Thanks. G
Pantheon International (LON:PIN) I also added this a couple of weeks ago as the discount widened to extreme levels. Long-term performance is very good and PIN do seem to be somewhat more defensively positioned than other PE funds, which is probably a good thing in this environment As with many of its peers, the board seems to be making a real effort to tackle the discount through increased returns to shareholders/buybacks. Another thing I like about PIN is their increased focus on co-investments rather than through PE funds - this not only saves on fees but should also mean a bit more concentration into the best opportunities. Worth watching some of their IMC presentations where they always come across well in my opinion.
Pantheon International (LON:PIN) Certainly looks a promising opportunity and thanks ~Graham for the input - would be interested to see/hear comparisons with for example Oakley Capital Investments (LON:OCI) - any thoughts please
Pantheon International (LON:PIN) - I've held for a decade or so. Pantheon are a high quality manager, delivering c10% per annum returns for 30 years or so. The discount is an anomaly but could blow out a bit further if we do get a global recession and I think private equity deals are currently getting pulled. Not quite a buy for me, but happy to hold.
Well done topvest, looks like you are sitting on a decent return after all that time holding PIN. Would be even better if that discount would close!
Bohenie, I prefer OCI on a number of grounds. PIN I have always struggled to value and whilst thier presentations are brilliant not so sure performance is. AIC 5v year performance shows HgCapital Trust (LON:HGT) at 135.26 % total return ( The top is 3I's but that is a trust I would not touch due to its reliance on one major holding) OCI is123.92% and PIN 56%. 10 year is HGT at 482%, OCI at 207.67 and PIN at 107.76. All PE companies performance is here https://www.theaic.co.uk/aic/f...
Thanks for your input Charles! Much appreciated.
Trusts are sort of my "thing"- used to sell them to institutions back in the 1980's. But that was a while back so no expert now. PIN have always done great presentations, very convincing spokesperson. So is the manager of Augmentum Fintech (LON:AUGM) and that has been a disaster share price wise for me !!
Is that share price returns or NAV returns? I think you need to use NAV returns to get a better idea of underlying performance. As mentioned above, PIN is somewhat more conservative than the other PE funds (eg lower leverage and more defensive sectors) so that probably explains the underperformance you mention. Depends what you're looking for really - right now I would personally go for PIN for it's unusually wide discount which I suspect has to come in, and it's also a bit more diversified (OCI is a bit more concentrated I think).
All the discounts are wide for PE trusts. OCI NAV 5 years is 111.1, PIN is 80.2.
Yes agree thanks Charles - did some rummaging round this afternoon and decided PIN 3 year performance simply doesn't stack up - OCI has also suffered but much better and frankly I prefer the management style at OCI but will now take a look at HgCapital Trust (LON:HGT) also before a decision
But they are all quite different, with varying risk & exposure profiles.
Oakley Capital Investments (LON:OCI) has a European focus.
There is also ICG Enterprise Trust (LON:ICGT) which is also worth a look. Harbourvest Global Private Equity (LON:HVPE) is another.
I hold all 5 of them to some degree (HGT, OCI, PIN, HVPE & ICGT), and as the discounts move around I tend to top up accordingly. If I could only keep one it would probably be HgCapital Trust (LON:HGT) .
Monty-I did miss HGT. An error, but it happens with investing. I like the OCI portfolio.
Also look at Patria. In the same category of a fund of funds as PIP and HVPE, this is well diversified and has strong performance. Invests in European mid market funds and co-investments. Much better performance since Abrdn under Brd sold the business to Patria.
You're welcome bohenie, I'm enjoying taking a fresh look at the investment trust/PE space. I haven't got any immediate thoughts on OCI but will need to study it when I get a chance.
as in "buy and hold " the index Graham?
A whole lot of rotation going on and a transfer of leadership - maybe more the demise of lazy passive tracking and enter an era of some actual stock picking ?
- BRK International Holding (NAQ:BRKHM) one of the biggest outliers and at record cash holdings ?
Heatmap YTD for S&P 500
Talk of BlackRock buying up 'undervalued' UK shares. Will be in the FTSE100 class I imagine, but might have a spillover effect for small caps?
£MLR there have been quite a number of “complaints” recently of Stocko stock ranks and classification. Isn’t it time Melrose was upgraded from the current “Sucker Stock”
Which stock are you talking about? I can't see any uk MLR ticker.
The £ was replaced by @ before the ticker a long time ago.
Complaints, must have missed those.
Sorry got it wrong - Melrose Industries (LON:MRO)
I see. Does not look good at the moment, but if they meet the forecasts, then it will be re-rated on Stockopedia. Stockopedia goes on results. 1st half year is 31/7/25 l think. Will tariffs effect them?
The rankings are algorithmic - it's not something that will be "upgraded" unless the underlying numbers change. Melrose Industries (LON:MRO) is classified as a Sucker Stock simply because the Q, V and M rankings are all low.
I'm astonished at the number of subscribers who are happy to pay for this service but don't appear at all interested in understanding what they are paying for. I would heartily recommend watching any or all of Ed's educational videos where he discusses the Stock Rank system in detail.
This article explains the 6 classification styles: https://www.stockopedia.com/ac...*7pj7k4*_gcl_au*MTI4NDAwMDUxMS4xNzQ0Mzk4NzA0LjE0NTQxODEyNTQuMTc0NTUwNzM4Mi4xNzQ1NTA3ODU2
The problem is not that there's some misunderstanding of what the rankings do and how they are calculated; it's that the underlying data is wrong, making the calculations meaningless. They put a fancy table and calculations on data that is incorrect (a case in point being that they don't deal with share consolidations correctly). My portfolio has been incorrect on a regular basis because they can't add up simple numbers. I've raised it several times with Stocko and never had a satisfactory response.
Argentex (LON:AGFX)
So the end game is almost in the books already.
2.49p per share maybe (which is sort of better than expected on Wed morning) and the CEO gone. Presumably that's the CEO bit of his career gone now - it probably should be.
You would think that their clients would desert them en masse, but then the buyer presumably thinks otherwise.
Good job it's a nice sunny Friday today.
Cheers
Chris
Here in Wiltshire the sky is overcast, suiting the mood. A minor hiccup in Greatland Gold (LON:GGP) today that I put down to a futue 2% dilution so I added some more shares with dividends earned.
Shocking equity destruction Argentex (LON:AGFX) - all for a company which took no risk and has been caught with its trousers down speculating on FX movements (or at least not hedging properly).
I believe Record (LON:REC) takes no credit risk.
Graham - a quick write-up on Record (LON:REC) - you may know better as a financial investor?
Yes, Investment Hunter, I'm a big fan of REC and have been for some time. I think I previously owned a few shares in it, if memory serves. Not very impressive in terms of growth but highly credible IMHO, and a totally different species to the likes of Argentex.
"President Trump has said that the current 145% tariff on China "will come down substantially - but won't be zero". I have my fingers crossed for a major U-turn by Trump, under pressure from many of his own supporters."
Interesting articles in the press that claim that Walmart, Target and Home Depot have made representations to the White House - saying that shelves will start to empty in two weeks. No doubt that this has focussed minds.
The Telegraph also reports that the significant disruption to shipping with cancelled orders has halved 40 container costs. Possibly a problem for the quoted shipping companies if this persists.
If I were in the China camp negotiating I would sit on my hands for two weeks and see what happens.
Taylor Maritime (LON:TMIP)
Could one of the analysts please comment on Taylor Maritime today?
It has announced a major disposal of assets this morning which will leave the business almost debt-free.
I hold.
Thanks.
Hi Graham, would be good to have your views on OMG.
Will do, Berksbee! cheers. G
What a disaster Mobico (LON:MCG) is turning out to be. US school bus sold for a derisory value, more write-offs on onerous German rail contracts and losses at the original National Express business. I thought that transport companies were supposed to be steady and reliable cash generators. I am a very unhappy holder of this sorry investment that has been mismanaged for a long time now.
Are there any glimmers of hope or should I cut my losses and run?
RWS Holdings (LON:RWS)
I see the RWS CEO bought 1 million shares at 67.9p yesterday.
I bought yesterday too. I have followed RWS for a while and view yesterday's price drop as very harsh.
Funny how the directors sold a chunk in January . Lucky old them
They all seem to have been share options.
Hi Ian,
I am a suffering holder but doubled down yesterday @ 65.7! Agree the drop seems very harsh. The big question for me is the "AI will replace this all" risk. I am not at all convinced it is as simple as that. Also, right now, AI sales by the big boys are nowhere near where they need to be and they are virtually giving it away - this wont last. ( I have a senior role in IT btw).
Hi Berksbee
RWS is certainly a company's in the eye of the AI storm.
We will have to see the extent to which its products are replaced by AI rather than enhanced by it. From the outside it's obviously difficult to make that call now, especially as AI functionality and adoption is very fluid.
What I like about the company is its broad and good quality client base, low gearing and its FCF - although I realise these are all coming under pressure.
Anyway, we'll see.
Completely agree Berksbee, AI is overplayed as a replacement for everything. I'm sure it will become a useful tool, just like search engines, online videos, and the like.
I worked as a developer until recently, and I heard exactly the same things about the outsourcing, the internet, open source, off shoring. They were all going to take my job, but amazingly I was still working over 30 years later than the initial scare story. Maybe in a few years time AI will take some more jobs, but more than likely it will just enable things to be done better and for companies to avoid repetitive tasks.
The constant threat of AI in the air, plus now material proof that profits have taken a nose dive, will surely be a constant downwards force on this stock though - even if AI wont actually be able to completely wipe this company out, I would expect if people start to dump high risk assets again, this might take another big hit?
I'm interested given how much FCF they still have and the amount being passed back to shareholders, but probably only to the tune of a small holding...