Daily Stock Market Report (Fri 26th September 2025) - Webinar Review, MTEC, S247, KEYS, CWR, TND, ZIG

Good morning!
Ed and I presented a webinar yesterday with our thoughts on results season - here's the link. There was too much to discuss but we did our best!
As for today, I'd like to catch up on some stories we missed during this busy week, so I'll be looking again at all the comments under the reports.
Hanging up the pen now, cheers!
Webinar Overview
Macro (from Ed):
- End of September is one of the major annual spikes in results announcements.
- Companies in January with "ahead" statements and big jumps have, in aggregate continued to do well since then.
- This is consistent with the lesson to buy/hold when companies are ahead of expectations or see big price jumps.
- Rates are falling but are still 1% higher than expected (4% vs 3%). Inflation has been sticky, nudging higher (close to 4%).
- FTSE All Share index still significantly cheaper than international peers despite performing well this year, matching the S&P 500 year-to-date
- "Don't fight the tape. Don't fight the Fed." - Martin Zweig.
- Gold price rocketing.
Core Discussion Themes:
1. Investing: brokers, funds and platforms.
- Peel Hunt/Cavendish. Not many IPOs yet. Cash-rich investment banks waiting for activity to pick up again.
- Jupiter Fund Management: their CCLA acquisition looks promising (good value). Shares have recovered well but could have more to go (StockRank 99, MomentumRank 99).
- Polar, Impax (I own), Mercia all interesting in their own ways.
- IG Group (I own): volatility has calmed down since Trump tariff panic, still like it as a long-term hold.
2. Retailers.
- Currys: LfL revenue growth 3%, gaining market share - general market not strong.
- DFS: finely balanced outlook statement. Consumer strength is not strong or weak.
- Jet 2/OTB: consumers delaying holiday purchases until they are sure they can afford it.
3. Video game companies.
- Frontier Developments: huge post-Covid fall. Primed for recovery? Big release coming out in October.
- Everplay: indie developer and publisher. Maker of Worms. Lower risk due to back catalogue revenues, more diversified.
4. Defence
- Goodwin: amazing RNS, big contract with Northrup Grumman. Family business, not interested in the City. No forecasts.
- Rolls-Royce: big upgrade back in July. Valuation worrying at these levels. High Flyers can quickly become Falling Stars.
- Babcock/Cohort: very pleasant conditions for companies to benefit from government spending in the sector.
5. Government contractors (Ed)
- Morgan Sindell/Galliford Try/Kier. New "frameworks" guarantee revenue and allow the companies to share in gains and losses, less risky than Cerillion days.
- Made Tech: IPO failure, now on recovery with government spending on digitisation.
6. Gold sector (Ed).
- Producers: Serabi (Brazil), Altyngold (Kazakhstan). Improving the amount of recoverable resources as they mine out.
- Explorers: Metals Exploration, Thor Exploration.
- Operational gearing and balance sheet healing thanks to the high gold price. Net debt moving to net cash.
- Junior Gold Miner ETF has doubled.
7. Lenders
- International Personal Finance: Graham still not entirely satisfied by bid from New York buyer.
- DFCH: discount to net assets, big increase in EPS estimates, expanding to new loan types.
- ASAI: microfinance in Africa and Asia, average loan only $210, millions of customers.
- MAB1: benefiting from increase in new mortgage lending, refinancings also to pick up.
Case study from Ed: high-rank shares have an uncanny ability to outperform profit estimates, driving momentum. Can check this by clicking on "Print" on a company's StockReport and downloading the report from a year ago. Look for companies with high StockRanks and surprisingly low profit growth forecasts! Morgan Sindall is a good example.
My thoughts post-Webinar: I have to say that I think these are very nice conditions in which to be investing. We all suffered the small-cap bear market for a long time, but it now looks like we have possibly turned a corner as many sectors (not all by any means!) have recovered well. And yet overall valuations aren't excessive. There are still plenty of cheap P/E multiples out there for those focused purely on value.
If you look at the sectors we covered in the webinar, I think it would be hard to argue that many of them are in bubble territory. Some of them (gold, defence, government contractors) have performed extremely well, but the reasons for that strong performance are logical (high gold price, government spending). So I don't think that the market as a whole has become irrationally optimistic yet - far from it!
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Pennon (LON:PNN) (£2.1bn) | On track against expectations in 2025/26. Target RORE (return on regulated equity) 7%. | ||
Ceres Power Holdings (LON:CWR) (£274m) | SP -14% Most probable revenue c. £32m (StockReport: £53.5m estimate!). Uncertain timing of revenue recognition from new agreement. | BLACK (RED) (Graham) [no section below] We've been cautious on this one, e.g. Roland in July. More recently, Megan provided a preview for us in The Week Ahead. Today's results to June 2025 start off with the good news: cash and short-term investments of £104m. The pre-tax result is a less promising £19m loss - worse than £11m loss seen in H1 last year. The company has been cutting costs. I can't claim to understand the technology at play here but I know a revenue warning when I see one; CWR was supposed to generate far more revenues this year than the £32m they have guided for today. I'm going to give this a RED today on the back of this negative surprise. Material losses are forecast for the foreseeable future, but I could still upgrade it to AMBER/RED if it meets forecasts over the next 6-12 months, as it should at least have enough cash to survive the next few years. | |
Big Technologies (LON:BIG) (£251m) | Resolutions to remove and replace the Chairman. Supporting shareholders hold 52% of active voting rights in BIG. | ||
Seeing Machines (LON:SEE) (£122m) | Significant 5-year agreement with leading UK bus OEM. OEM manufactures 1,700 units annually. | ||
Quadrise (LON:QED) (£81m) | SP -5% Addendum to June 2023 agreement with Valkor in Utah. $1m due to QED will be rephased over the period to June 2026. | ||
Brave Bison (LON:BBSN) (£75m) | Lord Ashcroft wishes to appoint a new Director to the Board. | ||
Ondine Biomedical (LON:OBI) (£75m) | Continued commercial expansion and clinical progress. Revenues +18% ($1m), loss from operations $12.5m. Cash $5.6m. | ||
Time Out (LON:TMO) (£48m) | TMO’s 13th food and cultural market opens following last week’s Budapest opening. | ||
Carclo (LON:CAR) (£47m) | Performance in line & exps unchanged. D&E revenues to partially recover in H2, strong margins to be maintained. | ||
Tandem (LON:TND) (£11m) | SP -9% | AMBER/GREEN (Graham) [no section below] The share price here has made a little upward progress since I covered it in March. I used to own a large (for me) stake in this business, but lost interest after years of limited progress. With an £11m market cap today, it continues to struggle to take things to the next level. At least the outlook is in line, and Cavendish have issued a note today leaving their forecast unchanged: adjusted EPS of 8.5p in the current year, with an adjusted PBT of £0.5m . Net assets are £23m of which only £5.5m is intangible. It remains objectively cheap in balance sheet terms, and is categorised as a "Super Stock". It just never seems to generate enough real profits to get taken seriously. Historically, there has also been a capital allocation problem in my view - meaningful profits have been generated from time to time, but have not been reinvested successfully. The company has posted a small operating loss and a £400k pre-tax loss for the first six months of the year. I like to think that I'm a patient investor, but personally I don't have the patience for this one. It's still AMBER/GREEN for the potential it has to come good some day. | |
Blackbird (LON:BIRD) (£11m) | Elevate.io will be exhibiting at Chamber’s “Annual Business Expo” today. | ||
Smarttech247 (LON:S247) (£11m) | SP -64% Numerous contract wins but margins to be slightly softer than anticipated: trading EBITDA and profit to be less than guidance. Company is undervalued; a delisting will provide greater strategic flexibility. | RED (Graham) [no section below] Commiserations to anyone holding this overnight. From £10m and below, I tend to be very concerned about delisting risk, but this shows that being just over £10m is no defence against delisting. In fact the risk here was heightened by the presence of a majority shareholder who owns nearly 70% of the company, as I pointed out in January. This share is now only suitable for those who are happy to own a private company, so I'll put it RED today to further emphasise the special risks and complications associated with that. The lesson is that life is easier when we stick to companies that are a little bigger than this, with bigger free floats! |
Backlog
Made Tech (LON:MTEC)
35.35p (£53m) - Final Results - Graham - AMBER/GREEN
Made Tech Group plc, a leading provider of digital, data, and technology services to the UK public sector, is pleased to announce its audited final results for the year ended 31 May 2025 ("FY25" or the "Period").
Let’s catch up on these results.
I’ve highlighted some of the numbers that jump out at me from the results highlights:
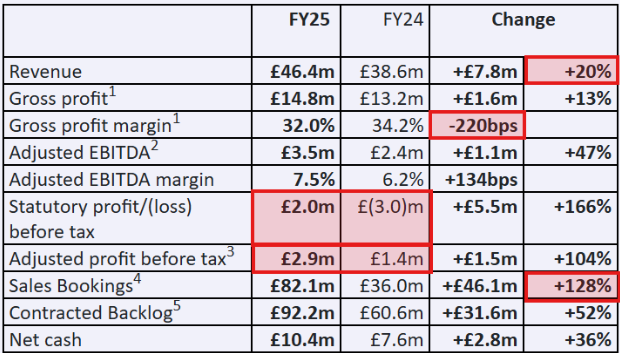
20% revenue growth is positive, even if it comes at a slightly reduced gross profit margin.
PBT makes a big improvement whether on an adjusted or unadjusted (“statutory”) basis.
Finally, we see a very impressive more than doubling of sales bookings.
The CEO is of course pleased:
"I'm delighted by the progress we've achieved this year, with strong revenue growth, improved profitability, and solid free cash flow. Our focus on sales and bidding has paid off, driving a marked increase in Sales Bookings and a materially larger Contracted Backlog.
This is one of those government spending stocks:
The UK Government's emphasis on digital transformation, highlighted in the State of Digital Government report, the UK's Modern Industrial Strategy, and the Strategic Defence Review, continues to underline the scale of the long-term opportunity. With the Spending Review now concluded, the demand for modern digital services is clearer than ever, offering the potential for sustained growth.
Outlook
There’s been a “strong start” to FY May 2026. Revenue, adj. EBITDA and cash conversion are all in line.
Solid Contracted Backlog underpinning expectations for FY26
UK Government emphasising the significant role technology will play in delivering its priorities supports confidence for long term growth
Reading through the Chair’s statement, she notes that the “political clarity” after the General Election and Spending Review will “drive significant investment in digital initiatives”.
Perhaps an overview of the group would be helpful.
Service Division: when organised by industry, this covers Health & Life Sciences (includes NHS modernisation), Public Safety & Defence (Ministry of Justice), and Central & Devolved Government (the largest group, “delivering a wide range of nationally important programs”. 41% growth in the year).
The company is also organised along service lines - a wide range of services provided such as Technology, Data & AI, etc.
Finances
No dividend is anticipated “in the near term”, as the company prioritises growth. That’s totally reasonable, but many income-oriented investors are likely to give it a pass for now.
Balance sheet: £14.5m of equity, almost fully tangible and mostly consisting of cash. There’s a £10.4m cash balance with zero borrowings. Not bad at all for a £50m market cap company.
As usual, I investigate the differences between adj. EBITDA, adj. PBT and actual PBT.
It’s nice to see that there are zero exceptional items.
There were also no impairments.
It therefore seems that the main - indeed, the only - adjusting item is share-based payments of £0.9m.
I do not permit this to be adjusted out, as it’s a cost borne by shareholders in the form of dilution.
Therefore, I prefer the actual PBT figure (£2m) rather than the adjusted figure (£2.9m).
Adjusted EBITDA is £3.5m. I still think £2m is the most accurate profit figure. .
Estimates
Thanks to the company and its advisors for including this:
Based on the latest published equity research, the company understands current market consensus for the year ended 31 May 2026 (FY26), as at 23 September 2025 being the day prior to the publication of this announcement, to be revenue of £50.1m, Adjusted EBITDA of £3.9m and cash of £13.0m, and for the year ended 31 May 2027 (FY27) to be revenue of £55.1m, Adjusted EBITDA of £4.4m and cash of £16.1m.
Graham’s view
The success of government-linked companies is an interesting dynamic considering that higher taxes (especially NICs) are seen as dragging on the consumer. Every cloud has a silver lining, I suppose?
The revenue forecast suggests top-line growth of 8% this year (FY May 2026), and then 10% the following year.
Adjusted EBITDA is expected to increase by about half a million pounds each year.
Based on these numbers, I have to say that this look fully valued to me.
Research from h2Radnor acknowledges that (at 38p per share) it’s trading at a 2% premium to its UK Software Service peer group, but argues that the premium is merited given its public sector prospects.
I’m willing to concede that point, noting the very strong growth in bookings and order backlog. But at the same time, the financial forecasts - revenue and EBITDA - suggest that actual financial results will be more limited.
We’ve been GREEN on this - see Roland’s June coverage. I can keep a positive stance on this, but I’m not sure if a fully GREEN position can be maintained.
In StockRank terms, it’s a High Flyer but with declining momentum:
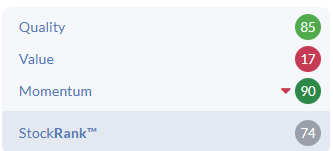
In simple Value terms, it’s not offering that much.
On balance I think that AMBER/GREEN is most reasonable at this point.
Keystone Law (LON:KEYS)
674p (£214m) - Half-year Report - Graham - AMBER/GREEN
We’ve been AMBER/GREEN on this national law firm for a while - most recently in February. It issued interim results on Wednesday which caught the eye of some readers.
Company description: “a highly scalable, premier tech-enabled platform law firm”.
Key points from Keystone:
Revenue +16.5%
Revenue per Principal +9.9% (£116.8k)
Adjusted PBT +20.4% to £7.3m
All very impressive progress. It’s an altogether pleasant update:
Positive recruitment market conditions - 30 new Principals added.
AI strategy “focused on delivering real value and real-life solutions”.
Marketing brand refresh
Current trending and outlook: ahead of expectations.
The Group has made a positive start to H2 2026
The Board are confident in the ongoing success of Keystone and expect revenue and adjusted PBIT for the year ending 31 January 2026 ("FY 2026") to be ahead of current market expectations, whilst the newly renegotiated interest rates mean that adjusted PBT is expected to be comfortably ahead.
They helpfully let us know that market expectations were for revenues of £103.6m and adjusted PBT of £12.9m.
“PBIT” is presumably the same thing as EBIT (earnings before interest and taxes).
With higher interest income, PBT is doing even better than EBIT against expectations (higher interest income benefits PBT, but not EBIT).
Some readers focused on the AI element of the report, so let’s take a look at that:
I’m very wary of non-AI companies describing themselves as AI companies, but that’s not what’s happening here. AI seems to be having a very real impact on how this law firm does business. As always, the challenge will be to stay ahead of the competition who are presumably doing the same:
During the Period, we have rolled out a number of generative AI tools, which are available as extensions to the market leading products we already provide to our lawyers. These include the ability for our lawyers to produce file notes of Teams meetings in seconds and for our lawyers to use generative AI solutions across any documents held within NetDocuments (our secure cloud-based document management system). We have developed an internal tool using generative AI as well as an element of agentic AI. This enables our lawyers to interrogate our voluminous Operating Manual using basic English language queries providing them with logical answers as well as links to the relevant sections of the manual; taking only seconds…
It goes on, but I think you get the drift.
Balance sheet: there is some (not much) tangible equity, about about £12m.
Net cash is £6.5m. There are no financial borrowings, and it’s nice to hear that the company has worked to maximise the interest on this cash pile.
Graham’s view
I’m happy to leave our AMBER/GREEN on this.
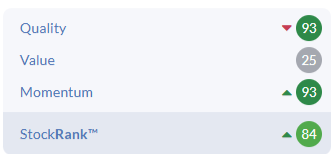
It’s another High Flyer but in this case momentum is rising and we’ve just had an “ahead of expectations” update, so it would be wrong of me to change stance at this time.
It’s certainly very expensive for a law firm:
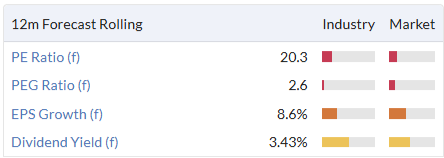
The AI revolution is worth reflecting on - will it ultimately be a good thing for law firms? I would say yes, in the same way that every major technological improvement is a good thing (the internet, etc.). Customers get more productivity, and the firms themselves can spend more time on their higher-value work.
But is it necessarily a good thing for investors? Personally, I doubt that it will translate to significantly higher returns for investors, because every law firm will likely get access to similar AI tools before too long. But perhaps Keystone can prove me wrong, and be the law firm that uses AI most intelligently and profitably! We shall see.
ZIGUP (LON:ZIG)
315.5p (£716m) - AGM Statement - Graham - AMBER/GREEN
This is “the leading integrated mobility solutions platform providing services across the vehicle lifecycle”.
I would prefer if they said “we provide van rental and related services”.
They used to have the rather serious name Redde Northgate.
Roland was cautious on it in July, noting a high degree of leverage and heavily adjusted profits.
This AGM statement was pretty good:
The Group has performed well over the first four months of the financial year. VoH (GN note: “Vehicles on Hire”) is ahead of the prior year and good vehicle supply has supported our fleet replacement plans. Activity levels in Claims & Services are as expected, alongside continued stable hire durations and it is now entering the traditionally busier autumn and winter period.
In addition to positive news on contract extensions, they have a new “Operations Control Centre” for roadside assistance, along with upgraded UK call-centre infrastructure.
Leverage is “in line with our target range of 1.-2x”. In the absence of further information, I’ll assume it’s still at the higher end of this wide range. It was at 1.8x when Roland looked at it.
Outlook: unchanged.
Graham’s view
I note that some readers are positive on this, while Roland has been moving between AMBER and AMBER/GREEN.
On the back of an in-line AGM statement, and considering the StockRank of 80, I’ll give this the boost to AMBER/GREEN.
The cheapness is pretty clear:
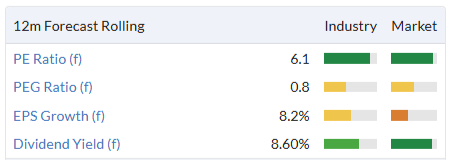
But the quality is also average, as you’d expect for a rental business. ROCE/ROE of c. 7-8%, and a QualityRank of 54.
Net debt was last seen at over £800m, bigger than the market cap. Rental companies often need to borrow heavily, in order to achieve acceptable returns.
I’m leaning towards the conclusion that everyone is right: the company is right to borrow heavily, Roland is right to be careful, and yet there is an opportunity if nothing goes wrong. So let’s give this an upgrade by one notch, a nice way to end a nice week! Have a great weekend all.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

31 comments
Many thanks for the Made Tech (LON:MTEC) review. You've confirmed my view that I can put my farthings to better use elsewhere for now.
Hopefully Ed and Graham have not packed up for the weekend and will read this . I enjoyed the webinar last night enormously and I particularly enjoyed the format as it was thought provoking at the company , sector and macro level . Grahams thoughts this morning however were very interesting : My thoughts post-Webinar: I have to say that I think these are very nice conditions in which to be investing. We all suffered the small-cap bear market for a long time, but it now looks like we have possibly turned a corner as many sectors (not all by any means!) have recovered well. And yet overall valuations aren't excessive. There are still plenty of cheap P/E multiples out there for those focused purely on value.
The term very nice conditions really bugged me because shortly after reading the above I was reading the Daily Mail article by Alex -City Editor entitled "In 50 years as a City writer, I've almost never felt so worried a terrible crash is coming. Warning signs are EVERYWHERE."
Taking the politics out of it you couldn't have two more diametrically opposed view of the the current market conditions. Who is right ?
how many people are out there commentating on the markets.
you will always find somebody who thinks the end of the world is around the corner.
and well the daily mail loves a good old made up story like this doesnt it.
oh and its behind a paywall so we cant even fact check what this guy is saying to see if his logic makes any sense.
What says it all is that guy has been in the business for 50 years and i dont think i have ever heard his name before - thats probbaly me though paying very little attention to journos
I worked at the Mail 15 years ago and Alex Brummer was an institution then. The Mail's City Desk is tiny. Alex B knows the City well but I never thought of him as a stock analyst. Anyway, in the article he's concerned about Nvidia' s investment in AI, doesn't like Cathie Wood's bullish support of crypto and tech, usual stuff about tariffs, US economy. Thinks we're in hyperspeculative "bezzle" territory and overdue a correction.
He says: "Now the marathon bull-run could soon be over. And, here, the gold price is a useful bellwether. Historically, private investors, central banks and asset managers turn to gold, which offers no dividends or interest, when they are fearful and searching for a safe harbour for their assets."
Nothing new really.
strewth if he knows nowt about tech stocks and the like its probbaly better not to comment rather than saying "its way overvalued". for example nvidia net income went from $30 bill ye jan 24 to $74 bill ye jan 25 - with decent growth expected jan 2026 and beyond. yes company is expensive but the company is making buckets of real profits. Not for me either and i would be worried it might turn into ober supply situation - but little evidence that is the case.
practicably speaking we havent really got started on the real smart ai yet for most day to day stuff - so overall its not that we cant expect growth in number of chips being needed long term.
hey ho if he thinks he is genius good on him.
ref cathie wood - well she was always a one trick pony with no sensible backup plan - even there though i suspect her larger picks have probably perfomed on average decently.
You will always get opposing views on any subject where you get people drawing different conclusions from the same facts and data. You only have to read half a dozen articles of the daily report to see this in action.
A key issue here or in any discussion is one of context. If someone is 65 and managing an investment portfolio of 20 million, then they might well have different views than someone aged 20 with 5k to invest.
I deal with this noise by making my own business decisions based on what I observe on a day to day basis. I am currently seeing inflation, stagnating growth and a high probability of stagflation. For my personal circumstances, the best option is a defensive portfolio with gold as a key defensive investment. It has been this way for some time now.
When I started investing we did not have the luxury of etfs. If I was a young investor today I invest in a broad spectrum of etfs and accumulate on a long term basis. I would resist the temptation to tinker and come back in 40 years and look at what had been achieved. No need to worry about macro discussion with this approach.
Good luck with your investment strategy.
Where can I get live prices from LSE? And how much does it? tia
I greatly enjoyed the webinar, and it provided great motivation to try and get a bird's-eye view on the entire reporting season. Graham and I had far too much to pack in, and realised we must do this much more often - whether via audio or video - and with the rest of the team too.
I'm going to share 2 slides - from a data study that we did last year (using 10 years of data) - that are relevant to one discussion point last night - that Graham highlighted again above.
and...
This is the reason we so often see "ahead of expectations" announcements in high StockRank stocks... that the market has often given very low forecasts for - stocks like Currys, Morgan Sindall and so on.
Seeing the Ceres results above reminds me that the AIM market has a few listed "new" technology battery manufacturers which, after many years, seem to be winning contracts and potentially becoming commercially viable. Has anybody stumbled across and broker or other research into the future of the sectors and the potential winners and losers?
Two to look at are Invinity Energy Systems (LON:IES) - Vanadium flow batteries, good for large scale storage but too heavy for cars, etc - and Ilika (LON:IKA) - solid state batteries, tiny batteries for medical and big ones for cars. Both are promising growth but are using technology that have good advantages over standard lithium batteries in safety and durability. But it's a highly competitive market and I suspect getting the price right to beat the foreign competition will be a challenge.
Bloom Energy in the USA has similar SOFC tech to Ceres and just did a massive deal with Oracle to supply power for Ai and datacentres. With all the datacenter power demand maybe it's now or never for Ceres. To my understanding Ceres tech is more efficient conversion from natgas to electricity and less pollutants. Ceres seems like they're focusing on Asia and Europe while Bloom has the Oracle deal. Doosan built a factory for SOFC (solid oxide fuel cell) so we could see some datacenters in Korea run on them, maybe it takes off. If you size it like a bet that you don't lose much if this is wrong, I think there could be a lot of upside especially for Ceres. It seems like things at Ceres are progressing according to the plan, base on the limited research I've done. Ceres tech sounds better than Bloom since it operates at a little lower temperature.
A great seminar I really enjoyed the anecdotal discussion between Ed and Graham. Through sheer forgetfulness I managed to miss the first ten minutes, but it is definitely worth a re-watch in its entirety to make sure I got all the salient points.
Excellent webinar, with some very enlightening pointers
Very interesting Webinar yesterday afternoon. A lot of information to digest. I will be looking back at the recording in the next day or two. Thank you Ed and Graham for hosting.
Very helpful webinar yesterday and useful summary today, reminding me to hold rather than take gains at what may seem a high point to an inexperienced DIY investor new to Stockopedia. I am tempted to think that Northrop Grumman in the same field as British Aerospace and able to provide such a contractual boost to Goodwin, may be the reason for my holding in BA not moving as anticipated and have transferred my funds in BA to THX making me overweight in gold miners in my Naps portfolio, especially as my original choices of MTL and SRB have both almost doubled in value since I first came across Stockopedia thanks to an advertising flyer tucked inside my Investors Chronicle magazine. The only investment I have doubts about, not shared by institutional investors and usually cropping up at this period, but dispelled for several years now, are those in YU having read about the number of consumers failing to pay their power bills, but as far as I can make out the company looks to be doing very well indeed despite the reduced share vale from January. Thanks to all for an excellent service.
Agreed Robert, this really must be a time to hold.
Carclo (LON:CAR) also interested in this one if you have time. Trading update sounded muted but I think that is the new CEO style?
Thanks for the Webinar summary. Great show Lads. Plenty of nuggets of trading advice.
Thankyou for the link Graham, I came late to the party, missing the first half-hour and will play catch-up today.
IOCs (International Oil Companies) will only receive $16 a barrel.
https://www.ainvest.com/news/i...
less reliable, more detail: https://musingsoniraq.blogspot...
Graham
Obliged if you could look back at Made Tech (LON:MTEC) and give your views. SP reaction surprised me a tad.
Thanks Jim, we've had a few reviews for that one so I'll be prioritising it. Cheers!
Gulf Keystone Petroleum (LON:GKP)
The oil is due to recommence flowing through the Kurdish pipe line in the next few days. Will the company share price start flowing as well?
I wouldn't believe anything agreed with Iraq until money actually starts flowing for a number of months. They've done everything to stall - they don't want the extra production and want Kurdistan to be kept on a tight leash.
Given the delays you are right to be skeptical Ben but the RNS seems to suggest a much better third party overseen process for receiving cash. The outstanding receivables have still to be agreed
Yes but you have to see this with Iraq's eyes. They don't gain anything by allowing Kurdistan production - they are already over their OPEC limit and Kurdistan's production will cost them more and more than that they hate Kurdistan. The only reason things may be moving would be because the USA is kicking and threatening Iraq. So far Iraq has used the strategy of stalling again and again.
If I am not mistaken I believe Gulf Keystone Petroleum (LON:GKP) are also owed a huge amount for previous production/exportation prior to the closure of the pipeline.
The geopolitical risk here is very high, but with risk comes rewards IF everything pays off. It's been a serial cash-cow in the past and I would hope it would return to big regular divi payments. But just in case I did sell out some of my holdings on the recent spike, but happy to leave the rest where it is and see what plays out over the next 3-6 months.
Hi Kevin
Gulf Keystone Petroleum (LON:GKP) has been paying big dividends despite the pipeline closure.
Yes they are owed a lot of money, and agree about Gulf Keystone Petroleum (LON:GKP) being a risky share in a risky area.
BUT BUT….despite the pipeline closure Gulf Keystone Petroleum (LON:GKP) have still managed to sell a lot of oil and even before the good news about the pipeline reopening they were paying an 11% dividend. Next pay day is Tuesday. Even now the share price has gone up a lot the current dividend yield is 8%. And there could be big dividend increases ahead.
See this link for loads of superb up to date info on dividend yields, pay days etc etc:-
https://www.dividenddata.co.uk...
The link above is for Gulf Keystone Petroleum (LON:GKP) where readers will see those 2024 and 2025/dividends, but it’s then well worth checking out the ex dividend dates and pay days for every share or Trust we hold.
I’ve held Gulf Keystone Petroleum (LON:GKP) for years (except for a while after the shock pipeline closure news) LON:GKP) It has proved to be a great income share and in the days before the pipeline closure plenty of capital gain too
Hopefully Kurdish Iraqi oil will replace Russian oil if Trump applies sanctions in the right places. I hold Gulf Keystone Petroleum (LON:GKP) .
Are we talking about the same Fracking Trump, currently arranging an attempt to jail Comey, who was sacked for investigating the suggestion that he may be Moscow's man in the Whitehouse...(:-))
Don't ask me, ask Mr Putin the friendly enemy.