Daily Stock Market Report (Fri 27th March 2026) - ASC, KMR, HEAD, GSK, HSP, FTC, CPI

Good morning!
The FTSE closed down 1.3% yesterday, as it continued to tussle with the 10,000 level.
This morning, it is set to open up 25 points, at around 9,995.
In war news, Trump has given Iran an additional 10 days to negotiate before he will approve strikes on their energy infrastructure.
Brent crude has been bubbling higher again, and is now back over $100. It’s up by around $30/barrel this month.
Israeli strikes on Iranian military assets continue.
So the mood music is still quite negative, but let’s try to find some positivity in the news today, if we can.
Backlog: there’s not much positivity in the backlog yet. I’ve given my views below on three shares that reported earlier this week. Please keep your requests coming, as we might be able to produce another couple of backlog sections today.
New writer: please give a very warm welcome to Dr. James Fox, who joins me in the DSMR cockpit today. James is a highly accomplished share analyst and stock picker, who holds a PhD in Development Economics, and we are lucky to get his perspective on shares today. Let’s try to make him feel at home!
Hanging up our pens there. Have a great weekend everyone and thank you for all the interesting feedback all week! And many thanks to James also for his maiden contributions.
Agenda
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
| AstraZeneca (LON:AZN) (£215bn | SR70) | Tozorakimab met OBERON/TITANIA primary endpoints | Positive high-level results from the Phase III OBERON and TITANIA trials in patients with chronic obstructive pulmonary disease (COPD) showed that tozorakimab reduced the annualised rate of moderate-to-severe COPD exacerbations compared with placebo. | |
GSK (LON:GSK) (£83bn | SR92) | The EMA has accepted GSK’s marketing authorisation application for bepirovirsen, a potential first-in-class treatment for chronic hepatitis B. The company’s phase III B-Well trials met their primary endpoints, with statistically significant functional cure rates versus standard of care alone. | AMBER ↓ (James) GSK has genuine momentum and on balance I believe the direction of travel is positive. The valuation is certainly not demanding – at a circa 30% discount to the global healthcare sector and a near 50% discount to AstraZeneca on a simple P/E basis. Improved operating margins and a solid balance sheet also point to this strength. However, there is a genuine patent cliff in the medium term, and investors will need to see more positive signs before the company closes the valuation gap with its UK peer. | |
Herald Investment Trust (LON:HRI) (£1.19bn | SR N/A) | Herald’s board confirms it’s still seeking a mutually agreeable solution with Saba, which would provide shareholders with a choice of outcome. A backstop tender offer will proceed close to the NAV if no agreement is reached. The board is exploring a tax-efficient structure to allow shareholders to remain invested in a non-Saba vehicle. | ||
Senior (LON:SNR) (£1.16bn | SR74) | Advent’s PUSU (Put Up or Shut Up) deadline for Senior plc is extended to 17 April 2026. Senior rejected Advent’s previous approach, which valued the company at 270p cash plus up to 2p final dividend. Discussions with Advent and other potential suitors are ongoing. | ||
Hargreaves Services (LON:HSP) (£236m | SR96) | Hargreaves is launching a £20m tender offer at a price of 850p per share. This represents a 16.4% premium to the current share price. The board recommends that shareholders vote in favour of the buyback. Shareholders may tender up to 7.12% of their holdings. | AMBER/GREEN = (Graham) I appreciate the shareholder-friendliness of this proposal, but I don’t think it should budge me from our existing AMBER/GREEN stance (see Roland’s comments here). Roland was AMBER/GREEN on HSP at a market cap of c. £240m in January. Since then, in March, the company has upgraded its FY27 revenue and PBT expectations by 4%. The share price is also up by 4% since then. I’m therefore going to trust our previous stance and leave this on AMBER/GREEN, while acknowledging that it’s a Super Stock with a StockRank of 96. | |
Cab Payments Holdings (LON:CABP) (£220.1m | SR46) | This is an announcement by the “Helios Consortium”: they already own or control 45% of CABP shares, and proposed to buy the rest of the company for $1.15 per share. They say that the rival offer from StoneX is not deliverable as they (Helios) will not agree to it. Also, the CABP Board is not cooperating with Helios as Helios attempts to put its own offer to CABP’s shareholders. | PINK | |
Seeing Machines (LON:SEE) (£152.3m | SR20) | Adjusted revenue $23.4m (H1 last year: $25.3m). Adjusted EBITDA loss $13.7m (H1 last year: $17.7m loss). Outlook: “...royalties from automotive production volumes are projected to rise significantly in the upcoming quarters... The Company continues to trade in line with market expectations..” EBITDA to be positive in Q3 and H2. | ||
Amcomri (LON:AMCO) (£83.5m | SR61) | Subsidiary GridCore has agreed to buy the National Compliance and Testing division of Enerveo for £1. Revenues in FY25 were £5m, net assets £1.5m. | ||
ImmuPharma (LON:IMM) (£22.9m | SR8) | IMM has received a Combined Search and Examination Report in relation to its UK patent application for P140, filed in September 2025. “The supportive response is as expected by management at this stage of the patent examination process and represents an important positive milestone in the ongoing progress of the application.” | ||
Parkmead (LON:PMG) (£26m | SR55) | Revenue £1.5m (H1 last year: £2.1m). Operating loss £1.2m. As of 26th March, the company has cash and term deposits of £16.1m. Outlook: “the Group is well positioned to take advantage of organic drilling in the Netherlands and to significantly advance its renewable energy portfolio. The year ahead is expected to see multiple growth catalysts…” | ||
Europa Oil & Gas (Holdings) (LON:EOG) (£16m | SR25) | EOG has received consent from the Irish government to extend the Phase 1 of FEL 4/19 to 31 January 2028. Will use the extension to carry out further technical studies and allow more time to secure a partner to advance development of the licence. |
Backlog stocks covered: ASC, KMR, HEAD, FTC, CPI.
Backlog
Asos (LON:ASC)
Up 13% on Wednesday to 239.5p (latest market cap: £278m) - Pre-Close Trading Update - Graham - RED =
This was a H1 update to the end of February/beginning of March.
It provided some reassurance to ASOS investors on Wednesday, after the stock had dropped by around 25% year-to-date:
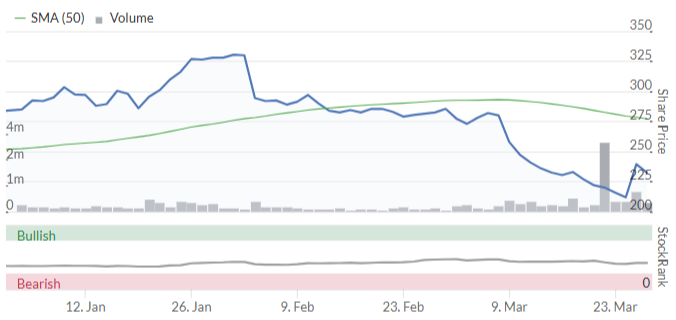
The company reiterated expectations for FY26. These expectations are:
Gross merchandise value “to show an improving trajectory throughout the year, 3-4ppts ahead of revenue.”
Gross margin improvement of at least 100bps to 48-50%.
Adjusted EBITDA of £150m-£180m.
Broadly neutral free cash flow.
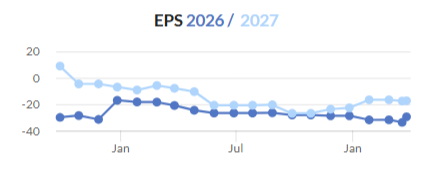
Despite the expected improvement in EBITDA, consensus forecasts say that ASOS will remain loss-making not just in FY26 but at least until FY28.
Some other key points from this update:
Gross merchandise value down 9% year-on-year. The company points to sequential quarterly improvements (from Q4 2025 to Q1 2026, and from Q1 to Q2) - surely this is problematic, given seasonality?
Adjusted gross margin +330bps YoY to 48.5%. This does point to a level of success for the new business model.
Graham’s view
The new business model includes more emphasis on the loyalty programme and on providing suggested outfits for customers, alongside lower inventories and fixed costs.
I have no problem with any of that - it sounds like they are trying to avoid head-on competition with Shein and Temu, which makes sense.
Where I do have difficulty is getting positive on a loss-making business, in a highly competitive industry, that’s also carrying significant debts.
Net debt was last seen at £185m having been reduced by the sale of 75% of Topshop.
Compared to EBITDA, the leverage multiple is therefore only a little higher than 1x.
For a business converting EBITDA into real profits, that’s a perfectly reasonable number.
But as things stand, I remain cautious. I just don’t see enough light at the end of the tunnel - do we think it’s going to be profitable in FY29?
Kenmare Resources (LON:KMR)
Down 11% on Wednesday (latest market cap: £172m) - 2025 Preliminary Results - Graham - RED ↓
Kenmare Resources plc (LSE:KMR, ISE:KMR), one of the leading global producers of titanium minerals and zircon, which operates the Moma Titanium Minerals Mine (the "Mine" or "Moma") in northern Mozambique, today announces its preliminary results for the 12 months to 31 December 2025.
This is an Irish mining company. We’ve had a couple of requests for me to look at it.
The shares have had a rough year:
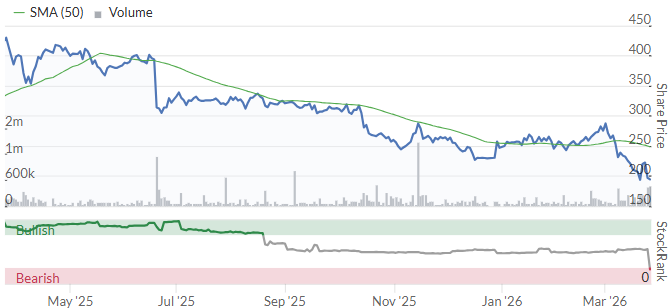
Overview:
Mineral product revenue of $312.1 million, down 20% year-on-year (“YoY”) due to a 13% decrease in shipments and a 6% decrease in the average price received for Kenmare’s products to $338 per tonne (excluding the by-product ZrTi)
Impairment charge of $301.3 million, inclusive of the $100.3 million impairment charge recognised in H1 2025… primarily due to lower future revenue projections associated with an uncertain pricing outlook and updated assumptions relating to the potential renewal terms relating to Moma’s Implementation Agreement (“IA”)
2025 final dividend suspended in light of elevated net debt and weak market conditions – the Board is committed to resuming dividends as soon as it is prudent to do so and financing facilities permit
The company has posted a loss of $23.7m, vs. a profit of $64.9m in 2024.
Net debt finished the year at $158.8m, up from $25m twelve months previously. This was “due primarily to peak capital expenditure during the year of approximately $156 million on the Wet Concentrator Plant (“WCP”) A upgrade project”.
They say that much lower capex is anticipated for 2026: only $60m, with “discretionary sustaining capital items being deferred where safe and practicable to do so”.
The kicker:
Kenmare is in discussions with its Lender group regarding adjustments to its Revolving Credit Facility (“RCF”), including amendments to covenant levels, in light of the prevailing weak market conditions
Q1 2026 update:
With Q1 almost complete, Kenmare is on track to achieve its 2026 guidance on all metrics and has begun drawing down its finished product stockpiles, in line with its value over volume approach
Graham’s view
Regular readers will know that I’m no mining analyst. I do not profess to be an expert when it comes to Kenmare, Mozambique or titanium minerals.
However, if I do attempt to look at it through the prism with which I study other companies, I’m afraid it’s going to be an automatic RED. The reason is that I’ve heard the keywords "discussions… lending group… amendments… covenants”.
Checking the interim results, I see that the company had equity of over $1 billion, fully tangible.
Even with an additional $200m of impairments, that leaves potentially c. $800m (£600m) of tangible equity. In theory.
However, I have no idea what the Moma Titanium Minerals Mine might really be worth. I do know that I try to steer away from companies that need debt covenant amendments, and an important purpose of our editorial colour rating is to highlight companies that we view as high-risk.
Therefore, while Kenmare might be an excellent long-term investment, the short-term financial risk requires me to put this on RED until further notice.
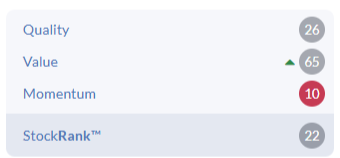
The StockRanks do not disagree with me, calling it a Value Trap with a SockRank of only 22:
Headlam (LON:HEAD)
Down 6% on Wednesday to 42.1p (latest market cap: £34m) - Full Year Results - Graham - RED =
Headlam Group plc (LSE: HEAD), the UK's leading floorcoverings distributor, today announces its full year results in respect of the year ended 31 December 2025 (the 'Period').
These results are terrible, as expected.
The company is loss-making even at the EBITDA level, both for 2025 and for 2024.
One rule that I follow is to be very harsh on companies that are loss-making even at the EBITDA level - if they are unprofitable even with a high level of adjustments and deductions, I have to think of them as either a turnaround or a startup, not a mature company.
2025 EBITDA is minus £12.5m, while the underlying operating loss is £33.4m.
Without any adjustments used, the pre-tax loss is a staggering £70m.
This triggers another rule I use: to be very careful when a company’s annual losses are higher even than its market cap.
In this case, the annual loss is double the market cap.
Net debt: the company has rapidly moved from net cash of £10.9m into net debt of £31.4m. They have a new asset-backed lending facility that is agreed until 2029.
Asset backing: this is the main source of comfort for investors here.
The Group owns property in the UK valued at £75m. Six properties disposed over prior two years at an average premium of 84% to book value
The £75m figure is the market valuation of the properties, not their balance sheet book value.
Looking ahead, here is an outline of their financial ambitions:
…our transformation plan will create a return to profitability in 2027 and then a return to historic midsingle-digit operating profit margin levels thereafter from the annualised positive benefit of these initiatives.
To fund the strategy and build balance sheet resilience, cash is expected to be generated from property disposals and working capital optimisation. We therefore expect to have significantly reduced Net Debt by the end of 2027 with further improvement thereafter.
They say “The new strategy, specifically focused on profit generation, alters the preceding narrative which was focused on revenue growth.”
The company lost its CEO and “Chief Customer Officer” late last year. It also lost its CFO last month.
The quote about “the preceding narrative which was focused on revenue growth” (rather than profitability) strikes me as a fairly strong repudiation of the strategy pursued by former management.
Graham’s view
We’ve been fully RED on this one since its profit warning in November, and I’m not inclined to change stance today.
My reasoning is similar to what I’ve already said about other stocks today: the company is loss-making, and is expected to remain loss-making for the foreseeable future (until 2027 at the least), despite the company’s plan to produce a profitable result next year.
If they sold all of their properties today for purported market value of £75m, that would eliminate all net debt and leave them with net cash of over £40m.
Deduct anticipated losses over the next year or two, and you are let with maybe £25m of cash, before any adjustments needed for working capital, etc.
Given the market cap of £34m, this could be an interesting deep value play.
Stockopedia has noticed the discount to tangible book:
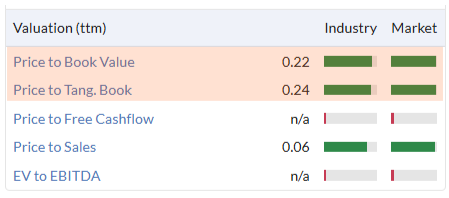
So this is a case where I think that over the medium-term, the risk:reward is potentially interesting.
I’m definitely open to the possibility of upgrading our stance on this to something a little bit less negative.
But in the short-term, I’m going to follow the simple rules that have served me so well: treating companies with negative EBITDA, and companies with annual losses higher than their market caps, with extreme caution. Headlam is an example of both.
Capita (LON:CPI)
Up 15% yesterday to 240.5p (latest market cap £326m) - Disposal - Graham - AMBER/RED =
Yesterday we learned that Capita was selling its private sector contact centre business:
This is a continuation of the strategic simplification of the Group, focusing on areas where we deliver complex, differentiated middle and back-office services in large growing markets where demand for technology-enabled transformation is accelerating.
Some highlights of the deal:
Disposal is priced at £1 (I wonder will that be cash or cheque?).
£6.5m of cash will be left within the business for the buyer, for working capital.
Potential defcon of up to £61.5m, depending on future financial performance and cash availability.
Value sharing with Capita if there is another change in ownership within five years.
The buyer is Inspirit Capital, a UK private equity firm.
It’s clearly a very defensive structure from Inspirit’s point of view: nothing up front, and little risk if it doesn’t work out, beyond any losses that may be incurred in the short-term.
Although those losses could be substantial, based on the historic performance of this contact centre division:
2025 adjusted revenue £398.1m, 2025 adjusted operating loss including overhead allocations £34.9m
Capita will be left holding “only three currently underutilised properties which represent a lease liability of 2025: c. £65m and an associated lease cost c. £10m per annum…”
Also, “c. £25m of Group costs previously allocated to the business will remain with the Group”.
That sounds pretty poor - and it suggests that previous accounting was rather misleading, although that’s not necessarily the company’s fault. Central costs do have to be allocated somewhere, after all. But it’s unfortunate these costs are not leaving Capita with the business that is being sold.
Another way of looking at it is that the adjusted operating loss isn’t real. Remember from what we pasted above: the 2025 adjusted operating loss “including overhead allocations” was £34.9m.
But it turns out that this £34.9m includes £25m of central expenses that are not going away even after the contact centre business is sold.
Therefore, the real loss that’s being removed might be somewhere in the region of £10m, depending on what other adjustments are involved.
That’s very different to removing an annual loss of £34.9m.
Also, there are “Expected transaction, transitional restructuring and separation costs in 2026 of approximately £20m”. Which removes much of the near-term value of getting rid of contact centre losses in the first place.
They do promise £40m of other annualised cost savings over the next two years, from the broader simplification agenda that they are working on.
Snippet from the CEO comment:
The sale of the private sector contact centre business further simplifies the Group and will enhance our margin expansion. It enables us to focus on Public Service and Pension Solutions and invest in our technology capabilities to improve our differentiation.
Graham’s view
I turned moderately negative on this share earlier this month (at a market cap of £360m) and I’m not inclined to change stance again so soon.
This deal probably is a net positive, as it gets rid of a low-margin, loss-making, unexciting business, and simplifies the overall group.
But I’m not convinced it’s going to make all that much difference to the balance sheet or to their net profits in the near-term. Capita is having to spend money to save money, and will rely on the £61.5m defcon to get a favourable outcome.
Please see my comments from earlier this month for a bigger picture view. I do not see any fundamental change arising from this disposal, although the removal of £400m of empty revenues will at least help to improve the clarity of the story it’s able to offer investors in future years.
Our rankings categorise this as a Sucker Stock:
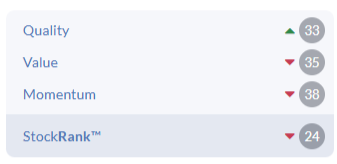
Graham's Section
Hargreaves Services (LON:HSP)
Up 7% to 761p (£252m) - Tender Office and Notice of General Meeting - Graham - AMBER/GREEN =
Hargreaves Services already said they were doing a £15m return of capital.
They are proceeding with this, subject to shareholder approval, and have upsized it to £20m.
The tender price is 850p.
Naturally, the company will not be able to buy back all that many shares at 850p. At that share price, £20m would buy 2.35 million shares.
The company has 33 million shares outstanding, so the tender offer can reduce the share count by 7.1%.
This is the logic behind each shareholder having an “Individual Basic Entitlement to tender approximately 7.12 per cent. of the Ordinary Shares held by them..”
It’s an attractive tender offer, compared to the prevailing share price. Indeed, HSP hasn’t been over 850p in over a decade.
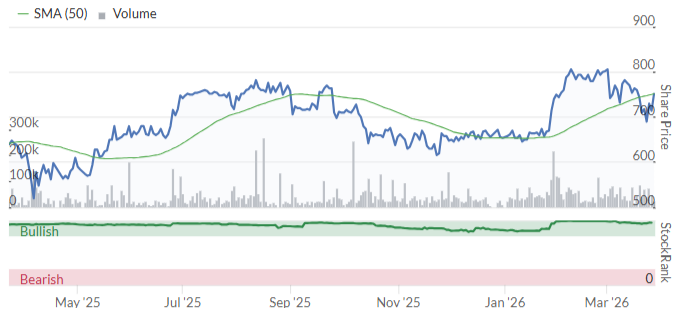
That being so, I would expect the majority of HSP shareholders to tender their full basic entitlement. For every shareholder who doesn’t do that, it will enable others to sell more than their basic entitlement.
This is a share within the Harwood stable - they own 27.9% of the company, and have undertaken to tender their basic entitlement.
Graham’s view
I appreciate the shareholder-friendliness of this proposal, but I don’t think it should budge me from our existing AMBER/GREEN stance (see Roland’s comments here).
A tender offer, in general, is an excellent and perhaps under-utilised mechanism. I think of it as a buyback that’s simply more formally organised than what you get with on-market purchases. Shares are repurchased at a fixed price and in a fixed amount.
In some ways it’s fairer than on-market purchases, as everybody knows when they are transacting with the company and gets exactly the same price for their shares.
Roland was AMBER/GREEN on HSP at a market cap of c. £240m in January.
Since then, in March, the company has upgraded its FY27 revenue and PBT expectations by 4%. The share price is also up by 4% since then.
I’m therefore going to trust our previous stance and leave this on AMBER/GREEN, while acknowledging that it’s a Super Stock with a StockRank of 96.
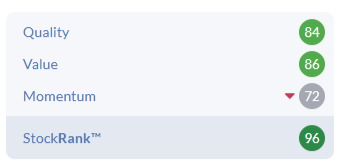
James's Section
GSK (LON:GSK): (LON:GSK)
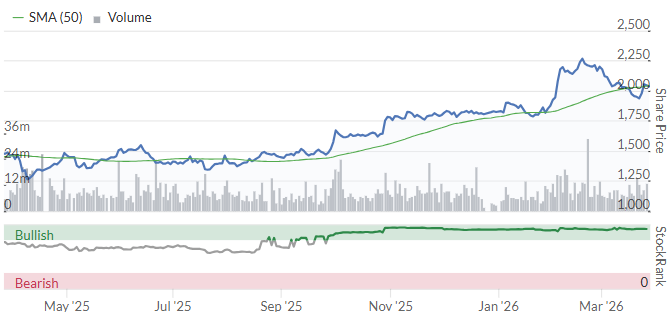
Down 0.4% at 2,047p (£83.1bn) – Bepirovirsen accepted for MAA review by EMA – James - AMBER ↓
Today’s announcement was unlikely to be a market move – we heard in January that Bepirovirsen had achieved its primary endpoint in trials.
However, this is a company that seems to have genuine operational and market momentum right now – and that marks a significant shift from where we were a couple of years ago.
FY25 headlines
- Revenue £32.7bn, +7%
- Core operating profit +11%
- Core EPS +12% to 172p
- Oncology +43%, HIV +11%, Specialty Medicines +17%, Respiratory, Immunology & Inflammation+18%
2026 guidance: sales +3-5%, core EPS +7-9%.
The aforementioned momentum has probably gone under the radar, but GSK has now delivered eight consecutive quarterly earnings beats. Revenue has also come in above expectations in every quarter since the split with its consumer healthcare division – now Haleon.
A snapshot of the StockReport from three years ago shows just how far the company has come. The operating margin (%) has improved 234 basis points over the three-year period, while the return on equity (%) is up 480 basis points. This is reflected in GSK’s QualityRank score of 97.
It is worth noting that 2026 guidance was set before the conflict commenced in the Gulf in late February. There could be unquantified headwinds if the conflict is sustained.
Key momentum drivers:
· Oncology is growing fast from a small base. New CEO Luke Miels has been acquisitive early – RAPT Therapeutics ($2.2bn) and 35Pharma ($950m) both bolster the late-stage pipeline.
· Cabenuva – the long-acting HIV injectable, grew 42% in 2025 and is taking share from daily oral competitors.
· HIV pipeline remains highly compelling, with Q4M treatment addressing 30% of patients and Q6M 50% of patients. Cabenuva is administered every one or two months.
“Products are the key in this business, and we need to be more product-centric...”
Sound footing
The Zantac-related overhang is now “materially complete” with GSK settling for $2.2bn – significantly lower than many had been expecting. This allows us to look at the balance sheet with greater clarity, and it’s worth noting that net debt/EBITDA sits at just 1.3x, leaving ample firepower for further bolt-on deals.
Dividends (forward yield sitting at 3.5%) are well covered by earnings (around 2.6 times), further supporting this idea of financial strength.
Broadly, its valuation grades remain strong, with the forward P/E representing a circa 30% discount to the wider healthcare sector globally.
James's view
I don't hold GSK. I find pharma and biotech highly exciting, but it’s also a sector that carries significant operational risk. The risk of a late-stage trial failure, a patent cliff, or an unexpected safety signal means position sizing matters as much as stock selection.
And this is something to bear in mind here. As much as 50% of GSK’s 2025 revenue are threatened by patent expiry in the medium term, and that puts pressure on the company’s pipeline to perform.
The company has four phase III readouts scheduled for H2, and investors will want to see continued execution before the market delivers a re-rating.
For context, it trades at a circa 50% discount on a simple earnings-basis to AstraZeneca, implying that there would be room for a re-rating if pipeline optimism improves and is sustained.
While not directly comparable, AstraZeneca says it has 197 projects in the pipeline – GSK notes 58 potential new vaccines and medicines in their pipeline.
Filtronic (LON:FTC) (backlog story)
Down 0.8% at 180.50p (£400.6m) – $8m amplifier contract win – James - AMBER =
Yesterday’s contract win – an $8m agreement to develop and manufacture amplifiers for satellite communications for an American client – is another positive step for Filtronic. While modest in isolation, it’s a company that appears to have found its moment.
FY25 headlines:
Revenue £53.6m, +121%
Adjusted EBITDA: £17m +248%
Net cash £6.8m (excluding right of use property lease)
Filtronic designs and manufactures advanced RF solutions for the space, aerospace, defence, and telecoms infrastructure markets. Ironically, it went under most investors' radars until April 2024 when it announced a strategic partnership with Elon Musk’s SpaceX.
The partnership, expanded in FY25 and again in FY26, has resulted in the largest contract wins in the company’s recent history. This $62.5m (£47m) contract complements additional wins the likes of Leonardo and Airbus.
Visibility looks really strong for a relatively small company too. The business pointed to approximately 90% of FY26 revenue covered by contracted orders. Meanwhile, Filtronic is set to launch net-gen GaN amplifier systems in calendar year 2026, including an expansion into V-band.
The forward picture may disappoint some investors, however. Management expects to meet current market expectations of £55.5m in revenue and £10.9m in EBITDA for the year.
“With a record order book, increasing customer diversification and the business now operating at greater scale, we have entered the second half confident of continuing our planned growth.”
James’s View
There are very few sectors that excite me more than space right now – equally there are very few companies I want a slice of more than SpaceX. Coupled with rising defence budgets and resilient aerospace demand, Filtronic looks exceptionally well positioned.
Of course, everything comes back to the valuation. At 50.1x forward earnings and 7.5x sales, the business looks richly valued given the current forecast, which essentially shows revenue remaining flat throughout FY26.
I think most would agree that it’s not meaningfully undervalued on current forecasts.
As the $62.5m contract with SpaceX is due to be delivered in FY27, there will almost definitely be a meaningful uplift in revenue next year. My view is that uplift needs to be sustained in order to justify the valuation as we see it today.
Investors also need to consider concentration risk. SpaceX, for example, is very good at doing things in-house.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

76 comments
Calamity for Burford Capital (LON:BUR) as shares crater following US Court of Appeal decision to overturn verdict in YPF case. Thank goodness I sold my shares last October.
Huge fall in the Burford share price - presume some negative case decision but not looked into it. I used to hold a significant position but sold up a while ago as it never delivered - the ultimate jam tomorrow share. All the litigation funders have been disasters
NEW YORK, March 27 (Reuters) - A U.S. appeals court on Friday struck down a $16.1 billion judgment against Argentina for seizing control of state-owned oil company YPF (YPFDm.BA), opens new tab in 2012, a victory for Argentine President Javier Milei as he tries to stabilize the country's long-strained economy.The decision was issued by the 2nd U.S. Circuit Court of Appeals in Manhattan.
Argentina had been seeking to overturn the $16.1 billion award in September 2023 by a lower court judge to former YPF shareholders Petersen Energia Inversora and Eton Park Capital Management for alleged losses tied to YPF's nationalization.
The natural gas chart is looking interesting for a possible break-out to the upside, and hedge for a share portfolio. Gareth Solway is excellent on charts. It's pretty much the only commodity to not have exploded at this point. Anyone any thoughts?
S&P500 is close to confirming a breakdown to the next support of 6,100 as well. It's all getting quite bearish but only a minor correction so far.
It's all kicking off with the 10-yr yield in the UK briefly above 5% today, but now just under https://tradingeconomics.com/u.... This will be on the news no doubt as it is a first since 2008!
Wonder if the B of E were called on to get it below 5%
A lot is talked about fundamentals on this site which is great, but as a trader I pay even more attention to the technicals. So I thought ( for anyone interested) I would show you how and why I enter and exit a trade.To not put a finer point on it I personally will never buy a stock unless the technicals are in my favour as I expect to be in profit within a very short period of time ( if i have got it right) hopefully within minutes. As an example I am showing Journeo as this appears to be a popular stock.
If you look to the left it had a great run respecting the 10 MA perfectly ( a great sign of strenght) I had missed this run but now on my radar. Look at the 1st buy point a textbook VCP and look at the really tight( circled) small candles coupled with the volume drying up. This matters as its saying there is little activity between buyers and sellers meaning if it goes up it will probably bolt. The volume goes up and you have your classic pivot point. I see a great opportunity. Potential stop just below the previous days low wick end, as Im not taking any chances( not all trades work). It does as expected and hoped and immediately in profit. As it breaks into new highs I see a point to add, after all a profit is already on the table. Soon after peaking it breaks a MA it was previously respecting. At this point Im looking to preserve profits, Im not here to gamble with profits! take some profits off the table and give the rest a chance. After breaking the 50 Im out. You now see a great shakeout below the 50. This is good as it will put weak holders off from buying. A great wick , followed by an upside reversal the next day . Another great buy point. Another run but then fails to go much beyond the previous high (a possible sign of topping) De risking at that point by taking some of the table . As it breaks the 50 again exit as previously it went a bit below it. I would now see this stock as risky as it tested the highs twice. Infact it goes to test a 3rd time later and drops after that. It then tests the 200 intially with success , but im already put off by the topping now seeing the trade as risky. Note how now on is latest drop the MA is now a ceiling. Previously on its inital run it was support.
The Market knows more than we ever will, and the market sets the price. But good to combine a bit of both methinks hence Stocko to check not making a big mistake.
Just to clarify the picture above was not showing the 50 MA ( apologies). This is the right one below where you can see the upside reversal on the 50. Also just to clarify meant to say the 21 MA breaches were my exit points not the 50. All the the MAs shown are SMA except for the 21 where I use the EMA. I do not use any other indicators. I keep it simple. Green is 10 SMA, yellow 21EMA, red 50 SMA, black 200 EMA
Our annual Mello event is back on the 2nd & 3rd June in Chiswick, West London. 400 investors, 50 companies and 2 days full of investor networking and ideas.
Full event details: MELLO 2026
We will have keynote talks from Christopher Mills (Harwood Capital), Georgina Brittain (JP Morgan AM), Richard Staveley (Rockwood Strategic), Lord John Lee and more. Former Ideagen CEO & Exec Chair, David Hornsby will also be interviewed on stage... Many will remember Ideagen as an AIM market star, delivering over 600% returns in seven years before its £1.1 billion sale in 2022.
Beyond the keynote talks, we will have 40-50 companies delivering investor presentations and exhibiting in our main hall. We have already announced the likes of Abingdon Health (LON:ABDX) B.P. Marsh & Partners (LON:BPM) Harbourvest Global Private Equity (LON:HVPE) Rockwood Strategic (LON:RKW) and Works co uk (LON:WRKS). Many more will follow...
We will also have our ever popular BASH (Buy, Avoid, Sell, Hold) panels on both days featuring investors such as Leon Boros, Paul Scott, Mark Simpson and many more. The Mello Team will be pulling out all the stops to make this as great a Mello event possible. I hope to see as many of the Stockopedia community at the event with us... I am sure there will be many familiar investor faces attending.
There is nowhere better to chat through stocks, investing strategies and cover so many companies in one place.
Tickets are still on early bird for another few days (Just £59 for a one day pass or £89 for a two day pass).
If you miss the early bird, use code Stockopedia25 for 25% off General Sale & Final Release tickets: https://www.melloevents.com/mello2026
See you in June for Mello2026, it is going to be an excellent two days for investors!
PS. we have about 15 spots left for companies... if you have any suggestions, we will do our best to entice management to join us.
Hi David,
In the spirit of self interest here are some suggestions for companies you might consider inviting to Mello Chiswick, if you haven't already done so. Needless to say I hold them.
Fintel (LON:FNTL) Anpario (LON:ANP) Journeo (LON:JNEO) Johnson Service (LON:JSG) Pebble Beach Systems (LON:PEB) James Cropper (LON:CRPR) Sabre Insurance (LON:SBRE)
All the best
Thanks Jonno. We will do our best to get along management from the above. Fintel & Journeo have been Mello regulars over the years and we do speak to all those you have mentioned to encourage them to meet investors f2f.
Hopefully we can get a couple of them along to Chiswick.
Personally i think the news is good. Why would Trump give the Iranians another 10 days unless he didn't want to bomb their power plants? I think Trump wants the war to go away.
BTW
The Iranians said that they would take out all the de salination plants lining the Gulf if he did this. Making the Gulf states uninhabitable, causing a massive refugee crisis.
Personally i think the news is good. Why would Trump give the Iranians another 10 days unless he didnt want to bomb their power plants?
US troop mobilisation to the Gulf is expected to be complete in between 10 and 20 days time. He needs to buy time to get them in position. The troops being moved aren't enough a full ground invasion so this would be a more limited campaign, either to secure Kharg Island and / or the Straits of Hormuz.Of course all previous US administrations were fully aware that the Iranians could choke off supplies through the straits, but it seems not to have occured to this one that if they were going to attack Iran they needed to have options to address the issue. It's the wartime equivalent of small boys football: lots of shouting and running about but no actual strategy.
Bottom line is that it's too early to say how this will pan out, but some form of US ground operation is possible, maybe even likely. They're not moving 7,000 soldiers as part of two amphibious ready groups from Japan and California plus the 82nd Airborne Division for fun.
From Trump mostly likely this is belt and braces: negotiate on our terms or we'll remove your negotiating power. But there are an awful lot of risks in this: Iran could still retaliate by attacking desalination plants or oil infrastructure. Escalation is only an itchy finger trigger away: who is in charge of Iran's military right now? And however it pans out it's unlikely there'll be much stability in Iran for years to come.
Put it this way: I'm not making any scaled bets on any particular outcome. The uncertainty here is real and I'm surprised markets haven't reacted more violently.
timarr
Great thoughts thanks. Maybe there is a strategy - a common thread from Venezuela, Cuba, Panama, Syria and now Iran is a black molecule and the red dragon. The US cannot fight in Europe, the Middle East and Taiwan at the same time, there is a short window in which to shut down Iran and nobody on any side is saying that's a bad thing (except the IRGC and mullas). But they have such tyrannical control over the country (fear of torture then death) that I can't see anything rising up to change matters.
I'm sure China and the US can get along without a fight, but unfortunately some countries get subsumed - History. Will have to leave that to next weekend, working on my Chemistry degree this one.
Hi Timarr,
Fully agree with your thoughts on the movement of US troops to the Gulf, The obvious conclusion, which may or may not happen is that delusional Donald intends or wants the option to put American troops on the ground. How that will pan out I have no idea, but I suspect will go down like a lead balloon in the States.
What a mess. Trump has opened Pandora's box. We all now has to live with the consequences.
The maga's are still generally behind him Jonno a lot of them are as crazy as the mullah's running Iran I think for a lot of these deep red states in their mind the civil war never ended.
Its got a bit of that early covid feeling for me Tim where markets took it in there stride for week then wallup all be it this has been a small (ish) decline over the last month so far.
If we get a repeat of 2022 then I can only think of oil and money market being positive anyone know if there is a dollar index etf as that might do okay also.
Hi TP
If we get a repeat of 2022 then I can only think of oil and money market being positive
If we're looking at higher oil prices, higher inflation and interest rates - and that's not guaranteed - then oil, commodities in general, CPI linked investments (e.g. HICL Infrastructure (LON:HICL) or Greencoat UK Wind (LON:UKW) ) and possibly gold (although if interest rates stay elevated then that'll take the shine off it).
Cash is great for short-term optionality, but obviously a losing proposition in the long -run. When uncertainty is elevated as we see at the moment there's no harm in sitting back and waiting.
The real downside here is if this leads to a permanent rise in the price of oil and gas, as we saw in the '70s, as that's a real drag on economies and could lead to a rolling bear market. Most likely that won't happen which makes the current depressed state of the market a careful buying opportunity.
I've been cautiously dipping back into the market this week - Genuit (LON:GEN), ICG (LON:ICG), Mortgage Advice Bureau (Holdings) (LON:MAB1), Intertek (LON:ITRK) and Craneware (LON:CRW). Buying into the teeth of the gale is never a comfortable experience, but in all of these you're buying at a significant discount to where we were a few weeks ago. If the dip is purely a Trump induced derangement then that'll correct as and when he decides he's had enough fun bombing things, and if his little excursion turns out to have longer term effects then, well, none of these companies are going to go bust soon and the sell button is always available.
Working out the possible paths forward here is impossible, ask any two experts and they'll give you a different answer. So assume the worst and hope for better,
Still don't see how the US comes out of this well though. What a mess.
timarr
Agreed Tim I really thought they would have taken heed from the mess Russia has got itself into in Ukraine and not make the same mistake.
WIth the age of drones yes a superior air force can bomb the hell out of a country but all you need is thousands of willing foot soldiers with flat back trucks and you can launch from anywhere. By all counts Vlad thankfully won't be profiting as much as he hoped as Ukraines long range drones are now hitting the oil fields Vlad thought were WAY out of range.
I do wonder if Trump will just tell the U.S military to go home and leave the gulf states and Europe to clear up the mess he's made it amazes me how these nutters time after time end up in positions of ultimate power.
Personal opinion at some point he will be recognised as one of the worst presidents in U.S history and he will certainly be leaving the world as a much more dangerous place than before he took the wheel.
This is all highly educational. Water as a critical asset (yup), salt (UK about to be no longer able to grit the roads, or make chips (potato variety, or any vegetable actually) palatable). Oil and gas (thought Millibund and Greta had sorted that out), Rare Earths (the name says it all).
Geography highly relevant (the non-straight straights) - oh and today Helium raised its head on a podcast. Not just party balloons but massive in semiconductor production, space tech, cooling, MRI equipment and quantum computing (cooling again).
So Saturday after some chores I'm getting a Masters Degree in Chemistry (:))
Fun fact (sic)- the Hindenberg was designed for Helium mined in the US, but Uncle Sam did not want it used in war machines (naughty naughty Germans) so they ended up with Hydrogen (YouTube spoiler alert - it did not end well).
Welcome to Dr James Fox.
Thank you :)
Dr Fox is Ed's AI chatbot investment guru - so you need to ask a question (cleverly crafted) :)
This year, we will be running an extra one-day Mello investor conference for all to enjoy. Hopefully as many of the Stockopedia community will be able to join us on the 22nd April as we head to Birmingham. We have already announced the first ten companies to be joining us in Birmingham and we will have many more to announce in the next few weeks
The investor day will feature up to 30 UK listed companies, investment trusts and funds. We will also have a number of keynote speakers, educational sessions and of course our popular BASH (buy, avoid, sell, hold) panel to round off the day. There will be plenty of investors, both familiar and new, to meet up and share your investing thoughts/stories with.
Paul Hill will be starting off the day with a breakfast talk to cover a number of stocks and the market in general. Mello will try to attract as many companies to attend, present and engage with investors. If you have any company management teams you would like us to approach, suggestions are always welcome and we will do our best to get them to Mello Birmingham!
Full details and a link to tickets is here: MELLO BIRMINGHAM
Location: The Burlington Hotel, Birmingham City Centre, B2 4JQ
Date: 22nd April 2026
Stockopedia Discount Code: MBStockopedia25
We do try and head out of London with our Mello events and hope an event in Birmingham will be well received. Hopefully as many of the investors on Stocko can support us with this one-day Mello in Birmingham and we can make it a great success and run many more for you in the years to come!
Please feel free to use this thread for any suggestions and question for the team and our Mello Birmingham event.
https://www.melloevents.com/mellobirmingham
I know this thread is mainly focused on shares.... but since its Friday.... any thoughts on the rising govt bond yields globally?
We haven't quite had a full blown panic on them - but is it a case that everyone's too distracted about the house on fire, to realise the volcano next to the town is about to erupt?
And the "real world" implications - consumer lending, business financing, etc.
Haven't really heard much in the media about this. But again, is this because of the oil price focus/distraction? Whereas the knock-on effect on govt rates is also an important story but overlooked?
Good morning Boon, what a difficult question to answer? With the rise in Oil 10 year yields have increased 50bps give or take in most places in expectation of higher rates to combat the inflationary impact. The issue therefore poses the immediate question of whether Oil prices will remain high or fall back soon. A resolution to the straight issue needs to be tabled with broad agreement between Mid East - US - China and Europe. Never the less it would be reasonable to expect Oil to stay elevated so not quite neutralised by a positive resolution ....and so slightly positive for inflation. Watching Andy Haldane yesterday he thought Oil < $150 was manageable but a longer period here or higher starts to creep into cost structures and wage negotiations. This suggests resolution is positive for Bonds and less need for rate rises. Thus the Oil spike holds the economy back and does not feed cost push inflation. The comments from the ECB were more forceful suggesting they want to extinguish any inflationary impact without hesitation. This would mean higher for longer on rates and more of a negative. The US is an interesting one.... on balance I think they will resist pressure to raise but more ambitious rate cutting agendas have to be tempered.
What does all this mean? Well the negative consequences of the conflict are already there and so yeah....the equity market appears to have his fingers crossed whereas the bond market has adjusted to the new normal. With resolution they probably meet in the middle so some rebound in Bonds and falls in equities yet to be seen. My tour of UK equities yesterday .... many traditionally defensive sectors like tobacco, food retail and pharma aren't really performing as strongly as you would expect. I think these moves can still be seen and think performance should improve. The Dollar remains quite well bid and for me that needs to weaken before markets can normalise and recovery plays emerge. For now you are right that bond moves and equity resilience don't quite make sense.
Thanks for the long comment! It spurred me to go do some more reading over the weekend.
I've not heard the word "stagflation" thrown around yet... but it seems to describe what might be a more and more likely scenario? Your comment about the ECB suggests it'll be Europe for sure. Maybe the UK and USA will hold or lower rates instead of temptation to raise to conquer inflation. Although that might create problems bigger than stagflation...
Boon do you think this might be part of what is feeding through in the Finance sector? Some fairly big drops from companies like S&U (LON:SUS) , Funding Circle Holdings (LON:FCH) and Time Finance (LON:TIME) even where results have been at least half decent. Have only picked out these as I either hold or see on Screens I run. REITs are generally impacted too but I accept that is primarily down to higher interest rates and their yields not looking so tempting given their business risks.
I have been particularly surprised by the drop in Funding Circle Holdings (LON:FCH) given they hit next year's targets and are due to update forecasts.
I think financials are struggling due to the flattening yield curve since the ME crisis, this will compress NIM if it stays this way or flattens further.
Interested to know what your flatter measure is? 2-30s spread looks higher to me as does 2-10s but by less...so I don't see much flattening apart from less expected cuts at the short end. The real problem I see in the US is inflation data worsens anyway due to the back book later in the year.
At the end of Feb the U.K. gilt 10-2 spread was 82bp vs ~40bp today
yep apologies hadn't realised it had got quite that high..... but 40-50 seems more normal.
I had a thought specific to Time Finance (LON:TIME) when thinking about this.
So they don't reveal NIM, but lets assume its 2% to 3%.
At the moment, bad debt is 1%. So that's great - they make the extra 1-2% spread as profit.
When interest rates rise though, the NIM stays the same. Time gets funding from wholesale, so they are charged higher cost of funding. They'll naturally pass on as much as they can to borrowers, but its a competitive market, so NIM probably isn't going to expand.
However, at higher interest rates, businesses are more likely to get into trouble. So that 1% bad debt rate will rise.
Lets say Time's NIM is 2% and bad debts rise to 1.5%. That's a halving of the lending income at Time, and a much steeper fall in operating profit (after fixed costs).
This is obviously a very simplistic view from me, and I have never worked in lending or commercial banking... but I have this risk in my head on Time.
"We haven't quite had a full blown panic on them - but is it a case that everyone's too distracted about the house on fire, to realise the volcano next to the town is about to erupt?"
The effects are already being felt. Mortgage rates have increased and in turn we are seeing a decline in Housebuilding stocks. A sector that looked cheap is becoming even cheaper.
Other sectors which could be affected are those with unsecured or poor quality lending. REITs which usually move in relation to interest rates have also declined noticably,
Depending on your view of the world, these types of stocks have either good entry points or are falling knives.
You might like to listen to the latest Financial Times 'Unhedged' podcast, 21 mins - "The rout in UK and European bonds What rising yields mean for everyday people" if you can find it.
Sorry, i listen to it on my mobile and i can't find it on my laptop to give you a link, but there's a transcript at https://www.ft.com/content/b60a258a-b08b-4a1c-aa88-2c4d54cc0d2c?shareType=nongift
Thanks for this recommendation - also didn't realise FT had a podcast called Unhedged! Now followed for future episodes...
Last weekend,'s FT covered it quite well!
This fella is very good on macro and interest rates Boon , personally think we will see a repeat of 2022 bond yields will rise, stocks down general view seems to be damage is now baked into the economy moving forward even if the war stopped and straight reopened next week.
&t=930sHi Graham, any chance you could cast an eye over Alternative Income REIT (LON:AIRE) ? They put out final results within the last couple of weeks but are now subject to a takeover bid although the share price has barely moved... (I hold their shares).
And welcome to Dr Fox!
re: AIRE. I'm sorry Richard, I don't study REITs very often and I won't be able to get around to looking at this one! Apologies.
Thank you - Understood!
Supermarket Income REIT (LON:SUPR) and Safestore Holdings (LON:SAFE)
you are wise young Graham.
Dr James Fox, your have joined a great team with Roland, Graham and others. I think that the reason that they have such great respect across all the community (even the prickly ones :o)) is that they steer clear of the motley fool style clickbait that seems to litter the internet. Welcome aboard.
Seconded! Dr Fox, if you read these comments and have a moment, it would be great if you could tell us a little more about yourself and your investing journey, for those of us that are meeting you for the first time. I hope it won't be your last visit to these shores.
Thanks for the warm welcome.
Of course... happy to introduce myself. I've been an investor all my adult life and like to think I'm very systematic and disciplined. My focus is on investments that may be temporarily undervalued on a growth-adjusted basis and typically within sectors with secular or structural tailwinds. In recent years, I've been most interested in opportunities around AI, compute and industrials (not on my own there), but I still have diverse holdings across leisure, consumer, banking etc. I also like to think I've learned to treat that discomfort as a signal rather than a reason to step back.
More broadly, I worked at the European Bank and briefly as a journalist while writing my PhD (development economics). I also produce written work elsewhere on the www, edit a marketplace sector journal, and train AI.
Look forward to learning more about you and interacting more going forward :)
Thanks so much :) Really kind and appreciate the comment
Harbour Energy (LON:HBR)
Another secondary placing at Harbour - this time 80m by BASF.
Seemed like another buying opportunity to me so I topped up - but risky.
A.
Alot of debt? But will pay that down quickly at these oil prices, fste100 entry possible june
Hi Graham. I like your market opening / status summary at the beginning of each daily report.
You have made me laugh with this statement:
"So the mood music is still quite negative, but let’s try to find some positivity in the news today, if we can."
Promptly followed by 3 company analyses with a RED colour rating! LOL ;)
I think I'm becoming numb to the bad news at the moment.
Haha, I realised too late that it was three REDs.... hopefully that's not representative of what happens when I respond to reader requests!!
I particularly like the comment yesterday that the market background is "fluid". Understatement!
A ‘crude’ comment methinks.
Wish I’d paid more attention to geography and geology.
Dear Dr James Fox, good morning and welcome. Had you been raising your cash ratio anticipating problems and are you a bear or a bull now?
Good morning and thank you! Of sorts, I had increased my take of 3 and 6 month Gilts and I'm gradually putting that money to work as they mature -- I have a long-term thesis and I like to think this is a good opportunity to build positions accordingly... even though it might be choppy :)
Lots of stuff is on sale if you ignore the Orange Moron. Hard, I know.
Gilts free of CGT, of course.
Not the coupon, only if you make a capital gain
Hi Graham, can you take a look at Hercules (LON:HERC) . Earlier in the week they issued '
Delay in Final Results and Temporary Suspension'
Maybe profits "took a haircut".
Looking for positivity, and you hit us with Red, Red, Red :-).
Can you find any positivity is the Hargreaves Services (LON:HSP) rns. As I read it, they will pay me 850p for my 715p shares, but I will be lucky if they buy 7% of my small holding. Wouldn't just paying a special dividend been easier?
Dividends are taxed at high rates of tax so I prefer this way to reward shareholdes for their excellent management
Hi GloucesterBob, as already noted, the big difference with a tender offer vs. a dividend is the tax treatment of capital gains vs. income! You should have a basic entitlement like everybody else, no? G
@Dr James Fox. Good morning and a warm welcome. As a stock picker if the market sentiments suddenly changed to positive, what criteria would you use to target the stocks that you believe would see the greatest positive reversal?
Those with relative strength since the the ME war began
Hi, Momentum Trader and thank you :)
If the reversal in sentiment were driven by the end of the conflict and normalisation of supply chains (especially energy) I'd expect the greatest turnaround to be in those sectors directly impacted by fuel prices -- airlines, cruise liners, companies with contracts relating to flying hours etc (JET2, AIR, CCL, MRO). I appreciate that's not overly nuanced, but these are obviously areas where the pullback has been more pronounced.
In my opinion, there are other opportunities too with stocks that were undervalued on a relative basis before the war being caught up in the correction. One example could be SANM at 12x forward earnings, which looks cheap compared to a former favourite of mine CLS at near 30x.
At the same time, this market appears to forget quickly... and we're whipsawing from trend to trend. Memory selloff this week, but wouldn't be surprised to see them rebound next week.
These are just my thoughts. Would be great to get yours too!
Thank you for your input, much appreciated. I agree that sectors impacted by fuel prices could see a reversal as sentiment ultimately drives the market. I personally would also be looking at stocks that were quick to react with volume when Trump gave the impression that a deal was on a few days ago. Stocks that have resisted the drop and are showing good relative strenght I would also be interested in. I would further look to Identify stocks that are among the first to break out of their bases and make new highs as the market turns.
Hi Graham, complicated share to analyze, but could you take a look at Capita (LON:CPI) announcement to dispose of its private Contact Centre business yesterday. Cheers!
second vote for capita!
I talked to an ai: "... so they are only really shedding 15m costs?"
£40m annualised savings promised
Less £25m stranded costs that stay with the group
Net real saving = ~£15m (and that's spread across 2026-27, so perhaps only £10m benefit in the near term)
And that's before the £20m cash cost to achieve those savings, which essentially wipes out the first year or two of benefit entirely.
So the headline "£40m savings" is quite misleading. The market may have taken that number at face value in the initial reaction, but the net benefit to the continuing group is far more modest. Combined with giving away £398m of revenue for £1, you've essentially handed someone a large business, kept the overhead, and called it a transformation.
The contingent £61.5m is the only scenario where this looks genuinely value-accretive — and that's entirely dependent on Inspirit turning around a business that Capita itself couldn't make profitable.
... the last sentence means cpi seems to lack some key skills an outsourcer really should have or there isnt a good chance of seeing that 60m
I think the point is that everyone valued the contact centre at zero anyway. It would have been a multi year turnaround with negative FCF for years to come. So disposing it and paying the buyer £6M while having the option of taking 40m of cost out and potentially receive the £60m of contingent consideration is a positive for Capita
The market can now hopefully focus on the remaining divisions (Public Services & Pension) and value them appropriately even though they should trade at a discount to Serco and XPS pension.
What about the total net lease benefit of £26.2m. Both you and Graham seem to have totally ignored that.
Done, Nurzel! G
Thanks Graham
Thanks Graham
Futures up, more positive spin from Trump. We shall see...crazy times!
Trump's pressure points index working -- oil price and Treasuries near November mid-term election danger for Republicans. He Taco's.