Daily Stock Market Report (Fri 28th November 2025) - SRB, MAB, QED, CFYN, ESYS

Good morning!
I'm hoping to catch up on some company news that slipped through the cracks over the last few days.
I'm afraid I've run out of time - have a great weekend all.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our View (Author) |
|---|---|---|---|
Mitchells & Butlers (LON:MAB) (£1.53bn | SR83) | SP +10.5% Strong trading ahead of the wider market, like-for-like sales +4.3%. Adj. operating profit +5.8% (£330m). Solid start to FY26, like-for-like sales +3.8%. | AMBER (Graham) [no section below] | |
Metals Exploration (LON:MTL) (£324m | SR98) | Channel sampling has outlined an extension to the initial Phase 1 North pit at La India of a minimum of 100 metres up to potentially 300 metres. High-priority drill programme planned. | ||
Quadrise (LON:QED) (£60m | SR9) | SP -8% “Whilst progress during 2025 overall has not proceeded as expected, the Company closes the year in a stronger position, with a clearer path towards commercialisation and the resources in place to achieve this.” | RED = (Graham) [no section below] This is an "energy transition technology company focused on the decarbonisation of shipping and heavy industry through deployment of low carbon fuels and biofuels". Their technology is supposed to produce a synthetic fuel oil or biofuel by mixing residuals oils with a specialist chemicals. I've had to be RED on this due to the lack of meaningful revenues and the resultant consistent losses. Today's update describes progress at various projects: trials in the marine sector, and a timetable for the payment of $1.5m to QED for licensing and equipment it provided in Utah, etc. Unfortunately it remains at a very early stage of its development and so I must remain RED. | |
Serabi Gold (LON:SRB) (£201m | SR99) | Unaudited interim results for the three and nine-month periods ended 30 September 2025 | Gold production for the first 9 months of 2025 of 32,634 oz (same period in 2024: 27,499 oz), positioning Company on track for full year guidance. Post-tax profit for the 9-month period of $34.9m (same period in 2024: $17.8m). | AMBER/GREEN = (Graham) I'm a sceptic here when it comes to valuation, and I do have some questions about rising administrative costs where I'd love to hear an explanation from the company. However, I am going to leave our moderately positive stance unchanged as the stock does enjoy strong momentum and a very high StockRank, and I'd be more comfortable if someone who covers the stock more regularly was the one who gave it the downgrade! |
Facilities by ADF (LON:ADF) (£17m | SR39) | New CEO appointed, starting in January. She was CEO of Picnik Entertainment. | ||
B90 Holdings (LON:B90) (£17m | SR37) | All current revenue is derived from partners and customers located outside the UK. As such, these duty changes have no impact on B90's business model, financial guidance or operations. The company continues to trade in line and full-year results are to be “consistent with, or ahead of expectations”. | ||
Caffyns (LON:CFYN) (£13m | SR50) | SP -10% Revenue falls 2.7% to £134m (2024: £138m). Underlying pre-tax loss £0.81m (2024: profit £0.45m). CEO: "The motor retail market was particularly challenging in the half year to 30 September. We have responded by making a number of operational changes to improve performance." | AMBER (Graham) [no section below] This share has been knocking around for a long time, but it has been tough to make money in motor retail. Profits have been minimal (or non-existent) since 2023, despite over a quarter of a billion pounds of annual revenue. Gross margin fell and then labour costs rose from April 2025: with a low-margin business, small changes in costs have an outsized effect on profits. It could be argued that the additional £0.5m expense from minimum wage and higher NICs is responsible for the majority of the £0.8m H1 loss. The primary attraction of this share is probably £30m of balance sheet net assets, which is almost fully tangible amd includes freehold premises. But the stock is controlled by the Caffyns family through 2,000,000 preference shares, each of which has a vote (there are only 2.7 million ordinary shares). Value could get unlocked here some day but it's anybody's guess when that might happen. | |
essensys (LON:ESYS) (£10m | SR23) | SP -9% | BLACK (profit warning) (RED =) and PINK (takeover situation!) |
Graham's Section
Serabi Gold (LON:SRB)
Up 5% to 277.8p (£209m / $276m) - Unaudited interim results - Graham - AMBER/GREEN =
Most days, I avoid talking about the gold sector, but let’s try it today.
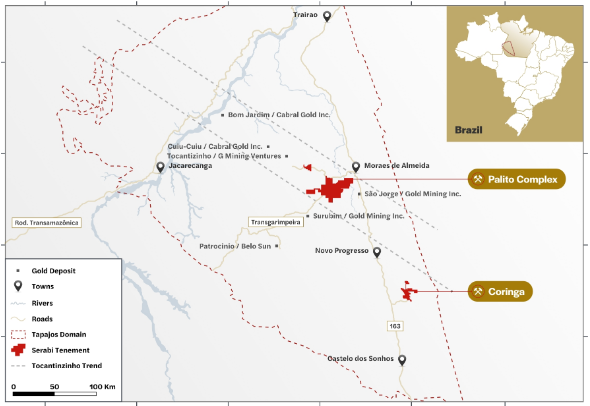
Serabi is a Brazilian gold miner: here’s a map of its operations in the Tapajós region in Northern Brazil:
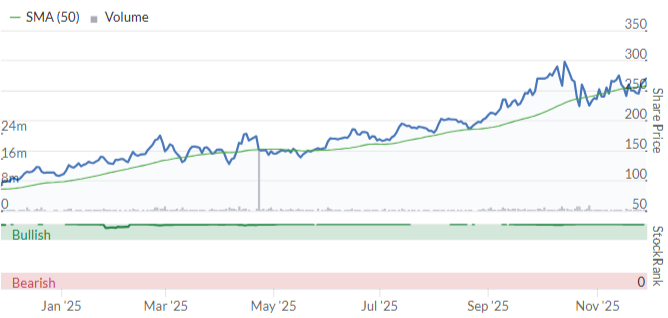
The share price has nearly trebled over the past year; and it’s a ten-bagger since 2023:
So let’s check out these interim results:
Q3 production 12,090 ounces, year-to-date production 32,634 ounces (up 19% over the corresponding nine-month period last year).
Post-tax profit for the nine-month period of $34.9m (nearly double the result for the corresponding period last year: $17.8m).
The figure given for “net cash inflow from operations” ($34.3m) matches well with the post-tax profit figure. That’s after spending $4m on mine development.
The average gold price on sales ($3,244 per ounce) is up 39%, with a leveraged impact on profits.
The All-In Sustaining cost was $1,816 per ounce, only slightly higher than the same period last year.
If I naively take the difference between the average sale price and the AISC, I get $1,428 of profit per ounce, versus only $548 of profit per ounce last year.
Serabi’s Net cash improves to $33m. There is a $5m loan with Santander in Brazil, charging 6.16% (sounds impressively low to me).
CEO comment:
“The nine months to 30 September 2025 have delivered strong financial and operational performance for the Company placing us firmly on track to meet full-year guidance…
On exploration:
In parallel, exploration and resource development drilling continued across both the Palito Complex and Coringa, with approximately 27,937 metres completed year to date. Early results are encouraging, supporting the Company’s objective of increasing resources to the 1.5-2.0Moz range in the oncoming years as part of Phase 2 of our growth strategy.
Graham’s view
I’m bringing a fresh set of eyes to this company, and don’t claim to have any particular expertise.
One thing that jumps out to me is that quarterly administrative expenses have risen 60% year-on-year. On a 9-month view, they are up 50% (to $8.2m).
This is much faster than the growth in AISC per ounce (cost to produce an ounce), and it’s also much faster than the growth in ounces produced. Of course, given the rise in the gold price, you could argue that it’s not too relevant. But clearly the central cost overhead is rising rapidly.
Looking for an explanation in the commentary, I don’t find anything too specific, although the company does refer to “inflationary cost pressures”, and they also say that “Reported revenues and costs reflect the ounces sold in each period”. I’d like to have a better understanding of this $8.2m spend - does it include exploration spending, for example?
It might seem odd that I’m honing in on this item, but I think it makes sense to focus on costs rather than revenues - miners don’t control the gold price, they can only control their costs and how much they produce in a given period.
When it comes to production, I would assume that Serabi is faultless: there’s been a very pleasing trend of increased production.
When it comes to cost, the AISC looks great, but I do think that the admin costs deserve more details when the annual report is published.
And the other big question is longevity - how long will the company’s assets continue profitably producing?
I find the following table in the 2024 annual report:
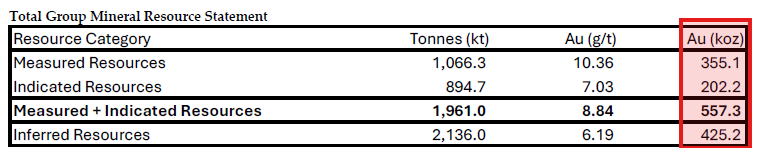
With 12,000 ounces being produced in the most recent quarter, this suggests an impressive number of years of life left, e.g. production at 50,000 ounces per year would take 7 years to deplete the company’s measured resources.
Of course I would assume that the cost profile is likely to change (increase further) over time, and that production will slow down at some point.
But I think that this table implies Serabi has above-average longevity for junior miners.
Mark was AMBER/GREEN on this in August, and he also had some questions about costs.
I’m happy to leave this on AMBER/GREEN: I don’t have enough conviction to change our stance on my first write-up of the stock.
It does enjoy a StockRank of 99:
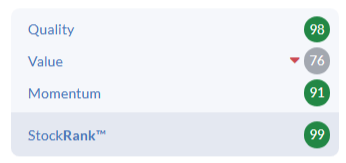
And a cheap earnings multiple - although personally I don’t think that any wasting assets, such as mines, should be valued on the basis of an earnings multiple. Earnings multiples should be reserved for companies with long-term earning power:
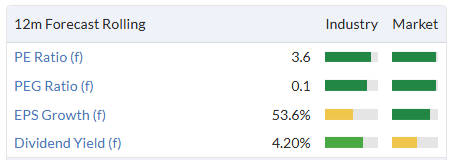
In an ideal world, I’d value a stock like this based on its book value, but that doesn’t make sense either, seeing as the gold price has surged higher.
If I tried to stick to something objective like free cash flow, I don’t get a massively impressive answer: year-to-date there has been $38m of net cash inflow from operations, offset then by $4.1m of mine development expenditure, $6m of PPE, $6m of exploration, and $7m of pre-operational project costs.
In the end, there’s a $16m cash inflow for the 9-month period, which doesn’t seem all that high to me, compared to a market cap that’s equivalent to $276m.
So I guess that makes me a sceptic when it comes to valuation here. I could see myself cashing in gains if I was a shareholder - but that same instinct would have prevented me from enjoying the gains that the stock has already achieved. It still enjoys very strong momentum, and a rising gold price can keep it going. So who knows?
When I did invest in gold miners (I owned Orosur Mining (LON:OMI) a very long time ago, also a South American gold miner), I quickly learned that cash profits were not being delivered to shareholders. Cash profits were instead being spent on development and exploration: this are perfectly logical activities for a gold miner to spend money on, but from a shareholder perspective, it felt like my winnings were being reinvested into more lottery tickets, and eventually I would lose. This is why I abandoned the sector all those years ago, and it's one of the reasons I've missed out on a 10-bagger here.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

48 comments
It does seem very strange to have a tax-free savings scheme that taxes part of the contents.
You could put cash into Amundi Smart Overnight Return GBP Hedged (LON:CSH2) ETF in your ISA - low risk and you get about a 4% return. Easy to buy and sell in bulk EDIT Meant to reply to TopInvest
I am guessing that that product is exactly what the Chancellor is looking to tax .
Amundi Smart Overnight Return GBP Hedged (LON:CSH2)
in which case there goes my cunning plan..
Serabi Gold (LON:SRB) the last annual report suggests that operating expenses have increased due to increased activity in the Coringa prospect
More stupid red tape and complexity from Rachel Reeves: your cash holdings will be monitored and charged a fee in a stocks and shares ISA. No more holding too much cash for a suitable entry point. Presumably if you are holding 60% of your portfolio in shares that would be easier, but I suspect that is far too straightforward when someone can design something much more complex and burdensome!
https://www.telegraph.co.uk/mo...
Would have thought that'll be nigh on impossible to police. A daft idea, as the rates on cash in S&S ISAs are generally uncompetitive anyway.
More stupidity from Rachel Reeves:
Restricting cash ISAs to £12,000 and then allowing people to hold £8,000 in cash in a Stocks and Shares ISA would be irrational, to say the least. In terms of not allowing cash holdings it's close to a reversion to the pre-2014 rules.
The problem is that this does very little to encourage stockmarket investment, which was supposedly the aim.
timarrPresumably only for under 65's ??
I can see HL, AJB et al really looking forward to wasting an awful lot of time making those calcs for people trading in an ISA where their cash balance alters every day!
Agree it is stupid but much depends on how long one can hold cash before HMRC think it's too long. Will it apply only to new cash subscriptions or to include dividends received as well. The former is manageable by drip feeding as and when required but the latter might be a problem as the amounts may not be economic to invest without waiting to accumulate a larger sum.
I have taken to putting spare cash into low coupon gilts within a non ISA share account. No CGT and negligible interest on which to pay tax.
Is there a big sign in the Treasury that says "what else can we find to tax?"
Agree it is stupid but much depends on how long one can hold cash before HMRC think it's too long.
It seems the approach will be to tax at source - i.e. all interest income in an ISA will be taxed at the standard rate and reported to HMRC in the normal way, so that if you don't declare it you'll get a bill.
In the end the argument is over nothing very much - why would anyone hold cash in a Stocks and Shares ISA for the interest if they weren't trying to circumvent the new rules, which are intended to encourage people to invest in the stockmarket?
And if you're not holding cash in a Stocks and Shares ISA for the interest - e.g. because you're perma-convinced the market is about to crash and want to keep a healthy cash balance just in case then presumably this doesn't matter much?
It often seems that people here only see matters through the lens of their own self-interest, but ISAs are a mass market product mainly for people who don't handle their own investments and are probably the best investing product in the world. I can happily live off the income from my investments while occasionally making a sale of some investment at an insane profit. All tax free, benefiting from over 30 years of using my ISA allowance.
What's not to like?
timarr
Fair comment Tim.
As an example, a pal of mine who is not really interested in the whole investing scene set up an ISA 2 or 3 years ago. Has accrued £800 of interest on a stake now totalling £30k. With say a 2% interest received that gives £16 a year to tax. At say 20% that really isn't worth the admin to collect is it? And if it does happen he won't cry about it. He does plan to sell a couple of things and reinvest all of the balance so that is only a transient position. Let's hope they take a pragmatic approach.
I wouldn't say the UK stock market has been delivering 'insane' profits over the last 25 years.
And after this budget the likelihood of 'insane' profits in the future are very low.
I wouldn't say the UK stock market has been delivering 'insane' profits over the last 25 years.
Neither would I. However, as there's no geographical restriction on ISAs that shouldn't have hindered investors building up substantial capital gains benefits.
That said, there've been plenty of great UK stock performers - I've saved several years of retirement income through avoiding CGT in ISAs through Goodwin (LON:GDWN), Games Workshop (LON:GAW) and Cerillion (LON:CER) alone.
The Stocks and Shares ISA is a fantastic investing vehicle, particularly for longer term patient investors, and anything that can be done to encourage people to use them for stocks instead of cash is to be applauded. I just wish the Chancellor had gone further.
timarr
i could have sworn they said they would be slashing red tape too - with impendig mtd 3 monthly returns for sole traderes and landlords they due appear beyond gormless - that without me trying to be unkind. she was questioned by marin lewis about how they would tax people on basic state pension and not much else - all she could say is we are working on it - ie i dont have a plan or a clue.
Surely under current rules there would be nothing to stop someone opening a Cash ISA with £12k max and then a S & S ISA with the £8k balance and then shortly afterwards closing that and transferring it to the Cash ISA?
Do you know if this will apply to money market funds also Topvest ?
topvest: Yes fiddling and piddling away the economy.
These sort of daft rules indicate that the MPs who thought them up has never run a business or any organisation for that matter.
Graham says " most days I avoid talking about the gold sector". If you are dispassionate you could have followed the trend and done very well in the last 12 months. Unfortunately, I have the same bias and my only holding is CAPD! If you look at the Momentum stocks which have done well...gold. Some people do not want to buy "defence" stocks; others "tobacco"; others "oil and gas". I will try to be dispassionate on anything from now on! Your point on admin costs is valid imo!
Re Serabi Gold - I hold
Good to see coverage on Stockopedia. There are some risks which holders need to keep in mind..
When a gold miner starts to make decent profits it attracts a lot of attention, some of it not that positive for investors. The Government of the country may decide that it wants a bigger slice of the action.
The long running saga of Barrick Gold trying to regain control of its assets at the Loulo-Gounkoto complex is a case in point. Nothing to suggest that is likely to happen in Brazil, but worth consideration.
Regarding the increasing costs at Serabi, I notice that there was a presentation at Mello. Was this increase explained?
Slightly off topic but quite interesting...
Article on Citywire suggests that the Department for Energy Security and Net Zero is briefing against its own Government Policy on the subject of renewable subsidies and the possible switch from RPI to CPI.
https://citywire.com/investmen...
The thrust of the article is that it will hardly save consumers any money off energy bills but would seriously undermine investment (and profitability) in the sector.
I am not sure if this PR approach is wise as it makes the sector, which is now quite mature, look permanently reliant on subsidies without being able to deliver any meaningful price benefits to the consumer.
There is a good discussion on the Investment Trust thread on the subject of renewables.
It is discussed on the thread Intuitive. I have been having a dig and looks like the report will not be out for 12 months, which I find hard to believe. Foresight Environmental Infrastructure (LON:FGEN) today quantified that if it was removed/reduced it would affect NAV by 6p- which in the scheme of their discount to NAV , 37% is not a huge blow. The industry, AIC and I assume other are submitting to the enquiry- closing date is the weekend I understand. As an environmentalist I think the renewables is an important sector, but understand Gov cash is tight. Will a reduction in subsidies improve efficiencies- maybe !
Current Quarterly gold price for Q4 is up another US$ 500 per ounce. Mostly dropping to the bottom line.
Suggests current share price is too low.
Hi Graham, it was pleasing to see you take the bull by the horns and take Serabi Gold (LON:SRB) apart this morning. I have held since 2021 and have added whenever there was money to spare. Missed the August 2023 price of 21.5 pence opportunity due to stated reason but have never sold, giving me a current 2-bagger. The likelihood of a maiden dividend is greatly increased by today's news so I'm a happy shareholder looking to the future.
Hear hear - seeing Graham commenting on a gold miner... who would have thought! I have been a happy holder of Serabi Gold (LON:SRB) over the last year, and nice to see the price action still responding positively to news.
I was analysing the market yesterday, and saw that there were 41 stocks that have doubled this year (above a £10m cap). I'll be doing a big StockRanks annual review piece at some point in December. Wish I'd bought Altyngold (LON:ALTN) like my youngest son +399%!
Hi Ed, I had kept an eye on Altyngold but dismissed the idea of getting some shares as I think Kazakhstan is too close to Russia for comfort, also I lost a lot of money with Polymetals International. Again, I got out of Anglo Asian Mining (LON:AAZ) , for the same reason (Russia) but at a profit, just before that took off. I also watched Thor Explorations (LON:THX) which I think beats Altyngold but couldn't resist buying in when it became obvious that this company is unstoppable.
Ed, you should add Greatland Resources Greatland Resources (LON:GGP) to that list - share price was the equivalent of £1.26 on 2nd January, and is now £3.75 making an increase of 297%. I hold.
Mitchells & Butlers (LON:MAB) The stated increases in sales would, given inflation in the pub hospitality sector, seem to imply a reduction in footfall and/or average spend per customer.
Mitchells & Butlers (LON:MAB)
The stated increases in sales would, given inflation in the pub hospitality sector, seem to imply a reduction in footfall and/or average spend per customer.
You have lost me
Strong trading ahead of the marketb with like-for-like salesa growth of 4.3%
Like-for-like salesa continued to outperform the marketb
Note i dont trust these companies to not pick stats that suit their narrative - ref footfall that could be down if prices are up 5% - but if lfl are up 5% surely either footfall or spend per customer must be up - if not both both up ?
Let’s assume that the past customer base was 100,000 customers who each spent £1k pa. Company’s annual turnover is £100m.
Annual inflation adds 8% so to ‘stand still’ company has to increase annual turnover to £108m. However, company trumpets that it has raised turnover by, say, 4% to £104m.
Therefore, company has either reduced customer numbers, because the ‘stand still’ spend per customer would have to be £1,080, and/or seen a real terms decrease in spend per customer. (1,000 customers spending £1,040, which is below the ‘stand still’ rate of 1,080).
Mitchells & Butlers (LON:MAB)
but is 4.3% not higher than the curent rate of inflation - so up in real terms and not down ?
plus they said they were doig better than the market - so if on average companies are delivering sales increases 0.1% above inflation they are doing better than others (well per their definition that is)
perhaps they have stated they have upped prices by 8% - if thats the case i agree with your assessment of the position. If thats the case though is that not still acceptable - eg if sales are going up in real terms and you are delivering less sales well that can aid keeping costs down. Yes no one wants to have lower net spend or less footfall - but is the 4.3% quoted number not the the main important stat?
I made the point, in the initial note, that inflation in the pub hospitality sector, is running well ahead of inflation. If, like me, you visit pubs from time to time you will have seen marked increases in the cost of drinks and food over the last year.
I suspect that the 'hidden message' in today's announcement is that whilst they may be doing better than most, all are in a shrinking market with, potentially, no one growing in relative terms when pub inflation is taken into account.
If, like me, you visit pubs from time to time you will have seen marked increases in the cost of drinks and food over the last year.
i am the exception to the rule - i was in the pub last night and it was £4.06 total for a pint of worthies and 6% maxim - must admit i did move onto the 7.5% Growling Dog 7.5% Tropical IPA - that was £6.40 for 2 decently sized cans.
I do get your point now that price inflation is probably higher than their sales increases (did they confirm tat ?) - so yes zero numbers game in that that would be less volume served.
Crimson Tide (LON:TIDE) is a microchip share at a current Quote of 74p. Stocko shows it as having traded 1 share today. What is the likely explanation for such a pointless transaction or is it more likely an error?
SRT Marine Systems (LON:SRT) I hold
"SRT Marine Systems plc ("SRT"), a global provider of maritime domain awareness systems and technologies for security, safety and environmental protection SRT is pleased to confirm and remind interested parties of the scheduled Investor Open Day and AGM taking place on Thursday, 4th December 2025 at its headquarters in Midsomer Norton, Bath, UK, starting from 09:00am.
Everyone interested in SRT is welcome and encouraged to attend. The event is open to anyone interested to learn more about SRT and its activities and operations and does not require prior registration. The day provides an opportunity to see our operations, experience live product demonstrations and meet and chat directly with many of our staff and all Board members. The open day is between 09:00am and 10:45am, with the formal AGM and Board presentation starting from 11:00am at the nearby Centurian Hotel. Coffee and home-made cakes are provided throughout the morning and a buffet lunch.
The address of our headquarters is: Wireless House, Westfield Industrial Estate, Midsomer Norton, Bath, BA3, which is located approximately 10 miles south of Bath. There is ample free parking for those driving. For those travelling by train the nearest station is Bath Spa which is a 20 minute taxi ride away. The nearest airport is Bristol airport which is approximately 20 miles away."
I see that Cavendish has a TP of 122p on SRT. Their forecast is £115.8m revenue (£78m) and PTP £10.2m (£5.2m). If Simon can expand on that , fine by me. Unfortunately I cannot make the AGM and will rely on others to give us feedback. I have heard that an analyst has visited recently and came away comfortable with progress. I look forward to all the feedback from private investors who can make it. Looking at the Momentum stock list SRT is not there ....yet. What dos it take to receive that accolade?
Graham can you review the latest results from Serabi Gold (LON:SRB) :
SCI20, I will make an attempt!
Thanks Graham.
More than an attempt Graham! Thank you for excellent review with your usual level of detail and balanced opinion.
I did my best, but I'm not the expert - Mark and Roland are both more informed than I am on this one! Cheers anyway. G
The large increase in admin costs I would assume are linked to all of the investigation work ongoing which was talked about in a fair bit of detail at Mello. There seemed to be a lot of plans to develop the various areas around the current holdings, which I am sure will cost a fair bit. Can't remember the detail. I am sure one of the current holders who attended the Mello presentation will be able to add more.
The numbers from the latest RNS for Serabi Gold (LON:SRB) were predictable, as the gold price, costs and production levels are all known factors. They are still very positive though and show how cheap this gold miner is at current gold price.
What is interesting is that the current estimates for full year profits assume a similar Q4 profit to Q3, but this is likely to be higher as the gold price is substantially higher now and production is likely to be too. My back of the envelope calculation is a full year profit 10% higher than current estimates. Gold price is increasing too.
Serabi Gold (LON:SRB) is my biggest single position so obviously I am biased!
@SRB Agreed, good looking results A couple of interesting numbers - it looks as if EPS will be about double last years but the AISC at $1890 is quite high compared to say Thor Explorations (LON:THX) who have higher production and an AISC of under $1000. I hold both.
A slightly unusual year with these stocks doing so well with the market. Normally you get the luxury of thinking they will come good if markets struggle .... yet this time the metals have benefited from liquidity and therefore might struggle "IF" liquidity trends reverse. Personally this makes these stocks much less defensive for me... but it goes without saying they generate oodles of cash if metal prices hold current levels. I have moved on for now and will reassess if conditions change.
As they noted at Mello - open pit miners like Thor have much lower AISC than underground miners like Serabi; it's more expensive to do it this way. Their AISC seems in line with underground contemporaries.
Thanks for catching up on mobico yesterday...
Hey, you're welcome Chris!