Daily Stock Market Report (Fri 29 Nov 2024) - EAH, PEEL, NTBR, TIFS, CFYN, NANO

Good morning and welcome to Friday's report!
I'd quickly like to send a huge shout-out to everyone who contributed to the report this week (Megan, Roland, Mark and Keelan) for producing so much content while I've been under the weather. These reports would have been far thinner and less interesting if they hadn't done so. Cheers!
1pm: today's report is finished. Thanks for dropping by.
Explanatory notes
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day. We usually avoid the smallest, and most speculative companies, although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We have a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Add your own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing. Links:
Daily Stock Market Report: records from 5/11/2024 (format: Google Sheet).
Companies Reporting
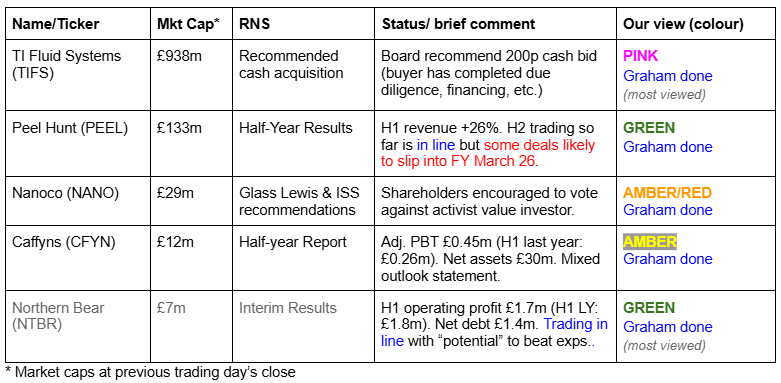
Summaries
Peel Hunt (LON:PEEL) - down 2% to 106.25p (£130m) - Half-year Results - Graham - GREEN
Today’s outlook statement could be interpreted as a mild profit warning, as revenue in the pipeline is likely to slip into the following financial year. However, there are no official market expectations for this stock. I am encouraged by 26% revenue growth in H1 and remain hopeful that IPO and fundraisings may recover in the medium-term.
Northern Bear (LON:NTBR) - up 8% to 54.75p (£8m) - Interim Results - Graham - GREEN
Strong results with 83% of full-year EPS already in the bag as NTNR heads into the seasonally more difficult and usually quieter H2 period. I’ve thought NTBR was cheap for some time and in the absence of the share overhang that was affecting the stock until June, perhaps its valuation can improve.
Short Sections
ECO Animal Health (LON:EAH)
Up 6% yesterday to 69.5p - Interim Results - Mark - AMBER/RED
There seems to be a big mismatch between how Eco Animal Health view themselves:
…a rapidly growing global animal health company
And how their customers view the demand for their products:
Group Revenue decreased 13% to £33.2 million (H1 2023: £38.0 million)
This means losses are increasing:
Loss per share of 2.50p (H1 2023: loss per share: 1.93p)
This is despite capitalising significant amounts of R&D:
Research and development ("R&D") expense and amounts capitalised were in aggregate a cash investment of £4.1 million (H1 2023: £3.6 million).
Which means their cash balance is decreasing. Although it remains significant:
Cash balances decreased to £18.3 million (30 September 2023 £20.6 million)
However, only £6.9m of that cash is held outside of China:

They have managed to get cash out of China recently, subject to a 5% dividend tax. However, they also say:
On a day‐to‐day basis, the Board considers the cash held in the Group's joint venture subsidiary in China to be unavailable to the Group outside of China; accordingly, cash management and funds available for investment in R&D is based upon the cash balances outside of China.
Personally, I’d exclude this from any valuation. After all, it can be hard to ensure corporate interests are aligned when it comes to partially owned foreign subsidiaries.
Broker Equity Development say that these interims point to a stronger second half. Indeed, they will need to be to hit forecasts. They also say that the adjusted EBITDA outlook is reiterated. However, adjusted EBITDA is not a sensible measure for a company that capitalises so much R&D. Nor is EV/EBITDA a good valuation metric including cash in Chinese JVs.
No doubt, management will point to a payback on that R&D at some unspecified point. However, this is outside of any reasonable forecast window, so we have to go with what we have. A forecast P/E of 34 and no dividend:

Mark’s View
Graham gave this an AMBER when he looked at it following the profit warning in October given the potential for that R&D spend to generate future products that may improve the business prospects. However, for me, with those benefits appearing out beyond any reasonable forecast window, and the risks associated with Chinese subsidiaries and JVs, it is an AMBER/RED.
TI Fluid Systems (LON:TIFS)
Up 2% to 192.4p (£981m) - Recommended Cash Acquisition - Graham - PINK (takeover)
Perhaps this is just a formality, but I wanted to mention that the takeover of TIFS at 200p has been finalised with due diligence and documents complete (see coverage in October). Now shareholders will need to vote on it.
35% of shares have promised or indicated that they will vote for the deal to go ahead, so I would say that it’s likely to proceed. Completion is expected during the first half of 2025.
This one spent most of its life on the stock exchange below its 255p IPO price:

I withdraw my AMBER/GREEN stance as I expect the takeover to go ahead.
Caffyns (LON:CFYN)
Up 6% to 449p (£13m) - Half-year Report - Graham - AMBER
Another tiny company finds its way into today’s report. This is a group of car dealerships in Sussex and Kent run and owned by many Caffyn family members.
Today’s interim income statement is not the most important part of today’s announcement, in my view. There is £450k of underlying operating profit, including £140k from the sale of a personalised numberplate.
What I really want to point out is balance sheet equity of £30m, including freehold properties at 16 of their 18 locations, so that the stock is trading at less than 50% of NAV.
Normally I’m inclined to take a positive stance when I see this, but I should also point out that the company has been availing of temporary banking covenants after it generated a loss in the previous financial year. It is expected to return to normal banking covenants in June 2025.
Additionally, it has a pension deficit, based on accounting rules, of £7.6m (down from £10m at the beginning of H1). This is already taken into account in the NAV calculation, and may not be a problem, but it does suck cash out of a business whose profitability has not been reliable in recent years.
For these reasons I’ll cautiously take a neutral stance on this one for now, but others may wish to investigate it in more detail.
Nanoco (LON:NANO)
Down 2% to 14.65p (£26m) - Glass Lewis and ISS recommendations - Graham - AMBER/RED
I’ve been AMBER/RED on this stock due to excessive cash burn - see coverage in August.
The company’s position is that it is exploring “an orderly sale of the Group’s trading business (including IP)”, with the goal of continuing to return surplus cash to shareholders.
Its cash balance was £20m as of July 2024, and it then spent £3m to finish a share buyback. The cost base is £6m.
The current controversy relates to an attempt by a Cayman Island-registered fund (“Milkwood”) to appoint two people to the Board of Nanoco. Apparently - according to the Chairman of Nanoco - Milkwood’s intention is to retain surplus cash and convert Nanoco into an investment company.
Today’s news: the two main proxy advisory services, ISS and Glass Lewis, who advise institutions on how to vote their shares, have both recommended voting against Milkwood’s resolutions.
Graham’s view: Milkwood only owns 8% of Nanoco and my instinct is that investors are more likely than not to organise against them so that cash is returned rather than retained in the company. But I don’t know which way the vote will go.
I’m leaving AMBER/RED on this as, like Milkwood, I have doubts about the inherent value of the underlying business, and the stock is now trading at a premium to its shrinking cash pile. Let's see if they can sell the underlying business for a decent price.
Graham's Section
Peel Hunt (LON:PEEL)
Down 2% to 106.25p (£130m) - Half-year Results - Graham - GREEN
I left this on my best ideas list for two years running. Despite reaching 140p a few times, it hasn’t held onto these gains:

Today’s interims show some progress:
Revenue £54m (+26%)
PBT £1.2m (H1 last year: £0.8m loss)
Adj. PBT £4.6m (H1 last year: £0.5m loss).
Unfortunately I don’t think the adj. PBT measure is worth emphasising, as it excludes share-based payments which are a real cost.
While I’m on that point, some observers may be put off investing in this when they realise that staff bonuses have eaten over 70% of available PBT.
I have sympathy with that point of view but I think the point of investing in Peel Hunt is to bet on a recovery in the IPO market - not on a continuation of the conditions that produce results such as today's.
According to EY, there were only two IPOs in London in Q3: one on the Main Market and one on AIM.
With thanks to EY who created these charts, here is the historical fundraising picture for the Main Market:

And here is the historical fundraising picture for AIM:

I don’t think it’s an exaggeration to say that both IPO markets have been dead since 2022.
Is this a “new normal”? If it is, then I’m wrong to have Peel Hunt on my best ideas list.
But I still find it hard to believe that current conditions are representative of the future.
I do expect that the very largest firms may choose the US over London for the foreseeable future - e.g. European fintech Klarna (value c. $15 billion) has chosen to list in New York.
But for small-caps and mid-caps, AIM and the Main Market should remain strong contenders, in my view.
Let’s turn back to Peel Hunt:
Net assets are an impressive £95m, covering a large chunk of the market cap, and only £2m of this figure is intangible.
CEO comment (emphasis added):
"We were able to capitalise on improving market conditions in the first few months of FY25, most notably executing two IPOs, collecting material M&A fees and generating increased trading revenues.
However, the recovery slowed over the summer period and investor sentiment was impacted in the last few weeks of the period due to concerns around the UK Budget, particularly in relation to AIM.
We welcome recently proposed policy initiatives, including pension reforms and HM Treasury's call for evidence to support a growth and competitiveness strategy for UK financial services, which are designed to increase investment and liquidity in UK risk assets."
On market conditions and fundraisings, Peel Hunt notes that despite a year-on-year increase, “overall activity remains below historical averages” (no surprise there).
They say that “IPO activity appears to be gradually resuming” although I'm not sure exactly what they are basing this on.
On bid activity, they note 19 active bids for FTSE-350 companies as of the end of September, compared with just two in 2023! My conclusion: UK stocks are cheap.
Outlook: there are no brokers/analysts providing estimates for Peel Hunt, but this outlook reads like possibly a mild profit warning to me, as some revenue in the pipeline slips into the next financial year:
Trading in the first few weeks of our second half is in line with management expectations. Although we have a solid pipeline of corporate transactions, including M&A and IPOs, we expect a degree of uncertainty to persist in the short term and consequently some of these transactions are more likely to execute in our next financial year….
Graham’s view
I’m a broken clock on this one: my assumption is that IPO conditions on AIM and the Main Market must improve at some point in the next few years, and my belief is that Peel Hunt will look very cheap if/when this happens.
In 2021, the year that Peel Hunt IPO’d, they generated an incredible £197m in revenues. Perhaps a year like that will not be seen again, but it shows what is possible when market sentiment is strong.
Northern Bear (LON:NTBR)
Up 8% to 54.75p (£8m) - Interim Results - Graham - GREEN
I did not intend to cover this, due to the market cap which is really too small for this report. However, it is 6th on our “most viewed” list so I will give it a mention!
NTBR was last seen in this report in May, when I was GREEN on it at 56p.
It’s a family of businesses providing building services “throughout Northern England and beyond”.
The stock has looked cheap for some time but failed to break out of a range of c. 40p-60p:

Canadian investor Jeff Baryshnik was trying to get out of it for some time and I believe that he created an overhang of shares - he eventually got out of it in June this year.
Today’s results show operating profit of £1.7m (H1 last year: £1.8m) on revenue of £37.6m (H1 last year: £36.9m). NTBR says that the H1 results are ahead of expectations, but then in the outlook statement it says it is trading in line with expectations!
I’ve noted similar confusion before, where the RNS needs a little bit of interpretation to help make it clear what they are saying.
From the outlook statement:
The Group has traded very well during the first half of FY25 and has the potential in the second half to trade ahead of strong prior year results and market expectations. This is on the assumption, inter alia, that current market conditions remain, the additional investment in operations continues to meet revenue expectations, and that there is no major weather-related disruption which had a significant impact in H2 FY24.
The recently-appointed Chair says:
"I am pleased to report that we remain in a strong financial position and have continued to make good progress against our medium-term objectives. This has been possible in the main by a combination of continued investment, organic growth and focus on cash generation, which has underpinned the results in the period.
Net debt is £1.4m, but the company points out that this is “a snapshot at a particular point in time and can move by up to £1.5m in a matter of days”. They helpfully disclose that net debt moved between £0.1m and £2.5m during the period, with an average of £1.5m. If only every company reported like this!
Option scheme: there are 13.8m shares outstanding, and NTBR recently granted 1 million options to staff, exercisable at 52p from October 2027 for those who are still with the company at that time. It implies max dilution of 7% but maybe this is a good way to promote retention?
Management: the FD is leaving but will stay until March 2025.
Estimates: Hybridian note that H1 is usually stronger than H2 for NTBR. Last year, for example, storms and rainfall impacted its roofing activities. However, the company has “already produced 8.4p EPS, which is 83% of the full year 10.1p forecast”.
Graham’s view
I can’t avoid the conclusion that surprises here are more likely to be the upside than to the downside, although this is another view I’ve held for some time.

According to Hybrdian, the dividend for the current year is pencilled in at 2p for a yield of 3.6% at the current share price.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

54 comments
ECO Animal Health (LON:EAH) - Investor Presentation (Interim Results) video recording - December 2024
David Hallas (CEO) and Chris Wilks (CFO) of ECO Animal Health conducted an Investor Presentation covering their Interim Results for the period to 30th September 2024. Management discussed the measures to protect profitability despite the fall in Aivlosin® revenues, while also exploring the factors behind good growth in the Americas and new Aivlosin® claims approved in the period. The team discussed progression of the R&D pipeline, detailing time to market in their six key projects. Management provided a detailed overview of key financial performance, and answered a range of questions submitted by viewers.
?si=gp4_Ej-HppquaXIq
Thank you for your insights. Much appreciated
When I saw NANO I got excited thought it was Nano Nuclear Energy (NAQ:NNE) makes containers for transporting fuel. One for a nuke discussion board.
Did we lose access to the google sheets that captured the SCVR team's traffic light views on each stock covered
It says access denied etc. But that was under Paul Scotts account?
Great report on Peel. Although instinctively one knew that IPOs had dried up the graphs were revealing. Thanks Graham.
I see GMS slowly dropping day on day. Was one of Paul’s and my favourites. Anyway have a view which could help. Assumed the seller was gone but apparently not?
Gulf Marine Services (LON:GMS) l would ignore Stocko prices. Can sell for over 16p now.
Down from a peak of 24.6p - so basically lost 1/3 of value - that patience-testing !
Needs someone to pump it up.
Not as bad as Plexus Holdings (LON:POS) though.
Gulf Marine Services (LON:GMS) Increased volume and a doji formed today at an important support line. I agree its could be good value but I'd want to see the indicators ( MACD, TSI and RSI ) starting to improve before assuming this is a bottom.
I think the problem with Gulf Marine Services (LON:GMS) is the 24% ownership of the stock by Seafox and we know they want to get out. This puts a ceiling on the share price as every time it climbs in the 20p range they do an ABB. Fundamentally I agree that it is undervalued at 0.6x NAV, but will take Seafox selling down materially to break out for good and be a sustainable upward trajectory. Just my 2 cents though…
Advise sought, how can I set up a screen for US Investment Trusts ? Id like to invest to give me exposure over there but not in singular stocks. Thanks
Hi Colin. I use Pickafund and Trustnet for my IT research. You'll need far more information for you to select the actual US IT than Stockopedia provides. Note that both websites are free to use. You just need to set your search criteria. In addition there is a very good thread on Stockopedia for Investment Trusts if you have any specific questions. Its normally quite high up on the All Discussions option as it's very active.
Hi Colin, There are only a few pure US plays in the Trust sector. See here listed on the AIC . https://www.theaic.co.uk/inves... and for smaller companies https://www.theaic.co.uk/inves...
The monthly Trust thread is here- starts again 1st of the Month. You will get some good feed back I would think. https://www.stockopedia.com/co...
Personally I don't have any need for Level 2 data. If you are trading very large sums and/or over a very short timeframe, then I can see the purpose of it. When I need to buy or sell a share, I will be given a live price and the volume offered at that price - that's enough for me. G
The PTM Levy on share purchases/sales above £10k is going up from £1 to £1.50 from Monday - squeezing out another little pip from the apple....
50% increase is a bit cheeky considering inflation rates.
Price increases above inflation from public organisations are becoming more frequent. Both Companies House and the Land Registry have recently announced or implemented fee increases.
Stealth taxation in action.
Supreme (LON:SUP) is in advanced discussions to buy the Typhoo Tea brand out of adminstration as part of their diversification from vaping, funded by existing bank facilities.
On Beach group (LON:OTB) results on Tuesday. Pre close update was strong:
"Looking ahead, Winter 24 volumes are currently 34% ahead of the prior year, with customers seeking winter sun and enjoying our Long-Haul destination packages. Notwithstanding that it remains in its early stages, bookings for Summer 25 are very encouraging and we look forward to providing further detail at our preliminary results in December."
Debt free with £95m cash, eps fcst 14.6p, peg 0.5.
Good reports by others in the travel sector lately. I've added recently.
Graham
I think you've made a mistake on your report with Northern Bear. In your first line, you've written 'Up 85% to 54.75p', but at the time of writing it says up 8.37% to 54.73p. Certainly got me going though!
Best, Eugene.
Haha, thanks Eugene!
The CEO of Peel Hunt (LON:PEEL) was on the Today programme this morning, bemoaning the state of the UK stock market. If you want to listen on BBC Sounds, he starts at 1.20.22.
Facilities by ADF
One of my businesses sells reclaimed ships lighting and biggest market is actually the film set buyers
There has been a huge upswing in the past 8 weeks especially from ***** tv . (NDA) and lots of activity
Probably they are getting al their final sets ready for production early 2025
Read across to facilities by ADF who will presumably be the ones on site in the new year when the cameras start r rolling
The sales for the tome of the writers strike were literally zero . We are well above pre strike sales at the moment and have been for 6 weeks .
British television is dying
https://archive.ph/CCHl8
The big productions ate not from british tv .
Yes the film (The Power) down the coast from me, was for Amazon, it was handled by Facilities by ADF (LON:ADF) , the beach was closed for a month, they built from scratch a great big building and demolished straight afterwards, must have cost millions. Of course the road and near by car park are in a worst state than before, none of that money, went on improving them.
Also nearby The Dig and Yesterday were partly there. The money is being spent Amazon and Netflix, it seems.
I wonder if the long running saga of of the HRMCs tax avoidance legal action is also weighing on the domestic film industry?
Rockwood Strategic Plc Interims:
Facilities by ADF
The 'writers' strike' of 2023 impacted this business which provides premium-quality serviced vehicle hire for TV and Film productions, specialising in high end TV/feature films to some of the world's largest traditional and on-demand content production companies such as Netflix, Amazon Prime, Sky, Paramount+, Disney+, Apple TV, HBO Max, ITV and BBC. The industry appears to have structural growth due to modern demand for attractive content for which ADF's 700+ vehicles provide high quality studio and on-location assets. Sales are expected to have almost doubled in the three years to December 2024. We supported a key strategic acquisition to diversify the business, drive scale and unlock revenue synergies. High barriers to entry abound, supported by strong margins which does not justify a single digit PE ratio. We expect a recovery in trading, further accretive bolt-on acquisitions and a justified re-rating of the shares which we purchased at 50p. On current market expectations, the shares were valued on a PE of 5x for their financial year 2025, at period end.
https://www.investegate.co.uk/...
Decent director buy recently of 200k @30.5p
Large volume in Facilities by ADF (LON:ADF) today so far (3.3 million)
PlanetX,
Thanks for your comments on Facilities by ADF (LON:ADF) I am now holding a starting position. Looking forward to anymore info’ on the industry if you have it.
Graham.
General enquiry: do you pay for live prices and/or Level 2 data? There are Black Friday deals around but just wondering about the value of this data for a longer term investor rather than short term trader.
You can get live prices for free on Google Finance...
Yes...and no. Google can do some very strange things later on in the UK day, and it seems to get very confused over what the closing price in the UK is....until the US market also closes. Behind the scenes I suspect is it very much tied to the US timezone.
The fundamental question is whether paying for live feeds or Level 2 changes the price you can deal at. In many cases it won't - you are stuck with whatever your dealing platform serves up, and if you are selling you can hardly switch across to another platform!
Level 2 gives you a better idea of market depth, but again in most cases it won't tell you that much more than the dealing spread is already telling you. Bear in mind there are institutional trades going though in "dark pools" all over the place that retail investors can't easily access anyway.
If you are a trader in less liquid stocks with a short time horizon I can see some merit. If you are a long-term investor in largely liquid instruments then the cash is probably better off invested in the long run.....
Monty Carlo. Please would you be so kind to give us a paragraph on what the dealing spread tells a trader? I am not looking for a definition of what the spread is, just what we can learn from it.
Warrantstar, I'll give one if its any help. Brickability (LON:BRCK) spread was 60.8 - 62p after results Tuesday. You could sell at 60.8p and buy plenty at 60.9p. Tells your theres probably sellers around so its may drift down . Today its 59-59.4p and when I tried earlier your could buy and sell at 59p.
Thank you WOSS.
oh dear so the more inside the spead we get (when buying) the more chance there is share is on the way down - siggghhhh can we ever win?
Being positive. Conversely, if the spread is tightening from below it tells you the market makers are improving the price for sellers i.e there is a lack of supply and so next move could be up.
I get live prices on my platforms free. Other sites have live prices also.
Level 2 is different. Some people find it useful for when to buy or sell, Robbie Burns uses it quite a lot and he gets some good deals, it is not just about prices but demand. He has some deals on his website. For long term investing probably not so important.
Northern Bear (LON:NTBR) H1 results worth a deeper look. i believe the are the highest ever H1 EPS since the company floated in 2008. CASH flow strong. and H1 eps achieved despite investments in future. benefits of last years buy back could really give a gearing to future EPS. given order book, new contracts, investments and CASH flow its easy to see EPS of 15p-18p next year with no debt. thats a PE of c.3! its a micro cap but if new mgt make bolt on avquisitions could be a multi-bagger with a 5% yield while you wait. disc: i hold
Does anyone know why Spire Healthcare (LON:SPI) has shot up 5% this morning on no news? I hold sitting on a large loss so am quite interested!
https://m.economictimes.com/in...
i was wondering the same,this maybe?
Devi Shetty sets his heart on UK’s Spire Healthcare
Mumbai: Devi Shetty-led Narayana Hrudayalaya (rebranded Narayana Health) is in discussions with key shareholders of Spire Healthcare Group Plc to acquire a controlling stake in UK’s largest private player in revenue in the segment, said people aware of the matter. This comes as the UK is seeing a record boom in private healthcare on the back of serpentine National Health Service (NHS) waiting lists. If successful, this will mark the Indian medical group’s second global foray after the Cayman Islands
Sounds like that’s the reason - thanks.
Bid coming maybe? Pure conjecture
The Economic Times in India reported Bangalore-based Narayana Health is sizing up acquiring a controlling stake in private hospital company Spire
Northern Bear (LON:NTBR) seems to be doing OK. Inline outlook in today’s results.
TI Fluid Systems (LON:TIFS) l thought this 200p bid, was back in October? Paul had it the SCVR, October 14.
That wasn't a firm offer Rusty as the buyer hadn't done their due diligence and all the other steps needed. They're ready now and the proposal is finalised. G
This is slightly off piste, but for any holders of Harbourvest Global Private Equity (LON:HVPE) , and I am one, the letter from Metage Capital, published in today's RNS News, is of interest and of relevance to anyone who is frustrated with the huge discounts prevailing on listed private equity trusts such as Caledonia Investments (LON:CLDN) RIT Capital Partners (LON:RCP) Oakley Capital Investments (LON:OCI) Pantheon International (LON:PIN) . I hold them all, and they haven't kept up recently.
Results from Northern Bear (LON:NTBR) today look OK?
I cannot see that in HVPE RNS feed. Where can I find it, I’m a holder of HVPE.
https://www.metage.com/api/dow...
You might want to follow the excellent monthly discussion thread on Investment Trusts found here https://www.stockopedia.com/co...