Daily Stock Market Report (Fri 29th August 2025) - SRB, CAR, OCN/HAN

Good morning!
Let's kick things off with a backlog section on Serabi from Mark.
All done for the day and for the week, see you next time!
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Ocean Wilsons Holdings (LON:OCN) (£342m) | A response to Arnhold’s open letter (external link) which described the merger with Hansa as “deeply flawed and unfair”. | PINK (Graham) I get into the weeds of this a little bit, trying to understand the arguments made by each side. In the end my sympathies are with the shareholder, although I think that OCN are right about the technical details of the merger. | |
James Latham (LON:LTHM) (£223m) | 6m initial investment for the land, then £39m over two years to construct and fit out the warehouse. | ||
Avacta (LON:AVCT) (£223m) | SP +13% Deferral of several bond payments. £3.25m equity placing at 50p to settle the quarterly bond payment for October. | RED (Graham) [no section below] This one always seems like a basket case, and there is no change today as its convertible bondholders agree to defer two of their quarterly payments next year (Jan and April 2026) out to October 2027, although bondholders will have options to accelerate payments before then. Bondholders will benefit from a lower conversion price (75p instead of 88.7p) and will also benefit from a £3.25m equity placing, that will be used to settle their October 2025 payment. There is speculative potential with Phase 2 trials planned for next year, but as the equity looks unsafe to me, I have to be RED. | |
Serabi Gold (LON:SRB) (£149m) | H1 Gold production +14% to 20.545koz. EBITDA +102% to $26.3m. AISCC flat. $30.4m cash balance (31 Dec: $22.2m). | AMBER/GREEN (Mark) Production and cash are known, so the new information is sales and costs. Sales beat my expectations as they catch up with production. However, there is a huge jump in costs in Q2 which isn’t fully explained in the narrative. If I assume the Q2 cost profile for the rest of the year, I now get a risk of a material miss on PAT compared to the current broker consensus. However, not all is lost, even if my current estimates based on Q2 cost profile going forward prove closer to the reality, the stock remains on a P/E of around 4, with net cash. This still looks too cheap to me. The big question is if the market cares more about valuation or the estimate momentum? As a value investor, I’m sticking with the valuation-based view, at least until we have more information. | |
John Wood (LON:WG.) (suspended at £127m) | Sells North American Transmission & Distribution engineering business for $110m. | PINK | |
Carclo (LON:CAR) (£35m) | Rev -8.6% (£121.2m). Adj. EBITDA +12.3% (£16.4m). Outlook: “expect to continue this positive trajectory through FY26”. | AMBER/RED (Graham) A large pension deficit, a more expensive debt facility, and a red flag issue (failing to publish its annual report on time): I think a high degree of caution is appropriate here. This company has many mouths to feed and shareholders can't be particularly high on the list of priorities. |
Backlog
Serabi Gold (LON:SRB)
Up 4% to 205p - Results to 30th June - Mark - AMBER/GREEN
Production and cash figures here are already known:
Gold production for the first half of 2025 of 20,545 ounces (corresponding six-month period of 2024: 18,010 ounces).
Cash held at 30 June 2025 of $30.4 million (31 December 2024: $22.2 million).
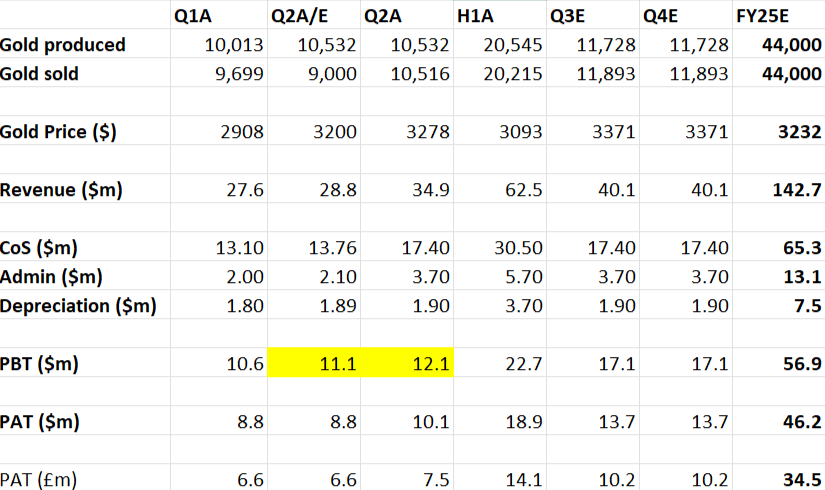
What matters in these results is sales and costs. Here it is a mixed bag compared to what I modelled following the Q2 production results. Sales beat my expectations for Q2, but with production guidance the same this just moves revenue forward. Together with a higher Q2 gold price than I modelled this means that PBT for Q2 beats my expectations:
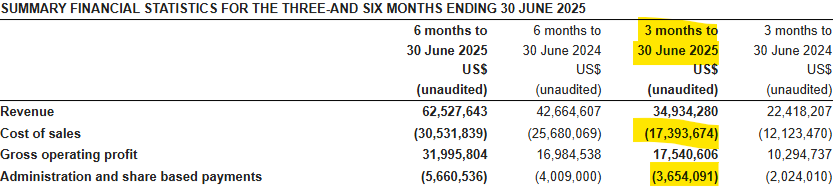
However, costs have also increased significantly for Q2:
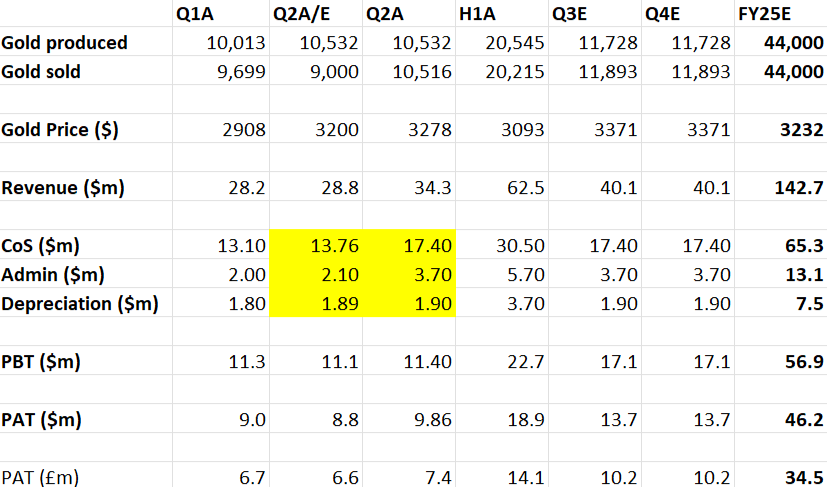
And here’s what these look like in my summary model:
The only comments they make about this are:
While mine development expenditure has increased year-on-year, the investment continues to underpin our growth and expansion plans. All-In Sustaining Costs (AISC) for the period were $1,792 per ounce, reflecting both inflationary pressures and the increased development activity. Nevertheless, the Company continues to deliver strong margins, underpinned by the high gold price environment and improved production profile.
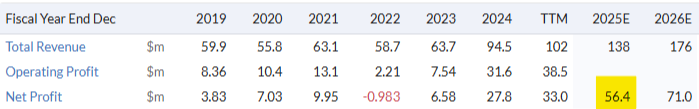
So, in the absence of other information, I think we must assume the Q2 cost profile is more realistic going forward. This takes a big chunk out of my PAT estimates which now stand at $46.2m for the year, whereas previously I estimated $55.6m. At the time, the PAT looked like it would be a healthy beat on expectations. However, since then the consensus estimate has increased from $49.9m PAT to $56.4:
Presumably this is on a higher gold price, but even if I put current spot into my model for Q4, I still get a reduced figure of $46.5m:
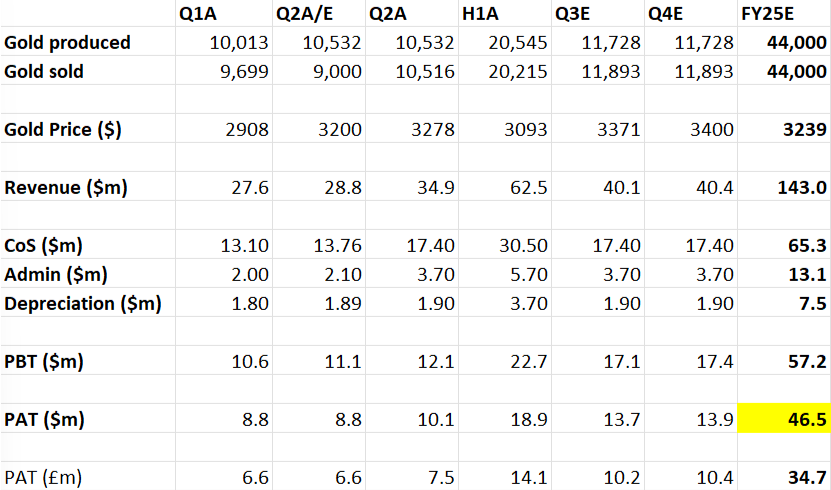
This is some 18% below consensus estimates.
Mark’s view
It may be too early to panic, as high costs for a single quarter don’t necessarily mean that these will be significantly higher going forward. However, in the absence of a clear explanation, there will be many, including myself, who will want to take the conservative view. So, with a single set of results I have gone from thinking they will beat expectations, to the risk of a material miss. This adds to my existing concern that a H2-weighted production profile can be risky in this industry.
However, not all is lost, even if my current estimates based on Q2 cost profile going forward prove closer to the reality, the stock remains on a P/E of around 4, with net cash. This still looks too cheap to me. The big question is if the market cares more about valuation or the estimate momentum? As a value investor, I’m sticking with the AMBER/GREEN rating. At least until we have more information.
Graham's Section
Carclo (LON:CAR)
Shares suspended at 47.4p (£35m) - Full Year Results - Graham - AMBER/RED
These are results for the year ending March 2025.
On the LSE’s main market, companies have four months to publish their annual report (it is six months on AIM).
As Carclo failed to meet that requirement, its shares have been suspended during the month of August.
That is a huge red flag, but Carclo has insisted that it has been trading well: a July trading update confirmed that FY March 2025 was ahead of expectations and that the company expected its margins to continue to improve.
What Carclo does: they have a “CTP” division (Carclo Technical Plastics) that manufactures and designs various complex products and parts - this seems to have a healthcare focus. They also have a “Speciality” division focused on parts for aerospace and for optics/LED.
Results highlights: these results are very backward-looking now, but let’s cover the main points.
Revenue -8.6% (£121.2m(
Adj. EBITDA +12.3% (£16.4m)
Operating profit £7.6m (previous year: £1.7m)
Net income £0.9m (previous year: loss of £3.4m).
The depreciation charge for the year is £6.5m and I don’t know why we’d leave that out of the calculations for a manufacturing business. So my instinct is to completely ignore EBITDA.
Operating profit of £7.6m is an impressive figure given the low market cap, and that’s after suffering over £2m of refinancing costs. These were “legal and professional costs”.
Debt position
The debt situation looks complicated. As of March 2025, total loans and borrowings were £30m, or about £22m if we exclude leases. And on the balance sheet date - 31st March 2025 - Carclo was “briefly overdrawn due to timing of cash flows, however, the balance was immediately repaid… with no adverse consequences”.
The new arrangement is with a lender called “BZ Commercial Finance”, and involves a £27m term loan and a £9m RCF. The previous lender - HSBC - has been fully repaid.
BZ is charging a higher margin over base rate than HSBC: according to the announcement in April, there was an increase of 1.75% over the previous facilities.
Pension deficit
Also in March 2025, the pension deficit was revalued by actuaries at £64.5m (as of March 2024). Carclo agreed to pay £5.1m in April 2025, then £3.5m annually until 2029, and then indexed annual payments starting at £5.8m until 2037.
An accounting valuation was also carried out and came up with a deficit of £51.7m as of March 2025. Higher life expectancy assumptions were primarily responsible for this having increased by £14.5m compared to March 2024.
Carclo also mentions having made a loss on its “liability driven investments” (LDI). LDI funds were at the heart of the gilt market crisis in 2022, and are designed to hedge interest rate risk for pension funds.
Interest rates increased in FY25, which is a good thing (it reduces the present value of liabilities). However, LDI funds did their job in hedging rate risk, both positive and negative, and so the value of Carclo’s LDI funds fell, causing the pension fund to make a loss of £8.7m.
Outlook
Now that I’m clear on the latest debt and pension deficit situation, I’m not sure if I care too much about the trading outlook! It sounds like the company’s pensioners and lenders will have to be their priorities (and rightly so!).
We’ve generally been AMBER/RED on this one - my last time was in December 2024.
Anyway, here’s the outlook:
The success of the strategic actions taken in recent years to turn the business around are bearing fruit and their success is evident in the improved operational and financial performance reported for FY25. The Board expects the Group to continue this positive trajectory through FY26 with continued margin expansion and positive cash generation, notwithstanding an increasingly complex global backdrop…
Growth in the medium-term will focus on accelerating expansion in the Life Sciences sector, where demand for high-precision solutions continues to grow and continued momentum in our Speciality Division, particularly in the aerospace sector. Strong cash flow performance, an improving net debt position and the new borrowing facility with BZ provide a solid financial platform for this growth.
They finish the outlook statement by promising “enduring value for all our stakeholders”; shareholders are indeed just one constituency, among many, that the company needs to care for.
Graham’s view
I think AMBER/RED continues to make great sense here.
Checking the balance sheet for one final sense-check on the company’s position, I see that it has negative equity of £12m. Exclude intangibles from the calculation and the number becomes minus £34m.
With that hole in the balance sheet, I can’t take a positive or even a neutral stance here.
In other industries, e.g. highly profitable software or media businesses, I can sometimes look past weak balance sheets. But in engineering and manufacturing, I can’t. There is also the red flag issue that the annual report could not be published on time.
I have no idea how the share price might react when the shares begin trading again, but I’d have little interest in getting involved here.
Ocean Wilsons Holdings (LON:OCN)
Unch. at £12.11 (£344m) - Response to Arnhold LLC’s Letter to Shareholders - Graham - PINK
OCN has hit back at a public letter published by one of its shareholders, Arnhold LLC.
Let’s examine the initial letter from Arnhold first.
They say that their clients own approx. 900,000 shares of OCN. I think this makes them a 3.2% shareholder.
They note that OCN shareholders are set to receive HAN/HANA stock worth approximately £12 (at market prices) in exchange for each of their OCN shares.
This matches up with my calculations, which have fluctuated between £11.57 and £12.30, depending on the latest price of HAN/HANA shares.
This compares poorly with a net asset value of OCN stock that is over £20 per share (but of course HAN and HANA shares are trading at deep discounts to their NAV, too).
Arnhold notes that Hanse, which is a 33% shareholder in OCN, will receive OCN’s investment portfolio rather than new HAN/HANA shares.
So from Arnhold’s point of view, Hansa will get “full value” for their OCN shares, while other shareholders will not.
Arnhold argues that the market agrees with its view that the merger is negative for OCN shareholders, on the basis of the behaviour of the OCN share price:
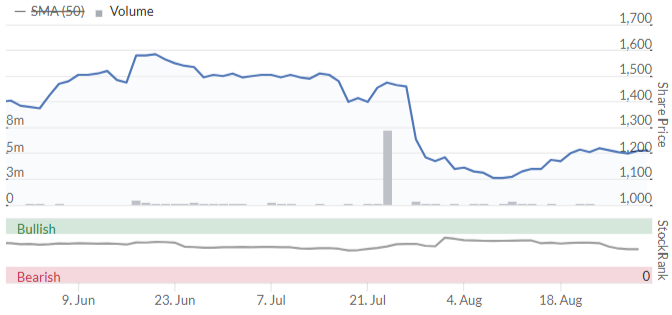
It does appear to be the case, as I’ve said before, that the OCN discount widened in response to the proposal, in the direction of the c. 40% discount at which HAN/HANA has typically traded.
Arnhold says that the rising price of HAN/HANA stock indicates that the market believes the deal favours Hansa.
They also note that 58% of the OCN portfolio is simply cash, and on that basis they argue that the companies should not be merged as if £1 of the OCN portfolio is worth £1 of the Hansa portfolio. They seemingly think that, ceteris paribus, a cash-rich portfolio should be viewed as worth more than a portfolio of funds.
I can understand their frustration that a cash-rich portfolio would be sold at a large discount. But I'm not sure if there is any fairer way of carrying out a merger of two portfolios.
In order to determine the exchange ratio of OCN vs. HAN/HANA shares, the NAV of each portfolio was used. Arnhold says that in making this calculation, and determining the value of its stake in OCN, Hansa did not use the market value of OCN shares, and instead used an inflated value (perhaps the £20 NAV per share?).
They say that as Hansa's investment management company will be the fund manager of the combined group, the interests of Hansa are not the same as the interests of other shareholders.
This bit is fairly damning:
…Arnhold calculates that the Combination would result in the shareholders of Ocean Wilsons receiving approximately £12.00 per share in illiquid new Hansa shares. Hansa published NAV as of 22 August 2025. Instead, by distributing to its shareholders the US$449 million of cash that it currently holds, Ocean Wilsons could pay almost the same amount in a cash dividend of £11.75 per share, and such a distribution would still leave £8.41 per share remaining invested at Ocean Wilsons (primarily composed of its investment portfolio). As a result, even winding up Ocean Wilsons over time and paying all shareholders the net asset value of their investment would be a preferable alternative to the Combination from our perspective, and would, in our view, result in the shareholders of Ocean Wilsons receiving significantly higher value than the Combination.
As alternatives to the merger, Arnhold would also prefer buybacks or for OCN to simply continue in its current form.
Let’s turn to OCN’s response.
First, they reiterate the positive points of the deal.
a) create a differentiated, scaled-up investment vehicle with over £900m of net assets.
b) unite two complimentary portfolios under the same investment manager.
c) realise cost efficiencies by spreading fixed costs over a larger asset base at a low ongoing charges ratio that is “materially more competitive” than current arrangements.
They go on to defend the merger on the basis that each company is being valued on the basis of its contribution of assets to the combined group.
In their words:
The proposed Combination comprises the merger of two investment portfolios and, as such, it is the NAV of each company (and the respective contributions of Ocean Wilsons’ and Hansa’s shareholders to the NAV of the combined group), that should determine the exchange ratio. This is a customary approach when looking to combine two investment portfolios and Ocean Wilsons’ share price is simply irrelevant for these purposes, as Ocean Wilsons’ shares will not form part of the investment portfolio of the combined group, whereas its assets will.
When it comes to valuing Hansa’s stake in OCN, they say that it would make no sense to value it at market prices:
Arnhold’s preferred approach of valuing Hansa’s shareholding in Ocean Wilsons at market value would have led to an arbitrary and unfair outcome whereby an interest in the same underlying assets (i.e., Ocean Wilsons’ investment portfolio) would have been valued in two different ways as part of the same transaction. In other words, Hansa’s contribution of its interest in Ocean Wilsons would have been valued on a different basis to Ocean Wilsons’ contribution of the same assets.
Graham’s view
On the technical details and the logic of the merger calculations, I think OCN are correct.
When merging investment portfolios, the fairest outcome is to compare the NAVs of each and then distribute shares in the combined group accordingly. That is what is being done here.
That said, I do understand Arnhold’s frustration with what is happening.
They (or their clients) have held shares in an investment vehicle trading at a discount to NAV.
When a catalyst appeared (a disposal) that generated a mountain of cash and simplified OCN’s portfolio, they could have reasonably hoped for a huge cash dividend and/or large buybacks over time.
They did get a £109m tender offer in July, taking out 20% of outstanding shares.
But it’s a reasonable stance that they’d want even more than this.
Instead, their OCN investment is getting rolled into a larger vehicle under the same investment manager. This larger vehicle has historically traded at an even larger discount to NAV than OCN has.
So I do understand Arnhold’s frustration. Their hope for a faster catalyst to narrow the discount has been pushed out indefinitely.
But there is no easy remedy: HAN/HANA shareholders would be reluctant to accept a mix of the portfolios which saw them disadvantaged.
I still think that this could ultimately work out quite well for OCN shareholders if it goes ahead: lower fees and larger scale could help to boost performance and attract new investors who might narrow the discount.
But there is no guarantee that this will happen. And when investment vehicles are trading at discounts that are anywhere in the region of 30-40%, I tend to think that their managers should be attempting to close that discount as a priority. But sadly, that is not what we see in reality.
It comes down to OCN shareholders and what they are willing to approve. But it's not a fair fight: well over 50% of OCN shares are held by Hansa or by Hansa-connected individuals.
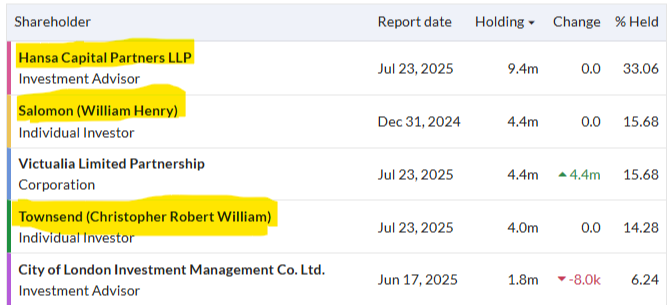
So if I try to summarise what has happened: Arnhold were hoping for a more decisive catalyst that would bring the value of their OCN investment closer to NAV, such as more dividends and buybacks. They were also happy to wait for the discount to close by itself over time.
Instead, Hansa and OCN have agreed between them - and Hansa as the investment manager clearly does have a large stake in the decision - to attempt a different type of catalyst (a merger). Whether or not this catalyst will help to generate value for OCN shareholders is not clear to me.
If I was Arnhold, I’d probably also wish for dividends and buybacks rather than a merger. But that’s the problem with value investing - you can wait many years for a catalyst, and then you get one that you didn’t want!
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

52 comments
Carclo, sorry Graham, but the auditor comment is a bit disingenuous in my opinion.
The company gave advanced warning that they would be suspended as auditors Forvis Mazars LLP needed more time, having been given as much toime as they requested originally and normally require. This wasn't a failing by Carclo.
Forvis Mazars LLP also did the same to AEP a few months back. They had to suspend. The shares have ripped north 60%+ in 3 months after the suspension.
There were no accounting issues for AEP or CAR, it was the fault of Forvis Mazars LLP.
Basically the issue is with the treatment of the huge pile of cash that Ocean Wilsons Holdings (LON:OCN) OCN holds (USD449 million ) making 58% of OCN's NAV.
However, the controlling interests of Ocean Wilsons Holdings (LON:OCN) and Hansa Investment (LON:HAN) are saying to minority shareholders via their proxies we will "take" your cash invest it in the market for a potential 30 - 40 % reduction in value.
IMHO the level of promised buy backs is so low that this merely sugar coats the bitter pill minority shareholders are given.
A fairer option would be for the controlling interests wind up OCN , return cash to shareholders; Hansa then issues shares for the benefit of those who want to take on that bet.
Surprised no discussion on Facilities by ADF (LON:ADF)
CEO suddenly left end of July. Now, CFO also sudden departure, leaving October.
Neither of them had successors in place, and searches for replacements still ongoing.
Chairman is new, having joined in Feb25.
Feels like its a clearing out of old management after the debacle last year. I note that the latest trading updates all indicate a "H2 weighting" and "assuming a pick-up in activity in H2, that was postponed from H1".
Thinking next financial update won't be pretty, and maybe some kitchen sinking.
Lets hope it's a sign that Harwood is getting a grip of Facilities by ADF (LON:ADF). (I hold for recovery)
As it is a quiet Friday, I hope readers will not mind me asking a question re Investment Clubs. Interactive Investors are withdrawing dealing services for all clubs and I find that HL and AJ Bell also no longer offer this. Does anyone know of a mainstream broker continuing to support Investment Clubs? Thanks.
A Friday (non political) thought on the Autumn budget. UK public finances are backed into a corner and it is hard to raise taxes and backbenchers have demonstrated giant aversion to spending cuts on welfare. I think the Chancellor will have to show markets a credible action to close the deficit.
So I expect to see a cut in capex programmes. Therefore there could be an impact on smaller construction company shares which are especially reliant on public sector building works.
Serabi Gold (LON:SRB) is there any news on potential dividends? Sitting on net cash so hoping so!!
Serabi Gold (LON:SRB) Share buy back makes more sense.
UK Banks: from ADVEN 'In equity markets, banks were the worst performers on the FTSE 100, with NatWest, Lloyds, Barclays and HSBC all lower after the IPPR think tank suggested that chancellor Rachel Reeves should levy a new bank tax.' Edmund S's trend data got me into euro banks, all of which have been doing well. My more recent Barclays buy has been hit today but it might be a top up opportunity, if the weakness persists. Interestingly the German report author, a former B of E and IMF Economist, fingers both the Treasury and the BoE as making errors in their Quantitative Easing product structure. No other country made this error. The proposed tax emulates one introduced by Margaret Thatcher previously! Still, it's only a 25BN error!
"after the IPPR think tank suggested that chancellor Rachel Reeves should levy a new bank tax"
One would hope that poor Rachel will learn the lesson from last year, and quash the spate of rumours/speculation that will come out between now and the budget (which is a long 2 months from now) on which particular magic tree she is going to shake some money out of.
I will guess that she won't, and so we will see continued pessimism and overreactions to each and every story that comes out. It is likely to be a rough ride....
The commercial banks' interest income on their deposits with the Bank of England must now be an irrestistable target for the chancellor. It suprised me she left this income intact in last Autumn's budget.
Back of the envelope I thought it could raise up to £10bn. A worthwhile amount from the HM Treasury's point of view, and a noticeable, though hardly devastating reduction on EPS for Lloyds Banking (LON:LLOY) Natwest (LON:NWG) etc.
Serabi do explain the increase in costs in more detail than in the RNS in the full interim statement on their website:
"Q2 cost of sales increased by US$3.9 million when compared to Q1, driven primarily by changes in ore mix and inventory drawdowns. Approximately US$1.2M of this increase relates to the processing of low-grade CMT stockpile at Coringa, consumed across March and April.
This stockpile had been held on the balance sheet at year-end and its release into cost of sales was concentrated in Q2, rather than being spread across the year."
It would appear therefore that $1.2 million of the cost increase was a one off and so the costs in Q3 and Q4 should be less than mentioned in Mark's analysis. If true then the CoS in Q3 and Q4 should be $16.2 million per quarter and the resulting PAT for 2025 should be about $49 million rather than $46.5 million.
Am I reading this right?
Thanks Silicon for your analysis. Marks was excellent as well. For me one should really only be in this type of share if you feel the Gold price is going up , even if thats only 10% or so as it makes a huge difference to these miners profitablity . Normally I wouldn't have a view with a commodity price but gold tends to be a place of safety and there is plenty in the news (and probably will be till Trump goes) to want that. IMHO
Morning all,
Being one who is glad we now look that the odd resource + miner, Andrada Mining (LON:ATM) this morning announced their '25 FY results.
Tin and Lithium in Namabia is the story there. Tungsten too. There's a lot going on.
No huge surprises in today's results. Sales of £23m, GP £3m, Op Loss (£3.9m), EBITDA a positive £0.5m.
Plenty of notes are available at Research Tree, with racy TP's from the likes of SP Angel and Hannam of 30p and more. Zeus also cover but say they await further developments before putting forward a view on valuation. Perhaps they will have a stab now these results are out.
The Oak Bloke (excellent substack, I highly recommend) has recently changed his view and become quite positive, seeing multiple upsides: https://theoakbloke.substack.c...
The other "story" going on at Andrada Mining (LON:ATM) is the recent material purchases by several "strategic investors", namely ACAM LP and Talent10. There was also a large purchase by JLE Group, which I think is just a keen investor.
Market seems mildly pleased with todays results, up 5% as I write.
Usual risk warnings about holes in the ground apply. Share count has quadrupled in the last 6 years.
Famous last words - it looks like it's becomming profitable. But will it need further funding...
I hold, God help me! Other reader thoughts and comments welcome and appreciated.
God help us is the correct term as I am also a holder - in theory it is a wonderful story but delivering the potential is going to require a lot of patience and unfortunately more and more capital which then leads to further dilution . This is the one share that I look at and cry ( I should have sold but I have a small emotional attachment to it) . Ed Croft would say " I told you -look at the Stockrank numbers "
Serabi Gold (LON:SRB) Mark thank you for your analysis. Looking at figures for cost of revenue from Stockopedia’s quarterly income analysis:-
Q1 Q2 Q3 Q4
2023 10.2 12.5 14.7 12.0
2024 14.6 13.3 15.2 12.1
2025 15.0
The quarterly cost figures are very volatile but appear to be on an upward trend. I would be very wary of basing forecasts on one quarter.
Mark have you contacted the company to ask for an explanation for the high costs in the second quarter?
I am a holder of Ocean Wilsons Holdings (LON:OCN) shares and have found the recent tender offer and proposed merger with Hansa somewhat baffling . Any chance of unpicking the letter from Arnhold LLC and Ocean Wilson's response today . My instincts and the market tell me that Arnhold PLC are correct - it is a massive reduction in shareholder value . My problem is that I am not technical enough to understand why I feel that way (other than the fact that my stake in OCN has decreased even though they managed to sell their stake in Wilson's for a huge amount of cash ) There seems to be a bad smell about this deal but I don't know why .
In very simple terms, it is a bad deal because Ocean Wilsons Holdings (LON:OCN) could be wound up and realised close to NAV - given the current discount shareholders would see a significant uplift, and in a reasonably short timeframe. If it merges with HAN as proposed, then it's likely to languish on a 35-40% discount (this is where HAN has typically traded an no reason to think this will change)
I think holders of OCN are being shafted (i hold)
Just a reminder to let us know about companies you would like to see presenting at the two day MelloLondon event in November. We now have 22 signed up but it tends to be slow in August as management are on holidays....it will pick up speed in September and we expect to reach over 50 companies wanting to meet and engage with the Mello community.
Meanwhile ticket sales are booming....Do grab yours before the cheap early bird tickets run out... https://www.melloevents.com/mellolondon2025
I should mention that Serabi Gold who have reported today and discussed on here have already signed up for Mello London
Aviva (LON:AV.) went XD yesterday. so, a question: If shareholders sells before close of business TODAY, August 29th, do they still qualify for the Dividend? The reason I ask is this statement within their Results page of August 14th:
``The Company announces an interim dividend of 13.1 pence per share for the financial year ending on 31 December 2025 on the Company's Ordinary Shares of 32 17/19 pence. The interim dividend will be paid on 16 October 2025 to shareholders on the Register of Members at the close of business on 29 August 2025``.
Bold text is mine. Is it a risk to sell this morning, or do people wait until the next trading day, which is Monday?
You qualify for the dividend if you hold the shares when they go xd. In the UK usually if you hold them on the Wednesday night as shares go xd on Thursday morning
I am tempted to think that there was a misprint in the Aviva (LON:AV.) results statement. It is normal for shares to go ex-div on a Thursday, and all data sources that I use showed them going ex-div yesterday. If you sell today you will not miss out on the dividend.
Hi john2, thanks for your comment. I think that Aviva`s reference to August 29th is not so much relating to the XD date, which was August 28th, which is correct. The 29th is the Record Date, today. So my question is more about selling before the end of the Record Date. So therefore, I ask, why do people sell off before the end of the Record Date, which is today. They`ll miss the Dividend, surely? I`m not as experienced as yourself or many others, so forgive me for my lack of knowledge.
The record date doesn't make a difference. It's just the xd date that matters. You can see by the way the price usually drops on the xd date.
I am tempted to think that there was a misprint in the Aviva (LON:AV.) results statement
I seriously doubt it - oddly i had exactly the same question myself reference International Personal Finance (LON:IPF) - they have an almost identikit wording used ref their divi - the ex divi day was the same say as Aviva and they also mentioned close of play on the 29th
per ipf interims
The interim dividend will be paid on 26 September 2025 to shareholders on the register at the close of business on 29 August 2025. The shares will be marked ex-dividend on 28 August 2025.
I dont really get it i think the explanation is along the lines of what cpmal1 advised ref the 1 day timing difference.
i would have thought it must be the same principle for buyers and sellers.
i would have thought if price has dropped (ie gone ex divi) then its a given that to be fair anyone who sells after price has dropped should get the divi and anyone who buys wont get the divi - surley shirley that must be how it works ?
I am slightly worried though now that if you sell on the day could you miss out ? that would be odd. Hopefully its simply that you sell on the day and its simply a 1 day delay before thats ratified and register updated?
update
ok thanks stehuk for confirming that it appears that the close of play bit is irrelevant - must admit its odd that in formal announcements they would use stuff that has potential to cause unecessary confusion.
Thank you, I think BlueFrew has explained things correctly. I was confusing the trade date with the date of registration.
At least my last sentence was correct - if you sell today you will still receive the dividend.
Don't confuse trading with registration as it takes at least 1 day to register after buying/selling . On the day a share goes XD you can buy/sell without the dividend .
You answered your own question. You need to hold at the close of the day, ask yourself if you sell in the morning, will you be holding at the close of the day?
The important date isn't when you agree to sell the shares, it is when the trade is settled. UK trades are usually done on a T+2 basis, so settlement is 2 trading days after the sale.
If you sell on August 27th (before the ex-dividend date), settlement is on the 29th so the buyer is the shareholder on the Register of Members at the close of business on 29th August 2025.
If you sell on August 28th (ex-dividend date) settlement is on the 1st September so the seller is the shareholder on the Register of Members at the close of business on 29th August 2025. The buyer does not take ownership of the shares until after the seller has been recorded as the recipient of the dividend payment.
UK trades used to be done on a T+3 basis and the ex-dividend date was thus usually a Wednesday. Presumably the idea was to allow the whole weekend to record the list of eligible shareholders. Probably not required now that most trades are done electronically and the registrar can pull up a list of eligible shareholders in seconds, but the tradition of the record date being after close of business on Friday remains even with the move to T+2. If we ever move to T+1, the ex-dividend dates would probably move to the Friday.
Meet Management Teams face to face: International Consolidated Airlines SA (LON:IAG) M P Evans (LON:MPE) Central Asia Metals (LON:CAML)
Are you interested in meeting management teams face to face? Yellowstone Advisory is organising an in person event with 4 listed smaller companies on 17 September in London.
Management teams from International Airlines Group, MP Evans, Central Asia Metals and 1 other TBC will be presenting and there will be plenty of time after the presentations for informal discussions with the management teams over drinks and canapes.
The event starts at 5.30pm in EC1
Register: Join Webinars & Events | Yellowstone Advisory
Excellent! But production is increasing in the second half and Mark's cost profile could even be too low. The other difference with Serabi is the further large increase which should certainly happen in the following year - this is what makes it such a good and different play in the gold producers.
However this will entail yet further cost profile increase - can you model this, Mark, against what the analyst consensus view is for the following year?
Serabi Gold (LON:SRB)
Yes, forecasts for next year are an important part of the investment case. It would be good to see Mark's excellent analysis extended into 2026.
And don't forget they mentioned back in April that they will commence paying dividends sometime soon - presumably next year.
Thank you Mark, for rising to Graham's invitation to dig into Serabi Gold (LON:SRB) for me. I continue to hold a spread of small gold miners, at least they are not so subject to our Chancellor's whims as companies reliant on our home markets are.
I have been off loading mine (mainly Fresnillo (LON:FRES) ) as the shares have done so well, as have gold and silver during current Dollar weakness. My Fear would be a reversal in this trend seen so far this yer ...ie a Dollar rally ...limits further progress. Conversely Sterling strength weakens the case in the UK which I doubt many are that worried about.
Yes Fresnillo (LON:FRES) seems very highly valued on ordinary measures. Is it the "only silver option" that has taken it to such high levels???
No I think Hochschild Mining (LON:HOC) also has silver but all these companies have disappointed with production although Fresnillo (LON:FRES) has done better from gold. I wouldn't pay too much attention to PE ratios for these stocks to be honest and look at NPV DCF over life of mines as a better guide. Obviously Silver strength has helped but it wasn't so long ago that the shares were down at 6-700 and no-one interested. The volatility in the commodity hurts and after the strong run im happy to take a step back.... and reassess later.
Thanks, good points. I had Fresnillo (LON:FRES) in my sights at 450p but didn't pull the trigger. Doh!
If you are bullish silver I suggest you to buy into explorers with a resource in the ground. Most of these stocks are listed in Canada or Australia though. The market cap of these companies is modest and such explorers (with a silver resource in the ground) will move rapidly when silver goes up much more than Fresnillo percentage wise. These are four I have: southern silver exploration, gr silver, kootenay silver and equity metals corporation.
The bad thing about explorers is that they have no production so will need money every once in a while to keep digging and exploring. But Southern Silver, Gr Silver and Kootenay have all raised recently so should be ok for a while. The good thing about them is that in a way they are less risky than miners since incidents are less likely - the resource in the ground will remain there - its about valuing it! [we know mining is risky!]
Well im a lot less bullish after the run... feels like a period on consolidation at east to me but who knows...good luck with these.
bensummers
I agree the explorers have different risks to the miners. Which is a good way to diversify. (Although they are both high risk). However the three you mention are very small which adds to their risk and also means a large bid offer spread.
I identified Silver Mines (ASX:SVL) as a possible candidate but the price action has been aneamic, which is a warning i take seriously. I generally only buy when a share is on a clear upward trend.
Do you have a resource that you use to research this area. Why did you choose these three?
What I don't like with Silver Mines is that there are already 2.09 billion shares plus the market cap is already chunky for an explorer at $251 million cad. I research hundreds of silver/gold miners. My biggest positions currently are in Equinox Gold and B2Gold. (gold not silver)
It is interesting that the silver miners are expensive on a PER above 15 and the gold miners are cheap on a PER below 5. Presumably they both have a similar level of risk.
I interpret this to mean that the market thinks that silver will rise in price and gold will not. The gold / silver ratio is very high at the moment at about 90, compared to a long term average below 70. Which supports the idea that silver is very cheap at present.
I am trading this by going long silver.
What's your silver vehicle of choice?
Maxed out on SIPP and ISA, so spreadbetting.
Invesco Physical Markets (LON:SLVP) - 0.19% holding charge plus platform fee.
On a dollar rally:
Started off agreeing with you but then tried to think of what would trigger that dollar rally.
Couldn't think of anything but can think of reasons for continued dollar weakness
hmmm ok, well not so long ago tariffs were supposed to be US dollar positive... but I would say losses remain US Dollar positive for now, and so a market reversal will no doubt push the Dollar up, making precious metals less defensive than normal. I don't think it's too hard to think of catalysts for the Dollar to be fair.
Serabi Gold (LON:SRB) excellent commentary Mark but I think the investment case remains very strong. EPS upgrades, revenue expectations rising, low PE, stock rank 100, gold price strong, volatile global politics. My biggest holding. DD
Great write up on Serabi Gold (LON:SRB) thank you.