Daily Stock Market Report (Fri 3 Jan 2025) - WIZZ, RYA, VLX

Good morning! Let's see what the newswire has for us today.
7.15am: my initial impression is that today's feed does not contain any items that I would ordinarily consider to be worth covering. I will add the briefest of comments on WIZZ, RYA and VLX.
9.10am: today's report is now finished. I guess this will be the last weekend before the RNS gets busy again!
12 Stocks of Christmas: this series continues today with Mark Simpson looking at Serabi Mining (SRB). This stock also featured in Ed's QVM Portfolio.
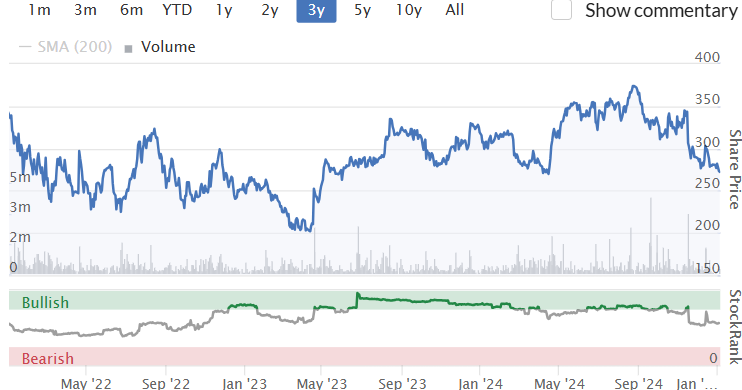
Wizz Air Holdings (LON:WIZZ) (£1.46bn) - December 2024 Traffic Statistics
This Hungarian airline saw December bookings increase slightly year-on-year, despite a reduction in capacity. Its load factor therefore increased from 82.1% to 86.5%. Early indications for the company's Q4 period (Jan to March) are "positive, with bookings currently running ahead by over 2ppts [percentage points] vs this time last year".
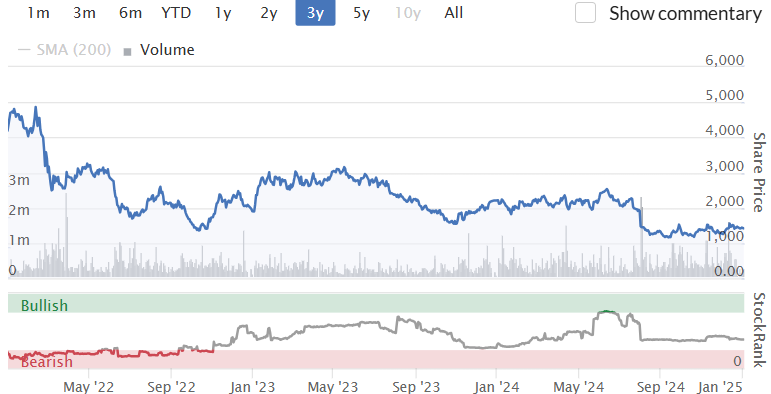
Graham's view: the cheap earnings multiple at which this stock trades (PER 5.6x) is explained by the net debt figure of nearly €4.8 billion (as of the Sep 2024 interims).
Ryanair Holdings (NSQ:RYAAY) (£17.1bn) - Ryanair December Traffic
Ryanair doesn't have a London listing these days, but let's check in on its latest numbers anyway.
The total number of December passengers was up 8% year-on-year, and the monthly load factor was up 1 percentage point to 92%. Note the difference vs. Wizz Air at 86.5%.
The rolling figures for the financial year show Ryanair's load factor running at 94%.
Graham's view: the market will have priced them in already, but today's figures are unambiguously positive. Ryanair also runs a net cash position (€0.6 billion as of Sep 2024) even while buying back shares in large quantities and paying dividends. Ryanair's shares trade at a premium to its peers and rivals, e.g. RYA is at 12x while EZJ is at 8x.
Volex (LON:VLX) (£497m) - Deferred consideration for acquisition - GREEN
This is a good news update: a Turkish business acquired by Volex in 2023 has hit its initial EBITDA targets.
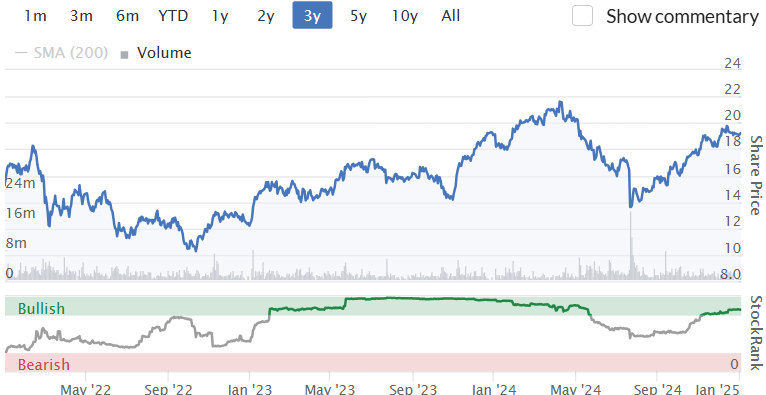
The result is the payment of €10m (£8.3m) in cash to the vendors, along with 2.9 million new VLX shares (value around £8m at the current share price). There are already over 180 million VLX shares outstanding, so the dilution is limited.
If EBITDA targets are also hit in the current year, it will result in a second and final set of defcon payments.
Graham's view: VLX shareholders should be very happy that Murat Ticaret is hitting its targets; this was a very large deal with a total potential cost of up to $200m. Hopefully the acquired company's EBITDA is converting to cash and helping to fund its own defcon payments. That should always be the aim in this type of situation.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

31 comments
Volex (LON:VLX)
I have never quite understood the investment case after this has reached the £4 mark.
With a forward 2027 EV/FCF at 20X is not the cheapest listed stock on the LSE.
Hopefully for all here is not going to be the next Bumi!
All the best
Volex (LON:VLX)
It kind of makes sense whilst they are increasing sales and acquiring other entities that the FCF wont match earnings. No one really knows how the mop will flop ref the future but everything looks on track ref investments paying offf.
there is two ways to skin a cat - if one doesnt have any reason to not believe the actual earnings are real then it all does look fine and dandy to me.
Perhaps if they take pause for breath now ref acquisitions then the FCF metrics should be expected to start to improve pretty soon?
I have not quite got round to buying here - there are expected big jumps in profit and when acquisitions are at play its always slightly more risky tyhat the new stuff will deliver as expected. Looks like they are solidly on target to hit some very decent numbers this year overall (compared to prior years) so i think some of the risks are subsiding in that regard unless they go on another spending splurge - that is very possible if not probable. Overall they have done a decent job of building the steps for future higher profits and the all important free cashflow (per share)
I am talking about 2027 FCF!
Thanks
Volex (LON:VLX)
I am talking about 2027 FCF!
I havent really looked at this company in detail - so i am guesing you will have more clue than me why FCF in that year would be less than profits being generated (my presumption that is the case) - not sure what forecasts are for that year either but i would be surprised if they expected profits to drop.
for anyone interested the two Pauls have covered this company on their latest podcast recently (vox markets you tube) - they did mention that Volex that there might be tariff headwinds for Volex so that might be creating some short term uncertainty i hadent really thougfht about.
I did hold but it was one of my AIM holding that I chopped pre budget and don’t see the need to rush back in. I am slightly surprised by their lack of recent progress. Although EV car sales have slowed the building of the infrastructure has not. Additionally, with the boom in AI, what is definitely required is high speed data centres and lots of them and that means miles of specialist cabling. Both of these should have really driven earning but it doesn’t seem to be filtering through to the share price yet. I’m happy to sit on the sidelines for now but I do recognise the quality metrics so expect to buy back in at some point.
Volex (LON:VLX)
people say volex is going great guns but the trending forecasts for this year and next on stocky show that the expected earnings have been subject to a dripfeed of reductions for this year and next over the last 12 months.
is this not at odds with the narrative coming from the company ?
so if they are doing well why are these numbers trending downover ?
The EPS is still increasing by 15 % each year, rather than the previously forecasted 20 %... that seems slightly nit-picking considering what has been thrown at the economy in the last 6 months IMHO... I wish that all my other holdings were increasing at such a healthy clip ... I hope that Nat Rothschild will under promise and over deliver...
Volex (LON:VLX)
it is nitpicking indeed to a degree so not a huge issue. Note you have to be careful ref trend though if trend looks like it will continue in same direction.
For example 2025 expectations back in October were for 0.365$ eps for 2025 year - we now have 0.365$ eps expected for 2026. To me thats suggests nil growth 2026 compared to position expected back in October - even if it will be actual growth due to paring back both sets of numbers.
Note its still levels well above prior years - but practicably speaking the trend at the moment if stocky is correct is downwards. No biggie but personally i prefer companeis to under promise and over deliver when they are promising growth - i am kinda nitpicking a bit here as the economy certainly aint booming at present and i understand that there is probably external reasons why the figures may have slipped - a reversal of the downward trend would be nice though. Should they have perhaps tamed expectations so as not to reduce them later ?
Note how most major shareholders have been topping up their holdings since the November SP drop. They clearly see value at these levels. I hold
Happy New Year all! Quick question on a quiet day, the scheme of arrangement has paid out for Tritax (Tritax EuroBox (LON:BOXE^L24)). Any thoughts on similar that I can further investigate as a replacement? Had a quick look at Schroder European Real Estate Investment Trust (LON:SERE), but seems to have some adverse on potential french tax, which is not something i necessarily need. That said it looks to be trading on a decent discount after recent falls.
I found this thread useful as well (https://www.stockopedia.com/co...) led off well by the ever insightful Ken Mitchell....but is a bit dated now.
Thanks in advance!
Hi archibold
Ask on the monthly Investment Trust thread - here: https://www.stockopedia.com/co...
But agreed, the Schroder European Real Estate Investment Trust (LON:SERE) tax situation and the lack of provision for it makes it hard to invest there at the moment.
timarr
Thanks timarr! You mean there is more than one place to post things on stockopedia, who knewo? :)
Tritax EuroBox (LON:EBOX^L24)
On this general subject, there is an interesting comment in today’s Investors Chronic, re SEGRO (LON:SGRO), Slough Estates as was, and their new £350m investment in 3 data centres and the premium rental that these will command.
Volex (LON:VLX) Graham hi. Thanks for the quick note on volex (I hold and topped up yesterday). You mentioned that the Turkish large addition had hit EBITDA targets and thus was good news.
I have confirmation bias as a holder! And read it as a veiled hint of “exceeding expectations”. To quote exactly. And we now all know how to view those 3 magic words.
Murat Ticaret has exceeded the EBITDA targets set out under the acquisition agreement for the first 12 months immediately following the Acquisition.
I suspect the timing is down to the fact that the market didn’t like the failed acquisition, the price has dropped 20% on No real change and they want to remind the market that they are doing well.
But I could be hearing an echo from my chamber?? Any other holders out there? Thoughts?
thanks in advance
Only that I agree with you. I need to see if I can find some spare cash to top up at these levels. I don't think the market thinks they will meet H2 estimates (which are challenging v H1) but Volex (LON:VLX) keep telling us they will. And they should know by now because they will have got visibility of their orders for the remainder of the financial year.
Patrickmylnetrade
Volex (LON:VLX) I’m a holder and topped up recently. Good to see they weren’t prepared to overpay for TT and walked away.
Murat is obviously performing well and cross-selling to their existing customers will benefit other parts of the Volex group.
I'll hold and wait for the 'ahead of expectations' announcement.
Patrick & Jim
Volex (LON:VLX) is my largest holding.
I have a lot of confidence in Nat and as the largest shareholder he has a vested interest to ensure further success.
Problem with SP is there probably not be any more financial information until April and price seems to drift downward till March.
I intend to add but will wait.
I do hope the recently mooted take over does not happen as there seems great concern if company adds to its debt pile in current uncertain world markets especially EVs
Tom
This news caught my eye "Shipments to China of foreign-branded smartphones, including Apple Inc's AAPL.O iPhone, fell by 47.4% in November from a year earlier,"
Also "Trouble in China's shopping paradise as Hainan duty-free spending tumbles"
"Duty-free spending slumped 29.3% last year in China's island province of Hainan, where global luxury players from LVMH LVMH.PA to Kering PRTP.PA have set up shop, as a weak economy led to a sharp drop in numbers of domestic visitors."
Things not looking good in China, even at the top end. Read across to Burberry (LON:BRBY) ?
I was in Hainan for a ten day holiday before Christmas, and visited the duty free shopping area for dinner and window shopping.
Anecdotally, it seemed busy, with Jaeger Le Coutre looking to be doing good business.
Hotel prices much reduced from the pandemic era, when Hainan was the only place Chinese could go on holiday.
Lots of Russian tourists there as well.
Some of those figures maybe a bit misleading as the Chinese are travelling abroad more now, seemed to start around Chinese New Year, 2024. There were plenty in Thailand and Laos. Also lots of Russians in Thailand.
We need this type of foreign correspondent reports!
Haha. Nothing like hands-on reporting. Thanks.
Oh and for what its worth regarding Burberry, we walked past their store in Hainan but my wife(Chinese, 36yrs old), wasn't interested and described it as an 'old lady' brand.
Lots of old ladies in China though.
Just had a terrible flight with Wizz Air. Delayed 24 hours with almost no communication. Once a bad reputation sticks it is usually game over.
I had 50 flights with them without issues. easyJet similar number, less with ryanair, but no problems at all! Maybe I'm just lucky :)
But I had Lufthansa flights with stopover I missed both times my second leg as the first delayed, so I had trouble with legacy airlines only.
I've only flown once with Wizz Air Holdings (LON:WIZZ) and it was pretty terrible. That doesn't mean it's a bad investment though...
My quality xmas stock for today is ...
IG group (LON:IGG) 996p It's an online sharedealing platform, which will be familiar to most of you. It's still my preferred trading platform due to its ease-of-use and cost structure.
The shares had a good year last year, up 32%. They have spent most of the last 10 years going sideways, though. The valuation is cheap. PE of 9.4, P/FCF of 9.2, EV/EBITDA of 6.4, dividend yield of 5.0%. It has excellent returns on capital, averaging about 23%. EPS was 36.0p in 2015, 81.4p in 2024. That's more than double, which I look for. Stocko give it a Q score of 96, and an overall rank of 94. It has net cash.
I hold.
For a high quality business IG group (LON:IGG) is clearly outstanding value by any metric . However the reason why it doesn't and shouldn't trade on a high multiple is the very real threat that you might wake up one morning to find you have been punched in the goolies. Especially under a Labour government, spread betters are a very obvious target both to raise some extra revenue and for customers to be offered greater protection. Standard online gambling companies are now extremely restricted in how much they can allow customers to lose, yet Spread betters basically allow you to punt off your net worth with minimal interference. . Lord Cruddas, founder of CMC markets, donated millions to the Conservative Party for a reason..
I agree that spreadbetting is an obvious tax target but the gambling industry has had (and still has) strong ties to the Government . In the past it could be claimed to have even stronger ties to the Labour party than the Tories. Remember Blair’s push for super casinos . Below are a couple of articles on Labour’s gambling ties: for balance one from the Guardian (more relevant) and one from the Daily Mail (more recent).
https://amp.theguardian.com/so...
https://www.dailymail.co.uk/ne...
Brilliant, thanks.