Daily Stock Market Report (Fri 30 May 2025) - HVO, MNG, AUTO, BOWL

Good morning and welcome to Friday's report!
The quiet RNS will give me a chance to circle back to some of yesterday's releases that we missed.
Mello 2025: Ed, Mark and I will be at Mello in London next week, which will be a great chance to meet some of you in person. If you'd like to go and haven't booked it yet, we can offer a discount code "STOCKOPEDIA50", which can be used at this link. See you there!
12pm: today's report is finished, have a nice weekend everyone and I'll see you in person at Mello next week, if you can make it! Cheers.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
M&G (LON:MNG) (£5.4bn) | SP +6% M&G becomes preferred asset management partner in Europe for major Japanese insurer. Expected to deliver >$6bn of new business flows for M&G over five years. Dai-ichi Life intends to acquire 15% of M&G through on-market purchases and will then have the right to representation on M&G Board. Trading update: performance year-to-date is “broadly in line”. | AMBER/GREEN (Graham) [no section below] M&G’s total AUM was £346 billion as of Dec 2024 and so >$6bn (£4.45bn) of new business over five years may not be all that material. However, notice that the Japanese company will buy 15% of M&G shares through on-market purchases (regulators permitting) is interesting - and a good reason to mark up M&G shares in advance of those purchases. I’m moderately positive on M&G although I do find it very complex - we looked at its final results in March. | |
Harmony Energy Income Trust (LON:HEIT) (£209m) | Drax offered 88p but that offer has now lapsed in favour of a 92.4p bid from Foresight group (LON:FSG). | PINK [no section below] | |
hVIVO (LON:HVO) (£111m) | SP down 57% Major profit warning. Significant contract cancellation alongside a postponement and a smaller study cancellation. New 2025 revenue forecast £47m if there are no further contract wins (prev: £73m). New op profit forecast: loss of £12.1m (prev: profit of £5.8m). | BLACK (RED) (Graham) Net cash that's nearly as large as the current market cap provides some comfort. But losses are expected to eat into that cash balance this year, and it's difficult to have much faith in next year's forecasts. |
Backlog items (see below): AUTO, BOWL
Graham's Section
hVIVO (LON:HVO)
Down 57% to 6.99p (£48m) - Trading Update - Graham - BLACK (RED)
This is the company formerly known as Open Orphan.
I’m dismayed to report that this is an enormous profit warning.
Here are the numbers from Cavendish (many thanks to them for publishing on this first thing):
FY Dec 2025:
Revenue forecast down 36% (from £73m to £47m)
Operating profit forecast reduces from £5.8m profit to £12m loss.
Future years are also severely impacted:
FY Dec 2026: operating profit forecast cut from £10.9m to £3.6m.
FY Dec 2027: operating profit forecast cut from £15.2m to £8.2m.
Of course it’s difficult to have confidence in any 2026 or 2027 profit forecasts in this situation.
Turning to the company’s statement:
hVIVO… has received notification of a significant human challenge trial ("HCT") contract cancellation alongside a postponement and a smaller study cancellation. These client decisions are believed to be related to the current uncertainties in the pharmaceutical industry and the continued depressed biotech financing market. The current volatility in the pharmaceutical industry, particularly in the US, is impacting the whole CRO industry and has led to an increase in cancellation rates, postponement of clinical trials, and delays in approvals for new projects.
There are a few silver linings.
The new £47m revenue forecast is based only on contracted revenue for the current year - and the company “expects to achieve further contract wins during the course of FY25”.
Also, the sales pipeline is “at a record level”, with “high probability opportunities” that should provide “significant revenues in FY26”.
Recent acquisitions are said to be “progressing well”.
However, there is no getting away from the fact that this is an enormous profit warning.
CEO comment excerpt:
"Whilst we are disappointed to have received notification from these clients due to matters beyond our control, we still remain confident in the continued growth of human challenge trials and the overall prospects for hVIVO as we also continue to diversify our revenue streams and build our offering as a full-service CRO [contract research organisation].
Graham’s view
I have to be RED on this in the aftermath of an enormous profit warning that sees the company swing from a forecast profit into a large forecast loss.
However, I am open to upgrading my view on this once the dust has settled, as I note that the company had cash of £44m as of December 2024. With a market cap now of only £48m, one could argue that it’s in deep value territory here.
However, the operating loss forecast this year can be expected to take a large bite out of that cash balance. And then we’ll be relying on an improvement in 2026 to bring it back up again.
I'm no expert in this sector, but I'm willing to take the company at its word that macro factors are responsible for increasing the risk of contract cancellations. So let's hope that they can get back on track once the "volatility" in the pharma industry has died down.
However, one unfortunate feature of the company’s current governance is that the ownership of Board members has reduced. The CEO currently owns 0.6%, as does one of the NEDs.
Chairman and co-founder Cathal Friel previously held a 3.1% stake, which he sold last year with the share price at 29p (“to satisfy institutional demand”). He is not seeking re-election to the board at the AGM next week.
This context is another reason for me to be a little doubtful about recovery prospects here - commiserations to anyone holding this one.
Backlog
Auto Trader (LON:AUTO)
Down 10% yesterday, now at 793p (£7.0bn) - Graham - AMBER/GREEN
These results were considered underwhelming by the market yesterday.
Key points:
Revenue +5% (£601m)
Operating profit +8% (£377m)
EPS +12% (31.66p)
This is an exceptionally high-quality company - look at the conversion from revenue to operating profit. We rarely see margins like this in any industry, but profitable “marketplace”-type stocks are able to do it.
An important reason for this is that successful marketplaces tend to resemble monopolies: this lets them generate above-average margins and returns over the long-term. Auto Trade says “we remain more than 10x larger than our nearest competitor”.
Maintaining and fully exploiting that position does require ongoing development, however. AutoTrader’s AI tools, collectively referred to as “Co-Driver”, are now helping retailers to quickly generate effective cars ads.
At the same time, Deal Builder helps buyers to set up their purchase online, and is now part of Auto Trader’s “core advertising proposition”.
Market overview: high demand for used cars, and limited supply of cars aged 3-5 years, “has led to cars selling at a faster rate than any time our recent history”.
However, this hasn’t helped Auto Trader’s revenues:
We have seen a 5% increase in the number of cars advertised through Auto Trader which is slightly higher than the increase in overall used car transactions. Fast speed of sale has meant retailers have benefitted from increased utilisation of Auto Trader's slot-based advertising model. As a result, even though consumer and retailer activity have both increased, it has not directly benefited revenue…
As for new cars, the retail channel saw a 4% decline last growth but is up 6% so far in 2025. The company has a positive outlook here:
With the announcement of a UK/US trade deal and the Government's plans to soften the Zero Emission Vehicle ('ZEV') mandate, we expect overall new car registration volumes to be well supported over the next two to three years.
CEO comment excerpt:
"Despite broader macroeconomic uncertainties, the UK car market is in good health and we continue to deliver against our strategy to improve car buying and retailing."
"We remain confident in the outlook for the business given our strong market position, the value we deliver for customers, and our unique data and technology capabilities."
Outlook: retailer revenue growth was only 5% last year, and the speed of sale remains an issue for Auto Trader in the current year, but they do expect retailer revenue growth of 5-7% for 2025.
Losses at Autorama, owner of van leasing company Vanarama, will reduce in line with expectations.
Graham’s view
I think the quality of this company is largely undisputed. The question is how to time an entry - it tends to trade richly (PER in excess of 20x almost as a rule) and so investors have to balance that against their desire to own a company with a formidable competitive position.
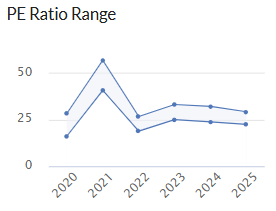
Today, I’m happy to give this an AMBER/GREEN.
An overly simplistic strategy that I’ve used in the past is: for a very high-quality company that I’d be happy to own long-term, I’m generally ok with buying it below a PER of 20x, even if the growth outlook isn’t very impressive.
Auto Trader is now trading at around 22x:
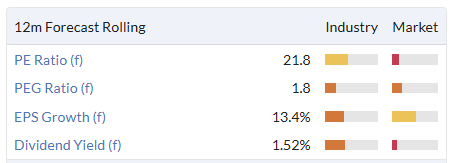
There’s no shortage of car buyer criticisms to be found, especially to do with the site having too many ads in its search results, and too many non-local “cinch” results. Dealers will often complain about Auto Trader, too.
But that’s natural when a company achieves monopoly status in its sector: you become a magnet for complaints.
Given its competitive position, I think the stock is a fine buy-and-hold candidate. But I do like to hold out for a juicy entry point, and I'm not sure we are there right now.
Hollywood Bowl (LON:BOWL)
Down 8% yesterday to 266p (£448m) - Half-year Results - Graham - AMBER
There was little hint of a profit warning in yesterday’s headline, but the shares fell 8% anyway:
STRONG PERFORMANCE AND PROFITS IN LINE DRIVEN BY INVESTMENT IN GROWTH STRATEGY AND CONTINUED DEMAND FOR FAMILY-FRIENDLY, AFFORDABLE LEISURE
Like-for-like revenue growth was only 2.1%, having been negatively impacted to the tune of 1.1% by some calendar effects (Easter/leap year). So I guess that “real” LfL revenue growth was 3.2%.
Canada led the charge with LfL 3.7%, vs. UK only 1.5%.
And Canada also saw 13.6% growth in overall revenues as it expanded to 15 centres (vs. 75 in the UK).
H1 adjusted PBT fell 9% to £28.0m. Actual PBT fell 4% to £28.3m ~ nice to see that there is little difference between the adjusted and actual figures.
Capex: there was a £20m capex spend in H1, of which £14m was expansionary. This tends to depress profits in the short term as high depreciation charges are incurred on new capital whose profitability has not yet matured.
Outlook:
On track to have 130 total centres by 2035 (I’m not used to seeing a company with a 10-year goal!)
“Resilient demand” and “well insulated from inflationary pressures”. Low labour-to-revenue ratio of <20% in the UK.
But this is where investors and analysts start to worry:
The recent warm and dry weather - marking the driest spring in over a century - has had a short-term impact on trading over that period. In response, we have proactively managed margins and costs, maintaining strong operational performance, which remains at historically high levels.
Despite this temporary headwind, we remain confident in our outlook for the second half of the year. We are well-prepared for the key July and August holiday period and continue to expect full-year EBITDA to fall within the range of current analyst forecasts.
“Within the range” of forecasts is fair enough, but perhaps the company could be slightly more forthcoming and say that they expect to be towards the middle, the top, or the bottom end of the range?
The company's brokers are Investec and Berenberg. Rival broker Peel Hunt cut their PBT forecast for BOWL yesterday from £52.6m to £50m, according to Proactive Investors.
Net cash is £23m before leases and the company continues to pay a useful dividend (yield c. 5%).
Graham’s view
Roland covered BOWL’s half-year trading update in April and while generally taking a positive view, he noted that LfL growth was starting to look weak.
I’ll downgrade our stance now, as I think there is a heightened risk of an "official" profit warning later in the year. I also feel the company could be more helpful when it comes to providing forecasts.
My overall impression of Hollywood Bowl remains positive. Unlike many of the capital-intensive leisure businesses we cover, it does generate profitable returns. Even more impressively, it has been doing this while it expands, which is no mean feat.
So at this valuation it still could be interesting:
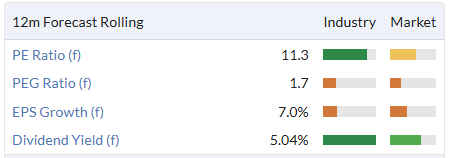
But my AMBER stance reflects the short-term risk that weak LfL growth persists, and as stated above, the risk of an "official" profit warning.
The momentum trend is not currently BOWL’s friend, and is deteriorating:
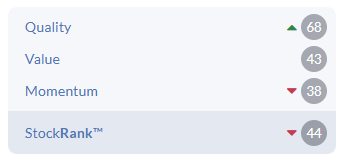
PS: to hedge against dry and warm weather, perhaps BOWL shares would pair well with cider maker CCR. Therefore, come rain or shine, at least one of the companies in the portfolio would be happy about the weather. I'm sure you can think of more examples where the weather risk could be hedged!
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

49 comments
Re M&G (LON:MNG) which I have kept on principally for the dividend I should think if it had used half the dividend on buy-backs the picture would be quite different to the present.
Dai-ichi Life is one of the 'great' Japanese life companies. Their Tokyo HQ was taken over as the HQ of the US occupying force under Macarthur after the WW2 Japanese surrender. Many years ago there was a minor agreement with Baillie Gifford which involved Dai-ichi personnel studying BG investment methods in Edinburgh, allied, I believe to some investments capital placed with BG. This looks much weightier with the key difference being the apparent intention to act as a major share buyer. I can't see that it would prove anything less than beneficial for M&G. Incidentally, Dai-Ichi was for many years a mutual life company but the company was listed under the Japanese market code 8750 some years back. I would guess the company is enjoying the benefits of an higher interest rate environment. The market cap is just over £20bn equivalent, roughly x4 the size of the British-based company.
HVO was a share I bought back in Jan at about 20p. I heard many positive things about it and thought it sounded pretty good. I sold out 2 months later at 15p when I realised I had made a mistake. The company seemed way too promotional to me, and too eager to buy other businesses.
Shares are now 8.7p. Sometimes there's just a bad "smell" to a company and it pays to get out.
Warehouse Reit (LON:WHR) done deal at 110.6 p - another UK listed entity off the market. Long drawn out drama now over with
? Not yet! I read PUSU extended to 6th June.
The detail is in the RNS NeilS of the revised final offer.
The detail is in the RNS NeilS of the revised final offer.
NeilS is correct, this is not a final offer.
The RNS is a PUSU deadline extension extending the offer period by a week and notifying that market that that revised bid price is 110.6p. Blackstone haven't submitted a final offer and could still pull out, although that's presumably unlikely unless there's a world wide financial crisis in the next week.
Although, frankly, at the moment anything is possible.
https://www.londonstockexchang...
timarr
Buts it's recommended ...
But*
Buts it's recommended ...
So was the previous one, but Blackstone renegotiated that.
At this stage it's unlikely to not go through but I have seen it happen when a financial crash occured between the recommendation and the final bid. However, a mere week's extensuon does imply the extra time is to finalise terms rather than to allow further due diligence.
timarr
Bottom line is that the takeover is now 99% going ahead at 109p and will be wrapped up imminently next week.
"On 19 May 2025, Blackstone submitted a final* revised proposal at 110.6 pence per share"
Seems final to me, save the usual caveats. It's not a done deal though. That I agree on.
Seems a pretty poor deal at a 15% discount to NAV.
ITM Power (LON:ITM)
Price spike on about double volume.
Probably one of the two disclosed shorts closing I think.
Hold a speculative small position here on the basis that hydrogen could gain traction in the energy transition.
But you've always got to remember Betamax.
A
Albertos I four interested in hydrogen have a look at Hydrogenone Capital Growth (LON:HGEN) Been a bad investment for me- I bought on launch as keen on the sector. Now trading on a crazy discount to NAV of 70% despite the NAV only falling 11% since launch. They are, in my opinion, going to have to do something re the discount. I would think maybe another lot larger hydrogen fund might/should have a look at it.
But I have no reason to think that is happening I hasten to say.
Thanks for that Charles
I will investigate.
A.
Agree on your view on Autotrader Graham - wonderful company but I also would want a bit of a better buying opportunity than this still, but I doubt anyone would regret buying at this price if they just buy and look back in 10 years.
I have a lot of respect for Autotrader, having worked in senior roles at various competitors, as well as for some years being a large customer to them, have spent time in their office near St Pancras a number of times and seen how they work. Anyone in the industry knows that these guys are unkillable, even if what they're selling is not that good or horrendously expensive you still have to suck it up and pay for it because everyone else is and they just get an insurmountable advantage if you do not follow suit!
They have so many advantages that no one will catch up realistically - not just their brand name, but these guys use their advantages to create more advantages, both large and small. As a small example, in the UK if you want to know the specific options fitted to a car, you might normally have to pay someone like CAP HPI some miserable fee like £0.50+ per car (which is unmanageable if you for example want to check thousands of cars daily to decide whether to purchase them), Autotrader had access to this data because they work with the manufactures on a totally unrelated project, but used that relationship as an opportunity to talk them into doing a deal for them to pass this data along to customers without any transaction fee, totally breaking a long established model and opening up many possibilities for consumers, who suddenly get an amazing perk by being a customer - they hadn't covered all of the manufactures when I was involved but a fair few and were adding more all the time. Just a small example of an endless number of advantages that you could not catch up to as a competitor even if you had billions of pounds and 10 years to give it a go.
Similarly, Constellation that own BCA/Cinch/WeBuyAnyCar is not going anywhere, these two businesses will dominate for a long time unless something massive happens (anti-monopoly regulation, or the whole car ownership model changes in some drastic way).
Re Auto Trader (LON:AUTO) I totally agree they’re a dominant player in an incredibly profitable & sizeable niche…my only observation is that they have made at least one big strategic misstep imho…they paid £200m for vanarama iirc…which has lost them bucketloads ever since. to me this suggests mgt desperation to enter new markets that might longer term be a risk for shareholders…they are generating loads of cash but aren’t necessarily allocation it wisely imho
Inspecs (LON:SPEC)
To eParo - We had a brief chat on these last week following Luke Johnson's top up, just to let you know I'm also in and just tried to top up now at 50p but absolutely impossible to buy any quantity at that price.
Maybe Totterman's announced departure is the catalyst for a recovery and re-rating? It's what Downing wanted in their GM requisition......
Let's hope so. A key competitor in Germany has filed for insolvency which will help too Inspecs (LON:SPEC)
Biopharma Credit (LON:BPCR) With ref to hvivo and current market uncertainty. Recently a Stocko member highlighted an IC article in which John Barron (I think) suggested this stock as a non cyclical source of approx 8% divi. Views on whether this still holds would be useful to me as I was beginning to get quite excited about the use of BPRC as a further source of income! Confirms the need for DYOR if nothing else.
FWIW I’ve held since 2017. The value is pretty much unchanged but it’s returned slightly over 50% of my purchase cost in dividends with reasonably low volatility.
I feel quite confident in the ability of the managers to assess risk and structure loans for upside and as a specialist I think they are a go to source for funding in the industry and can cherry pick good opportunities.
JNEO. To those who hold I believe many might have missed an important element in yesterday's RNS - Alstom is a NEW client. To win with a real international major is a great achievement. The fact that Alstom is French possibly might have added another dimension to the deal.
Cavendish - hVIVO (HVO): CORP
Industry headwinds, downgraded expectations
hVIVO has announced that it has received notification of a ‘significant’ HCT contract cancellation alongside a postponement and a smaller study cancellation.
While the wider CRO landscape has met with headwinds in recent months, our assumption is that the most recent moves from the Trump administration to initiate and implement policies to tackle drug pricing in the US has resulted in drug developers further deferring decisions, or cancelling certain existing programmes, resulting in material volatility in the industry.
hVIVO will provide clarity on the FY25 outlook later in the year (and a 1H25 trading update is expected in late July) but given the company has £47m of revenue contracted for FY25 to date, we use this as our highly conservative base case assumption, and now expect losses in the current year.
Our new target price of 20p (35p) represents 10.9x EV/adj EBITDA on our downgraded expectations for FY26.
Also some senior indivuals in the US Government administration are vaccine sceptics. That does not bode well downstream for the type of respiratory virus challenge trials thathVIVO (LON:HVO) offers.
I sometimes listen to a podcast on viruses (this weel in Virology). It has recounted US government research labs and staff being closed down overnight.
So I am today one of the disappointed hVIVO (LON:HVO) shareholders, and I don't hold out much hope for a recovery from US originated pharmaceuticals trials. The issue isn't tarriffs it's their administrations approach to science and medicine.
Really solid set of results last night from Ulta Beauty (NSQ:ULTA) , raising forecasts for the year and trading +8% pre market. Anyone unfamiliar with the company, it's similar to Sephora in that it sells a number of different makeup and beauty brands.
I came across it in this YouTube video, worth a watch.
?si=UqVKjx-RDQDs3fgeThis one has taken longer to work for me than I'd hoped but looks like there's some momentum now. Nice set up- moderate topline growth + steady and significant buybacks + eventual re-rating to something nearer 18-20x (bear in mind this is a US stock) ought to get you 10-15% p.a. fairly comfortably over at 3-5 year period.
Another acquisition for AdvancedAdvT (LON:ADVT) was announced today, their second this month. It’s good to see the cash pile being deployed, albeit on an accretive basis rather than a knockout deal.
Potentially interesting use of cash and share issuance to close the deal when the cash in the bank would easily pay for this acquisition several times over.
Does this indicate a much larger deal in the pipeline, with cash being held back for that?
Tungsten West (LON:TUN)
Mining operations to recommence at the Hermedon tungsten and tin mine after a feasibility study. This should benefit Hargreaves Services (LON:HSP) that has exclusivity in the provision of earth moving and engineering services for mining operations at the site.
Not so much a minnow as a stickleback.
Warehouse Reit (LON:WHR) PUSU deadline today for Blackstone. They have until 5pm but the last announcement, on 12th May, was at mid-day.
hVIVO (LON:HVO) have announce a large contract cancellation which reduces their current year revenue from £75M - £47M. I'm expecting to see some volatility here today ... Thankfully a very small holding for me.
Some volatility? hVIVO (LON:HVO) will get atleast a 50% haircut today imo.
It’s funny, it’s been a bugbear of mine for the past couple of months, all these talking heads who come on the radio/tv to comment on the “Trump Tariff”disasters talk in terms of “market volatility” when they really mean the market has been flushed down the khazi! It really is strange.
I recall folks saying that customers paid up front. Maybe not methinks...
Yes, time to find your 'tin hat', I fear. That is a huge undershoot of expectations by hVIVO (LON:HVO) and I would expect the shares to tank today. It is a pity because it sounded a compelling story and was growing nicely for a while, but perhaps the lesson is to be wary of overenthusiastic Chief Execs who sound like salesmen!
That’s a very poorly informed comment. The CRO industry has been thrown into complete turmoil. It’s not the fault of the CEO for overpromising. It’s down to the circumstances which caused their income stream, which, let’s remember, was contracted, to be cancelled.
Should the CEO not inform the market of future contract wins because of the possibility of them being cancelled? Would it be best if companies didn’t report any developments to shareholders at all in case future events cause adjustments?
I understand your pain, BnB, but isn't there a bit of 'holder bias' in your response? I don't know anything much about the CRO industry but do you have evidence that others have suffered such big contract cancellations? I also question the quality of the industry if 'contracts' can be cancelled that easily without compensation. One response here from investors might be to place their revenues on a very low rating to reflect the lack of visibility?
do you have evidence that others have suffered such big contract cancellations?
Shares of IQVIA, the biggest CRO in the world at USD24bn mkt cap, have halved. Those in Icon, an USD10bn mkt cap challenger, are down over 60% on a series of major cancellations.
I also question the quality of the industry if 'contracts' can be cancelled that easily without compensation.
Contract cancellations do carry termination fees, but are by no means adequate to cover the loss of profit
No pain. This is just what goes with owning businesses in the cycle of markets
good to have your insight back on Stocko BnB. If it does 'tank' today is that an entry point though, given years of uncertainty to come?
Is that an entry point?
There’s every possibility that this is a great price for the long term. But the picture is very uncertain right now and shares could equally halve again on more prolonged tightness. I would suggest ignoring the chart and re-evaluating the shares when the market shows signs of stabilisation. That would be the entry.
I bought more this morning - in fact more than doubled my holding for a pittance really. The drop just seemed significantly overdone imo especially with the cash being so close to the new (low) market value. I can't blame Mo, the CEO, for this - it is surely caused by the situation in the US which was openly discussed in the Press and the forums when Trump took office.
Re hVIVO (LON:HVO) back in January's IMC this question was asked..I’m not sure the answer given sits well with today’s RNS
Thank you for that background info, BnB. You clearly know more about the industry than I do. However, if I were a holder here I would certainly be asking why management were being bold enough to still forecast £73m of revenues for 2025 as recently as April if there was this much turmoil going on in the industry.
Management base their forecasts by looking at the pipeline and applying a success percentage to each one. I had thought that they would have lowered those percentages once Trump was elected. We were never informed what was the value was of the large contract but plainly it was a real whopper and that is the real problem we have here - the smaller contract losses and the postponement would have been absorbed otherwise.
hVIVO (LON:HVO)
‘These client decisions are believed to be related to the current uncertainties in the pharmaceutical industry and the continued depressed biotech financing market. The current volatility in the pharmaceutical industry, particularly in the US, is impacting the whole CRO industry and has led to an increase in cancellation rates, postponement of clinical trials, and delays in approvals for new projects.’
This is not unique. Angle (LON:AGL) announced on Wed that new contracts were being delayed for the same reasons, esp anything that could be related to Medicare in the US.
Not sure I can agree with this view. To those of us who invested and held in Ideagen we had the great fortune (literally) to have first David Hornsby as CEO - a consummate salesman and and then Ben Dorks; another consummate salesman. The ability to manage and sell are fundamental to success.
This is appears to be a short term mishap for hVIVO (LON:HVO) . While Trump is still pulling the strings there is little incentive to invest in Pharmas in general. However, with hVIVO (LON:HVO) longer term order book and pipeline, there is a possibility of recovery in 2026 onwards subject to 2025 H1 trading update in July.
Whilst there has been a 50% plus drop in SP this morning , I wouldn’t just write hVIVO (LON:HVO) just yet. For some adventurous investors this might be a buying opportunity.
So for now just sitting on the fence unless some interesting statement comes out before then.