Daily Stock Market Report (Fri 3rd July 2026) - CRW, MRK, G4M

Good morning! Please note that US markets are closed today for Independence Day.
In market movements, the South Korean Kospi Index rose nearly 5% yesterday and is up 86% year-to-date. Samsung Electronics and SK Hynix are together worth more than half of the value of this index, a fact which I only learned this year and which I find terrifying.
While passive ETFs have done a wonderful job of opening up low-cost investing to the masses, they don't prevent - and may actually fuel - index concentration in the biggest winners. I always thought the S&P 500 was the poster child for this phenomenon, but I was wrong - it's the Kospi!
Overnight market movements:
The FTSE is up 0.2% at 10,690
S&P 500 is up 0.4% at 7,500
Brent crude (September) is up 0.9% at $72.40/bbl
Gold is up 1.2% at $4,170/oz
Bitcoin is up 0.2% at $61,700
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Craneware (LON:CRW) (£501m | SR38) | FY26 financial performance to be below market expectations, with revenue of US$205-$208 million and Adjusted EBITDA of US$65-$67 million, both broadly in line with FY25. Trading in the final weeks of FY26 was materially impacted by a slower than anticipated conversion of identified 340B opportunities into recognised revenue. | BLACK (AMBER ↓) (Graham) We’ve been moderately positive on Craneware. In hindsight, should we have seen this coming? Perhaps, but I don’t follow domestic US politics very closely. This profit warning seems to reflect the very specific conditions at present, where pharmaceutical companies and the Trump administration are looking at ways around the 340b programme. Craneware’s share price is equivalent to about $16, so the P/E for the current financial year (FY27) is 13x. Given the quality that the business demonstrated historically, I think this could be a fair price - with upside if dramatic regulatory changes do not materialise. | |
| Amaroq (LON:AMRQ) (£389m | SR10) | Update on Intention to Move from AIM to Main Market | Gives notice of its intention to cancel the admission of its shares to trading on AIM. “We believe that a move to the Main Market will enhance our visibility in the capital markets, support access to a broader pool of institutional capital, and further strengthen our platform as we continue to execute our growth strategy.” | |
Strategic Minerals (LON:SML) (£120m | SR47) | Cornwall Council's Mineral Planning Officer has approved planning permission for the proposed expanded drilling programme. Drillhole CRD044 was completed on 25 June. Drillhole CRD044_D1 is underway and advancing. | ||
Marks Electrical (LON:MRK) (£48m | SR73) | CFO has informed the Board of his decision to leave the Company. He will continue to fulfil his current role, which will include supporting a smooth transition. | AMBER = (Graham) [no section below] Last year, Marks Electrical lost its CFO of five years. They found a permanent successor in November 2025, but he isn't staying around much longer. Today's announcement is short on detail: he isn't thanked but the departure is said to be his decision, with the implication being that he hasn't been let go. Including their interim CFO, this means that Marks Electrical will soon have their fourth CFO since June 2025. This doesn't bode well for the company's recovery, but I'll leave our neutral stance unchanged nonetheless as the company did have a net cash position when it reported last. If it was already financially distressed, I would interpret this news much more negatively. | |
Cobra Resources (LON:COBR) (£43m | SR9) | Appoints Stephen McIntosh as Strategic & Technical Advisor to support the advancement of Cobra's Heavy Rare Earth Project through technical and economic studies and accelerate exploration at its Manna Hill Copper Project. | ||
Medpal AI (LON:MPAL) (£18m | SR0) | Has conditionally raised gross proceeds of £5m at 3.5p (last night’s close: 4p). Proceeds fund the acquisition of Solid State Technologies Ltd, a profitable electronic Medicines Administration Record software business. | ||
Altitude (LON:ALT) (£18m | SR46) | Appoints a new CFO designate. He has been CFO, Exec Chairman and NED of Altitude before. |
Backlog
Gear4music (HOLDINGS) (LON:G4M)
266p (£56m) - Final Results (23rd June) - Graham - GREEN =
We never got around to covering this when the results came out last week, so I’ll take the opportunity to do that now.
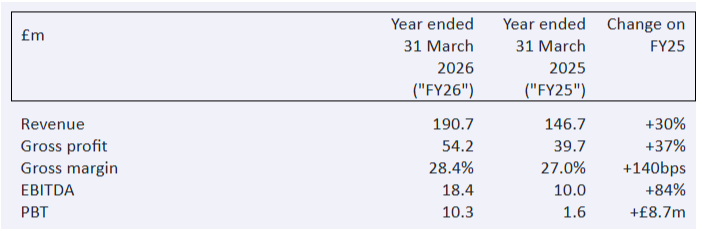
The highlights are excellent:
The company’s headline is:
"Significant revenue growth, and EBITDA and PBT ahead of recently upgraded market expectations with a confident outlook"
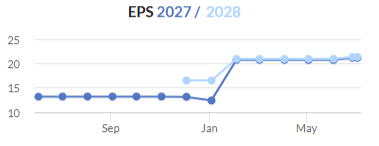
Market expectations for EBITDA are given as £18.1m, so that figure was beaten by just 2%, but the company had already upgraded expectations earlier in the year:
Comment by the founder, Exec Chair and largest shareholder Andrew Wass:
"We are delighted to report that FY26 delivered significant strategic, commercial and financial progress, with strong revenue growth of 30% contributing to an excellent full-year financial performance. Improved gross margins combined with disciplined cost control have driven an 84% increase in EBITDA and a significant improvement in profit before tax, an increase of £8.7m compared with the previous year.
The commercial KPIs for 2026 were excellent: active customers up 22% and products listed up 5%. The conversion rate for the website fell slightly from 1.51% to 1.39%.
FY 2026 was a unique year as two of G4M’s UK competitors went bust: GAK (Guitar, Amp & Keyboard Centre) and PMT (Play Music Today). A European competitor also went bankrupt in Spring 2026.
In those circumstances, and also considering that G4M swooped in and picked up assets from both of the UK businesses on the cheap, it’s not surprising that it had an excellent year. The European competitor that went bankrupt was Bax Music.
Outlook:
Multiple growth-focused technology and systems upgrades launched during Q4 FY26 and Q1 FY27 are performing well and set to yield benefits in FY27… FY27 trading to date in line with board expectations and on track to deliver FY27 consensus market expectations.
FY27 expectations are helpfully provided: revenues of £200.2 million, EBITDA of £16.0 million and profit before tax of £6.0 million.
This means revenues are forecast to rise by 5%, but profits are set to dip lower. PBT in particular is set to fall by 40%, according to these expectations - emphasising for us again the exceptional nature of FY26. There’s also going to be significant spending and costs associated with a new UK warehouse.
Net debt finished FY26 at £5m, a small improvement on FY26. Gross outstanding loans of £13m.
Balance sheet: tangible net assets of £26m.
Dividends: no dividends here and I think that’s fine, considering the size of the business and the opportunity to continue investing in its growth and reducing net debt..
Graham’s view
We’ve been GREEN on this and I think it makes a lot of sense to stay GREEN on this today.
When competitors fail, the benefits for industry survivors are often enormous and long-lasting.
Gear4Music is currently reaping the rewards of survival in a competitive industry: some of these benefits are short-term (buying assets cheaply out of administration) but some will also be long-term (increased consumer trust and pricing power).
I will note that G4M’s own-brand product revenue (up 24%) hasn’t kept pace with other-brand product revenue (+32%). So I think it’s fair to say that the Gear4Music product brand is not outperforming other brands. It does, however, provide G4M with a high-quality revenue source and nearly a quarter of its total product revenue.
Overall, I continue to like the story here.
It has perhaps been ludicrously overvalued in the past:
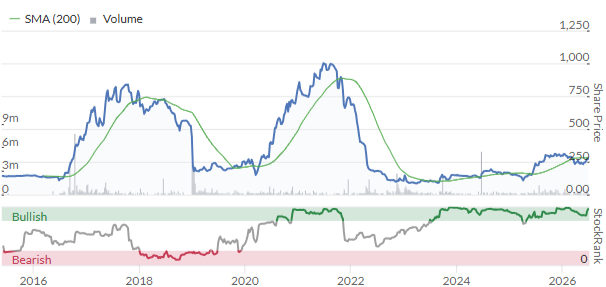
At the current share price 266p, it’s around 13x FY27 earnings earnings. Given the positives - founder-led, bankrupt competitors, a healthy own-brand product line, and a new warehouse on the way - I’m comfortable with us staying GREEN on this for the time being.
Graham's Section
Craneware (LON:CRW)
Down 18% at £12.06 (£410m) - FY26 Trading Update - Graham - BLACK (AMBER ↓)
Craneware (AIM: CRW.L), a leader in healthcare financial performance solutions, provides the following update on trading for the financial year ended 30 June 2026 ("FY26").
This sounds like a serious profit warning, exacerbated by the fact that it’s arriving so late in the financial year.
The Board expects the Group's FY26 financial performance to be below market expectations, with revenue of US$205-$208 million and Adjusted EBITDA of US$65-$67 million, both broadly in line with FY25. This change results from the timing of eligible 340B activity and the deferral of a small number of significant enterprise contracts, which are now expected to contribute during FY27. The final reported outcome remains subject to confirmation of eligible 340B activity recognised before the financial year end.
Estimates:
I have access to forecasts from Capital Access via Research Tree (thanks to both).
Previous forecasts for FY June 2026 were as follows: revenue $225.7m, adj. EBITDA $69m.
New forecasts: revenue $207.2m, adj. EBITDA $66.3m.
Unfortunately, it’s not just FY26 that gets cut. FY27 and FY28 also get a substantial trim.
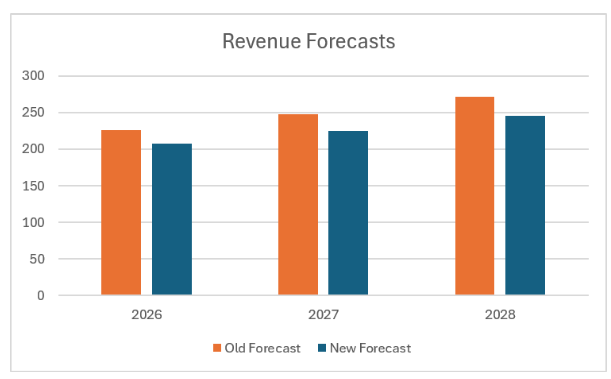
It seems to me that the company’s revenue progress has effectively been put back by a year, i.e. the new FY27 forecast is similar to the old FY26 forecast, and the new FY28 forecast is similar to the old FY27 forecast).
The Adj. EBITDA forecasts get cut too but they aren’t put back by an entire year, thankfully:
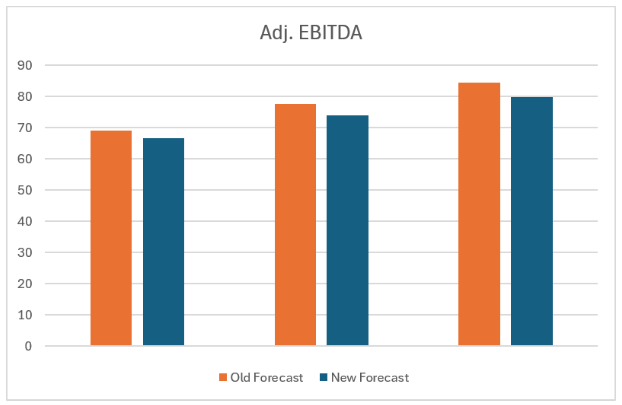
In percentage terms, there is an 8-10% cut to the revenue forecast for each year, but only a c.. 4-6% cut to the adj. EBITDA forecast each year.
Let’s turn back to the trading update itself and learn more about what has gone wrong:
Craneware continues to identify substantial opportunities for hospitals to optimise their 340B programs; with outstanding 340B qualifying drug purchases in the region of $500m, however, the pace at which those opportunities translated into eligible drug purchases slowed significantly as pharmaceutical manufacturers further expanded and operationalised restrictions on the supply of certain 340B-priced medicines.
I’ve mentioned 340b many times before in relation to Craneware: it’s the US program that enables hospitals and clinics to get drugs at discounted prices. Craneware’s software allows these entities to track and optimise their 340b spending.
However, it sounds like the pharmaceutical industry, and the Trump administration, may currently be working against 340b in its current form.
Some headlines in the last 24 hours:
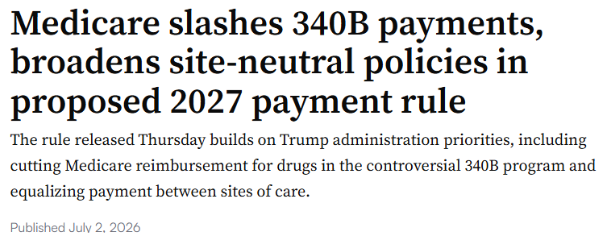
Source: healthcaredive.com
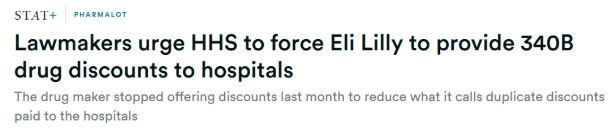
Source: statnews.com
I don’t follow US politics all that closely, but from what I can gather, the Trump administration wants to reduce the discounts offered to hospitals. This in turn would reduce the value of managing and optimising these discounts.
The thinking is that 340b is making hospitals rich, not helping sick people. For example, an article in the Washington Examiner last week suggested that 340b was being used to subsidise hospital acquisitions and build healthcare “empires”, rather than directly helping patients.
Here’s what Craneware have to say:
The Board believes that these factors reflect a short-term timing impact to the FY26 results. Looking ahead, customer demand is increasingly extending beyond software and analytics towards technology-enabled operational transformation that helps healthcare providers realise the opportunities identified by the Group's platform. Craneware has been developing these capabilities over the last three years and they now represent a meaningful and growing component of the Group's offering. This reinforces, rather than diminishes, the long-term strategic importance of Craneware's platform within the evolving US healthcare ecosystem.
Graham’s view
We’ve been moderately positive on Craneware. In hindsight, should we have seen this coming? Perhaps, but again - I don’t follow domestic US politics very closely. This profit warning seems to reflect the very specific conditions at present, where pharmaceutical companies and the Trump administration are looking at ways around the 340b programme.
In valuation terms, the new EPS forecasts are:
FY26: $1.11 (down from $1.18)
FY27: $1.25 (down from $1.35)
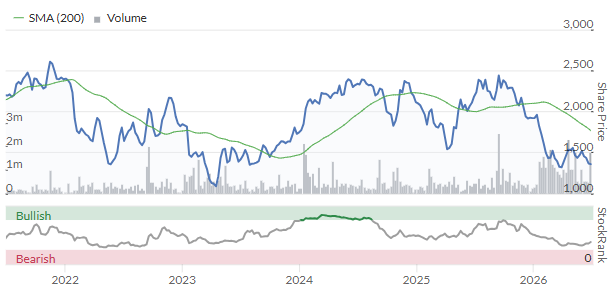
These are modest cuts of less than 10%, and so you might think that the 18% fall in the share price today is harsh.
However, I think that the warning highlights a potential vulnerability to regulatory change, which could become a serious issue.
Craneware’s business, as far as I understood it, was built primarily around 340b optimisation. The reference to the company helping now with “technology-enabled operational transformation” says to me that they are already looking towards a future when 340b optimisation alone becomes much less lucrative.
So I think it’s right to be cautious her. I’m taking our stance down one notch, as is customary when there's a profit warning, to neutral.
Craneware’s share price is equivalent to about $16, so the P/E for the current financial year (FY27) is 13x. Given the quality that the business demonstrated historically, I think this could be a fair price - with upside if dramatic regulatory changes do not materialise.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

41 comments
Meta Platforms (NSQ:META) is reportedly in talks with Samsung Electronics Co (KRX:005930) foundry business to design and produce next-generation MTIA AI chips worth over ~10T won ($6.5B).
The potential deal would strengthen Samsung's position in the AI semiconductor market and add to growing demand from custom AI chip customers. Industry estimates suggest Samsung's foundry order backlog could approach 50T won ($32.5B) over the medium to long term.
Beyond Meta, Samsung is reportedly attracting interest from AI companies seeking alternatives to external processors such as NVIDIA GPUs and Google's TPUs.
Separately, Anthropic is also said to be considering Samsung's 2nm process for developing ASIC chips as part of efforts to reduce dependence on third-party AI hardware.
All the best
Coming late to the party on Craneware (LON:CRW) my research doesn't indicate that this is a timing issue in their financials. It sound much more fundamental, and there are big battles going on in there. My summary, with the help of AI!
The 340B program strictly covers outpatient prescription drugs. It excludes inpatient medications entirely. Eligible drugs are broadly categorized by federal guidelines into three main buckets:
Why Manufacturers Are Restricting 340B SupplyThe program has grown into a multibillion-dollar marketplace, heavily driven by "Contract Pharmacies"—outside retail or specialty pharmacies hired by hospitals to dispense these medications.
Manufacturers have aggressively expanded supply restrictions for three main commercial and compliance reasons:
1.. Eradicating "Duplicate Discounts" Federal law strictly prohibits a manufacturer from paying a 340B discount and a Medicaid rebate on the same unit of drug. Manufacturers argue that the explosion of third-party contract pharmacies has created massive gaps in data sharing, forcing them to inadvertently pay double discounts on millions of prescriptions.
2. Combating Patient DiversionBy law, 340B drugs are reserved exclusively for eligible patients of the qualifying hospital or clinic. Manufacturers argue that without strict guardrails, independent and Pharmacy Benefit Manager (PBM)-owned retail locations frequently cross-contaminate inventories, routing discounted products to non-eligible, commercially insured consumers.
3. Protecting High-Margin Specialty Drugs. A select few highly expensive specialty drugs account for more than half of all contract pharmacy financial margins. Manufacturers target these drugs to legally bypass federal inflation penalties (which heavily discount a drug if its price increases faster than the rate of inflation) and stop PBMs from capturing the massive profit "spread" between the 340B purchase price and the commercial reimbursement rate.
How Manufacturers Operationalize Restrictions. Pharmaceutical companies have built a highly systematic playbook to enforce these restrictions, moving from sweeping bans to technical and data-driven bottlenecks:
I hope that means a lot more to you than it does to me. What I see is not a timing issue, as described in Craneware (LON:CRW) accounts. I see a lot of red flags, and IMHO this is not going to be resolved in Craneware (LON:CRW) and their customers' favour in the short term. This is really big bucks and the big pharmas involved don't seem too keen to help! It is not a threat to the company's survival but is a big barrier in their profitable growth. What a mess the US is!
I would like to remind everyone that the KOSPI companies are projected to report net profits in the region of $1T-$1.2T in the next two years, and the FTSE100 companies are expected to announce net profits of less than half of the above figure.
Graham has the right to write whatever he wants, but his comments are far from reality and the true facts. KOSPI is the poster child of the SP500??
Just reminding Graham about NVIDIA (NSQ:NVDA) Apple (NSQ:AAPL) Microsoft (NSQ:MSFT) Amazon.com (NSQ:AMZN) Alphabet (NSQ:GOOGL) Meta Platforms (NSQ:META) Eli Lilly and Co (NYQ:LLY) Walmart (NSQ:WMT) Exxon Mobil (NYQ:XOM) MasterCard (NYQ:MA) Costco Wholesale (NSQ:COST) Coca-Cola Co (NYQ:KO) Netflix (NSQ:NFLX) Merck & Co (NYQ:MRK) Goldman Sachs (NYQ:GS) Citigroup (NYQ:C) Abbvie (NYQ:ABBV) JPMorgan Chase & Co (NYQ:JPM) and many many other great companies.
Just reminding Graham and everyone that the SP500 is up ONLY 9.11% YTD and at the same time the FTSE100 is up 6.78%, so obviously there is no much difference.
All the best
Read both articles and I’ll stick with Graham’s view.
Read them again, take off the blinkers and pretend that mine was written by someone called Ed!
Spot the difference?
All the best
Rather assumptive of you to assume I’m wearing blinkers. Your apology would be appreciated.
I do apologise Chris, but please read my figures as they are all correct.
All the best
'KOSPI is the poster child of the SP500??'
Graham said that Kospi is the poster child of index concentration, which I think is a fair statement given the percentages involved. He hasn't said the SP500 doesnt have lots of great companies, only that there was some index concentration (but not that much relatively to the Kospi).
Where does Graham say "KOSPI is the poster child of the SP500??", to quote your post?
Playing with words here!
It’s not the SP500 the poster child of ETF’s but the KOSPI……..
Remember this obsession is going for days now……and Graham is trying to link the US stock market with the SK market, thinking (wishing) that a crash in SK will collapse the US one.
Graham continues to undermine and in every opportunity trying to criticise the best growth stock market that attracts the best investors and talents in the world.
I have provided figures about the KOSPI stock market. Stock markets move with growth and profits!
Are these SK profits sustainable in the future?
No one knows that.
All the best
With all due respect, I think you've slightly misread Graham's post. If I read it correctly, he was highlighting the issue of the concentration of big winners in ETFs which, imho, has become a challenge for passive investors. I don't think he was pouring cold water on any of the companies you mention.
It has been going on for some time now. I have read Graham’s post very carefully and I understand where it’s going. The SP500 has not been going up because of these amazing companies and their growth but because of the passive ETF’s -:)
Graham tries to find an excuse for the US market to collapse. I know very well what I am saying. He tries to connect the two markets, because of the semiconductors play, insinuating that the US market will crash on any SK stock market collapse.
My figures (in my original post) are all correct.
The US market will have a problem because of the massive government debt and not because of these great companies. iShares 20+ Year Treasury Bond ETF (NMQ:TLT) daily movements support my theory. But as always, they will find the way to overcome any problems and continue their journey…..
When Graham feels ready to discuss the US market, EPS growth and its outlook, I am here!.
Have a great weekend everyone and hopefully England will beat Mexico.
All the best
Indeed, Brian, I'm heavily invested in FAANG through my holding of the ACWI in a pension fund. I hope they all continue to do brilliantly. I previously made a nice profit from personally investing in Alphabet (NSQ:GOOGL), and from Berkshire Hathaway (NYQ:BRK.B)'s investment in Apple (NSQ:AAPL) (I still hold BRK.B). The so-called "hyperscalers" are objectively the best companies in the world. I'm not a hater! G
Interestingly Wise (LON:WISE) has slowly been marching higher and is now comfortably above the share price before the regulatory investigation drop (and above the 200DMA and 50DMA). Perhaps others with more knowledge are confident on the outcome of the investigation?
Think in this the lack of news is good news. These type of things are reasonably routine for banking companies and unless something comes from it then it might never be mentioned again. Wise (NSQ:WSE) like there financials to do the talking - happy holder
Wise (LON:WISE)
These type of things are reasonably routine for banking companies and unless something comes from it then it might never be mentioned again.
did they themselves not mention potential penalties ? - i think if they thought they had done nothing wrong that they would have robustly defended themselves against such speculation rather than go out of their way to mention penalties when they could have said nowt.
If they are able to carry on much as before and it it is a monetary penalty that probably changes little ref current valuation - it would be much more an issue if they need wholesale changes of their procedures - if its deemed they arent up to scrtach ref checks they do / did.
Good morning Graham, Firstly I much enjoy your morning reports. Goes well with an espresso. Sadly ETFs no longer do what they say on the tin. Hyperscalers appear to have worked their way into so many passive funds that unless you want to expose yourself that kind of risk, it's no longer worth the bother. Anyway, Happy Friday!
The Kospi has been boosted by a huge obsession with retail investing by ordinary Koreans.
Don't worry, It will never happen in the UK
I've recently increased my stake in Henderson Far East Income (LON:HFEL) as a play on not just Korea but the whole of the Asia Pacific region. Pays a steady divi and increases diversity of portfolio by selling shares to other institutions and re-investing cash.
Aberdeen Asian Income Fund (LON:AAIF) has 22% in South Korea (I hold), Aberdeen Asia Focus (LON:AAS) 14% and Henderson Far East Income (LON:HFEL) 20%. HFEL looks like it has improved, there was a period it was paying dividends out of reserves. I held a Korean ETF at the start of the year- sold it after a rapid rise and made a decent return for a couple of weeks holding it but obviously should have continued holding. The market is prone to large movements-up and dwon.
Fidelity Emerging Markets (LON:FEML) also has 12%
Yes I think there have been quite generous incentives or tax breaks to get people investing into Korea. We need something similar here as it could give UK markets a much needed boost.
India had the same 2024/25- and then ended not well.
From AI: Samsung Electronics and SK Hynix together account for roughly 54% to 60% of the entire KOSPI index
!!!!
If so Henderson Far East Income (LON:HFEL) should start to fly!
Craneware (LON:CRW) I do wish they would not use such gibberish 340B - A 340B opportunity refers to the potential for eligible healthcare organizations to generate financial savings or expand patient care services by participating in the federal 340B Drug Pricing Program. [1]This program requires pharmaceutical manufacturers to sell outpatient drugs to qualifying healthcare providers—known as "covered entities"—at steep discounts ranging from 20% to 50%. An "opportunity" typically means finding ways to maximize these discounts, improve compliance, or partner with pharmacies to capture more savings.
Thanks for the clarification
A few weeks ago I did some digging into Craneware (LON:CRW) given that I can't help myself looking at shares that have hit 52-week lows, like a moth to a flame.
After hours spent digging into the 340B drug programme, I put Craneware into the "look at it later bucket when the regulatory dust settles".
Its is clear that there is a big war over the 340B program in the USA at the moment. Drugmakers hate it, and have been trying to subvert it for the last year few years, if not longer. They feel that there is huge abuse of this discounted drugs program, and they're losing out lots of profits. Individual states have passed state laws on the 340B program, to protect cheap drugs for their voters.
The federal department that administers it wanted to reform it last year, by moving to a radical program of rebates later, rather than an upfront discount at the point of purchase. They had to roll back a pilot program in Dec25 after lawsuits and a court decision.
Pharmacies are apparently reaping huge profits from 340B, unjustly (but legally for now). This is what is causing a lot of the angst, I believe.
There's a draft bill proposed in one of the legislative chambers last month, that radically reforms 340B.
Craneware is stuck in the middle of this storm. I suspect that quite a large majority of its business, is software that faciliates the administration of 340B for hospitals. Thus, this junction poses either a major threat or opportunity for Craneware.
But it also shows that Craneware has potentially a unique singular risk factor - to the 340B program - that really hasn't been made obvious in the past. Hence why maybe their share price has drifted down so much in the past 1-2 years, as some investors has cottoned on to this.
had an offer over £26 , you'd imagine after the dust settles could be a TO target again
Maybe.
But if you look at the timing of the Bain Capital approach last year.
And then the timeline of all the announcements around the 340B program last year, including lawsuits, drugmaker activities, etc.
You'll find that... possibly.... at least when I "connect the dots".... that Bain walked away because of potential escalating 340B risk.
However, the flip side to my thinking... is that the angst/issues with 340B have been around for years, so Bain would have known about it before a bid or approach. But maybe the escalation in the spring of last year made them get cold feet.
maybe but of course 26£ a possible TO would be nowhere near there but 18-20£?
I would be wary of relying on some proposed takeover approach months ago as an underlying value comfort blanket. There appears to be developing significant political risk going forward, that holds more weight for me.
Thanks very informative post - I really should have done this level of research myself before investing in Craneware. Luckily only a smallish position for me, but certainly not tempted to add any more given what appears to be huge regulatory uncertainty
For what it's worth, Montanaro UK Smaller Companies Investment Trust (LON:MTU) recently added Craneware (LON:CRW) to their portfolio.
My wife has been a longtime holder and can't recall the last time it was in the black, much to her frustration.
I'm sure you're right - the 340B drugs must be an intrinsic part of every hospital's day-to-day business. Craneware's software has to manage this and they argue that their systems are up to the job but the current uncertainty is holding things up. Their media release makes the point that their revenue comes at the end of the process (the customer) even though they've adapted to the revised regime - and they've only recently had the data needed to assess the impact on their profits. This is what their media release says:
The Group recognises a significant proportion of this revenue upon the customer receiving the benefit from these eligible 340B drugs, rather than at the point opportunities are identified. The financial impact of this reduced conversion only became apparent once the actual amount of 340B drugs shipped to the hospitals before year end became clear. The Board believes that these factors reflect a short-term timing impact to the FY26 results
Boon, I've only just read your comment - and it seems to echo many of the points I subsequently published. Great minds think alike! (and fools seldom differ).
While I mentioned that this could be a threat or opportunity for Craneware... I do want to expand a bit more on the opportunity bit. Just to balance out my commentary.
Craneware (LON:CRW) might be a beneficiary of 340B potential changes.
The government (federal or state) might change/add rules that make it even more complex to administer 340B. This is a reason the Trisus software from Craneware exists. To digitise and automate manual paperwork and bureaucracy.
If more "software" is needed, can Craneware get hospitals to pony up more fees? Will pharma manufacturers need to do paperwork too, and therefore Trisus4Manufacturers becomes a new product, new revenue stream?
As a Craneware (LON:CRW) sharehokder, I'd be interested to hear whether Graham thinks this is a "sell-the-profit-warning" moment.
It sounds like a timing thing, so I am not inclined to sell at this stage unless they bring out guidance to the contray through the analyst reports
AMRQ maybe worth adding to the companies reporting table.