Daily Stock Market Report (Fri 4 July 2025) - GLE, FUTR, AVAP

Good morning!
As it's the Fourth of July, US stock markets are closed today.
Spreadsheet accompanying this report: link.
As there is nothing else of interest today, I'll wrap up the report there. See you later when I publish The Week Ahead!
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Future (LON:FUTR) (£741m) | £300m 5-year unsecured bond, 6.75% coupon. BB+/Ba2 ratings (junk). Also refinances its £300m RCF. | AMBER/GREEN (Graham) I like to see a business graduating from RCFs and other banking facilities to the bond markets, where debt is typically longer-term and less restrictive in terms of covenants. So this is good news. And I don’t think it will make any difference to the total debt being used by the company: as of the interim results it already had total facilities of £650m, of which it was only using £300m. Their leverage multiple was 1.1x which would not ordinarily be considered very dangerous. However, trading is under some pressure with organic revenues currently declining. See Megan’s coverage of the May profit warning here. On balance, this still looks quite interesting to me at the current valuation, albeit not without risk. The company's credit ratings are sub-investment grade. | |
MJ GLEESON (LON:GLE) (£227m) | FY25 PBT within market exps (£21-22.5m). FY26 to be at lower end of current exps (c. £24.5m). | BLACK (AMBER/RED) (Graham) Offers deep value vs. balance sheet strength but with earnings expectations in a downtrend, I have to stay AMBER/RED for now. Changes to the management structures appear to make sense, shortening reporting lines and giving the regional CEOs more control. | |
Avation (LON:AVAP) (£104m) | 10 aircraft to be delivered by Q2 2028. Actively considering ways to refinance $310m Notes due 2026. | AMBER/GREEN (Graham) [no section below] I’m happy to leave the AMBER/GREEN here but I note the company has $310m of Notes expiring in 15 months, along with a B2 issuer rating from Moody’s, i.e. in a bond context, Avation is considered “speculative and a high credit risk”. They’ll need to address this refinancing in a timely manner or it could have negative consequences for shareholders, e.g. being forced to accept a takeover bid at an inferior price. | |
Roadside Real Estate (LON:ROAD) (£71m) | Acquires former Sainsbury’s Petrol Filling Station from joint venture, for £1.25m. | ||
Huddled (LON:HUD) (£11m) | Deal with Ingenuity removes capacity constraints. Accepts £1.5m of new equity at 3.2p. |
Graham's Section
MJ GLEESON (LON:GLE)
Down 5% to 370p (£216m) - Trading Statement - Graham - AMBER/RED
Unfortunately this update includes a small downgrade to expectations for FY26.
It comes after a more serious profit warning in June, when Roland wisely downgraded our stance on it to AMBER/RED.
FY June 25: adjusted PBT will be in line with market expectations (£21 - 22.5m).
Gleeson Homes: 1,793 home sales completed (FY24: 1,772 homes).
It sounds reasonably busy, although I do note the drop in build sites (more on this later).
Net reservation rates have “improved significantly” to 0.64 per site per week (H2 last year: 0.50), excluding multi-units.
Forward order book of 845 plots (June 2024: 559 plots).
68 build sites (June 2024: 79 sites)
However, as flagged by Roland last month, the sale of some “extensive land holdings” in East Yorkshire didn’t happen. Gleeson are reviewing their options in relation to this.
Reorganisation: this division is losing its CEO and being reorganised under a “Central division” and “Northern division”. The leaders of these divisions will now report to the CEO of MJ Gleeson, not to a CEO of Gleeson Homes.
The outgoing CEO of the division is not thanked for his efforts after six years with the company:
The strengthened management structure is expected to lead to a marked improvement in performance and delivery, improving pace and quality of build and management and control of costs.
Later, the CEO of the group says “commercial delivery was not where we needed it to be”.
Gleeson Land: 7 disposals happened in FY25. 3 further disposals which had been anticipated, are now expected in H1 FY26. The FY25 operating profit result will therefore be at the lower end of expectations (£7 - 8.4m).
Net debt was £0.8m at year end (previous year: net cash £12.9m), “due to timing issues”. At least we can assume this means there wasn’t any window-dressing!
Outlook:
The housing market lacks confidence and remains subdued and the Board does not see a short-term catalyst for any substantial improvement.
However, as reflected in our robust sales rate, there are customers for well-located homes at the right price….
Continuing capacity issues in the planning system have delayed site openings and Gleeson Homes will operate from fewer sites than anticipated in the current year. However, our strong pipeline and improvements in our own process give us confidence in our ambitious growth plans.
Gleeson Land's performance in FY2026 is expected to be similar to FY2025 with delivery weighted to the latter part of the year...
Taking these factors into account, the Board expects that profit before tax and exceptional items for FY2026 will be at or around £24.5m, the lower end of current market expectations.
Graham’s view
I got this wrong back in February, taking a positive stance (at 498p/£291m), noting that the company had (fully tangible) balance sheet net assets of £297m.
After the recent profit warnings, it is now trading at a discount to this net asset figure:
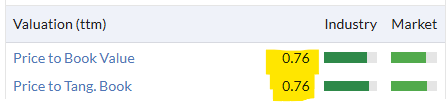
Which means that it’s showing up on Ben Graham deep value checklists:
The problem, of course, is that the market also cares about earnings.
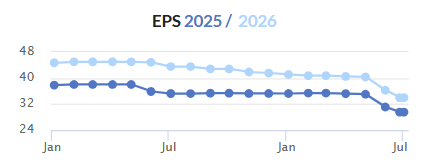
Back in June, Singer cut their FY26 adjusted PBT forecast by 20%, to £26.3m.
The latest estimate from Gleeson itself is that the actual figure might be c. £24.5m, i.e. 7% lower than Singer’s June estimate.
So I can’t argue with the share price fall today.
And I am going to have to stay negative on the stock, as we find that in the short-term, profit warnings tend to be followed by more profit warnings - and this is now the second warning in a row from Gleeson.
Looking out long-term - say three years from now - I’m more optimistic. In my experience, housebuilders trading at a discount to tangible book have limited downside risk (assuming that they are solvent, of course!).
I also think the decisive actions today re: management are promising. The CEO of MJ Gleeson will now have to be more hands-on at Gleeson Homes, as Gleeson Homes will no longer have its own CEO. And the two regional CEOs will have more control over their own regions. Surely these must be positive developments?
So I think over a 3-5 year timeframe, for people who want to own a housebuilder stock, Gleeson holds promise. But in the short-term, I do have to stay AMBER/RED on it, due to the risk of another profit warning.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

41 comments
Does anyone know why the weekly podcasts by Paul Scott and Paul Hill have disappeared from Vox markets? Some falling out no doubt, but a pity because they often contained the odd useful snippet or two.
They haven't disappeared. They are in Videos/Small Cap Investing. There wasn't one this week as Paul Hill is on his hols in Wales.
Thanks, Peter. Good to hear.
Avation (LON:AVAP) (I hold)I am not sure the maturing debt is a significant issue. The company has been paying back bond holders so I assume that they are confident of re-financing. As to accepting a low bid if they fail, given the shortage of aircraft worldwide I think unlikely. NAV per share were £2.71 in the last full year accouns.
Latest note from Zeus says AVAP trades at a 40% discount to NAV but with market values for aircraft trading at a premium the discount to market value is likely to be bigger than this would suggest
"The answer is diversifying into the five assets, shares, bonds, property, gold and Cash"
Sounds sensible, but gold is just a form of cash that holds its value (cash reliably loses 90% of its value versus gold every 25 years). And crypto is surely an established asset class now.
Any portfolio that had 8% gold and 2% crypto allocation 5-10 years ago will have outperformed any portfolio that didn't.
On 30th July at 6pm, Yellowstone Advisory and Killik & Co will host a private investor evening in aid of Prostate Cancer Research.
Management from AFC Energy (LON:AFC), Killik & Co Special Situations Fund, JOHCM UK Equity Income Fund, Kenmare Resources (LON:KMR), Polar Capital Global Financials Fund, Sankofa Global Investments, Sulnox (OFEX:SNOX) and Oxford Biodynamics (LON:OBD) will all be presenting and there will be plenty of time to ask questions and network with other private investors.
If you'd like to attend you can register here:
https://www.yellowstoneadvisory.com/event-details/summer-private-investor-evening-hosted-by-yellowstone-advisory-and-killik-and-co
Here's the link to make a donation to Prostate Cancer Research.
https://www.justgiving.com/page/alex-schlich-4?utm_medium=FR&utm_source=EM&utm_campaign=015
Vodafone
Having spent two decades in the doldrums, Vodafone is showing signs of life again.
At 80 it’s high for the year, has good rankings and a favourite of some of Stocko team and the community.
Vodafone (LON:VOD) I agree. Bowl forming after long plateau. I've been uninterested for years but my nose is just sniffing the air now....!
Problem is over-Regulation in all it's core markets, in favour of consumer not companies. Leading to very competitive marketplaces.
Deflationary pricing. The price per GB of data keeps dropping every year. Squeezing rev per customer. So to grow Gross Profits, you need to grow your base size. Hard in a mature environment - everyone already has a phone plan.
Meanwhile the offering is commoditised. At some point in the next 3 years, every sim plan will be Unlimited data. Then what's the differentiator?
Size does matter - scale leads to efficiencies. Vodafone (LON:VOD) is in this camp.
IoT was meant to be the saviour. Every connected device needs a sim card, a data plan. But hasn't really been transformational yet.
Maybe Vodafone is showing signs of life again because it has successfully merged with Three Mobile. Vodafone reckon this will lead to synergies of around £700 million per annum.
www.vodafone.co.uk%2Fnewscentr..." class="redactor-autoparser-object">https://www.google.com/url?sa=...
David.
I definitely buy the synergies story. I used to work at Vodafone, this was 5+ years back. And with my knowledge of how it is structured, how it works, and where potential value lies, I think they will get loads of synergies out of the combined group.
But gains from synergies are a one-off (albeit taking several years, and not completely risk free either). And probably already fully priced in as it is one of the key benefits trumpeted about the merger, as you pointed out.
What I'm more interested in is what is not currently priced in... that's where share price gains and market outperformance are to be had.
BT (LON:BT.A) are also showing signs of life, their shares have done even better than Vodafone (LON:VOD) this year.
Agreed, but interesting to note several director purchases the day before the close period on June 25th 2025.
Kinda looks like "forced" buying as part of their contract? Same thing happened last year.
Just like to record a big thanks to Ed and the team. I've always felt that the way Stockopedia is set up suits my investing style; with the Stockranks interpreting a lot of the data for us. For me there has been a huge improvement in output over the last two years mainly linked to the investing education and the articles provided by the team. My one complaint is that despite how much my own performance has improved (which it notably has), I'm still not beating the NAPS!
Thanks
Ted
Before I joined Stockopedia, I was with VectorVest until they withdrew from the UK. I had good market beating returns using my own customised metrics. I could graph foreward eps and net profit margin along with other of their metrics and ci to constantly get good results. Stocko gives me a lot of info but I am not making the returns I used to
Then you have bought the wrong companies. A good workman never blames his tools
Hi Descartes your post sounds like the reason for your drop in performance is down to changing to the stocko tools ? But they only offer facts and the same data you’ll get on other platforms ( well most of the time) is that what you meant?
It can take some time to adjust to a different system. Give it more time.
I started investing circa 2001. Learned a lot from Chris Dillow who wrote in Investors Chronicle, IC. Cancelled my sub when he retired a few years ago because i wasn't learning anything useful from the writers that remained.
I feel the articles in Stocko are much better than IC. And of course we get the data crunching, which is why i joined in the first place.
I don't always agree with what is written here, although this is probably what gets me thinking the most. I have a PhD in investing, but find that i learn new things each week. It is a fascinating (and profitable) area to study.
I started investing in 1982 Epitychia, became over confident of my amateur skills and let my stockbroker friend talk me into option trading using leverage. Wipe out happened in the two days of the October 1987 crash when I thought I could juggle positions fast enough to cope -- I couldn't, basically Put Option writers were stuffed. I started gingerly investing again in 1993 gratefully using the capital losses from the 87 wipe out. Two big crashes and numerous other sell-offs later here we are again. I read the FT online every morning, stopped reading the Investor's Chronicle years ago as Stockopedia offers so much more. Like you I learn every day but I bow to your PhD , I might just scrape an O Level.
Its interesting that i learnt the most from my mistakes and disasters.
Do other investors believe it is possible to get good without disasters along the way?
Having read about other investors, i suspect disasters are unavoidable. The key is not to get entirely wiped out.
Paul Scott (late of this parish) was refeshingly honest about his mistakes.
The secret to success? It's plain and simple to express: err and err and err again but less and less and less.
It's been a long journey for me, and others have gotten there much sooner and with greater style. I think I've been held back by Ben Graham and Intelligent Investor.
I don't think Buffett is an especially good guide, either. The whole thing about a punchcard with 20 tickets is a bad idea, as is being overly concentrated.
Peter Lynch said it better: if you can get 6 right out of 10 you will be considered excellent.
Successful investing is about predicting the future, which we just don't know.
I feel that sites like Stockopedia are important because quantitative statistics are often very hard to beat.
Investing is simple. But difficult.
A 60% success rate is stellar. Most of the other 40% are just random things that were unforeseeable anyway. But hiding in there are also a few clues on how to improve.
But you also need the mental discipline to implement them. Which is not easy.
I really enjoy reading about people's investing journeys, and this was no exception. I would love it if stockopedia did some interviews with some of their subscribers and dug into some people's investing history and lessons.
It would have been interesting to watch the market reaction to Trump's BBTB, imo it lacks two B's Boom then Bust, you might want another B too for Bitcoin! Sorry to digress from why we're on here but what happens there will affect us all.
Today's 4th of July US close will delay US market response to BBTB until Monday may be conflated with 9th of July end tariff suspension and whatever Trump posts over the weekend.
I initiated the transfer of a pension into my SIPP this week, on the basis that I have crystallised the current value and don't mind being out of the market in a week of such uncertainty.
I do not know what other people are doing but I have never held so much cash as I am sitting on right now. I know people say run with the winners but so much has doubled so quickly in the last couple of months, and the economic news seems so dire, that I am happy to bank profits.
Maybe it is an age thing, I am sixty plus, but holding nearly 50% in cash means I am going to sleep a lot better, even with the hot nights!
Buffett said, ' You get one or two really good investment opportunities every 5 years or so and spend the rest of the time worrying if you'll ever get a good opportunity again'
Patience is key and yes, run the winners until the facts change.
I’m sticking to my long term asset allocation and rebalancing strategy. Doing the right thing can be hard at times like this and I find sticking to rules, set when I wasn’t influenced by the news, makes it much easier. That’s true for my overall AA mix and individual shares. I’m actually more confident in equities at the moment due there being so much bad news and uncertainty about as most sustained crashes I’ve experienced have been when the news flow was very positive.
Taking profit and sitting on cash doesn’t necessarily make you sleep better at night!
The worries about when to re-enter the market , fear of missing sharp bounces and the goof shares running away while you wait may make you more nervous.
The answer is diversifying into the five assets, shares, bonds, property, gold and Cash.
Yadi
To help you sleep I’d add a sixth asset, (bonded) whisky.
PS if you are a gent and prone to falling out of bed add Viagra 8-) ……….. exit, stage left.
Same, 50% cash also. Reckon a pullback coming
Ditto Tiswas.
All the bargain or shall I say value stocks seem to have flown since Trump's tariff tirade and stocks with good results get heavily marked down.
Happy to wait for the next black swan
I'm 38% cash. Agreed that it's frustrating. Markets in the US are end of cycle, not start of cycle in my view so will maintain caution. Patience is critical. Markets have a way of drawing you in at the worst possible time!
Hi Topvest always look for your macro posts, I don't disagree with you but theres also a train of thought that Trump wants dollar down which should be good for stocks.
The US has to get someone to buy the $9 trillion roll over and there's talk of QE and yield curve control again would also be good for stocks.
I think Trump will be terrible for the US longer term but given his love of debt and low interest rates, I do wonder if we might see a less extreme version of a 2021 crack up boom over the next 12 months and then an inflationary repeat of 2022 maybe in a year to 18 months time ?
The Phoenix - you could be right. I'm taking the view that I will start deploying meaningful cash when the S&P500 drops by 30% and not before. In the meantime its earning 3-4% and my invested portion is doing OK. Timing the market is certainly impossible short-term and very difficult long-term. It worked for me in 2008, but this time has been much much more difficult!
Interesting comment. You could also argue that April 2025 was the ‘shake out’ prior to a further leg up (which we are yet to see).
Personally I am fully invested, having entered on the previous dip and I also added some further positions last week (Teleperformance, Crox and Elixir).
See below. Not sure how accurate this website is but I take a look every now and then. I think we’re in for a good summer, fingers crossed.
https://30rates.com/sp500
I agree, although it might take a while for the bust to arrive, and it would be interesting to examine which UK companies might benefit from any boom resulting from the investment and tax breaks present in the OBBBA.
I asked ChatGPT to look at the impact of OBBBA on Concurrent Technologies (LON:CNC) (I hold) by way of example...
How This Could Affect Concurrent PLC
Concurrent PLC operates primarily in aerospace, defence, telecoms, and industrial embedded systems, with a client base in both the U.S. and UK, including defence agencies, telecom operators, and high-reliability industrial customers. Here's how OBBBA may shape the environment it operates within:
1. U.S. Defence Spending Boost
2. R&D Incentives & Tax Depreciation
3. Industrial and Telecom Modernisation
4. Budget Trade-offs—Entitlement Cuts vs. Defence Rises
5. Clean-Energy Slowdown