Daily Stock Market Report (Fri 4th September 2026) - VCP, TTG

Good morning and welcome to Friday’s report! The main overnight news item I can see is Volkswagen’s plan to cut another 50,000 jobs, so that it now officially expects to cut 100,000 jobs by 2030. Its existing workforce is in the region of 660,000.
I don’t know about you, but I’ve noticed a huge increase in the number of BYD cars on the road. This Chinese expansion is coming directly at the expense of VW and also to some extent Tesla, given the superficial similarities between BYD and Tesla models.
On a related point, as I’m sure you’re aware, the UK government is planning to completely ban the sale of new petrol or diesel cars in just a few short years - although I must admit that I do expect the goalposts to be moved again. Under pressure from the likes of VW, the EU has moved the goalposts significantly, and now merely has a 2035 target for a 90% reduction in carbon emissions. That gives a little breathing room for the traditional manufacturers - but it may not be enough to save them from Chinese competition.
Overnight market movements:
The FTSE is unchanged at 10,830
S&P 500 is up 0.1% at 7,755
Brent crude (November) is up 0.1% at $95.65/bbl
Gold is down 0.1% at $4,470/oz
Bitcoin is down 0.7% at $80,950
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Arrow Exploration (LON:AXL) (£89m | SR93) | Current total corporate production is over 6,000 boe/d. Estimated cash balance is US$21.8m. "Although the IC-6 well was terminated sooner than expected due to encountering a fault, we were able to quickly pivot and complete the well as a water injector in a cost effective manner which will significantly help water handling and production efficiency at Icaco.” | ||
Cora Gold (LON:CORA) (£73m | SR22) | No revenues. $1.1m pre-tax loss. “This has been a truly transformational period for Cora as Sanankoro (Mali) has transitioned from an advanced development asset into a fully funded gold project approaching construction.” | ||
Victoria (LON:VCP) (£67m | SR67) | EBITDA improvement initiatives to enable stronger performance in FY28 “broadly in line with expectations”. Will assess any opportunities that may arise as a result of Headlam appointing administrators. Good progress on the refinancing of the 2028 bonds and preferred equity: on track for completion in calendar Q4. | RED= (Graham) I’m obviously staying RED on this one, due to its horrific balance sheet. | |
Fiinu (LON:BANK) (£15m | SR1) | Fiinu and Conister Bank have agreed an addendum to their existing agreement governing Fiinu's Plugin Overdraft® platform, which Fiinu believes to be the world's first unbundled overdraft solution. It formalises the updated implementation arrangements. |
Backlog
TT electronics (LON:TTG)
Up 11% on Wednesday, now at 153.5p (£274m) - Graham - AMBER/GREEN ↑
Let’s catch up on this story from Wednesday: an ahead of expectations update from TTG, at its interim results.
Materially improved profitability, margin expansion and stronger commercial momentum, reflecting actions taken during 2025, improved execution, and the delivery of strategic priorities in H1 2026.
TTG makes a wide variety of components: sensors, coils, convertors, etc.
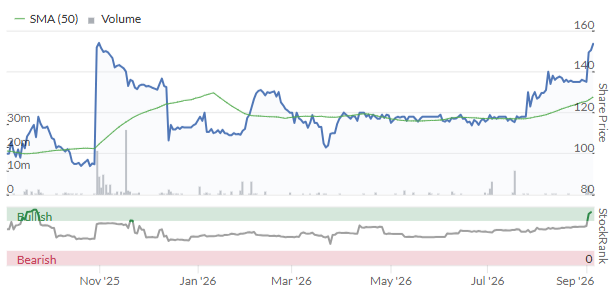
Earlier this year, shareholders rejected a takeover offer at 150p. That decision has been rewarded with the share price now exceeding that level. It’s an unusual price chart:
Some highlights from Wednesday's interim results:
Revenue down 2.7% organically to £228.1m.
Adjusted operating profit +37% to £18.5m
Adjusted PBT +86% to £15.8m
The statutory profit numbers don’t quite match up to the adjusted ones: actual operating profit is only £9.7m, while actual PBT is only £7m. They are at least much improved from H1 last year.
Net debt has also improved year-on-year from £73m to £52m, but most of that movement was achieved last year. Net debt had already fallen to £50m by December 2025.
The big news is the marked increase in profitability, which is the fruit of various decisions:
Changed to a new, “product-led” organisational structure
Sales “transformation” with “strengthened commercial discipline and pipeline management”
A cost reduction programme which is ongoing. Annualised run-rate savings expected to be over £6m when it’s finished.
I’m not close enough to the company to understand in granular detail what they’ve done, but it all sounds very positive.
They are also “evaluating a potential divestment” of their Components division, receiving “encouraging indications of interest”. This is the smallest of the three divisions:
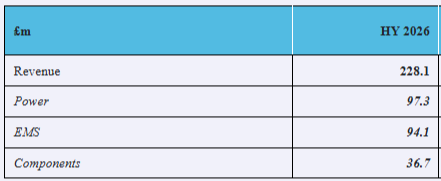
(EMS = Electronics manufacturing services)
I always love a well-planned divestment - it typically simplifies a complex business, frees up management attention and focus, and leads to a higher valuation as investors are better able to understand what they are buying. It also produces a cash injection, assuming that the business being sold is worth something! Let’s hope TTG can achieve all of that here.
Outlook
We enter the second half of FY2026 with improving momentum and increasing pace and effectiveness in execution across the Group. Demand in Aerospace & Defence continues to provide a strong foundation for the Group, supported by increasing defence investment and a healthy pipeline of programme opportunities….
Reflecting this momentum, together with the benefits of our cost reduction programme, the Board now expects adjusted operating profit for FY2026 to be ahead of current market expectations. b in the second half, with full-year cash conversion expected to be in the range of 70-80%, supporting further deleveraging.
The company helpfully informed us that they considered the consensus adjusted operating profit forecast to be £35.0m, with the highest forecast being £38.5m. So perhaps they are headed for £39-40m?
Cash conversion in H1 was pretty poor, with zero free cash flow and a “cash conversion” ratio of only 42%. So it’s also great news to hear that they are expecting a full-year ratio of up to 80%. It’s natural for this to oscillate, so I’m not worrying too much about the weak H1 cash performance.
CEO comment:
“The first half demonstrates that the actions we took in 2025 are starting to deliver tangible results. With the business now on a stronger operational footing, our focus has moved firmly to execution and delivery…
TT is a stronger and more resilient business than it was twelve months ago. We have a clear strategy, a refreshed leadership team and a solid platform from which to deliver sustainable growth and create long-term value for our shareholders
Graham’s view
This was a company in need of a turnaround:
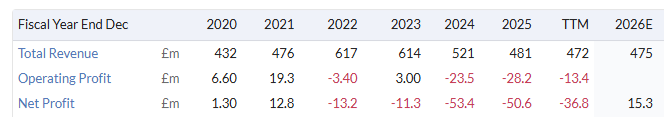
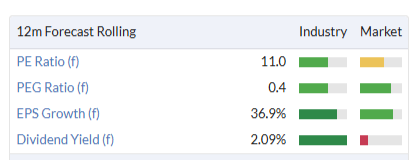
Fortunately, the turnaround appears to be working under new CEO Eric Lakin, and I must admit that I find it interesting at this valuation:
I will tentatively put us on AMBER/GREEN here. I don’t have massive conviction in the underlying quality of the business, but there are reasons for optimism in the short-term across its divisions:
The large Power division has a 114% book-to-bill revenue (i.e. orders coming in faster than they are being fulfilled)
At the EMS division, TTG expects organic revenue to return to growth in H2.
The Components division is potentially up for sale.
So I think there are enough reasons to be cheerful, and the valuation is still reasonable enough, that I can afford to be moderately positive here.
Graham's Section
Victoria (LON:VCP)
Down 5% at 55p (£64m) - AGM Statement - Graham - RED =
Let’s check out the latest from this stricken carpet group.
Full-year results for FY March 2026 showed net debt of £1,063 million, including leases of £189m. So let’s call it £875m, excluding leases.
EBITDA for the year was just £92m, and underlying operating profit was only £7m. So this is truly distressed.
Today’s AGM statement outlines various initiatives to boost EBITDA: “Each project will increase efficiency and output over the remainder of the year, which will enable stronger performance in FY28 broadly in line with expectations.”
We are only five months into the current financial year, but it sounds like we perhaps can’t hope for much, given the above reference to FY28 rather than FY27!
The phrase “broadly in line” also tends to agitate rather than reassure.
On Tuesday,Headlam (LON:HEAD) announced that it was appointing corporate undertakers: Victoria will “assess any opportunities that may consequently arise” following the demise of one its major UK competitors.
In passing, I’d like to point out that Headlam is about half the size of Victoria (Headlam generated £500m in 2025, while Victoria generated £1,046m in FY March 2026). And yet Headlam collapsed under net debt of just £40m: a tiny fraction of Victoria’s debt load.
Anyway, let’s continue with this AGM statement:
Across our other geographies, the broader operating environment for the industry remains volatile. The Board is continuing to monitor energy, diesel and input prices, which have risen further since the full year results were announced on 24 July, and further actions are being taken to mitigate the impact of the increases.
Good progress continues to be made on the refinancing of the Company's 2028 bonds and preferred equity and this remains on track for completion in calendar Q4. Documentation is expected to be finalised and posted in mid-September, at which time the Board will provide an update on current trading.
The refinancing of the 2028 bonds is excellent news, but I don’t think it matters if the company’s financial performance remains poor: any hope for the equity requires an enormous improvement on that front.
Graham’s view
I’m obviously staying RED on this one, due to its horrific balance sheet. But before closing this piece, let’s take a look at what’s involved here.
Net debt as of March 2026 looked like this:
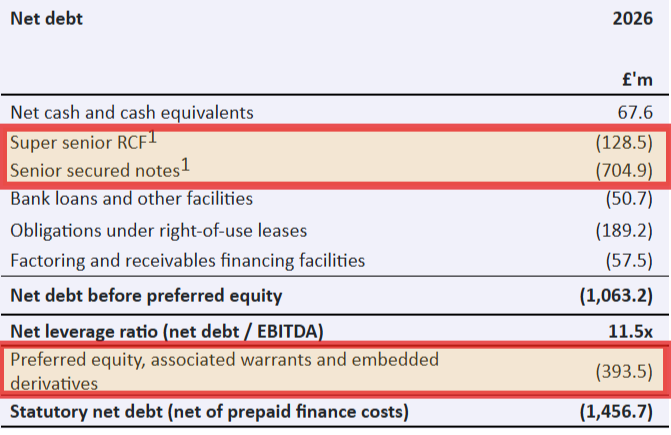
There has been lots of refinancing news since then:
c. €167m of senior secured notes due 2028 have agreed to instead accept €125m of notes due 2031, plus 35 million new ordinary shares.
Koch Equity Development (the investment arm of the huge private US company) also agreed to give up their £380m of preferred shares and instead accept £50m of amended preferred shares, 33 million new ordinary shares, €20 million new notes due 2031, and a “contingent value right” worth £34m.
Over £500m of liabilities have therefore been delayed or converted into new equity. The current share count is 116 million. Another 68 million would be printed by the transactions outlined above.
I’ve been positively surprised by the company’s ability to survive to this point. But I still think there’s a huge chance that the existing equity ends up having a negligible value.
Note that the SSNs who agreed to refinance have mostly converted their holdings into new debt, not into equity. They understand the risk.
The preferred shareholders are much lower down the pecking order, and even they limited the amount of equity they were willing to accept in exchange for their preferred shares.
It’s been a difficult journey for investors here, but Victoria will serve as a lasting monument to financial folly. It turns out that carpets, underlay and tiles could not be turned into a glamorous investment opportunity, even after being mixed with high-powered financial engineering and enormous leverage.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

17 comments
I mentioned here on August 11th that Thruvision (LON:THRU) was making some astonishing leaps even though it remained a very small market cap of under £10mm. Amazingly it has gone up 34% today, raising its status in my portfolio from interesting “punt” to serious investment. This sort of movement usually ends badly but I am hoping this is the exception of a company’s value starting to get wider recognition. Does anyone have an iSight that would support my view ( or pop my bubble)?
https://www.optimocapital.co.u...
also baron investment has a small position, but that is large for most of us:
https://x.com/baroninvestment/...
Thanks for that link stegga…
I’m in your boat exactly sir and my thoughts are the same. Am up 100% in a couple of weeks on a small investment and minded to top slice on Monday as the IC printed edition hits the mats today which may create some demand. That way I have a free ride on an ‘interesting punt’ as you rightly put it.
The company seems to have hit on a selling technique, but doesn’t have a great history of turning sales into profit. This time might be different of course (have heard that before somewhere)
Brunner Investment Trust (LON:BUT) managers o why you should view AI data centres as a commodity.
What can past investment cycles teach us about the AI boom?
Elixirr International (LON:ELIX) down, down, deeper and down!
A real mystery isn’t it, from the outside it looks perfect but the price action is awful
Any clues to what is going on? They appointed a joint broker in early August and it's just gone downnnnnn since.
RE: Elixirr International (LON:ELIX)
Any clues to what is going on? They appointed a joint broker in early August and it's just gone downnnnnn since.
Sometimes this just happens: there are plenty of other UK companies that have been taken out cheaply, Elixirr just looks like another where there's not a lot of liquidity.
If we want an explanation for the inexplicable then possibly there are concerns over future growth - a lot of their expansion has been fueled by acquisitions. On the other hand you have a company with record FY25 results and H1 26 revenue growth of 25% with very clear owner engagement.
All told this looks like an opportunity for a top-up rather than a reason to sell. Although so much is going cheap at the moment that buying a company with less than stellar momentum behind it might be considered an opportunity cost ...
timarr
I have held Elixirr International (LON:ELIX) for a while and it doesn't seemed loved by the market! Results are good, albeit aided with acquisitions and perhaps one concern is how much growth is organic? Also i think the AI "question" hangs over this consultancy, although the company are at pains to explain how they are using AI to their and their clients advantage. I see Interims are 21/9, so we don't have to wait long to get more detail and also weigh up the outlook. I remain positive.
£ELIXR
i have had a quick look - it looks a fairly interesting company for sure - i cant see any nasties here. It seems like they have kinda delivered as promised with 2 eps upgrades for this year and next in the last 12 months. so its slightly odd that the price woudl be trending down.
the trading update as recently as 3rd August seemed fine and Dandy - so one would like to think that their should really be anything to worry about ref us not being up with events.
onto the reasons why its doing so bad.
well shareprice is trending down and has been since April - thats not really a great advert for people buying in if they may be wiating for an uptick from a charting perspective.
It looks like nearly one million new shares have ben issued and there was a secondary placing with £12 mill of shares - i would always be worried that with secondary placing that the buying party might just be in it for a quick buck - or may not hang around if things go south.
Its an acquisition lead business that issues shares to buy others out - well to me thats kinda gonna leave sketchy sharebase of people who have mostly cashed in their chips previously and may only hanging around until then dust settles.
I am not a great fan of consultancy people companies - i do quite like here though that they seem to be big into using AI at the heart of their consultancy operations - so i am guesing they are more new school than old school.
Looking at the jobs available on their website they certainly seem to be looking for people to "deliver" and deliver quickly and they are happy to namecheck Palentir and OpenAI ref how roles are modelled.
We’ve deliberately modelled this role on how the category is defined in the market — pioneered at Palantir and scaled by firms like OpenAI. An FDE is a hybrid of technical lead, consultant and product manager: someone who writes production-quality code, but is just as comfortable sitting with users, understanding how decisions actually get made, and stress-testing a prototype in the field. Business acumen is not a bonus here — it is core to the job
Lets have a look at the other place to see if there are any consipracy theories there are moans there that after the latest trading update forecasts were actually reduced when cannacord initiated coverage - it seems factual that the numbers wre dropped - that may have been earlier broker forecast though not having factored in fx changes.so some think its slightly shady company withn acquisitions being necessary to keep everything moving forward.
overall it does kinda look cheap whilst the news is good
I’ve always been wary of side projects
Elixirr International (LON:ELIX)
cheers rhomboid1 - i do agree with you with your comments - being frank as soon as you hoc out a measurable % of your shares in any manner you are liklyl to be potentially compromised if things go south quickly - not sure if its still ok but being frank anyone who is officer of company perhaps shouldnt be able to use shares as colateral in such manner - perhaps with limited exceptions that are fully disclosed (eg divorce - temporary finanical woes etc).
Re Headlam (LON:HEAD) going into administration and mentioned by Victoria (LON:VCP)
Headlam is a great example of how a rock solid business with a super simple business model - buy low due to scale, sell on due to reach - can be trashed in a few short years. From clear market leader with a claimed x6 greater market share than the next competitor it has let itself go through failing to secure its customer base when senior management left to set up a rival, through a loss of focus by rolling out retail trade shops and by being seduced by big chain outlets. The maxim about needing a business so strong it could survive being run by idiots has never been more true. I still find it hard to fathom that with stocks and property asset it held it could not find a way out unless the balance sheet of a few years ago were mis-stated something.
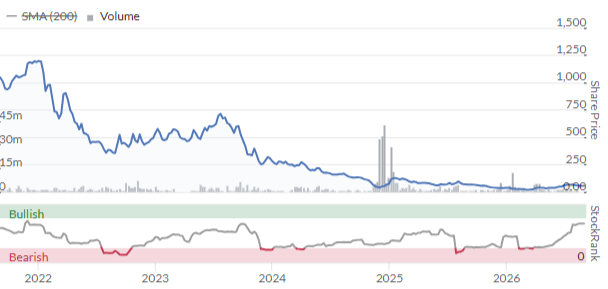
That Victoria (LON:VCP) is now hoping to find morsels to eat - itself having from from near 1200p to 55p after a financial engineering bubble - tells a story
Victoria (LON:VCP) Too much of a turnaround for me, but at least the directors are buying
American Labor Day Mon 07 Sep so NYSE closed
And the VIX Volatility Index is down at 14!
Rock on St Leger day!