Daily Stock Market Report (Fri 5th December 2025) - OCDO, TRST, HLMA, JHD, RGG, GDR, MEGP

Happy Friday!
Internet/Cloudflare crash: I haven't noticed any issues with Stockopedia or other websites I rely on today, but many popular sites are reportedly struggling including LinkedIn, Deliveroo, Canva and Spotify. This is getting more common - and a reminder of how reliant we are on so much infrastructure that we don't normally even think about!
In other news, Trustpilot (LON:TRST) issued a response to Grizzly Research yesterday, but it didn't help their share price:
The Report presents a series of claims that are selective, misleading and framed to support a predetermined narrative. It omits key context and publicly available facts, creating a false impression and exhibits a lack of understanding of how Trustpilot works. Trust is our guiding principle and is central to everything we do.
After they said this, their stock continued to fall, and they closed the day near the lows.
This morning, however, after everyone has had a chance to calm down, there has been a recovery of about 9%.
I do think the company needed to say something, even if they didn't say much. When a share price has collapsed that much in a single day, it's important to say to shareholders what their view is.
And by the way, I'm aware that I have an unpopular opinion on this one. But I also appreciate the civility of a debate that could easily turn nasty. There's nothing wrong with a frank exchange of views, and I don't mind being told that I'm wrong about something!
All done for today and for the week, have a great weekend!
Today's Agenda is complete. Spreadsheet accompanying this report: link (last updated to: 10th November).
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our View (Author) |
|---|---|---|---|
Unilever (LON:ULVR) (£109bn | SR52) | The demerger of the ice cream business known as The Magnum Ice Cream Company will complete on Saturday 6 December. Dealing of Magnum shares to begin on Monday 8 December. | Roland has covered this in great detail here - check it out! | |
Halma (LON:HLMA) (£13.74bn | SR80) | E2S bought for £230m. It provides notification, initiation and detection devices used in hazardous environments in heavy industries and complex manufacturing. 2025 forecast revenues c. £44m. | AMBER/GREEN = (Graham) [no section below] I'd like to find any excuse to switch to neutral on this stock, given that it's trading at 31x earnings and has a ValueRank of only 7. However, the uptrend remains firmly intact, with a MomentumRank is 99! Therefore I'm going to leave AMBER/GREEN in place for now, as the stock continues to reach new all-time highs. Today's announced acquisition sounds promising as usual but the value is less than 2% of Halma's market cap, so unlikely to make a very great difference to the investment case. Of more significance were the recent interim results, in which the company guided for mid-teens percentage organic constant currency growth this year - impressive for a diversified group of this scale. With that growth motor underneath it and with an impressive return on capital of 16.2% (as calculated by the company itself but not far off Stockopedia's calculation), I can remain moderately optimistic on this stock with a clean conscience, even if I do think it's fully valued | |
Ocado (LON:OCDO) (£1.55bn | SR13) | One-off payment of $350m to compensate Ocado following Kroger's recent decisions to close three fulfilment centres in January 2026, as well as a decision not to proceed with Charlotte (NC), one of two planned CFCs due to go-live in 2026. Closure of three live sites will reduce Ocado’s fee revenue in FY26 by c. $50m. | AMBER/RED (Graham) I think it makes sense to maintain scepticism on this "Sucker Stock" given the lack of any decent financial track record and the (at least partial) failure of its plans to expand in the United States, with Kroger being so desperate to close three CFCs that it is willing to pay Ocado $350m to do so. | |
| ME International (LON:MEGP) (£615m | SR62) | Termination of Offer Period | Board of Directors confirms that it has not received an offer that it believes would be in the best interests of all the Company's shareholders, and therefore discussions have been terminated. FY October 2025 trading update: revenue £311-318m, PBT £76-79m (in line with expectations set in November.). | AMBER/GREEN ↑ (Graham) [no section below] I previously promised that I would upgrade this if we had an in-line update, and so I'm happy to do that today. The stock is trading at just 10x earnings after it continued to fall following the November profit warning. The major news today however is not the trading update, but the news that the company is abandoning its efforts to find a buyer. I did view those efforts as being primarily about succession and legacy planning for the CEO, who continues to own 36.5% of the company. With no satisfactory buyer having appeared, the company will have to continue on in its current form - which I think most small shareholders will be reasonably happy with. |
James Halstead (LON:JHD) (£599m | SR65) | Revenues within the UK and North American markets have remained robust, but the challenges faced within the Central European and Asia Pacific regions have continued. | GREEN = (Graham) [no section below] We tend to give this one the benefit of the doubt, seeing as it's a "proprietorial" (using Lord Lee's terminology - family-owned) business. As pointed out in today's statement, the dividend (not including specials) has been increased for 49 consecutive years. It feels almost obligatory to be positive on a stock with this sort of track record, even if it's in the floor coverings sector! Of course it's not all plain sailing, and the Chairman admits as such. Recent full-year results showed small decreases in revenue (down 5%) and PBT (down 2% to £55.1m), but suggested that the company would make progress in FY June 2026. Consensus forecasts also suggest this. So it looks like James Halstead sould have another solid year, despite economic headwinds in various geographies in which it operates (France, Germany, Central Europe, Australia, New Zealand, etc.). | |
LSL Property Services (LON:LSL) (£269m | SR67) | During 2025, franchisees have made 10 lettings book acquisitions, compared with three in 2024, a significant step-up in activity. LSL has provided £3.2m of loans to franchisees in its assisted acquisition programme in 2025. | ||
Jadestone Energy (LON:JSE) (£126m | SR59) | Dr. Adel Chaouch's role as Executive Chairman has been extended, specifically focused on strategic initiatives to unlock and communicate the Company's underlying value. | ||
1Spatial (LON:SPA) (£50m | SR26) | Awarded a contract by Ordnance Survey Ltd to act as prime contractor to deliver the National Underground Asset Register Data Transformation and Ingestion Service. £4.2m contract value. Initial two-year term, option to extend for a further three years. | ||
Skinbiotherapeutics (LON:SBTX) (£43m | SR8) | Revenue of £2.2m (FY24: 1.0m) with EBITDA of £0.5m (FY24: £0.1m) - sales slightly lower than expectations; additional expenditure expected to support improved growth in FY26. The new financial year has started “very positively", 2026 anticipated in line with market expectations. | ||
Iofina (LON:IOF) (£42m | SR78) | Agreement to develop Iofina's next IOsorb® plant in the Permian Basin, a large sedimentary basin between Western Texas and Southeastern New Mexico. | ||
Rentguarantor Holdings (LON:RGG) (£39m | SR11) | Agreement will allow 12 Jones Lang LaSalle offices in London to offer tenants in JLL-managed properties the option of securing a professional guarantor through RentGuarantor. | RED = (Graham) [no section below] This has rebounded strongly since the fundraising in November that crashed its share price, and it's now even higher than the level prior to that fundraise. Important to note that the free float of this stock is tiny: the founder-CEO owns 30%, and Stockopedia's calculations suggest that in total 62% of shares are in the hands of top holders. So volatility is to be expected. The company now has a full-time CFO and today's update regarding a partnership with JLL is to be welcomed, but I remain wary of the valuation, which is more than ten times forecast revenues. | |
Quantum Blockchain Technologies (LON:QBT) (£11m | SR5) | Progress towards the commercialisation of QBT’s Bitcoin software: QBT has entered into three non-disclosure agreements with three separate ASIC manufacturers, each of which has developed its own Bitcoin mining rig. | ||
Genedrive (LON:GDR) (£10m | SR N/A) | Revenue doubles to £1m. Loss after tax reduced to £5.2m (2024: £7.1m). Cash £1.2m. It is evident that additional financing is required in the very near term in order to meet liabilities as they fall due and to continue as a going concern. | RED = (Graham) [no section below] This is an automatic RED given the financial precipice on which it stands. "Cash position at 30 November 2025 of £0.32m relative to an average monthly cash burn of c. £0.35m." That says it all, really. A £1m loan from the largest shareholder is under discussion, but that only keeps the show on the road for a few months. Accumulated losses on the balance sheet are a remarkable £63m. Shareholders prevented management from raising more equity earlier this year, but surely an equity fundraise is inevitable? | |
London BTC (LON:BTC) (£10m | SR1) | The Company is conducting an in-depth review with the aim of growing its mining fleet by around 30% in early 2026 with a move that aims to increase the fleet to around 1,500 ASIC bitcoin miners. Continues work relating to a potential dual listing on Nasdaq. |
Graham's Section
Ocado (LON:OCDO)
Up 9% to 200.7p (£1.69bn) - Update on Kroger Partnership - Graham - AMBER/RED
We don’t talk about Ocado in this report any more - but on a sleepy Friday, I thought I’d give it a mention.
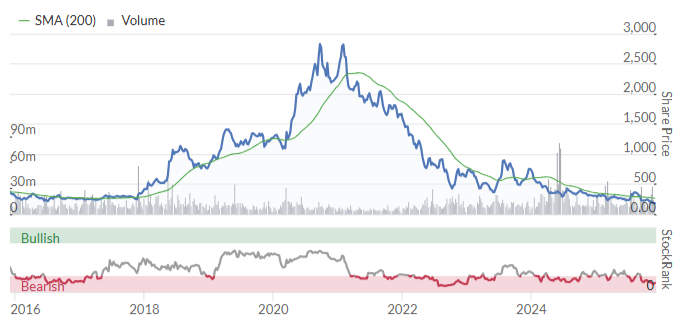
Due to a lack of profits, it has never appealed much to value investors. During the Covid bubble, the market cap peaked at over £20 billion.
With the share price down by over 90% since then, now back at levels last seen in 2013, and with zero dividends paid along the way, it seems that the scepticism was justified:
Looking at it with fresh eyes today, perhaps it could be worth researching at this much lower valuation?
Today’s news relates to the company’s partnership with US retailer Kroger.
Some background on this partnership, courtesy of The Guardian:
Ocado signed a deal to build 20 automated warehouses – known as customer fulfilment centres – for Kroger, the US’s fourth largest retailer, in 2018. Eight of those facilities are currently operating with two more planned for next year. The deal was seen as a major part of Ocado’s plan to sell its online grocery delivery technology internationally.
Ocado offers highly automated, capital-intensive customer fulfilment centres for grocery delivery. Unfortunately, it turns out that the economic viability of this model does not yet match up with the company’s aspirations.
But it’s not all bad news.
When it was announced in November that Kroger was closing three CFCs, Ocado said:
Our expectation is that Ocado will receive compensation for fees related to the early closure of these three sites of more than $250m.
Today we learn:
Ocado and Kroger have agreed a one-off cash payment of $350m to Ocado to be paid during January 2026, principally in lieu of future capacity fees for the impacted CFCs.
So Ocado is being paid 7x the revenues it would have generated from the CFC’s next year, which is presumably a much larger multiple of any profits it might have generated from them.
However, it also says something about how desperate Kroger must have been to escape those CFCs, if it was willing to pay that sort of compensation. The two companies “continue to work closely together” at the remaining five sites.
Looking ahead:
Ocado reaffirms its priority of turning cash flow positive during FY26, driven by continued growth in live and new sites, and underpinned by rigorous cost and capital discipline.
Graham’s view
Ocado has been a somewhat controversial company in the media, with mainstream articles focusing on Tim Steiner’s pay packages.
With companies that are worth >£1 billion, I tend to focus a little less on the integrity of management - although it’s still important. But the objective questions of company financials and business quality tend to be more important at this level.
And unfortunately, Ocado has never delivered when it comes to the financials.
The most recent interim results gave an adjusted PBT of minus £137m.
Within that, Ocado Retail (ocado.com), the joint venture with Marks and Spencer (LON:MKS), had an operating loss of £17m.
I get that it’s a technology company. It could be classified as a “robotics” stock. In that sense, it’s a bet on the future. But after 25 years in business, and with billions of pounds of capital allocated to it, should it not be able to produce some sort of a return?
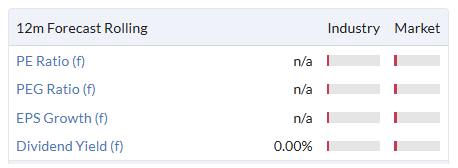
Net debt was over £1 billion as of June, so it’s difficult to make a balance sheet argument for the stock, either. Although having said that, £310m of the debt is leases, and the Kroger compensation payment will be worth about £260m, so true financial net debt should now be much lower than the headline figure from June.
I’d like to turn neutral or positive on this some day, and the >90% collapse in the share price does get me interested. But for now I think it makes sense to maintain scepticism, so I’m AMBER/RED.
They have an ambition to “turn cash flow positive during FY26”, but I wouldn’t read too much into it at this stage. They could technically achieve that ambition by burning cash for 11 months of the financial year, and then generating some cash just before the year ended.
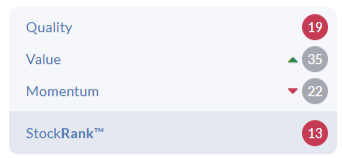
The StockRanks agree, calling it a “Sucker Stock”.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

26 comments
For me Ocado's technology has always been a flawed business model. The Ocado technology does work. Owning super warehouses to supply the end customer doesn't. Why? Because they are nowhere near the end customer. This is why Sainsbury and Tesco supply from local large supermarkets and do not need Ocado's technology.
Good thoughts
Trustpilot (LON:TRST) I think Graham's view is really interesting though. A company that survives and thrives despite being long suspected of having dodgy business practices definitely has quite a moat!! Will be very interesting to see if Grizzly Bear has the muscle to bring it down.
Trustpilot (LON:TRST) I haven't read the report, but I have heard of pay-for-reviews from third parties, and also payments to remove bad reviews.
My verdict: a waste of electrons.
Sorry Mike, I didn't get around to them but thanks for bringing them up! G
Hikma Pharmaceuticals (LON:HIK)
Possibly looking decent value. Its an Ed Naps 25 pick, and sits bottom of the pack at minus 20%. Its currently at a 3 year low, testing a strong support level that has held many times over the last 11 years. Could drop a fair bit more, charting wise, if the support doesn't hold. If support does hold it could be a 40%+ upside as it may rally back up towards 2350ish level.
Historically looking quite cheap. I think part of the sell off is due to Trump / tariffs and all the unknowns in that regard. But Hikma is mainly generics, and from what I understand has growing production in the US; the general view is that the tariff fears are overdone and that Hikma shouldn't be too badly hurt by them.
Overall performance since 2022 has been good. Pays a very well covered 4% dividend also. The vice chairman has purchased £13m worth at around current levels. I personally think this price level will hold. If it drifts lower I'll probably bail at 15%ish loss. Otherwise happy to punt that this is oversold and will find some support at this level. Any holders with views on Hikma would be much appreciated.
I did hold and sold a while ago because of the persistent drops and tariff uncertainty. They are a decent company tho and I understand they will shortly be launching generic weight loss jabs as patents expire. This will provide some boost to the outlook. They should be better valued but as someone from the Pharma sector I am very aware the there are many barrier to smooth progress.
Trustpilot (LON:TRST) Had several very bad experiences with Edreams and Opodo (the same company). They cancelled a flight at 2 days notice and never reimbursed me for the flight. Then kept charging for their annual subscription even though i had never signed up for it and i repeatedly cancelled it.
Wrote a bad review on Trustpilot which they accepted and posted on their site. Then Edreams emailed me and said they would investigate my complaint. A day later the review was deleted from the Trustpilot site. Of course Edreams never contacted me after that.
I suspect that most of the 5 star reviews of Edreams on Trustpilot are bogus, although i do not have evidence. They are very short and seem to be ridiculously upbeat.
P.S.
An alternative review company called Reviews.Io have 264 reviews of Edreams of which almost 100% are compliants / negative reviews. I could not find a single 5 star review.
In comparison on the Trustpilot site about 95% are 5 star reviews!
It does appear that Edreams have paid for these positive reviews. Although again to emphasize i do not have concrete evidence of this.
Yes TP very happy to pull negative ones for a customer with enough money :) The analysis from the team said they have a moat and it seems unlikely that en masse the public would somehow lose faith in them (despite how clearly they are dodgy and untrustworthy to anyone paying attention, maybe no one is paying attention), my stance on the contrary is it really would not take much mainstream media coverage at all for this business to become persona non grata and get dumped by Google to protect its own reputation. A business which is actively and intentionally misleading the public when its only purpose supposedly is to support and protect the public simply cannot last in my opinion, over the long term. They'll get caught going too far and something serious will happen because of their negligence. Whether it will be tomorrow or in 5 years, who knows.
Advanced Medical Solutions (LON:AMS)
Bridgepoint weighs 550 million pound bid for London-listed medical group AMS- Sky New
Long Term Holder.
Ocado (LON:OCDO)
If it takes more than 5 years to prove the economics of a business idea, that basically tells you all you need to know. Ocado has been given 25 years to prove their business idea. How they have kept this farce going for so long, just beggars belief.
I'm still amazed that Ocado is valued so highly.
Has it ever delivered a profit?
The proof in the pudding is closer to home with Ocado (LON:OCDO).
If the technology is so good, they would be dominating the online grocery space in the UK. That hasn't happened. Their technology has been incremental to own-grown solutions by Tesco, Sainsbury's, etc.
OCDO. I'd also add that it you do over £1b in revenue and still can't make a profit, then you've got a bad business.
What else? Oh, the company had less revenue in 2024 than it did in 2019. Anyone who thought it would be the Amazon of groceries or whatever should think again.
Net debt has gone from £146m to over £1b on a TTM basis. As an extra sanity check I like to check EV (£2.6b) against mkt cap (£1.6n). Both of these are saying the same thing: the compnay has too much debt and is a bankruptcy candidate.
I have said for years now that OCDO does not have a viable business model. It puzzles me that they could have gone on for so long.
Stockopedia gives it a Quality score of 19 and a StockRank of 13.
Ccompletely uninvestable.
ME International (LON:MEGP) - Termination of offer period. Following engagement with several interested parties, the Board of Directors confirms that it has not received an offer that it believes would be in the best interests of all the Company's shareholders, and therefore discussions have been terminated. As a result, the Company is no longer in an "offer period"
ME International (LON:MEGP) F/cast Revenue for 2025 311m - 319m, profit 76 - 79m. I wish they wouldn't keep putting the Co up for sale and just get on with their knitting.
Held up fairly well. Should never announced an offer period
Trading 212 down for anyone else?
Yes. Down for me too.
Substack also down with "500 Internal Server Error cloudflare" error message so cloudflare outage affecting multiple providers again?
Big Yellow (LON:BYG) - Blackstone has announced that it is no longer intending to make an offer.
https://www.stockopedia.com/sh...
Custodian Property Income Reit (LON:CREI) and Schroder European Real Estate Investment Trust (LON:SERE) both provide updates today. A while back property reits were covered but seem to of been forgotten. Both pay a handsom dividend and both report an improving picture. Could perhaps find the time to cover today
Echo that. REITa are one of the sectors that interests me most. Perhaps the most interesting update this week has come from NRR, my largest REIT holding. Lots to digest there and I would welcome Graham’s views.
Do you follow the Investment Trust, REIT and ETFs discussion board set up by Charles Mitchell? Have a look. There are a number of us who participate thoughtfully and I know Schroder European Real Estate Investment Trust (LON:SERE) is often mentioned. And we have discussed Newriver Reit (LON:NRR), whose presentation I will attend (online) later.
Thanks raggedtp
I did add a bit re SERE this morning. I have sold today as the risk/reward ratio unsettled me. https://www.stockopedia.com/co...