Daily Stock Market Report (Fri 5th June 2026) - EVOK, RPI, BOY, REVB, SOM, ACSO

S&P SpaceX Decision: overnight, S&P has announced that it will not change its eligibility requirements in order to fast-track mega-IPOs such as SpaceX into its indices.
In addition to free float requirements, the two main rules for inclusion are:
Seasoning: companies must be publicly listed for at least a year.
Profitability: for indices like the S&P 500, companies must have positive net income for the most recent quarter and in total for the four most recent quarters (this is why Tesla spent so many years outside the S&P 500, despite being easily large enough to qualify).
I must say that I’m glad that S&P aren’t changing the rulebook for mega-IPOs. Firstly, it’s important for the character of their indices. Gaining entry to the S&P 500 has always meant something, and it would change the character of the index to dilute that meaning.
Secondly, an important effect of the rules these days is the protection of ETF investors. While seasonality and profitability requirements don’t prevent index investors from having a bad outcome, they do serve to protect them from some of the riskiest situations.
Unprofitable, newly-listed companies are almost by definition riskier than profitable, mature stocks. But other major providers have been adjusting their rules to give newly-listed large-caps faster entry to their indices.
So well done to S&P Dow Jones for this decision. For the millions of passive investors who expect their funds to invest in blue-chip stocks, it's the right call.
Overnight market movements:
The FTSE is set to open unchanged at 10,350
S&P 500 is down 0.5% at 7,550
Brent crude is up 0.2% at $95.40
Gold is down 0.6% at $4,445
Bitcoin is down 1.2% at $63,000
Have a great weekend, thanks everyone!
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Raspberry PI Holdings (LON:RPI) (£1.6bn | SR51) | SP +27% H1 profitability materially ahead of H1 2025. The strong profitability delivered in the first half is expected to result in FY 2026 EBITDA being significantly ahead of current market expectations (consensus: $42m adjusted EBITDA). | AMBER ↑ (Graham) We were AMBER/RED on this last time, with the company warning of limited visibility and trading at what seemed a very expensive earnings multiple of 30x. The share price has exploded since then, up by nearly 4x. I’m going to have to upgrade our view on the stock, as it has very clearly negated some of the reasons for caution at the beginning of the year. The memory shortage is being overcome and price rises are being passed onto customers. | |
Bodycote (LON:BOY) (£1.41bn | SR85) | SP -10% | AMBER/GREEN = (Graham) | |
Resolute Mining (LON:RSG) (£1.26bn | SR76) | SP -6% Q2 has been impacted by logistical and supply chain disruptions over the past four weeks due to security challenges in Mali in late April and May 2026. Q2 gold production to be c. 30 koz versus original expectation of 40 - 45 koz. Production at Syama is expected to be around the lower end of the guidance range of 195 - 210 koz in 2026. | BLACK | |
Seraphim Space Investment Trust (LON:SSIT) (£444m | SR93) | Monthly newsletter covering £137m capital raise and developments at various portfolio companies. | ||
| Tufton Assets (LON:SHIP) (£233m | SR94) | Market and NAV Update | Intra-quarter update. NAV $413.5m, NAV per share $1.546. “The product tanker and bulker markets remained strong in April and May. Product tankers (which carry diesel, petrol, aviation fuel, chemicals etc.) saw benchmark rates decrease slightly in May from the highest levels of the past decade.” | |
BTG Consulting (LON:BTG) (£202m | SR92) | Buys MVLOnline.co.uk, a specialist solvent liquidations website. | ||
Evoke (LON:EVOK) (£180m | SR60) | SP +13% | TAKEOVER (Graham holds) | |
Somero Enterprises (LON:SOM) (£98m | SR77) | SP +4% “Stabilization in US private non-residential construction, the Company's largest market, continued and the positive trading momentum from the end of 2025 carried over with trading in the five months ended 31 May 2026 tracking well against the full year ending 31 December 2026 guidance.” Also conducting a thorough review of governance arrangements and legal constitution. | AMBER = (Graham) [no section below] In March, Somero guided that 2026 would see revenue, profitability and cash generation "broadly comparable" to 2025. Unfortunately, those 2025 results were a big disappointment compared to the prior year, with revenues falling 19% and PBT down 36%. I have suspected for some time now that Somero is struggling against homegrown US competitors offering much cheaper screeding tools. After this in-line update, I'll leave our neutral stance unchanged. | |
| accesso Technology (LON:ACSO) (£87m | SR79) | Holdings in Company | SP +18% Toronto-based Constellation Software discloses that its holding in Accesso is now 3.2%. | AMBER/RED ↑ (Graham) [no section below] This is no ordinary Holdings RNS. Constellation Software have appeared on the Accesso shareholder register for the first time: they are a huge player internationally when it comes to software M&A. Here's their Canadian StockReport. They own over 1,100 businesses and their interest in Accesso demands that I get this one off the RED list. Watch this space. |
Iofina (LON:IOF) (£82m | SR87) | Agreement with a new brine water supply partner to provide additional brine water to its IOsorb® plant, IO#11, located in Central Oklahoma. | ||
STV (LON:STVG) (£49m | SR40) | H1 TAR expected to be up c.4%. “Whilst we expect a boost in advertising revenue from the FIFA World Cup, we remain cautious on the outlook for the second half of the year given the underlying softness in the advertising and commissioning markets driven by the continuing uncertain geopolitical situation.” | ||
Revolution Beauty (LON:REVB) (£37m | SR37) | REVB has been notified by the FCA that its investigation into the Company has ceased and no further action will be taken against the Company. "It is fitting to receive this news from the FCA at a time when Tom and Adam are back involved in the business and have reinvigorated it with a clear strategy. The early signs that this strategy is working are very encouraging, and the future is much brighter for the Revolution brand." | RED = (Graham) [no section below] | |
Kendrick Resources (LON:KEN) (£28m | SR18) | Initial assessment confirms Kieshöhe has the potential to emerge as a major rare earth discovery. “These results mark an important milestone in the development of the Bonya Rare Earth Project and significantly enhance our view of the potential scale of the district.” | ||
Defence Holdings (LON:ALRT) (£26m | SR11) | The Transparency Notice states that the proposed engagement carries a value of approximately £226,000 over a three-month term and covers testing phase of the capability. | ||
Genedrive (LON:GDR) (£20m | SR14) | R&D tax credit refund of approximately £0.76m from HMRC in respect of FY June 2024 and FY June 2025. |
Graham's Section
Evoke (LON:EVOK)
Up 13% at 45p (£180m) - Recommended all-share acquisition of evoke plc - Graham - TAKEOVER
(At the time of writing, Graham has a long position in EVOK.)
This has been a stubborn holding of mine for years, and it seems to be reaching some sort of a conclusion.
The board of Bally's Intralot S.A. ("Intralot") and the board of evoke plc ("evoke") are pleased to announce that they have reached an agreement on the terms and conditions of a recommended all-share acquisition
We’ve known since April that Bally’s were interested in evoke. We were told then that Bally’s were considered an offer of 50p per share.
Bally’s is a Greek lottery company, listed on the Athens stock exchange: here’s the StockReport. It has a market cap of €2.2 billion (£1.9bn), so about 10x the value of evoke.
Today’s proposal is as follows:
0.537 New Intralot shares for each evoke share, representing a value of 52p based on the Intralot share price of €1.12
Cash offer: alternatively, evoke shareholders can elect to receive 52p in cash. If they fail to do that, they will automatically receive Intralot shares by default.
And there’s an important condition: the max amount of cash that Intralot will pay is capped at £117m. If demand for the cash offer exceeds this amount, then shareholders will get scaled back pro rata.
Premium: the proposal represents a premium of 138% vs. the EVOK share price, prior to the announcement of a Strategic Review.
Intralot’s perspective: the combination will create “a global gaming and lottery champion with scaled pan-European B2C, adding significant reach across locally regulated markets”.
evoke’s perspective: the UK government’s tax hikes on the gambling sector were a major cause for the Strategic Review which has ultimately led to this proposal. RGD on online gaming has increased from 21% to 40%, and duty on online betting will increase from 15% to 25% next year:
The evoke Board considered that these changes represent a material shift in the UK operating environment and, given evoke's significant UK exposure, were expected to have a material adverse impact on the evoke Group's profitability and cash generation. On the evoke Group's initial estimates, prior to mitigating actions, these changes would increase duty costs by approximately GBP 125-135 million on an annualised basis once fully implemented representing 36 per cent. of evoke's FY 2025 EBITDA…
evoke expected to mitigate about 50% of the hit, but that still hits profitability by over £60m, results in much smaller long-term growth prospects (as the mitigating actions include less marketing and promotional activities, and shutting stores), and severely challenges the ability of the group to tackle its £1.8 billion debt pile.
We are informed that Intralot has already made five earlier proposals, with the first of these being at 32p per share.
Under the current proposal, Intralot will redeem evoke’s 2028 bonds - which solves a major problem. evoke admit that they “faced near term refinancing risk with the upcoming 2028 maturities”. They currently have a junk rating “B” at Fitch, with a negative outlook.
Irrevocable undertakings/letters of intent: shareholders representing 29% of the company have already pledged to vote in favour of the scheme.
Graham’s view
I expect this to go ahead. Intralot is a credible buyer and as I said before, they must have a very detailed debt management plan in order to go ahead with it. Some of those details are laid out in today’s announcement.
And as I think that evoke could easily be a zero if it doesn’t get taken over, I am strongly in favour of this deal.
No offense to Intralot, but I’d rather have 52p rather than an Intralot share. So that’s what I’ll be asking for. If other evoke shareholders do the same, which seems likely, we will all end up getting scaled back accordingly.
And well done to the evoke board for salvaging something for us and for striking a hard bargain.
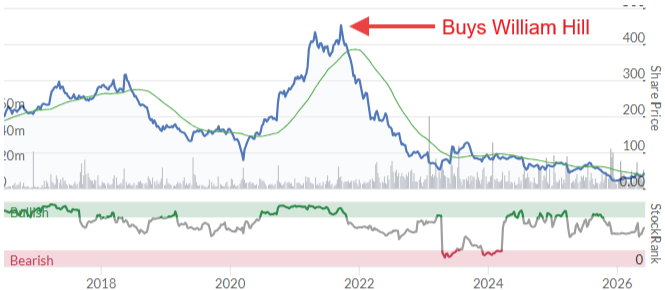
Previous awful decisions, by the previous management team - the takeover of William Hill, basically - ruined shareholder value here. The UK tax hikes were then the nail in the coffin. But at least we didn’t walk away with absolutely nothing.
Of course the smart thing for me to have done would have been to sell on the day of that announcement, which was pretty much at the top:
Trading approach: I’ve been asked why I held onto my 888/evoke shares for so long.
As this is sort of a philosophical point, I’d like to explain generally why I think that not selling works so well for me, most of the time, even when it’s painful.
The basic reason is this: I don’t think I’m smart enough to time my entries and exits on a regular basis. If I was moving stocks like Andrew Left does, then maybe I’d be able to do it. Or if I followed a different approach, e.g. regularly rebalancing with the help of an automated system, then it would make sense.
But my approach is simply to find stocks where I like the fundamentals and the price. Sometimes I’m right and sometimes I’m wrong. And after I’ve done my research, I want to gain the full benefit of that work. That means holding the investment for the long-term.
Fresh ideas come along regularly, and I’ll invest in them when I can, but I don’t want to spend my life jumping from one good idea to another. Intellectual honesty means admitting that I can’t predict which of my ideas will perform the best over the long term - so I see little point in constantly juggling them.
When I do sell, it’s for one of three reasons:
Cash flow: if I personally need cash.
Change of opinion: if I no longer believe in the investment thesis.
Concentration: if a stock has done very well and is too large as a percentage of my portfolio.
These are all good reasons to sell. But for me at least, they are rare.
Being a long-term holder who rarely sells has created four multi-baggers in my portfolio (Volvere, Berkshire Hathaway, IG Group and Next). They have all been very boring holdings, most of the time.
If I had sold evoke shares back in 2021 on the day of the William Hill announcement, that would indeed have been smart. But if I had been smart enough to do that, I might also have thought myself smart to sell IG when it announced the expensive acquisition of tastytrade, also in 2021. But the IG share price is up by well over 100% since then, and it has also paid out 250p per share in dividends. So that would have been a dangerous game to play.
Everyone has their own approach, and that’s fine. But as I’ve been questioned about my evoke holding a few times, I wanted to give my answer. The answer is that I like holding investments through to their conclusion, and it seems to work for me.
This does mean I might get a zero some day. evoke could very well have been a zero. But it has already been priced like an option for a while now, so I was fine with holding that option and seeing what happened. The final result is a reasonable one, in the circumstances. We move on!
Raspberry PI Holdings (LON:RPI)
Up 27% at £10.42 (£2.01 billion) - Trading Update - Graham - AMBER ↑
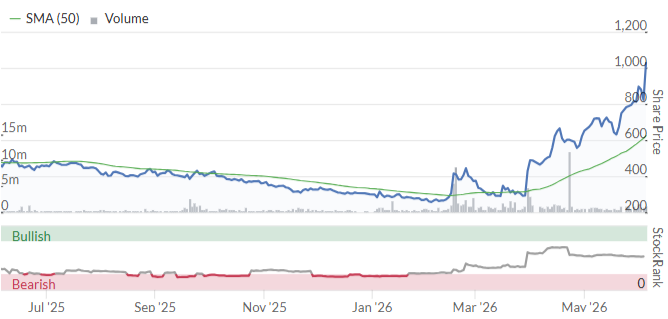
It doesn’t feel like this has been listed very long. The IPO price was 280p in June 2024.
It’s had a remarkable year, especially the last few months:
Today it upgrades expectations.
Key points:
H1 profitability materially ahead of H1 last year.
Over 4 million units, adjusted EBITDA at least $38m.
Profitability may cool down in H2 (emphasis added):
Despite DRAM related price increases, the Company has seen continued robust demand for its products from OEMs and other customers. In the second half, the Company will focus on the strategic opportunity to gain market share and further strengthen customer relationships. Unit economics are expected to moderate in H2 as inventory of memory procured at a lower cost in earlier periods is depleted.
DRAM = dynamic random-access memory, a key input for Raspberry Pi. The market for DRAM is supposed to be experiencing an AI-induced shortage right now, as mega corporations are hoovering up all available supply.
Raspberry Pi again says there are challenges with both the pricing and availability of DRAM and other memory. The company said the same back in January. But it is now “confident that it can secure the inventory necessary to meet its FY 2026 production goals”.
Conclusion:
The strong profitability delivered in the first half is expected to result in FY 2026 EBITDA being significantly ahead of current market expectations.
Market expectations for FY26 adjusted EBITDA are given as $42m. This consensus figure clearly makes little sense now, with 90% of it having already been achieved in H1.
Graham’s view
We were AMBER/RED on this last time, with the company warning of limited visibility and trading at what seemed to be a very expensive earnings multiple of 30x.
The share price has exploded since then, up by nearly 4x.
I’m going to have to upgrade our view on the stock, as it has very clearly negated some of the reasons for caution at the beginning of the year. The memory shortage is being overcome and price rises are being passed onto customers.
Where I would add caution is that today’s statement clearly warns about the sustainability of H1 profitability. Selling old inventory that was cheaply assembled always creates turbo-charged profits after a period of high inflation. My understanding is that DRAM prices have trebled over the past year. But Raspberry Pi will have to pay new DRAM prices when building new inventory, and that cost will be reflected in future profits.
So it seems to me that real, sustainable profitability is still very hard to judge here.
But still, I’m switching us to neutral. This one is in my “too difficult” tray - well done if you’ve been participating in the rally this year.
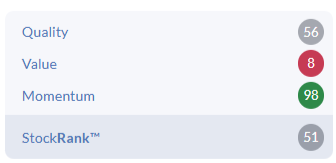
The StockRanks see enough Quality to give it an average StockRank, despite the lack of obvious value:
Bodycote (LON:BOY)
Down 11% at 735.5p (£1.26bn) - Response to statement by Apollo - Graham - AMBER/GREEN =
This takeover idea has ended very quickly.
On 22nd May, Bodycote confirmed it had received a possible cash offer from private equity giant Apollo at 885p per share. Discussions were ongoing.
Two weeks later Apollo has walked away, as politely as possible:
Apollo confirms that it does not intend to make a firm offer for Bodycote… Apollo continues to hold Bodycote and its management team in high regard, is appreciative of the discussions with them and Bodycote's board of directors, and would like to thank them for their time and consideration of the proposal.
In response, Bodycote says this:
The Board of Bodycote has strong confidence in Bodycote's potential and its strategy to create a high-performing, resilient business with attractive growth prospects. Bodycote continues to execute well on the group's Optimise, Perform and Grow initiatives, with a positive start to 2026 trading as set out in the AGM trading update of 27 May 2026.
Reasons aren’t given, so I don’t see much value in speculating as to what has happened. It could be a simple matter of disagreement over price. What we do know is that Apollo and Bodycote have remained polite to each other in public, which puts a limit on how serious the disagreement might have been. Perhaps Apollo will look at Bodycote again at some point.
Graham’s view
We turned AMBER/GREEN on Bodycote in March so I will leave that stance unchanged today.
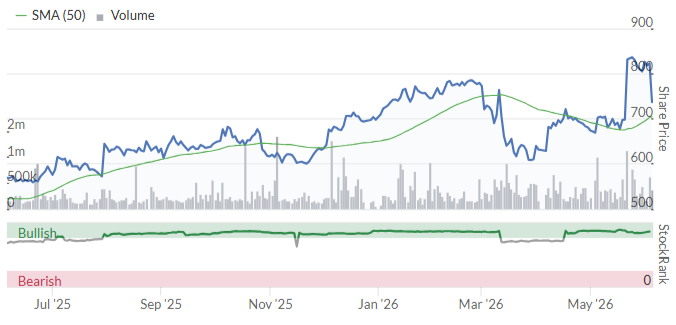
Could it be that we’ve reached the point where the most obvious takeover candidates have left the London market already, and buyers have to be a little more careful now? The Bodycote share price has been firm over the past year:
With Bodycote sticking around, the next one to leave looks like it might be Tate & Lyle (LON:TATE). The PUSU deadline for that one is next Thursday, 11th June.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

34 comments
Raspberry PI Holdings (LON:RPI) , extreme caution is warranted before piling into this, many IT hardware buyers have seen the memory and chip squeeze coming and have bought forward their purchases to stockpile hardware to mitigate price rises. Don't be surprised if their sales suddenly drop off a cliff.
Non farms surprised positively and wrong footed forecasters looking for a slow down...so bond yields rise with currency and markets bet next rate move from Fed is up ...not down. Higher inflation = higher rates for longer seems to be winning the day for now. Gold and silver getting crushed as a result as rising $ doesn't fit their bull story. Its just one data point but I figure ongoing failure to resolve the issues in the straight will cause todays move to go further. It all adds up to quite a complex situation and although volatility measures VIX and MOVE are behaving well - I am happy running a smaller book for now as a defence against sentiment the turns south. No sign of that yet.
I notice Hercules (LON:HERC) managed to sneak results out at 10.01 on a Friday.
Gamma Communications (LON:GAMA) Whilst we're on the subject of takeover deals, a reminder that GAMA is in a takeover situation. Forward PE is less than 10, which is totally daft.
I do hope that Graham is right that the takeovers will be pretty thin by now.
GAMA has announced that it is looking for buyers.
I hold. Generally speaking I do not like takeover deals.
Talking of lopsided deals ... I remember holding MicroFocus years back. Their big produce was a Cobol compiler, the most boring language you can think of. Nevertheless, it had good returns on capital and seemed to be doing pretty well for itself.
I did quite well out of it, as I recall.
Anyway, one day they did a big oversized deal. I was suspicious of the deal. The interest cover deteriorated beyond what I was happy with. I did a lot of thinking about this, and decided to sell. It was a hard decision for me, because I did like it at my original buy, and like I say, I was doing pretty well profit-wise. I decided I wasn't happy, and sold out. The share price continued to climb, naturally, but the situation deteriorated soon enough, and down went the share price. I count that as one of my most inspired sells. I don't have many of those to choose from, mind.
I have noticed that Kendrick Resources (LON:KEN) is covered in this morning agenda.
Colin Bird is behind this company!
Bezant Resources (LON:BZT) Xtract Resources (LON:XTR) Galileo Resources (LON:GLR) Are some of his past projects…..
DYOR, before you waste your hard earned money.
All the best
Good shout yiannos1
Many thanks Graham for your thoughts on Evoke and your investing style.
I, too, have come to the conclusion that for the most part holdings should be left alone and not tinkered with. I've sold stuff like JD Sports and numerous other holdings when I should have been holding on.
It depends on one's investing style, of course. If you're a value investor, then you just want to flip the shares. A growth/quality investor should be happy enough to let the holdings mature, pretty much indefinitely. I now sell or at least trim when the valuation gets ridiculous (not just "stretched"), or something goes decidedly wrong. I'm not talking about a disappointing update, I'm talking about the balance sheet looking stretched or I made a fundamental error at the outset,
Some things to consider is that if a deal is described as "transformational", then look out! That's your red flag.
In April 2020, Evoke was worth about £515m, whilst it was looking to purchase a £1.95b company. There, or thereabouts. No need to nitpick the finer details. That's a very lopsided deal, and one that smacks of hubris.
The IG purchase, OTOH, looks rather more modest. In Jan 2021 IG was worth about £2.9b, whereas the target was around £740m. A much more balanced acquisition.
"Tastytrade is a technology-focused, options-first platform" Sounds exactly like the kind of thing that appeals across the Atlantic and the WallStreetBets crowd. Not sure what happens if the market trades sideways for a decade, mind, and people fins that stonks don't just go up.
Evoke (LON:EVOK)
In April 2020, Evoke was worth about £515m, whilst it was looking to purchase a £1.95b company. There, or thereabouts. No need to nitpick the finer details. That's a very lopsided deal, and one that smacks of hubris.
You couldnt be more right here mARK - its your typical shit of bust management decision playing with shareholders cash/paper value whilst upping their salaries and little to lose if it doenst work - what was 888 used to be a solid company with a great balance sheet with cheap rating pre covid (from memory) - i was lucky enough to have sold out on the covid spike before the william hill acquisition - but bearing in mind shop useage was already in decline pre 2022 the warning signs were probably there. In theory i am guessing william hill would and should have brought with it fantastic cashflow after the deal check in soem cost savings ref merger - online gambling has never been the most reliable sector though and is an easy patsy for extra taxes - albeit william hill and 888 were probably both about as low risk as you could get with regard to falling foul of regulation.
Agreed, Mark. Thanks for the comment re: EVOK. The warning signs were there - it was a crazy deal. Although at the time, it seemed like it was possible that they could pull it off - perhaps not the most likely outcome, but it was possible. If I had sold out completely, and they had pulled it off, I'd have been disgusted! But perhaps I could be a little more nimble next time, e.g. reducing position size by 30-50% when the risk levels are radically altered. Thanks again. G
Well, after a,stellar April and May for my folio, June has been a terrible start. Seems like a lot of shares are now looking weak/giving back any gains.
Maybe trim one or two positions, June to November never that decent. Or just do.. nothing!
Anyone with any interesting shares atm?
A positive RNS update for Iodine producer Iofina (LON:IOF), with Canaccord upgrading 2027 EPS by +6%.
For those of you interested in "Jumps" (like me), take a look at the 9 previous below….
accesso Technology (LON:ACSO)
Constellation Software popped up on the ACSO register this morning with a 3.16% stake, and the market likes it.
AI says: "For anyone not familiar with them, Constellation is a Canadian giant that specialises in buying and holding niche, mission‑critical software businesses. They’re known for being extremely selective, very long‑term, and rarely take passive positions unless they see strategic value.
Given ACSO’s profile – sticky customers, vertical‑market software, global footprint – it’s not surprising they’re interested. Whether this is just a toe‑dip or something more meaningful, time will tell, but it’s certainly an interesting development."
Any ACSO experts here with a view? Edit: I note both Graham and Mark rated it Red in January but is the bottom now in?
Thanks for that info Peter. I hold accesso Technology (LON:ACSO). I'm no expert on the company but I am of the opinion that this is a bottom.
With this added information we can see that the Wyckoff pattern is accumulation not distribution. The volume is at around 270p. Watch for a retest of around 285p. If this is successful then the next target of the range is 340p and the volume shelf above. Of course if Constellation stop buying at these prices then the price could fall back into the range. Very interesting to watch (if you like charts!) ;)
Thanks very much for that, Revs8 — really helpful to read your take on it. I’ve taken a small position here recently and today’s news about Constellation does make me feel more comfortable being in it. And while I’m no chart wizard myself, I do read the posts on the Trade/Chart Ideas page with great interest and really appreciate the input from everyone there. I'll look forward to any updates you post — always appreciate the way you break things down.
Is that what you call an inverted Head and Shoulders pattern?
Yes. Of sorts. Wyckoff trading ranges often form these patterns but the difficult part is spotting if they are bottoms or continuation patterns. They can sometimes flip and go the other way.
Wise (NSQ:WSE) apologies for dragging us back to this But after comments re AML regs from others incl. rmilelree I dug a little deeper yesterday. It is true that AML regs have been tightened since I passed the regi rep stuff in the early 90s.... so the old ID verification is pretty similar but much more emphasis on source of funds and reasons to be suspicious. Furthermore, my old fashioned view that once in a bank its clean no longer holds. In theory the net is wider but this is the same for all financial businesses. And so they all have a greater responsibility to report suspicious activity esp if source of funds seems questionable. Personally, I don't think this is hugely negative for Wise (NSQ:WSE) as I see the real risk being they haven't completed the necessary checks. Of course a systematic fraud could have been implemented but this risk is always there and Im pretty sure WISE invest a lot to make sure their customers are who they claim to be. Obviously the volume of business they do is a positive and negative but the real Q I would have is have they done everything to prevent dirty money slipping through the net?.... and I can't answer this but would tend to assume they probably have. An interesting headache well timed with the Nasdaq float but a 30% share price correction would appear to capture a lot of the risk. The previous fine in the US was relatively small Vs the size of this fall in share price. So accepting some risk for sure but I do still think its all a storm in a teacup but yesterdays story that a class action is being filed re the admission data isn't helpful at all. Im not involved but tempted to punt it will all blow over.
Wise (NSQ:WSE)
Thanks for your updated comments RDHOWARTH they are most useful - as you say time are moving on very quickly ref mlr and thats the danger of mission creep from the authorities where we in 18th months time may have "more checks needed" than now so every year wise need to do more in each country are rules are made stricter - what is not really acceptable is where stuff gets so common that the regulators are asleep at the wheel for years and then act to late so regulators dont exactly help - they will probably say though well that compare chose to sail so close to the wind they crossed a line - and clearly that is the case when care salesmen can make up interest rates themselves
but yesterdays story that a class action is being filed re the admission data isn't helpful at all.
i used to worry about stuff like this when i first started investing in us - but it seems so common - often on super spurious stuff it seems reasonably clear to me most of the time its perhaps no more than marketing email to someone who might have some beef to register an interest - so i would pay close to zero attention to this specific issue - unless it escalates to the point the company need to update.
Wise (NSQ:WSE)
AML regulations are built to avoid fixed targets - there is no single set of processes or systems than any company can build in order to ensure they are compliant. This is in recognition of the reality that fraudsters are continually evolving their attacks and payment companies need to constantly respond.
Invariably investigations are data based - fraud is a way of life for payment companies, so there needs to be some evidence that something is going seriously wrong before regulators will get involved. In this case it appears that Wise was appearing as involved in an unusually large percentage of detected money laundering transactions. The de-facto assumption will be that there is a failure in Wise's monitoring systems and / or processes designed to respond to money laundering attempts.
Under the circumstances it's unlikely that there's nothing to see here: the question is whether this was detected or not. If Wise did detect it and then failed to block it and report it then the punishments are likely to be greater than if they didn't, unless that failure was so basic as to be deemed egregious.
Regulators often get criticised but generally they get the data last - only the payment companies themselves see the live data, so only they can stop fraud in process. Forthcoming EU regulations allow financial services companies to share fraud data which should mean detection of overall fraud patterns and outliers in fraud detection become visible more quickly, which will help to prevent this type of situation.
There are a range of possibilities here from no action through to a fine of 10% of global turnover and a temporary block on onboarding new customers. Generally the response is somewhere towards the lower end, but from the outside there's really no way of knowing: this is the problem with regulatory intervention for an investor, there's no way of assessing the probabilities of any specific outcome: it's a black box.
timarr
Wise (LON:WISE)
AML regulations are built to avoid fixed targets - there is no single set of processes or systems than any company can build in order to ensure they are compliant. This is in recognition of the reality that fraudsters are continually evolving their attacks and payment companies need to constantly respond.
100% agree - i think if you read the chain of my comments you will see that i am agreeing that wise have a near impossible job here spotting fraud. that doesnt stop regfulators getting the big stick out though with the beenfit of sindsight - teh mision creep here is clear though - its sort of moving away from strong suspiscion to an area where if you dont know - well you should probably swerve. I ssupect wise have some of teh highests standards here compared to others - whether thats enough or not - well hopefully if they have done their job they may get clean bill.
Regulators often get criticised but generally they get the data last - only the payment companies themselves see the live data, so only they can stop fraud in process.
My point was that especially with car finance the regualors were clearly asleep at the wheel - if they had looked as part of their routine questions or compliance shecks they would have been slapped in the face with the issue - it was pretty obviouslya nwrong un from tehn get go - so how did it take them 5-10 years to realise stuf was eidespread. good regulator nips stuff in the bud - so its not 1-15 years wrongs that need to be corrected.
Under the circumstances it's unlikely that there's nothing to see here: the question is whether this was detected or not. If Wise did detect it and then failed to block it and report it then the punishments are likely to be greater than if they didn't, unless that failure was so basic as to be deemed egregious.
i would say its also - "did wise do all the checks they should have done" - agreed it would be a big sin if they knew and took no action - it seems more likley that they didnt know . note i have no actual specific worries here - it makes sense if authorities dont know how its been missed - that they do as they have done - until they ask detailed questions they may not have the foggiest if wise are completely in the clear - thats sepculation on my part here. There is always imho the danger though the powers that be want to lay blame somewhere.
There are a range of possibilities here from no action through to a fine of 10% of global turnover and a temporary block on onboarding new customers. Generally the response is somewhere towards the lower end
100% agree - all we do know though is as small shareholders (i dont currently hold wise myself)- we will probably be last in the chain ref updates .
it deffo somewhat comes with the territory here - many vehemently said ref car financing that it was much ado about nothing when it was fisrt announced - and the reality is close brothers is with close to half what it was woth 6 monthns before the fca review was announced - is it any surprise that the shareprice was drifting in advance of the "bad news" being fed to investors - and the bad news looks like it was dripfed as slowly as possible hmmm.
anyway we have probably done this one to death now.
Raspberry PI Holdings (LON:RPI) Nice little update. Shares up 14% at one point. I hold on account of being a Raspberry Pi fanboy. So far, it's worked out. At a fwd PE of 80, it ain't cheap. It's a tiny part of my portfolio, I'm aware of the valuation risk, so obviously this post is in no way a recommendation to buy.
I had hoped to do small top-ups on an annual basis, but the valuation is too rich for my blood at the moment. It's probably one of those shares that will rarely be cheap. Shout out to "WheelieDealer" over on Twitter who said last December that RPI looked like it was in post-IPO consolidation and was due for a bounce. Blimey, he called that one perfectly. Maybe that's something to watch out for next time.
Alas, I didn't top up at the time.
SpaceX will still be in the NASDAQ tracker, so it will get passive index inflows which I understand will provide more than 50% of the anticipated combined passive index inflows if the S&P Dow Jones had allowed it to be included. So more Elon hype needed to sell to active investors!
S&P have at least seen sense. I think this IPO is around 30% retail, a relatively high amount. They’ll get suckered in of course and just hope they cash out after the initial jump. Of course the current administration Shills will have all bailed by then.
Mello , Chiswick was on Tuesday and Wednesday this week.
well attended , though I only met Mark from the Stocko writers.
Two interesting events to report: the BASH where Mark’s choice ( dotdigital) and Paul Scott choice (CT Automotive) were overwhelmingly voted down by the audience.
Lord Lee chose PZC again which won 70% approval.
The highlight of the day for me was meeting the managers of S&U.
This family owned company managers were present in full. An elderly identical twin and their cousin from the Midlands.
I enjoyed their straight, clear and no nonsense talk. “We treat our customers as we like to be treated “.
Apparently the business is doing well and they were not affected by the car finance scandal except for extra costs related to the investigation.
Anyone who has followed my BASH picks for a while knows that they always get a strong vote for avoid. I am sufficiently contrarian to take that as a good sign. If everyone loves a stock, it is unlikely to be undervalued!
Interestingly, I hold more CT Automotive (LON:CTA) than dotDigital (LON:DOTD) as it is more obviously undervalued on a forward P/E of around 3 versus around 8 for DOTD (adjusting for cash/debt) and CTA pretty much has their strong forward growth over the next few years baked in due to the way progam wins work in automotive. Whereas DOTD growth is more dependent on the cross selling opportunities from recent acquistions, so less certain in my view. You don't need much (any?) growth to justify the current rating, though, IMO, and both have been signficantly higher rated in the past with little difference in fundamentals or outlook.
Meeting the S&U team was also a highlight for me. They were hilarious and a breath of fresh air from some presentations you see (not necessarily at Mello) from managemnet that are highly polished but lack the decades of real long-term, cautious and understated delivery that the S&U team have.
Happy to back your judgement on CT Automotive (LON:CTA) Mark. I found a few bob tucked down the back of my grandchildren’s JISAs.
Well done indeed S&P Dow Jones!
But that will not preclude a tech sell-off to provide liquidity for SpaceX investments. What does the community think and how can one manage that risk?
LQQS is a 3xleveraged short ETF of the NASDAQ. Not for widows and orphans
That’s half of the story.
Last night’s decision has more to do with future IPOs (Anthropic and OpenAI).
SpaceX is still projected to officially entered the Nasdaq-100 index around 6 July 2026.
All the best
Yes and anyone in a QQQ type tracker being NASDAQ 100 will be going along for the ride (from day 15) and including the first 6 months. Also note VanEck funds have flexibility are structured with "fast-track" inclusion rules. so will probably buy from day one (not 15).
Correct what you said.
But also it is correct to emphasise that about 70% of these passive investments are benchmarked against and another large percentage of them is hedged.
All the best
Confirmation of the bid for Evoke at 52p. A slightly higher price than previously suggested.
Good Morning Graham and all. I thought my Tufton Assets (LON:SHIP) holding had been looking strong recently. They have been very well bid in the market. Today’s RNS explains why. Trumps war on Iran has increased charter rates. It’s an I’ll wind, as they say. Income and NAV on the increase. Shares should continue to do well. Happy days.