Daily Stock Market Report (Fri 6 Dec 2024) - JSE, EBQ, HEAD, MSI, DLG/AV., DFCH, WATR, TRU, CAR

Good morning!
1pm: we're all done! Have a great weekend.
Explanatory notes
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day. We usually avoid the smallest, and most speculative companies, although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We have a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Add your own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing. Links:
Daily Stock Market Report: records from 5/11/2024 (format: Google Sheet).
Companies Reporting
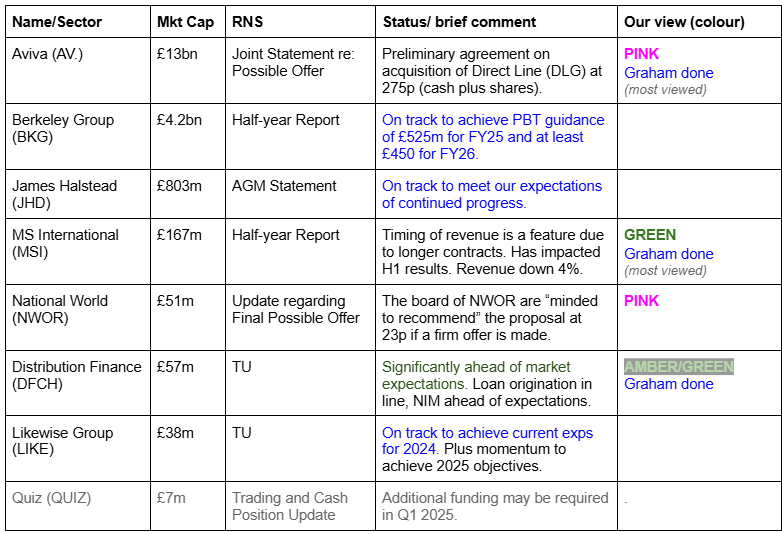
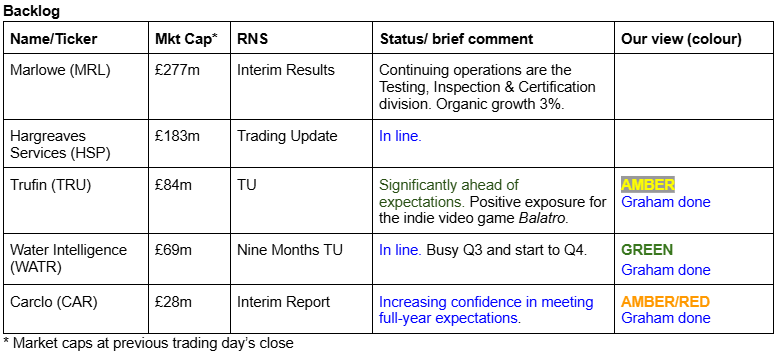
Summaries
MS International (LON:MSI) - down 5% to 975p (£157m) - Half-year Report - Graham - GREEN
These results don’t yet show the progress that I believe is widely expected by shareholders (though I acknowledge that there are no official forecasts). The Chairman points out that accounting rules prevent the recognition of revenue until delivery, and this will be an important feature of MSI’s long-term contracts. My own view is that these results are perfectly fine and that the £20m+ increase in inventories signals future success.
Short Sections
Jadestone Energy (LON:JSE)
Up 4% to 26.4p - Board Change & Corporate Update - Mark (I hold) - AMBER
This accident-prone Asian oil & gas producer loses its CEO:
A. Paul Blakeley has elected to step down as Executive Director, President and Chief Executive Officer of the Company.
Unlike Serica, the production problems at their Montara and Stag fields appear to be mostly their own fault. The lack of maintenance may have been due to a previous operator. However, the length of time that it took to do repairs and the costs associated are down to the company. As such, the CEO appears to have fallen on his sword. He recently bought shares in the company, so this appears to have been unexpected:
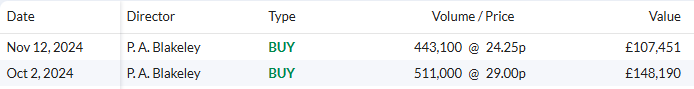
Blakely is thanked, but pointedly, the Chairman says:
A priority for the new management team will be ensuring operational excellence across the portfolio.
The Chair becomes Executive Chair, and a NED becomes COO, so they presumably are not in a rush to appoint another CEO. Not everything has gone badly during Blakely’s tenure. CWLH has proven to be an excellent acquisition so far:
Production also continues to run ahead of expectations at the CWLH asset and the Sinphuhorm field, with the latter recently benefitting from strong gas demand in northern Thailand.
And the Akatara gas project is performing as planned, after fairly normal start-up teething problems:
The Akatara project has achieved sustained gas sales at contractual rates of c.20 MMscf/d (the "Daily Contract Quantity", or DCQ), with overall Akatara production benefitting from associated condensate and LPG streams.
The focus of the new executive management team seems to be avoiding high-risk or capital-intensive development projects. Instead, dividends and buybacks should be back on the cards:
A stronger balance sheet will facilitate the next phase of growth for Jadestone, and allow for a resumption of shareholder returns, which remains a priority for the Board. Capital will be allocated efficiently by investing in projects and acquisitions that deliver the greatest value; we will continue to play to our core strengths of establishing material operated positions in existing upstream assets and creating value through efficient operations and selective reinvestment.
If broker forecasts are to be believed, this puts them on a P/E of less than 4. Given this broker trend, it may be too soon to put too much faith in this:
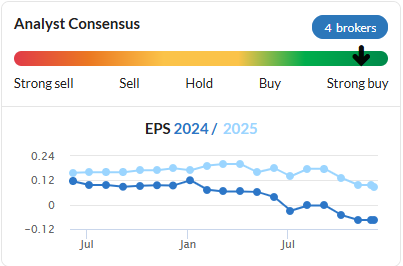
Mark’s view
This remains one of the most hated oil & gas stocks on the UK market. Yet, being Asian-focused it suffers from none of the problems with UK taxation. Instead, it is operational problems that have caused the issues. With the company drawing a line under those and refocusing on strong cash generation from its assets and shareholder returns, this could mark the nadir. It will be a while yet before trust is restored that they have a handle on things operationally, so I am rating it AMBER for the moment. However, £140m market buys a lot of production in favourable tax jurisdictions, so the potential upside is high if that confidence can be built by the new executive team.
Ebiquity (LON:EBQ)
Down 15% to 19p - Trading Update - Mark - BLACK/AMBER
This sounds like a profits warning:
As indicated in the Group's Earnings Release in September, the Board anticipated a stronger H2 than H1; that is proving to be the case with expected H2 revenue still representing a mid-single digit improvement on the revenues of H1 2024. However, the very final months of the financial year are not meeting those high expectations in all respects.
Which is confirmed by the CEO narrative:
H2 2024 performance has been stronger than H1 2024 albeit below previous expectations.
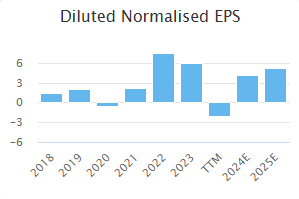
Assuming “mid-single digit” is 5%, this means £77.7m revenue and the guidance of 10% EBIT margin means £7.8m EBIT. They had about £1m of net finance costs in H1, so annualising that gives me £5.8m PBT and £4.3m PAT on a standard tax charge. This is quite a big gap to the £7.7m Stockopedia has for consensus Net Profit. In light of this, the 15% fall in response looks light. Although, it seems that given the forecast P/E, investors may already have been expecting this. The market cap is only 6xPAT on my calculations after the fall.
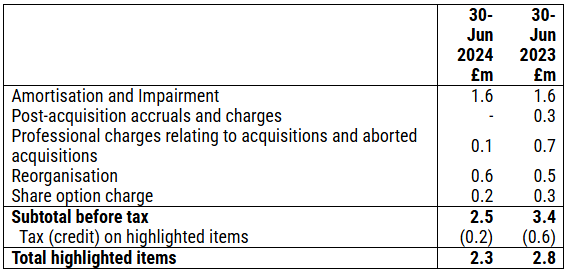
However, this is another acquisitive company that likes its adjusted figures, so things are undoubtedly worse than their preferred measure would have you believe:
Net debt is also significant:
Net debt as at 30 June 2024 was £15.3 million. As expected, given the normal seasonality of the Group's cash flows, net debt increased somewhat during the third quarter but is expected to reduce again by year end, following working capital management actions. Stronger seasonal cash collections will continue through Q1 2025 and the Group has ample liquidity and headroom against its banking covenants.
While it may be comforting to know that this increased net debt isn’t causing problems with banking covenants, it is another nail in the coffin of the current valuation, as it is now at least half the market cap.
On the plus side, they do generate decent revenue and have blue-chip clients. They also have a new CEO, who was head of the best-performing part of the business and one they acquired a few years ago. So this may well be the start of a turnaround. However, with a rather patchy history of profitability, it is hard to point to where they may get to if the new CEO does manage to improve things.
Mark’s view
The shares aren’t on a high P/E multiple, even after this profits warning is taken into account. However, the presence of significant net debt and a penchant for adjusted numbers means this isn’t as cheap as it may first appear. Paul rated this AMBER after the last profits warning, and I see no reason to change that.
Headlam (LON:HEAD)
Down 4% to 126p - Trading Update - Mark - AMBER
Yesterday’s news from Brand Architekts and Camelia shows that often good things happen to investors who buy stocks on a significant discount to tangible book value and simply wait.
Headlam has many similar characteristics. A big discount to tangible book value:
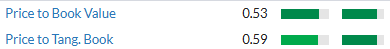
The freehold property on the balance sheet is almost certainly undervaluing it and making the real discount wider. They say:
The last valuation of the property portfolio was undertaken in January 2023; the most recent property sale (in June 2024) was at a premium to this valuation
However, these assets are currently very unproductive:
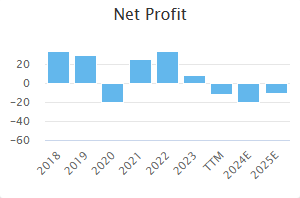
This is a situation that isn’t expected to change any time soon and this trading update to 30th November, moves things further into the future:
As has been widely reported, UK consumer confidence declined in the run-up to the UK government's budget announcement, and this resulted in a further deterioration in the rate of decline in consumer spending on home improvements1. Consequently, there has been no sign of improvement in the flooring market during the second half of the 2024 and we estimate that the market continued to decline at 10-15% year-on-year, in line with H1.
Costs are increasing too:
Whilst the Board anticipated some of the changes that were announced such as the increase in the national minimum wage, the reduction in the national insurance threshold was not anticipated. When combined with the rise in the employers' national insurance rate to 15% the overall effect of these changes will be to add c.£2 million to the Group's annual operating costs, effective from April 2025.
Mark’s view
Ultimately, this is a cyclical industry, and this company will have its day in the sun again. The big question is when? The current discount to freehold property suggests a significant upside to the shares when that upswing does come. However, the time it will take and the presence of better opportunities means that it is hard to think that now is a great time to jump in, and I retain the AMBER rating. However, there is a risk that a Brand Architekts-style scenario makes me look stupid here before the turnaround begins.
Direct Line Insurance (LON:DLG)
Up 7% to 252p (£3.3 billion) - Joint Statement Regarding Possible Offer - Graham - AMBER
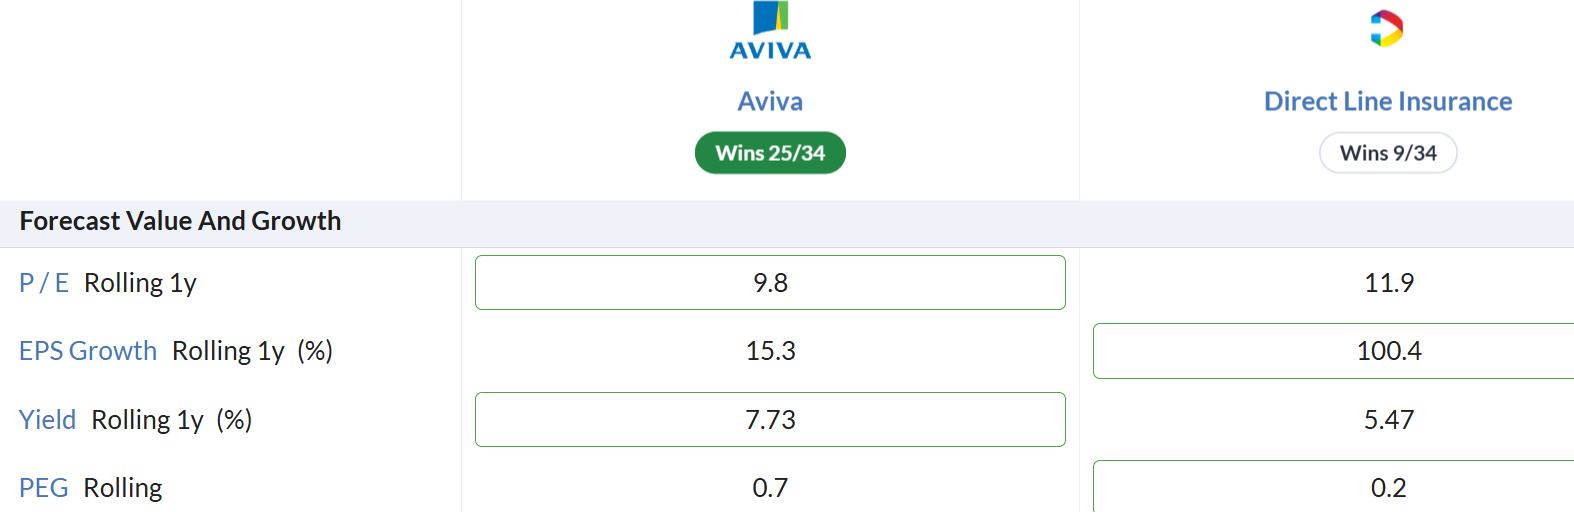
I have no strong opinion on DLG or Aviva shares but just wanted to mention in passing the big news of the day for the FTSE 100:
…the Board of Direct Line has carefully considered the Proposal with its advisers and consulted with Direct Line shareholders during the offer period, and has concluded that the Proposal is at a value that it would be minded to recommend to Direct Line shareholders should a firm intention to make an offer pursuant to Rule 2.7 of the Code be announced…
The offer is for 275p per Direct Line share, comprising 129.7p in cash, dividend payments of up to 5p, plus new Aviva shares.
It strikes me as surprising news because as recently as November 27th (Wednesday of last week), Direct Line said that the initial offer of 250p was “highly opportunistic and substantially undervalued the company”. It came to this original conclusion after consulting with its advisors.
I can only assume that DLG’s shareholders, when they were asked, took a different view. DLG shares don’t seem particularly expensive but then neither do Aviva’s. So swapping out one for the other (plus cash) could make sense.
Distribution Finance Capital Holdings (LON:DFCH)
Up 14% to 37p (£66m) - Trading Update - Graham - AMBER/GREEN
This specialist lender caught my eye this morning with a “significantly ahead of expectations” trading update.
Key points:
Loan origination is in line. End-of-year loan book c. £650-700m.
Net interest margin (NIM) remains ahead of expectations. “Cost of risk running well below the Group’s target of 1%”.
Result: underlying PBT to be significantly ahead of expectations at not less than £14m (2023: £4.6m).
Additionally, DFCH can now reverse £3m of provisions relating to the collapse of the caravan park Royale Life. In total, £4.7m is being recovered from a bad debt of £10m.
Graham’s view: Paul provided a nice overview of this in July. It provides inventory finance to a range of sectors: agricultural,industrial, transportation, motorhomes and caravans (which produced the large impairment), etc.
Tangible net assets at the interims (published in September) were £107m, with TNAV per share of 59.6p. It is currently applying for consumer lending permissions, with the goal of becoming a multi-product lender.
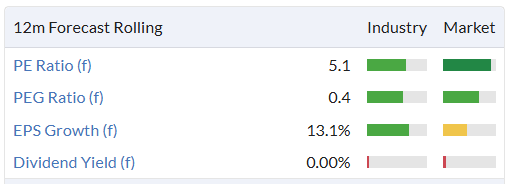
Given the strong trading, discount to book value, derisory P/E multiple, and growth ambitions, I’m happy to upgrade this to AMBER/GREEN.
Of course as a lender it will be exposed to obvious and not-so-obvious risks. I still shudder every time I think of what happened with PCF Bank, a specialist lender that we covered in this report and that abruptly collapsed and shut down, giving investors no explanation for their sudden capitulation.
Water Intelligence (LON:WATR)
403p (£70m) - Nine months trading and capital allocation update - Graham - GREEN
The interim results from this primarily US-based company didn’t impress me too much in September, with sales growth across its network of just 2%.
Yesterday’s Q3 update was in line with expectations.
Q3 revenue rose 10% to $63.5m, led by sales at its corporate-owned stores. Franchising royalties and other franchise-related revenues declined.
I think these trends are easily explained by the fact that it has been buying back stores from franchisees.
Q3 PBT was up 7% to $6.1m.
Net debt has spiked up to $11m but the company continues to argue that it is “under-levered” with a leverage multiple of less than 1x. It has been on the acquisition trail and recently started buying back its own shares.
An interesting comment from the very well-aligned Executive Chairman, who seems almost apologetic for the lack of share price progress:
"We have a had a busy Q3 and start to Q4. We continue to grow and our team is executing along all facets of a capital allocation plan that is expected to produce accelerated growth in 2025. Our balance sheet remains strong, enabling us to continue to drive growth from our capital allocation plan. We appreciate the continued support of our shareholders and will be calibrating the delivery of our growth plan with better communication on the value of our shares given the headwinds facing the AIM market."
Graham’s view
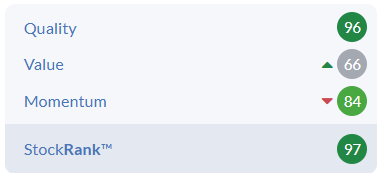
I’ve been GREEN on this but at the same time, I’ve been asking that the company find a way to boost growth rates, as 2% sales growth across the network is not, in my view, exciting enough to stay positive on the shares. In fairness, they seem determined to do this and I agree that they should be financially strong enough to make the necessary investments. I’ll leave my GREEN stance unchanged for now.
The StockRanks agree:
Trufin (LON:TRU)
79.6p (£84m) - Trading Statement - Graham - AMBER
Trufin is a collection of businesses in payments, games publishing and invoice financing.
Historically, it has been heavily loss-making but revenues are on the rise and it says it is “fully funded to profitability”.
Yesterday’s positive trading update relates to the success of a game called Balatro. As a result, financial performance for 2024 will be significantly ahead of expectations.
Group revenue is now expected to be more than £46m (FY23: £18.1m), representing year-on-year growth in excess of 150%. TruFin also expects EBITDA to be no less than £4.5m (FY23: £(3.5)m) and Adjusted Loss Before Tax to be no more than £(1.5)m (FY23: £(6.6)m).
Estimates: Panmure notes that this is the fourth upgrade and they increase their year-end cash estimate from £6m to £7m.
Graham’s view: I’m happy to upgrade this from AMBER/RED to AMBER as £7m of cash gives the company more than a few years to work its way to profitability, based on the current loss rate. The only disclaimer I would add to this is that video game performance is inherently unpredictable and in the absence of another Balatro next year, the situation could deteriorate. But according to Panmure, the company is on its way to generate a pre-tax profit in 2025.
Carclo (LON:CAR)
31p (£23m) - Interim Report - Graham - AMBER/RED
I looked at this components manufacturer in some detail in September, choosing AMBER/RED as the immediate risk of insolvency had diminished but I could not justify the valuation. The shares were 33p at the time.
In yesterday’s interim report, we learned that net debt had reduced to £25m (including leases).
Checking Panmure’s note, I see an improvement as they now estimate net debt of £24m for March 2025, then £18m for March 2026 (according to my notes they previously estimated £28m for March 2025 and £26m for March 2026). So that’s a very nice trend of falling net debt and falling estimates of net debt.
Today’s outlook statement is positive:
The markets for our businesses are stable, this along with our solid HY25 performance, provide the Board with increasing confidence in meeting its full-year expectations. The strategic changes underway are building a strong foundation for sustained performance improvement and we are confident that we remain on track to achieve our long-term strategic goals.
Less positively, the company did make a small pre-tax loss in H1, as operating profit was entirely eaten up by interest expense.
The performance looks a little better if you’re willing to exclude exceptional items: it cost £1.3m to refinance their bank facilities.
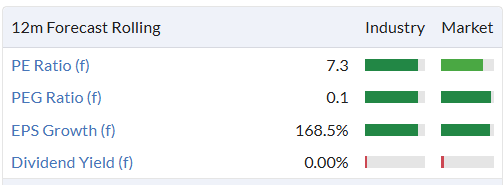
Graham’s view: perhaps a little harsh, but I’ll leave this at AMBER/RED. I don’t like the balance sheet with net assets of c. zero and negative tangible asset value. In addition to the bank situation, there’s a retirement benefit obligation of nearly £38m.
This one is cheap, but maybe for good reasons:
Graham's Section
MS International (LON:MSI)
Down 5% to 975p (£157m) - Half-year Report - Graham - GREEN
There has been a lot of excitement around this stock relating to new defence contracts. Paul and I were consistently GREEN on it over the past two years (see last update in June).
As far as listed companies go, it's an eccentric with no broker forecasts and much less commentary and fanfare than other companies.
A large part of the reason for that is heavy insider ownership. Michael Bell is Chairman:
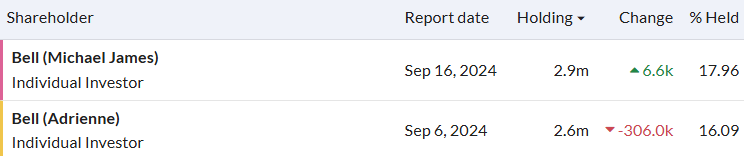
In addition to the top two names, there are other names with holdings of 10% and 7%.
In today’s interim results, Michael Bell seems a little disappointed with the financial outcome. He notes that modern accounting rules to do with revenue recognition for long-term Defence & Security contracts have impacted the figures:
As a result of winning these larger contracts, a substantial amount of ongoing work in the first half will not be recognised as revenue until either later this year or in following years, when the goods and services have transferred to the customer.
Timing of revenue will, therefore, be an increasingly significant feature going forward and, indeed, it has impacted the results for the first half. Nevertheless, the Company is making remarkable advances, even if the half year results do not fully reflect this.
The headline numbers are as follows:
Revenue down 4% to £54.7m
PBT up 14% to £8.8m
Defence & Security: MS International is “a top-quality designer and producer of naval weapon systems”, and is now gaining “a similar reputation in the much larger international land-based equipment section of the defence market”.
The facility in Norwich is being upgraded in anticipation of future business, and the property in South Carolina is also being prepared “to accommodate our projected growth”.
Forgings: there is reduced global demand for fork-arms; MSI are maintaining their market share.
Petrol Station Superstructures: UK activity remains high. Times are more challenging for the Poland-based business.
Corporate Branding: the UK operation prospers, while Netherlands/Germany business “restructures to meet subdued market conditions in the petroleum business sector”.
Outlook:
I am most encouraged with the considerable progress that we continue to make across all the divisions. This is particularly pleasing in a year of uncertainty, in terms of the political change in many of the countries we serve and, of course, movements in both interest and exchange rates.
There are some management changes - new MD and FD (internal hires).
A strategic review is nearly complete, with an update to come before the end of the financial year (April).
Graham’s view
I tend to like this company because it’s understated and clearly not trying to promote itself, while at the same time having a very long history of profits and dividends, a strong balance sheet, and a stable (even declining) share count.
While there are no official forecasts to compare with, today’s results do feel like a miss in the sense that investors have been keenly looking forward to bumper results from the Defence & Security division, and these have not materialised yet.
On the other hand, I wouldn’t dare to downgrade MSI as the results are still perfectly good in their own right: the accounts are perfectly clean and the profit margin is up on lower revenues. After-tax net income is £6.4m (H1 last year: £5.8m).
On the balance sheet there are net assets of £51m, almost fully tangible, including cash of almost £28m (H1 last year: £43m).
As pointed out in the comments section below, there is a large increase in inventories, up by over £20m year-on-year to £37.5m. This alone can account for the reduction in MSI’s cash.
The good news is that if these inventories are soon to be sold, future income statements should be very impressive indeed. The gross profit margin is currently running at 34%. So an extra £20m of inventories could in theory be sold for £30m+, leaving an additional £10m+ of gross profit behind (before the deduction of distribution/admin costs).
There are a lot of assumptions involved - who knows what the margin might be on new contracts - but I’m definitely inclined to see this inventory movement as a positive. As I’ve said before, it’s very often a good thing to see cash on the decline at growing businesses.
More generally, I reviewed the defence sector not long ago for a Stockopedia webinar with Megan, and came to the conclusion that the outlook for the sector was quite good.
MSI, while not yet producing the type of numbers we’ve been hoping for, seems to remain on a good track. So I’m staying positive on it.
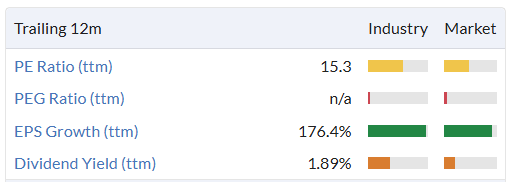
This historical PER does not adjust for the strength of the balance sheet or cash position:
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

87 comments
Not sure if the Graham and the team will see this as written a day late but I'd like to congratulate and echo what I've seen several other members comment on over the last few weeks
The coverage here has greatly improved since the departure of paul, I was a little apprehensive with his sudden departure but the team has really upped their game since then and I respect that the team seem to be listening to the subscribers and asking for input in how to best provide for us
The whole team seem active in the comments which shows to me that they generally care in the input put out to us
I'd like to extend a Hugh thumbs up from me to Graham, Megan, Mark and Roland (sorry if I've missed anyone out)
Having a larger staff taking up the workload on the boards here is definitely paying dividends for us subscribers, as we're definitely getting more output on a daily basis, whatever has went on behind closed doors I feel Ed has made the right decision and I hope to see stockopedia grow and thrive
The £295 yearly subscription is a bargain if you take into account the amount of writers contributing so we never have to go through lean spells due to illness or other arrangements effecting what any 1 writer can produce, we also have all the educational and analytical aspects etc from the site which is invaluable in helping company specific screening
Just wanted to give my feedback now the dust has settled on the whole reorganisation since Paul's departure and now having had time to digest what both parties have done since
Keep up the good work, you have a very happy subscribers here
In addition to Kier (LON:KIE) , which I hold, RM (LON:RM.) is up 10%. As far as I can tell the latter is due a trading update soon. I wonder if it has negotiated the sale of one of its three divisions?
Kier (LON:KIE) Up 9% today - there's no news so has someone kindly upgraded it?
I saw that and thought it was connected to Starmer's speech yesterday ??
Keir moved Kier?
Good spot
I missed a chance there ;-))
Not sure, others in that sector are not up much, apart from Somero Enterprises (LON:SOM). Apparently volume is high with lots of buying.
re Somero Enterprises (LON:SOM) , possibly overhang cleared (Allianz down to zero) and interesting new holder in Regent Gas (RNSs late yesterday)
Goldplat (LON:GDP) has gone into superstock ranking today, not bad for a minnow of £13mc. Value 95 and stock rank of 90
Thanks for the write up on that one Mark, nice 25% rise in 3 weeks, not too shabby!
I would suggest looking at the note on Rock Hill. 'We are also making provision at our existing, substantial and contemporary property in Rock Hill, South Carolina, to accommodate our projected growth.'
Which stock are you talking about?
Are you replying to anyone?
MS International (LON:MSI) Apologies Rusty2 - First post
No problem. It helps you put the ticker in. You can do this by typing @ then a screen will appear, start typing the ticker or name and it should appear in the dropdown menu.
MS International (LON:MSI)
How are people treating cash in their folios? My folios are split over different regions, such as UK/Europe and USA/Canada. The USA has 30% cash, if l take that out the valuation will drop and performance will go up. Is fair to have so much cash in that folio when in my real folio, it is all mixed in.
Trading212 still paying 4.90% on cash in account so happy keeping it there until a nice opportunity appears - but tend to keep fully invested with 10% or less in cash.
Yes l understand that but l was asking about in Stockopedia folios.
Hi Rusty, personally I don't use that part of Stocko's portfolios, a time waster? My broker is ii and I get interest on real cash held there.
I just want to see the performance on each folio, ie US or UK. Having so much cash in one folio is distorting the figures.
Hi Rusty2,
I don't use the portfolio functions too accurately, so I'm not so bothered by the cash contribution, but I suppose you could make a "withdrawal" transaction and remove the cash.
Then a "deposit" to add it back again, back dated. Not sure if that would work for you?
Regards,
Jon
I just want to see the performance on each folio, ie US or UK. Having so much cash in one folio is distorting the figures.
If you are using the Stocko portfolio tool, it uses Time-Weighted Return (TWR) which calculates the underlying performance of the portfolio and does not take into account the timing of any cash flows (deposits and withdrawals). What you maybe need is a portfolio tool that takes account of the timing of cash flows using Money-Weighted Return (MWR). I believe the Sharepad tool uses the Modified Dietz method that is a version of MWR.
Either way, if cash held is distorting the performance figures then there is something wrong, maybe you’re using some simplistic Rate of Return method? If you want to negate the effect of any cash then simply make a deposit before all buys and a withdrawal after all sells in the portfolio tool to keep the cash balance at 0 in the tool to give the performance only of the underlying holdings.
Thanks for your comments. By distorting l mean if the folio is fully invested in stocks then you should get the performance from the change in stock values. But if you have 50% in cash then that performance will be affected? As cash is not changing in value. So if my US shares go up 30% but l have 50% cash then that will show as 15%.
There are some issues on folios, l noticed on new folios, the chart was always wrong to start with, l was advised by Stocko that l need to add the cash deposit, the day before the stocks are added. When l changed that it impact the performance.
Thanks for your comments. By distorting l mean if the folio is fully invested in stocks then you should get the performance from the change in stock values. But if you have 50% in cash then that performance will be affected? As cash is not changing in value. So if my US shares go up 30% but l have 50% cash then that will show as 15%.
A TWR calculation should not include cash. I don’t know what Stockopedia are doing in that case. I would add and remove cash for each trade and avoid maintaining the cash holding within the portfolio tool as I suggested before. IMHO cash should be included for portfolio valuation only, not performance, unless you specifically want to see what effect holding cash has on the latter.
You should maybe build your own TWR based spreadsheet to calculate performance. I try to avoid external tools wherever possible because I don’t know what underlying assumptions have been made. It’s pretty easy to understand TWR once you get your head around the calculation for entry to a spreadsheet. It can be hard work if you trade a lot but no more so than adding each trade to a 3rd party portfolio tool. See: https://www.investopedia.com/t...
All the best, Si
Thanks.
There are critics of TMR, l saw one example where the actual trades, made a loss overall, but with TMR it showed as a profit, as the shares were in profit for a longer period than at a loss.
Do you mean TWR? That’s what Stockopedia and most fund managers use to provide performance net of cash flowing in or out of a fund/portfolio. If you know of a better way of doing it, let me know. I’m not even sure the scenario you paint is possible from a mathematical perspective if you use TWR properly because you have to value the portfolio every time cash goes in or out i.e. a buy or sell trade. So you either carry across a loss or realise a loss for a sale at below book cost. It’s not difficult.
Yes, sorry l meant TWR.
Just added some cash to my folio and the performance changed.
Something seriously wrong with some folios, just looking at one, gains 106,000, total value 237,000, performance +9.5%, should be 80.9%.
This is a very simple folio with no selling.
So there must be something wrong with the implementation, not the TWR method. I don’t trust software engineers any further than I can throw them which is why I always go back to first principles and build my own spreadsheets. I’ve never had a problem like this and I’ve been doing it for years.
If tracking your performance is so important why do you rely on some tool for which you have no idea what it’s doing under the hood or how it’s performing a simple computation? I don’t understand why you’d do that when it’s so easy to do it for yourself. Investing is not easy but you make it a lot harder for yourself if your totally reliant on someone else to tell you how you’re doing.
Anyway, enough. I was only trying to help you.
I wonder if Trump tariffs will have any impact on MS International (LON:MSI) given that the US appears to be their biggest market.
Fair point, johnsimith68 on MS International (LON:MSI) plus will demand from US fall off, given Trump's view that wars are bad for business, and obvious desire to keep out of as much as possible on his watch. Threaten but don't get too involved seems his watchwords - or were last time around and I don't see any reason to change view this time.
msiplc.com
MS International (LON:MSI) have an operation in the US which is what Trump is trying to make other companies do, so not an issue.
I read what i thought was a very apt comment on ADVFN this morning by a poster I respect and IMO has far better knowledge of the business than me, he said that he thought this morning was when shares in MSI passed from people who could not read accounts to those that could !!
I would add to that , people who did not understand the business to those that did.
Can you elaborate Helvellyn ? The shares have fallen today.
Personally I felt the results were poor and the chairmans comments almost bizarre, quoting age old accounting rules about revenue recognition, and pretending that the board was being updated when in fact they were only rearranging the deckchairs amongst the old guard.
The improvement in PBT was largely due to non- trading gains . Plus a huge increase in inventories - were these due to confirmed orders or a speculative build up in the hope of future orders ? A simple comment by the chairman could have clarified this.
MS International (LON:MSI)
It's unfair imo to suggest the derivative gains are non trading. The $ hedge was only put in place to protect margins against any FX exposure and therefore give smooth derisked profits by locking in the exchange rate when the contract was signed . The actual gain/loss can really be disregarded.
Inventories - whilst they don't break down the inventories in the interims the large increase is likely to have a large component of work in progress or finished goods (raw materials were already high at the YE). These would be partially or fully complete mounts not yet transferred to the customer.
Say you intend to send a container with eight £3m mounts to the US Navy but you've completed 5, partially completed 3 at the HYE. There could be almost £20m of future revenue sitting on the shop floor that you've already accrued say £10m of costs building. That £10m sits in Inventory. This is what MB (& Graham above) are alluding to. I suspect MSI Defence have completed the 'work' of around £55m of revenue in H1 but due to delivery schedules have only booked £35m.
‘Suspect’.
Why dont the company just confirm ?
They did in the narrative and the accounts!
For good or ill it's not handed to you on a plate at MS International (LON:MSI). No forecasts, no access to management apart from the Agm. You do have to do some homework.
MS International (LON:MSI) Defence Subsidiary
The UK in 2024 contains £22m which was destined for Ukraine.
Niox (LON:NIOX) - just drawing this to the community’s attention. Healthcare is weak globally which, in the absence of any negative company news, probably accounts for the recent drift exhibited by the name. Nevertheless, the SP has come down to a level that provided resilient support when markets dipped at the start of the year, since when the newsflow has been consistently solid. I like it at this level on a very reasonable FY25 PER of 18x (only 16x when adjusted for cash) for LDD growth, strong IP, US approvals and a pristine balance sheet. Beware the curse of BnB but this looks an attractive bid target with good prospects on a standalone basis. PT is 30% higher.
Hi BnB, I was a bit concerned about the potential impact of Trump tariffs on Niox as I believe there is a competitor in the US and, as far as I am aware, Niox's products are made in the UK. This may be a groundless concern but the type of product made by Niox is potentially a target for tariffs. However, this may actually encourage Niox to sell out to a US company so your comment about Niox being a potential bid target may well turn out to be true.
I hear you BnB but Trump and his Health Secretary Robert F Kennedy have introduced such uncertainty into the sector that in my opinion not much will happen until clarity wins out and even then under this new set up it may not be good news. I think tariffs are the lesser concern.
Hi Cantab. Great to meet you at Mello. I neglected to ask then: do you have a Cambridge affiliation of some sort? I’m visiting my son near there today - he is GK for the Cambridge handball team - and my daughter coached the Blues boxing squad. In response to your point, you might be correct, but analysts have concluded that MedTech is the area of Healthcare that is least likely to be affected by the new administration, which you can see in the healthy resilience of sector stocks. It’s Pharma that is in the crosshairs. I have a number of MedTech names and they are broadly unmoved. So I believe the drift in Niox (LON:NIOX) is idiosyncratic and a good entry. For which I may be punished by the market! Who knows?
Hi BnB you too. Yes I live in Great Shelford on the edge of Cambridge. Still yearn for the Dales mind!! Be delighted to buy you a beer any time you are down supporting your obviously talented offspring.
.
Paul and I were consistently GREEN on it over the past two years
Has there been any work commenced to backdate the google sheet to show historic ratings? Would be great to see trends on analysis for a company, would hold more weight for me if your view has been consistently green
That job is on me JSchoffer, I need to set aside time to do it. G
What we said on MSI:
10/7/2023 - Paul - GREEN - 540p - FY 4/2023 results subdued, due to large order slipping past year end. But large order book suggests FY 4/2024 should be excellent.
3/10/2023 - Paul - GREEN - 780p - Flurry of large military contracts won. Mgt say “significant upwards step change” in performance underway. Exciting.
12/12/2023 - Graham - GREEN - 882p - Strong H1 results. Not overvalued despite big price rise.
27/6/2024 - Paul - GREEN - 1100p
Carclo (LON:CAR)
I see this is on your backlog list.
I looked at this as it was thrown up using Ed's Clearest Trend screen.
Yesterday's interims show net debt excl. leases £16.8m. With the MCap £23.4m this is not my type of investment, especially if you then take in the pension liability of £38m.
Outlook - increasing confidence in meeting full year expectations. If so why was SP down 15.8% on day?
As it’s a quiet Friday, I wonder if I can ask a question regarding portfolio tracking. What software are people using to track their investment portfolios in equities, funds, gilts etc?
I’ve been using the Folios in Stockopedia for the last few years, but I’m finding this increasingly limiting as it doesn’t recognise a number of funds and gilts. I’d also like to be able to view my investments in aggregate (ie sum of the various Folios I’ve got (where each represents various ISAs, SIPPs etc) and benchmark overall performance against an index Total Return (also not available in Stockopedia).
I’m currently trialing Sharepad which covers these portfolio needs pretty well, but obviously there is a lot of overlap with Stockopedia on the company analysis side of things and I’d rather not be paying twice for this. I also much prefer Stockopedia’s approach to the analysis side of things, so I’m reluctant to give up on this. Still, I really don’t want to be paying for two subscriptions that overlap so much.
The other option is use a spreadsheet, but this takes away from some of the functionality (benchmarking, portfolio analysis etc) and also takes more effort to maintain.
In an ideal world Stockopedia would improve the functionality of their Folios to enable all of this. Not sure if there are any plans to move in this direction and improve the Folio functionality?
I have asked about this before. Stockopedia can stick to equities, but it would nice if they also incorporated the prices of funds etc. I end up monitoring my funds via IC or the platform they are on.
In addition to my Stockopedia portfolios I update a spreadsheet every evening. This allows me to track dividends received, and also to maintain a trailing stop loss which I consider an essential part of investing. This only takes 5 minutes or so, and the discipline of typing in a share price keeps me aware of the current situation with my 25 or so shares.
How accurate are Stocko folios? I have had problems in the past that required Stocko to adjust. Also the performance chart does not tie up the movement on the previous day. Stocko use Time weighted which is not considered as accurate as money weighted.
What do use instead Rusty2?
I don't but considering other options. Spreadsheets would take too much time. Did try google sheets but it was not accurate.
Every few weeks I check the total value of the shares in my spreadsheet (updated from the HL web site) against the total value in my Stockopedia portfolio. Occasionally a volatile share such as Warpaint London (LON:W7L) will show a slightly different value, but nothing significant.
On a weekly basis I download from LSE onto my spreadsheet. Important thing is to do whatever you do on a consistent basis
Have you tried SimplyWallStreet?
It is less expensive than some. I use both Stocko and Simply because I like Simply's DCF valuation model.
Thanks - I did come across this on my recent search for options, but perhaps was too quick to dismiss it as I assumed it was focussed more on US equities and US investors. Will take another look.
Good points, it would be really helpful if the portfolios were improved in line with sharepad (which I note also adds dividends automatically). On a related note does anyone understand how the stocko portfolio performance tab deals with dividends? I add dividend payments regularly, and clearly this alters the valuation, but on the 'performance' tab it is not clear to me they make a difference. I am aware the comparison index does not include dividends, which makes it perhaps a little pointless (surely total returns is all that matters).
Great thread this. If you have an HL account you can set up Fund portfolios in 'watchlists' and run any number of different portfolios. The Stocko portfolio for shares is not perfect but is good - but there will always be glitches to keep you on your toes - the one extra feature I would like is to be able to monitor the performance of the portfolio for the past 12 months - rather than from purchase - which may have been years ago.
With a couple of my Fund holdings - I take the Top Ten list and create a portfolio on Stocko. It not of course precise but gives a good indication of what's going on.
I'm becoming increasingly nervous of the UK stock market - the price movements are just crazy - up 15% one day down 30% the next so looking more to WW funds
Hi Man of Steel. I don't know if it is helpful to state but I use Advfn for prices and stock lists interested in. Stockopedia for analysis and admin is done by Hargreaves Lansdown including dealing (Don't get best prices but reliable), valuation etc. Run my own performance against inflation and bank account rates so maybe a lot simpler than what you are trying to do.
Thanks - I have used ADVFN a long time ago, so perhaps worth revisiting to see how things work now.
I might be trying to over analyse the performance of my portfolio, but one of things I enjoy most about investing is benchmarking myself. I've traditionally used the FTSE All Share on the Stockopedia Folios to do this and was feeling reasonably happy about my performance. When I then uploaded my portfolio history into Sharepad and compared into the FTSE All Share Total Returns index I was a little disappointed to see that I was only achieving a return slightly ahead of the index. It's this sort of level of detail that I'm missing from the Folios that I really value as it makes me think about the types of investments that I make and how I allocate my capital across different asset classes, segments, markets, companies etc.
If you have Sharepad, why not just use that?
The main reason I'm trialing Sharepad (at £35/month) is for the portfolio management capability. If I could get this functionality somewhere else I wouldn't subscribe to Sharepad.
I manage both my SIPP and ISA accounts using this free software https://www.portfolio-performa...
I reconcile my accounts monthly. Prices for stocks and funds are automatically updated in real time. You do need to declare dividends, management monthly fees and interest earned but thats 10 minutes a month. It therefore gives true performance
You can set up as many portfolios as you want, either in one file or separate . I run my live file for all real and run separate files for watchlist portfolios
Looks good. Can l download my Stocko folios to it or do l need to set them up from scratch ?
Hi Rusty2 it has numerous import options,
I did try them but did not work. Kept saying format not recognised, l'm using an iPad. Which option should l try?
I used the csv excel version, it wasn't perfect however! (That was a while ago). There is quite a good on line help section - Try this one for csv import (or search how to's) https://forum.portfolio-perfor...
OK, thanks l will give it a go.
Still does not work, something about not binary.
I am an intermittent subscriber and use Stockopedia primarily for information gathering. I am retired so this is a hobby with a focus on capital preservation and dividend income. My background is IT and I have a homegrown Excel spreadsheet (an elderly Excel 'cos I have an elderly MacOS). A few years ago I opened an online broker account with £10 so I could use their online portfolios and 'real time' pricing information. This gives me a real-time valuation of my ISA portfolios which I use to manually update the Excel spreadsheet weekly. A great spreadsheet time saver is a quick total column where I enter the current valuations of each ISA directly (rather than updating individual prices), letting me have a quick near real-time overview.
My spreadsheet has a control panel giving me an overall summary of ISA and non-ISA valuations. A master table summarising holdings, purchase cost and dividends paid along with a calendar showing which months each dividend is due and how much those are expected to be. This lets me derive various statistics about the current portfolios. I also have various tabs providing income forecasts.
My spreadsheet was grown over the years on a need to know basis, if I needed a particular feature then I built it for myself. I would commend this approach if you have a programming background because Excel is a programming environment but one in which debugging and testing is especially difficult; easy to use doesn't mean easy to get right.
I use Excel, which has one stock per row. This records the value of purchases and sales, my holding, the latest price and value, dividends received, current yield and the account in which it is held (mine or my spouse, isa or not) so I can calculate approximate CGT liability where applicable. I also show the weighting within my portfolio.
Although some manual updating is required, the most frequent need is to update current prices which is easily solved using a HL watchlist which replicates my portfolio. I can download all the prices at any point, sort by ticker into alphabetic order to match my portfolio and then copy and paste into my spreadsheet. This watchlist also enables me to see what is happening to each of my holdings whenever I want, even when logged out from my accounts.
I use the spreadsheet to calculate my running profit or loss for the year by including current cash in the various accounts and any withdrawals or cash injections during the course of the year. I can calculate my total dividends from expected yields and separate that which will be taxed from that which is in an ISA.
It matters not whether my stock is a fund, an equity or a gilt or other bond as HL provide prices on whatever is in my portfolio.
Yes, it does take time to create a spreadsheet which does what you need it to do but that's the beauty of using excel. You can add a new feature whenever you want or make it as simple as you like. If you like the format of a commercially available tracker but not the cost or some features, you can replicate it in Excel and customise to your own needs.
Over the many years I have been investing and keeping track of quite a large number of holdings, I have learned that keeping accurate records is worthwhile. I also maintain a separate but linked spreadsheet of each holding which records the date and nature of each transaction (purchase, sale, quantity of stock involved and dividends). The linking facility picks up the current stock price from my other spreadsheet although the formula for this is quite complex and requires some perseverance to create one that works reliably. Excel helps by offering the rules for the =LOOKUP formulae which allows you to copy a cell value from another spreadsheet.
Each year I create a new portfolio spreadsheet, by copying last years and zeroing those cells which start from scratch on the 1st of January.
Re: Folio management
I've been banging on about folio management tools for years. It would be lovely to analyse changes in value / sector diversification etc across a group of portfolios rather than only one portfolio at a time. I first suggested this way back on the old site (oh how I miss that, but then as they say nostalgia isn't what it used to be).
I use a naff spreadsheet but can't be bothered to add the features I need, mainly because I'm retired so don't have the time, I would rather be walking the dales than doing spreadsheets.
I think I might have a look at Sharepad, but also have an ingrained aversion to paying two subs for what one should do. It'd have to have good stock analysis too. I did use their old PC software last century, so I'm not totally unfamiliar with their stuff. Back then Stockopedia had the edge so I switched.
Also thanks to the team here for great coverage.
LT
Hi, I find that the only way to measure performance in exactly the way that I wish to measure it, is to use a spreadsheet. It's generally a more flexible approach than using anybody else's software. That way you can benchmark against any indices that you want. At the end of each trading day, I just enter the Stocko portfolio total value into the spreadsheet, along with the index values. I always keep the Stocko value of cash in the folio at zero, so that the cash is not distorting my returns. For instance, I have held no shares for a few months, so the Stocko portfolio value is zero. I don't include dividends in the calculation because my strategy is mostly about making capital gains.
Improved Offer at 23p in Cash for National World (LON:NWOR) from Media Concierge. I hold.
Good update from Likewise (LON:LIKE) in contrast to Headlam (LON:HEAD)
MS International (LON:MSI)
I am not sure how the rest of the market will take this mornings H125 results, but as part of it I see them in a very positive light. Increased PBT on slightly reduced revenue, a drop in cash due to increase of stock and work in progress but the fact management have increased interim dividend by such a large percentage with less cash in hand gives me every confidence in the company's prospects.
My only concern is what is the cause of the big increase in inventory? Is that WIP (work in progress)?
The Chairs very positive write up does suggest they are working towards delivery of a significant Inc in revenues which would suggest wip Inc. I am far more positive on these results than the opening market.
MS International (LON:MSI)
I would agree that it is WIP which should easily mean 100p EPS for FY25 which gives a cash adjusted PE of less than 8 and the very likely outcome of the business being sold in the not too distant future.
HI Helvellyn
Re MS International (LON:MSI) yes, the inventory build is what the Chairman referred to around the longer cycle of orders in defence. So expect these to effectively unwind over H2 and into next year. Those inventories turn back into cash.
Given the value of those inventories (we which will be held at cost rather than sales price) then I think we can easily see 100p EPS by year end and considerably more next year. They clearly have been in a build up phase over H1 and still managed 40p.
Cash is 200p so we are looking at a cash adj PER of 8 and I reckon closer to 6 in the next year or two. That just seems fundamentally way undervalued for what is now essentially a growth business in the area of defence where countries are increasing spend as a proportion of GDP.
Don’t really understand investors reactions - the absence of research doesn’t help I suppose as too many investors just don’t do any proper research around where companies are positioned - they just trade headlines.
Anyway I hold and am generally very happy - I look forward to a. Significant re-rating at some point. I think they should trade closer to other defence peers at around 15* PER but who knows.
What are the proportions of the business between the exciting defence etc and the unexciting rest of the business? Help, please - being lazy at the moment because of family issues and shortage of time to research.
Mention of takeover possibilities in comments elsewhere. Really? with the share concentration among family members? At first sight I doubt it, but am willing to be convinced otherwise. More likely to be taken private? Last comment spoken with the pain of someone who has been burned by a company taken private at well below a previous offered price for a takeover!
Help gratefully received from such fine contributors to this site.
Graham and team, if you get a chance to look at Trufin (LON:TRU) who gave their second upgrade yesterday and director buying announced today. They seem to have a successful game Balatro which is driving growth. A It may be a bit small for your reports but a potentially interesting play.
Greyster
Hi greyster, I've added that to the backlog table but can't guarantee we will get around to covering it! Thanks. G
Hi Mark would be really interested in Carclo (LON:CAR) review of results if you are able today. Board sounded confident but investors ran for the hills. Seemed overdone to me. Thanks. DD
Sorry, I ran out of time to look at that one. Perhaps next week will be quieter and I’ll get chance to look at some of the backlog of which this is high up my list.
As usual the results from MS International (LON:MSI) were unheralded, and untainted by PR consultants. They were probably written by stylus on papyrus and brought down to London by coach & horses.
But they are reassuring for holders. Cash flow not great, see build up in inventories, but that seems to be just a timing issue. Defence business going great guns, so to speak, and even the PFS division enjoying strong demand. Dividend increase is proof of board confidence. Surprised if FY forecasts are not edged up. I hold.
Thanks Grumpy5 - that made me laugh.
I am also a holder of MS International (LON:MSI) and my quick skim of the results was reassuring. However I don't think they do forecasts, or at least there is nothing on stockopedia.
Very nice comment grumpy5. But I'm not sure if there are any forecasts to be edged up. This is a do-your-own-forecasts type of stock. G