Daily Stock Market Report (Fri 6 June 2025) - PINE, SDI, TRN, MHA, AVCT, BGO

Good morning! And welcome to Friday's report.
The Agenda is complete.
2pm: wrapping up the report there, have a nice weekend everyone!
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
AstraZeneca (LON:AZN) (£166bn) | EU approval for treatment of adult patients with previously untreated CLL (leukaemia). | ||
Canal+ SA (LON:CAN) (£1.99bn) | Confirmed 2025 revenue and EBITA outlook. 2025 cash flow from operations to exceed €500m. | ||
Assura (LON:AGR) (£1.57bn) | Meetings to implement Cash Offer adjourned until further notice. Reciprocal due diligence ongoing. | ||
Trainline (LON:TRN) (£1.17bn) | SP +3% Trainline selected as a technology supplier to support digital pay-as-you-go trials. This is "a strategic opportunity to to demonstrate the benefits of [TRN's] in-app solution in a live environment", ahead of pay-as-you-go's potential rollout around the UK. Another announcement will follow upon formal contract signing. | AMBER/GREEN (Graham) [no section below] The potential financial consequences of this development aren't spelled out - and I imagine they would be very difficult to predict. But if digital pay-as-you-go is rolled out around the UK, then clearly Trainline will want to be at at the heart of this important change in the sector. I've long admired the company's quality metrics and I'm happy to upgrade it to AMBER/GREEN today, although I suspect that my fellow writers might disagree with this stance. The shares continue to trade below their £3.50 IPO price (2019) and have never paid a dividend, but the company has made significant financial progress over the past six years and consensus estimates suggest that its profits will continue to grow. At a P/E multiple of 13x, I think it offers some quality and value. | |
Pinewood Technologies (LON:PINE) (£402m) | Buys 51% interest in US JV from Lithia Motors for $76.5m. New shares to be issued at 386.5p. | AMBER/GREEN (Graham) This is a High Flyer - an interesting growth story where the growth opportunity has just increased thanks to the buyout of its partners in North America. Not only will Pinewood shareholders enjoy the full benefit of their progress across the pond, but that progress should come more easily now that US auto dealers will not be buying Pinewood products directly from a competitor. | |
MHA (LON:MHA) (£296m) | SP +9% Trade strongly in H2 of FY Mar 25. Rev growth, margins, cash in line. Adj. EBITDA ahead. This is a very recent IPO, floating in April at 100p (see here). | AMBER (Graham) [no section below] I like to stay neutral on recent IPOs, due to the risk of overvaluation and hidden risks. I'd also bear in mind the general point that forecasts put out prior to IPO can easily be engineered to create an ahead-of-expectations "surprise" shortly thereafter. So personally I wouldn't get too enthusiastic about this one just yet. Let's see how much of the adjusted EBITDA gets converted into real, clean profits now that they've moved away from an LLP structure. | |
Intuitive Investments (LON:IIG) (£251m) | Positive momentum for Hui10, Chinese lottery tech company. NAV/share 153.2p (SP:122.5p). | ||
Camellia (LON:CAM) (£143m) | 215k shares were validly tendered (7.8% of shares in issue), less than max allowed. £11.6m value. | ||
abrdn Diversified Income and Growth (LON:ADIG) (£136m) | Objective: orderly realisation of assets, return of cash. NAV ps 68.42p as of 31st March 2025. | ||
Avacta (LON:AVCT) (£133m) | Phase 2 trials planned for H1 2026. Cash £17m (April), runway to Q1 2026. Pre-tax continuing losses for 2024 were £29m. Material uncertainty. | RED (Graham) [no section below] It's so very late to publish results for FY Dec 2024. Revenues so far are de minimis. The company's first drug program has ongoing phase 1 trials, with phase 2 planned for H1 2026. The cash runway goes as far as Q1 2026 and the footnotes in these results state: "...the Group and the Parent Company are dependent on raising funds to advance their key projects and investments to remain cash positive during the going concern period. There are currently no agreements in place and there is no certainty that funds will be raised within the appropriate timeframe." As the existing equity is unsafe, this is an automatic RED. | |
SDI (LON:SDI) (£74m) | £4.75m. Designer/manf’r of furnace systems for advanced material processing and testing. | AMBER/GREEN (Graham) A nice little bolt-on acquisition at a modest earnings multiple; this is the core of SDI's strategy. Opens new markets to the group and creates new cross-selling opportunities. Broker estimates have been adjusted higher. | |
Anexo (LON:ANX) (£72m) | Revenue -1% (£141.9m). PBT -35.7% (£14.8m). Trading since the year end has been in line. | ||
Bango (LON:BGO) (£72m) | 2024 loss $3.7m. Adj. EBITDA for 2025 in line. Modest increase of $1m vs. consensus for FY26. | AMBER/RED (Graham) [no section below] Another very late set of results, which I take as a red flag. The company again posts an operating loss, albeit a smaller one than the prior year, while the headline results rely very heavily on adjustments - another red flag for me. Net debt finished the year at $1.8m but as that was nearly six months ago it doesn't seem very relevant now. The company's debt facilities have since been restructured, as announced in a separate RNS. I am going to downgrade this to AMBER/RED as I note that Singer are now forecasting that the company will have net debt (excluding leases) of $10.6m at the end of 2025. This was previously forecast to be only $1.6m. Given the shakiness of the company's financial performance, I would not be comfortable investing in its equity while it manages outstanding debts. |
Our rating system - the last six months
While I've been away from writing duties, one of my projects has been to update the spreadsheet that accompanies this report.
The overall headline is that we've looked at 549 different stocks in the last six months, and more than half of these have been looked at more than once.
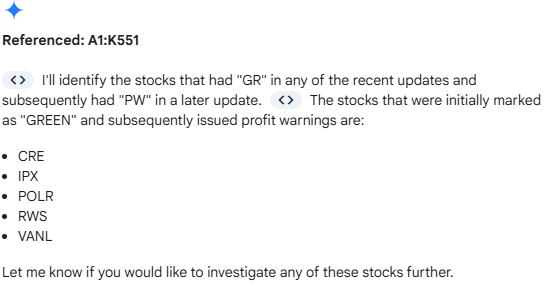
Something I particularly wanted to investigate was the companies that we were fully "GREEN" on, that subsequently issued profit warnings.
There were only five of these:
- Conduit Holdings (LON:CRE)
- Impax Asset Management (LON:IPX) (I'm long this one)
- Polar Capital Holdings (LON:POLR)
- RWS Holdings (LON:RWS)
- Van Elle Holdings (LON:VANL)
My main finding is that despite their profit warnings, these stocks haven't performed all that badly. Or more specifically:
Conduit Holdings (LON:CRE) - we were GREEN on this on 19th February. Share price at the time: 406p. It subsequently issued a profit warning on 31st March. Its current share price: 386p. So despite a profit warning, it is only down by 5% since we were last GREEN on it.
Doing the same for the other stocks that issued profit warnings:
Impax Asset Management (LON:IPX) is up 9% since we were last GREEN on it, despite issuing a profit warning since then.
Polar Capital Holdings (LON:POLR) is down 10% since we were last GREEN on it
RWS Holdings (LON:RWS) is the main casualty, down 55% since we were last GREEN on it.
Van Elle Holdings (LON:VANL) is down 3% since we were last GREEN on it.
As you can tell, the point of my analysis is not to say that companies we are GREEN on can't issue profit warnings - they most certainly can!
My point is that most of these companies have survived their profit warnings really well, which I think can broadly be attributed to their balance sheet strength and their fundamental cheapness when we were initially GREEN on them. More work is needed. I'm eager to learn more about how our rating system is performing!
Google's AI assistant, Gemini, assisted me in this. It required a lot of coaxing but once it understood what I wanted, it did a fine job!
Graham's Section
Pinewood Technologies (LON:PINE)
Up 13% to 451.7p (£454m) - Acquisition of Lithia’s Stake in North American JV - Graham - AMBER/GREEN
Formerly the car dealership group Pendragon, this is now purely the software business Pinewood.
Some interesting news this morning as it announces the buyout of its joint venture partner in North America.
The price is $76.5m (about £56.5m) for the entire 51% stake held by Lithia Motors ($LAD).
This does mean some dilution, as it’s going to be funded by the issuance of 14.6m shares at 386.5p.
Against 100 million shares outstanding, that’s 15% dilution.
In further news:
Pinewood.AI is also delighted to announce that, subject to completion of the Acquisition ("Completion"), it will enter into a five year contract with Lithia to roll-out Pinewood.AI's software to all of Lithia's current and future sites across the US and Canada by the end of 2028 at the latest…
By the end of 2028, Pinewood anticipates $60m of annual revenue from Lithia in North America, including revenue from both their current product suite (expected to generate $40m) and additional applications.
Rationale: among many other reasons, it is thought that this deal will remove “the perceived ‘competitor overhang’” as rival dealership groups may be more willing to use software that is not so directly backed by their competitor, Lithia.
This mirrors the separation of Pinewood from Pendragon in the UK.
However, Lithia will remain “a key customer and committed long-term minority strategic shareholder”. I don’t think that any change has been signalled when it comes to Lithia 22% ownership of Pinewood itself. The change only relates to their ownership of the North American JV.
CEO comment:
"We are delighted to have reached an agreement with Lithia to acquire the majority stake of the North America joint venture. The US and Canada are central to our growth strategy, and through the Joint Venture, we have made significant progress towards commercialising the Pinewood.AI platform for the North American market. Assuming full control of the Joint Venture will strengthen our ability to fully capitalise on the opportunities available in a key strategic growth market…
I would like to take this opportunity to thank Lithia for their partnership in the joint venture and we look forward to working with them as a key customer long into the future."
Trading update - contained within today’s announcement is a reassuring update.
Trading in the current year has continued positively, and the directors of Pinewood.AI (the "Directors") remain highly confident in the opportunities ahead for Pinewood.AI.
Graham’s view
I understand that Pinewood shareholders are very excited about their North American opportunity - and so it makes sense that they would be excited about having 100% ownership of it. Accepting a modest amount of dilution for this makes good sense, in my view.
The deal seems to make long-term success in North America more likely and it doubles Pinewood’s ownership interest in that success.
So I’m finding very little to dislike in this news.
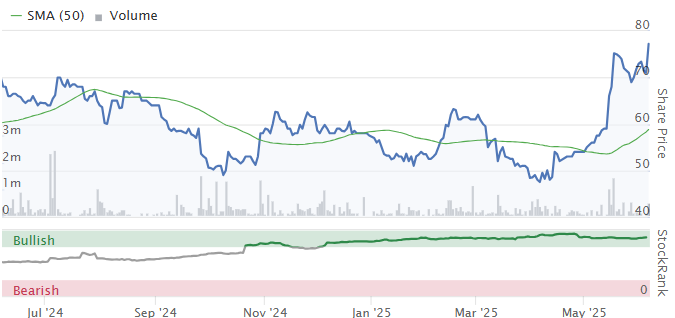
We last covered the stock in April when I upgraded my stance to AMBER/GREEN. Perhaps it’s worth another upgrade today, but bear in mind that you don’t get a cheap multiple here - you are buying into an interesting growth story.
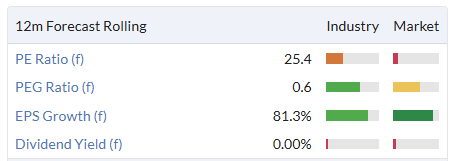
I might be a little slow to act here but for now the AMBER/GREEN stance continues to make sense to me. For growth-oriented investors, I would say that it’s certainly worth a closer look.
SDI (LON:SDI)
Up 9% to 77.25p (£81m) - Acquisition of Severn Thermal Solutions - Graham - AMBER/GREEN
We have news of a fresh acquisition from this buy and build group.
The new asset is Severn Thermal Solutions Ltd, which is “a designer and manufacturer of high temperature furnace systems and environmental chambers for advanced material processing and testing”.
The price: £4.75m, plus SDI will pay for the cash acquired of £3.6m.
SDI is still small enough that deals of this size can have the potential to move the needle for them.
Severn is said to have a “scientific niche in a growing market, blue-chip customer base and strong international revenues”. It gives SDI “expansion into the controlled environment market” with new, intra-group cross-selling opportunities.
Severn’s financial performance last year:
For the year ended 30 September 2024, Severn delivered revenue of £2.42m, adjusted EBIT of £0.88m (adjusted to reflect Severn's cost base as part of the enlarged Group) and a reported EBIT of £1.06m (all unaudited).
So it looks like SDI are paying 5x the EBIT that Severn would have achieved as part of SDI.
Estimates: the acquisition is earnings accretive and Cavendish have updated their forecasts for FY April 2026.
Forecast revenue up £2m to £75.4m.
Adj. EBITDA up £0.7m to £14.2m.
Adj. PBT up £0.4m to £9.8m (there are higher interest costs).
Graham’s view
The market cap is up by about £7m which is certainly a bullish response to the announcement of a £5m debt-funded acquisition. But SDI shares weren’t priced very aggressively to begin with:
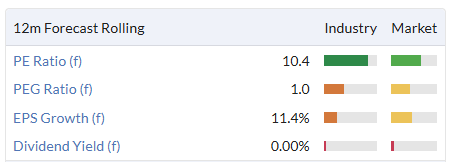
I was AMBER/GREEN on this in May (see here) and am happy to retain that stance again today. The main negative for me has been the lack of organic growth, but if the company can successfully add bolt-on growth - which is its primary strategy, after all - then why complain?
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

51 comments
After nearly four decades of investing, I ought to be immune to surprise—but the sheer depth of blind faith some private investors place in @Avacta still manages to raise an eyebrow. I wouldn’t mind so much if the Company didn’t have a track record littered with bluster, aggressive dilution, and a litany of RNS announcements that, being charitable, veer toward the misleading. Yet, social media is awash with die-hard believers, many of whom appear to have staked every last penny on this outfit, cheerleading it as though fundamentals were an optional extra.
Yes, I’ve never quite seen anything like it. There are some X commentators very heavily invested, or so they say, and a load of private investors with their whole portfolio stuck in it. As far as stories go it’s one of the best - we can stop the pain of chemo and cancer and help people live longer. It’s an emotional story which has drawn investors in. on the other hand, it’s at the level it was at in 2020 and it went on 1200% run, so it’s worth keeping an eye on. Just don’t fall for the marketing.
Graham; Thanks for your comprehensive reports and todays excellent idea to revisit past greens to assess post report latter performance.
Extremely help full , all of this helps me to become a much improved investor.
You're welcome, Funderstruck - and it was nice to meet you yesterday! All the best.
Just want to say a quick thanks to all the team over Mello- Graham, Ed- who took time to speak + engage with subscribers.
Was lovely to meet you in person and thanks again for the comments and wisdom.
As a holder of Conduit Holdings (LON:CRE) I'd point out that they issued a profit warning mainly because of the hit they took when Los Angeles burned down. So GREEN but a bit blackened around the edges.
deleted
deleted
Great example of how AI can be used to assist in the investment process. It's definitely not a tool to replace human intelligence, but it can definitely help to identify trends and patterns which hopefully make human intelligence more useful. Thanks for sharing!
Agreed - would love to see some articles on how AI can be used to assist the investment process. Have only really used it for simple queries to help with company research, but sure there's a lot more it can be used for.
Bouden54
Hi, I use AI quite a bit for investment research. For me one important aspect is to be quite pointed in how to define the prompt to be researched. For example I often use the AIs to assess how company X compares with company Y (or even across multiple companies).
By way of an example I submitted this into GROK today ....
Can you examine the similarities and differences between Archer Aviation In. (ARCH) versus Joby Aviation Inc. (JOBY). Differences i the products, the services they are proposing, the extent to which they have reached commercial services, any major contracts, their key partners, any positive or negative news feeds in past 12 months (or so)
I requested GROK to do a DeepSearch mode on this. Grok looked at 52 sources for me in less than 60 secs. and provided a well formatted report.
You could just cut and paste my prompt into your AI and see what it does for you.
Regards
Howard
Have you spelled the first company correctly? Should it be Inc. rather than In.?
Hi ridavies
Yes you are correct should be Inc. ... but the AI can work with my typo
Regards
Howard
Bango (LON:BGO) (I hold) Increasingly looking like a company which has a great product set yet, perhaps because it sells to much larger organisations who drive a hard bargain, is finding it difficult, if not impossible, to generate profitability.
That's the problem with Bango (LON:BGO) - I agree with the strong product, DVM. As well the moat they have built around the Transactions side of the business. I used to work in Telco, so am a little familiar with the ecosystem.
I do think their margins will grow strongly in the coming years, as Retention Rate stays >100% as clients mature, DVM penetrated deeper into their (Telco) customer bases, and they keep signing on more new Telco clients.
However, they have a mess of a debt, loans, warrants, etc. If they just sort out that side, and stick to cashflow neutral for a year or two while having rapid top-line growth and client number growth, the shares would re-rate to be a tech darling....
On my watchlist to add at some point. The time will come when the balance sheet is in a better place, and this will soar. Hopefully before the full margin momentum becomes apparent in the results.
Market reacting well to acquisition by SDI (LON:SDI) of Severn Thermal Solutions.
Cavendish have upped their price target:
We upgrade our FY26E EPS by 3.8% to 7.1p. We raise our target price in line with earnings to 140p, with the shares currently trading at an unwarranted 45% discount to its peers.
Kefi Gold and Copper, I'm not exactly cheered up by the full year report today as I hold well underwater and hoping it doesn't turn out to have the Contracter problems of Hummingbird as we know where that ended. If you're not getting gold out of the ground you are not winning!
Filtronic (LON:FTC) coming off the boil this morning, presumably on the news that the bromance between Agent Orange and Musk has ruptured spectacularly, with the former threatening to cut federal spending with Musk, therefore presumably impacting Starlink.
The worry kicked in last night therefore I set a stop loss of 134p against a closing price of 144p with H/L. I sat and watched this morning as the share went into freefall while my stop loss just sat there. Eventually I was informed that it was executed at 123p, doubling my losses. If a service offered is not fit for purpose, why is it offered? Another lesson learned the hard way.
That's the problem with small caps in early morning trading when the price action is chaos - there are no guarantees. IMO you either need to just accept you want out and take what you end up getting or ride it out till it settles and you are offered a set price. A few years ago I got caught with similar thing on another stock - was quoted price, though with caveat "price can't be guaranteed"...lo and behold what I got was a good bit below.
I don't spreadbet but believe it may be an alternative if you want a guaranteed stop.
I have found stop losses do not trigger at HL OFTEN
Stop loss price is not guaranteed. You would be in a queue of sellers. Probably no market to buy at 134p, so executed at a lower price. I found auto stop losses a waste of time, in the UK markets. Often taken out and then share price bounces. I'm sure market makers lower the price to trigger stop losses, so they can get shares cheap. Bad news shares are marked down in early trading, often they bounce back during the day, depends on the news.
You can sell at 132p now.
I don't use stop loss as a lot of the control over the sale process has been signed away.
I think that a stop loss has a place for large caps where you have a made a strategic mistake on the long term prospects of the stock. Plenty of liquidity would mean that the stop loss should be executed at about price.
I never put limit or stop loss orders at the open with HL. Always try to deal sharp at 8am. Just keep trying (smaller quantities if needed) if no quotes are available. I've managed to get better prices most of the time.
Seriously, don't bother with stops and limit with HL at the open!
Hello psin - and others who presumably speak the same language. Please indicate what share you are talking about.
The market makers software see your stop losses and actively try and trigger them. good to use them but trigger them manually.
I can categorically tell you that that is not true.
Morning Graham,
As a long tome holder of Van Elle Holdings (LON:VANL) and Polar Capital Holdings (LON:POLR) I would welcome any further views that you and your colleagues may have.
My personal and of course biased view that they will both recover. Van Elle Holdings (LON:VANL) will, I think but clearly don't know end up being acquired. I can't see Harwood and Gyllenhammer letting it continue to flounder on attractive metrics despite the profit warnings. The obvious suitor is Keller (LON:KLR) . Aa always patience is required, but it would be nice for my thesis to be proved right. I have a blended purchase price of 38p, so happy to sit on my hands.
Polar Capital Holdings (LON:POLR) is my gateway into technology, about which I know little. I listened to a very interesting interview with the erudite Ben Rogoff, manager of Polar Capital Technology Trust (LON:PCT) about AI. It is available on the Money Makers podcast.
Polar Capital Holdings (LON:POLR) is a well managed asset manger with some interesting an well performing funds. It has substantial cash on the balance sheet, like many of its peer group and is able to pay a handsome dividend at the current price. I also like the fact that Harwood are long term holders, although nobody gets it right all the time, not even Christopher Mills. I am currently some 25% down on my purchase price, but most of this has been recovered through dividends.
All the best
Polar Capital Holdings (LON:POLR) is a big holding of mine. On the plus side it has a very tasty dividend which they've managed to maintain so far due to their big cash balance, and they have not seen the level of net outflows that other asset managers have seen.
On the downside it had a nasty fall in assets under management when it last reported for the quarter ending end of March 2025. There was then the big Trump sell-off.
To try and get an advantage in the market I've started keeping a regular eye on the performance of Polar Capital Holdings (LON:POLR)'s funds on a regular basis - which are the bulk of its assets. They are easy to look up e.g. morningstar regularly updates on the fund sizes. I have not been regularly looking at the sizes of the Trusts.
Despite the big rebound in the markets since April, as of 28 May (the latest data I last accessed) I estimated their overall funds under management had only increased around 3.3% since the end of March figures. Not exactly a gigantic rebound and most of the lag seems to be in its healthcare funds - I assume reflecting concerns about US tariffs and policy on pharmaceuticals. (I stress again I have not recently reviewed Trust performance).
I'm still very positive on POLR. It's been well managed and high performing and seems to have been one of the few asset managers that has bucked the trend of net outflows in recent years. But I think it's worth just keeping an eye on current fund performance versus broker expectations (and perhaps currently more optimistic market expectations!) for FY26 in case of risk of a miss.
Is there any plan to add the colour coding into the Stockopedia filtering system? It would be very interesting to be able to combine high stock rank with colour coding (without having to manually check). Also does anyone fancy doing a back test analysis? (High SR plus green)
If you do, here's a plea to use blue rather than green. For the 1 in 7 males with R/G colour blindness, conventional R/G coding, particularly on screens, doesn't help...
Rights and Issues Investment Trust (LON:RIII) is worth a look at current levels for anyone interested.
It holds a fairly concentrated portfolio of UK small caps, including many widely-held Stocko favourites, and has dropped to a 20% discount on NAV despite the entire portfolio being liquid listed holdings that are easy to mark to market value. If you had a spare £100m lying around you could buy the whole thing and liquidate all the holdings tomorrow for a quick and easy profit of about £15 million after factoring in a few million for transaction costs etc. without even waiting for the holdings to rise in value.
Renold (LON:RNO) makes up almost 10% of the holdings and as most of you will know this is currently the subject of two bids - both markedly higher than current share price - so if one of these goes through this will leave RIII with a huge chunk of cash and should also help the discount to narrow. Several of the other companies held (including Jet2 (LON:JET2) and Macfarlane (LON:MACF) ) are ones I held or was thinking of holding anyway (though of course direct holdings don't get the benefit of the '20% off' discount that you get with this trust) and several others are now looking cheap and good value after some recent issues and share price falls, making now appear quite an opportune moment to get into this. New management seem sensible and are currently on a bit of an investor marketing push to get the message out there about their approach and to try to bring this one back onto radars as it seems to have been largely forgotten about (and may perhaps have been suffering from its historical name which is now nothing to do with what it does - they recently decided to keep this for historical/nostalgic reasons but to instead improve the marketing to drive down the discount). It has a little spread of about 3% or so (less than headline once you actually get broker quotes) but given the quality holdings and the discount this looks OK as long as you are not planning on short term trading it.
Thanks for the write up and agree they look well run but I guess my question is given most of their investments are public companies what do I gain by having them buy the shares when i can do so myself and avoid all the fees they charge?
The only benefit would be if the discount were to tighten - otherwise I agree not much point holding when you can buy the underlying compnaies yourself. 3% spread is also every wide, so that alone would rule it out for me.
You could buy all the holdings separately if you wanted to, but:
(1) you cannot buy 125p worth of these holdings for 100p (which is what the discount lets you do);
(2) you would incur significant transaction costs in buying and selling all the different holdings as each one would have separate costs (this has to be offset against spread of course for true balance); and
(3) you are also getting 1.3 years of dividend reserves in with the deal here (investment trusts can hold back reserves to smooth out between differing years of performance).
The main point is the discount. This was as narrow as 6% as recently as 1 January this year - if it gets back to that then you make 14% profit even if the share prices of the individual holdings go nowhere. If you held the individual shares directly you would make zero in this scenario. You have to believe this will narrow to some degree for the investment to make sense - if you believe all investment trusts are doomed as an industry model then steer clear of course! I don't believe this though and discounts are often (though by no means always - you have to avoid the persistent 'perma-discounts') fickle beings - my faith in the same concept of discount narrowing at Supermarket Income REIT (LON:SUPR) and Custodian Property Income Reit (LON:CREI) over the last 6 months has paid off handsomely in the property sector - hopefully there is scope for some of this newfound optimism in the small caps fund space too, especially with AIM and smallcaps picking up recently.
BIACS, your views would be welcome on the investment trust monthly thread as well
Just adding to Charles Mitchell’s reply, in case you and the many recommending your Investment Trust post today don’t already know of it, here’s the link to the June Investment Trust thread here, which Charles runs, and he updates it every month. He adds an excellent header article each month and with a lot of useful Investment Trust links. And a wide range of Trusts are covered by posters there:-
https://www.stockopedia.com/co...
Generally I would also rather simply buy the individual companies and avoid the fees, but I can think of a number of reasons why buying the collective vehicle could be preferred:
* If you're managing the account of a relative etc (A J Bell allow this, I'm sure others may do), then you might want it to be able to run reasonably well unattended for a while in the event of your incapacity or death. That might be easier with trusts/funds etc than individual shares, since you still have the manager making buy/sell decisions after your passing.
* If you're buying outside of a tax wrapper, then it may be more tax efficient to buy the collective vehicle. It's much more efficient to pay all capital gains tax in one at the end of a long compounding than to pay it at regular intervals along the way. So if the shares that either you or the trust would buy are rotated at regular intervals then the capital gains efficiency inside the trust might conceivably out-way the management fees. Not relevant inside an ISA/SIPP of course.
* Trusts can use gearing. PIs can in theory probably access cheaper gearing by way of remortgaging part of their primary residence, but every time the markets crash and I suggest that to my wife I'm met with a firm "no". So trusts may have access to cheaper gearing than the average PI can access in practice.
* If the discount is greater than normal, then there's a possibility of gaining from the discount closing.
I sse that the top holding is VP (LON:VP.) which I hold as well as Jet2 (LON:JET2)
When the company is marked up as GREEN and gives a profit warning then rather than selling my holding I will be adding to it.
Jubilee Metals (LON:JLP) - I hold - yesterday $90m bid for chrome/PGM producing operations in South Africa - would still leave them with their copper producing operations in Zambia and they say they will still retain an interest in their chrome/PGM production in SA which will enable them to profit from any rise in chrome/PGM price. The bid is for 3/4 of their market cap. I was expecting (hoping for) a big rise in SP but the response was very muted. Does anyone have more insight into what is going on?
My brief take on Jubilee Metals (LON:JLP), as a long term or should that be long-suffering holder.
SA operations are profitable but limited upside unless PGM basket price returns to levels experienced a few years ago. $90 mln is 2.1p per share, so closer to half market cap than 3/4 and is below value that brokers assigned to the business. The retaining interest in PGM production is the Tjate resource, which is an undeveloped mine that would require a sustained recovery in PGM price and billions of capex to bring into production, so understandably not assigned any value.
The Cu ramp up strategy in Zambia has been plagued by delays, some beyond the companies control e.g power availability, some self-inflicted with an over-confidence in being able to profitably process low-grade mine tailings. At some point the strategic pivots and flexibility to a changing external landscape starts to feel like ‘making it up as you go along’.
On the plus side, major issues do seem to be resolved and the value of contained metal in the mines and tailing resources they own, combined with a rising Cu price and a focus suggest there is significant value that could be unlocked. Stubbornly low share price is likely a reflection of a series of missed milestones and lack of clear production and financial guidance. I hold but reduced yesterday, as risk profile has changed.
A spot on summary Mercury287.
Hi,
Where do we find the spreadsheet normally when not linked above? Also is there a decode for the colour ratings?
Many Thanks.
I have twice asked for the link to the spreadsheet to be included in the daily report...no response! It used to be there. Please tell us where it is to be found if you won't include the link permanently
We will include it permanently, Conistons!
Splendid! Thank you...saves me looking back through daily reports, now when did I last see it?
Morning Dave! We have no need to change the link, so you should only need to save it once. Furthermore we will be linking to it in this report as a matter of routine.
As for a colour rating explainer, I think it will make sense to add this to the spreadsheet itself. In short, GREEN means that the author is positive on a stock, AMBER/GREEN means moderately positive, AMBER means neutral, AMBER/RED means moderately negative, and RED means negative.
Thanks Graham, much appreciated.
Strike my comment above: if it's Green/Amber/Red, my plea would be for Green/Blue/Red, as Amber makes no sense at all to me as R/G colourblind. How can I be allowed to drive? Amber is the one in the middle... In the Stocko system I just look at the numbers.
I agree, I'm also in the colour blind camp and find it very difficult to distinguish between them.