Daily Stock Market Report (Fri 6th February 2026) - TND, MEX, EMAN

Good morning everyone! With the New Year reporting season well and truly finished now, I hope your portfolios have survived in good shape!
I'm sorry today's news wasn't very exciting, have a great weekend! Cheers.
Spreadsheet accompanying this report: link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our View (Author) |
|---|---|---|---|
GSK (LON:GSK) (£88.9bn | SR94) | European Commission has approved Nucala (mepolizumab), a monoclonal antibody targeting interleukin-5 (IL-5), in adults as an add-on maintenance treatment for uncontrolled COPD. | ||
HgCapital Trust (LON:HGT) (£1.85bn | SR N/A) | 2025 NAV total return 4%, NAV per share £5.62 (latest share price: 403.5p). HGT share price is down 20% year-to-date due to recent decline in listed software shares. “The Board is actively considering a number potential actions (sic) to address the current discount to net asset value using the full set of tools at its disposal, including share buy-backs.” | ||
Victrex (LON:VCT) (£606m | SR63) | Q1 volumes down 4%, revenues down 6%. “Performance in H1 2026 is expected to be weaker than H1 2025, reflecting the weaker end to Q1 and the currency headwind being weighted to the first half.” Full-year guidance unchanged. | ||
Phoenix Spree Deutschland (LON:PSDL) (£158m | SR54) | Overall Portfolio value rose by 1.5% on a like-for-like per sqm basis. Condominium sales outperformed target in 2025: 122 units sold for €36.0m (2024: €9.4m). Sales target for the year was €30m. Early 2026: 14 units notarised for €4.1m, with a further 26 units (€7.0m) reserved and pending notarisation. The company intends to return capital to shareholders in 2026 via compulsory pro rata redemptions of Ordinary Shares. | ||
Berkeley Energia (LON:BKY) (£119m | SR21) | Subsidiary has filed a Memorial of Claim at the International Centre for Settlement of Investment Disputes in Washington, seeking compensation in the order of US$1.25 billion. Allegations that Spain violated multiple provisions of the Energy Charter Treaty. | ||
Everyman Media (LON:EMAN) (£25m | SR42) | New CFO hired from National World plc. Separately, one of EMAN’s NEDs is becoming Interim Creative Director. | RED = (Graham) [no section below] We've been RED on this for a while now, worried about both the sustainability of its financial position and its generally poor financial performance. It's a positive development that a permanent CFO has been hired, although there is still no permanent CEO. Also, the news that a shareholder-Director has been given the job of "Interim Creative Director" is interesting but I'm not sure how positive it is. This is a cinema group, after all - can he help them to find cheaper ways to implement their creative vision? From his bio on the company’s website: “The Directors do not consider Mr Dorfman to be independent... due to his shareholding in the Company.” He owns 6% of EMAN and so should be aligned with other shareholders, but is now also an employee. I'll stay RED on this. | |
Tortilla Mexican Grill (LON:MEX) (£22m | SR80) | The existing CEO steps down. The Founder is appointed as CEO. A new UK CEO is also hired. Various other changes. | AMBER/RED ↑ (Graham) I'm still cautious on this, but I'm willing to have a more open mind for the year ahead. The trading update last week was not bad, and these management changes are consistent with some strong ambitions and strategic priorities. | |
Tandem (LON:TND) (£9m | SR87) | 2025 revenue +6.2%. Adjusted PBT to be slightly ahead of market expectations. Trading at the start of 2026 has been in line with management expectations. Continuing to target revenue growth in FY26 broadly in line with FY25. | AMBER/GREEN = (Graham) This one doesn't excite me any more (it used to be my largest position). It has been around for decades, and profitability remains very limited. It does at least have a strong balance sheet, and the StockRanks love it, so I'm happy to retain our moderately positive view. | |
Huddled (LON:HUD) (£7m | SR9) | Commitments for a proposed subscription of up to £730k of new shares at 1.75p (last night’s close: 1.9p), alongside a debt facility of up to £600k. Retail offer £100k. |
Tandem (LON:TND)
Up 9% to 185p (£10m) - Trading Update and Notice of Results - Graham - AMBER/GREEN =
Tandem Group plc (AIM: TND) designers, developers, distributors and retailers of sports, leisure and e-mobility, provides the following trading update
This company has long been of interest to those who muck about in UK nano-caps/micro-caps.
At one point it was my largest individual position - I think it was my largest position for a few years. But I ended up losing interest in the end.
The share price did have quite an excited period around the Covid era, before dropping back:
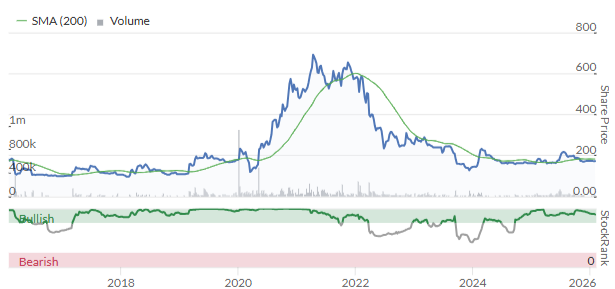
Tandem’s shares have been listed for c. 25 years and are one of the big reasons I moved away from focusing on tiny and ostensibly cheap companies
In the end, I concluded that the company was just “not a compounder” - it would occasionally have good news, and occasionally have bad news, but it was probably not going to turn into a much larger and more profitable company.
So far, that conclusion has been correct, but let’s see if today’s trading update changes anything...
Trading Update
Key points:
2025 revenues £26.2m (+6.2%)
Adjusted PBT “slightly ahead of market expectations”
Let’s quickly survey each of the divisions:
Toys, Sports and Leisure: revenue down 17.5%, which reflects “softer demand in certain discretionary categories, changes in retailer purchasing patterns and the timing of product ranging and promotions”.
Bicycles: revenues +37.6%, with mechanical bikes sales up by a remarkable 47.6% and electric bikes up 30%.
Golf: revenues +8.6%.
Home & Garden +30%, helped by “an exceptionally hot summer”.
Outlook:
Trading at the start of 2026 has been in line with management expectations… Management continues to target revenue growth in FY26 broadly in line with FY25, alongside further improvements in margins and profitability, supported by rigorous cost discipline and operational efficiency.
Estimates
Cavendish covers this share, and thanks to them for publishing these forecasts today. The 2026 forecasts are new:
2025 revenue £26.2m (as disclosed in the RNS), and an adjusted PBT of £0.6m
2026 revenue £27.8m, adjusted PBT £0.8m.
Cavendish points out that the shares are trading at c. 0.5x tangible net asset value.
Graham’s view
My view here is unchanged from what I said in September last year.
As I said then, this share does continue to offer intriguing possibilities for value investors, including that strong tangible balance sheet position.
As a reminder, net assets at the interim results were £23.3m, of which £5.5m was intangible. So that’s £18m of tangible value, including freehold property, plus whatever progress has been made since June 2025.
There’s a catch, and it’s a powerful one: the lack of clean, real profits.
After so many years in operation, and especially considering the strong top-line growth, I would have thought that these higher revenues might have translated into meaningful profits.
That doesn’t make it a bad business, but as an investment, it just doesn’t excite me.
Even when it releases good news, I assume that this will be followed 6-12 months later by a reversal.
Take today's trading update for example: there are huge revenue movements in several of the divisions, both upwards and downwards. There's potentially an interesting story in the explanation of why these movements occurred. But the announcement doesn't try very hard to help us to understand. I'm left to conclude that the movements are unpredictable, and that weather or other short-term trends will change the trends this year.
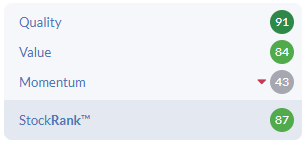
I’m still leaving Tandem on AMBER/GREEN, because it’s performing in line with (modest) expectations and the balance sheet does provide optionality.
The StockRanks also really like it:
Tortilla Mexican Grill (LON:MEX)
Up 4% to 59p (£23m) - Directorate Change - Graham - AMBER/RED ↑
Before getting into today’s Directorate Change (spoiler: new group CEO and new UK CEO), I should take a step backwards. MEX issued a trading update on Wednesday last week, which we neglected to cover.
So without further ado, here are the takeaways from that trading update, covering the financial year ending 28th December 2025:
Revenue +8.5% to £73.8m
UK LfL sales +6.2%.
Adjusted EBITDA in line (figure not given in the RNS).
Net debt £10.7m excluding leases.
Outlook: expecting good improvement in FY26 over FY25.
The Group has had a positive start to the year, with the UK outperforming the market in each of the first three weeks of 2026. We continue to assume that pressure on UK employment could have a downward impact on the consumer economy this year. Cost headwinds seen in FY25 and those announced in the Autumn Budget will continue into FY26 therefore, in line with others in the sector, we will review our pricing.
Estimates: Cavendish left forecasts unchanged, with the following adjusted PBT estimates.
FY25 minus £0.8m
FY26 positive £1.8m
FY27 positive £4.2m
So far, so good.
We’ve been negative on this stock (or more precisely, I’ve been negative on this stock), due to its losses, the net debt position, and the generally poor performance of listed restaurants. But I acknowledge that the trading update and the forecasts for the next two years are not as gloomy as that stance would suggest.
What’s really curious is that the company has just had an OK year, which might suggest that the existing management structure is doing fine, but it’s still choosing to make massive changes.
From today’s announcement:
The founder (and former CEO, until 2014) is coming back to run the business.
New UK CEO hired.
One of the NEDs takes a more hands-on role as “Board Advisor”, “leading UK and European franchise development”.
The existing CEO steps down after eight years.
It’s strange to see a CEO come back 12 years later to run their business again. It’s not unheard of, but when it does happen, it’s usually in some sort of crisis situation where existing management has made a mess of things.
That’s not really the case here. While the share price would suggest that the business hasn’t done terribly well…
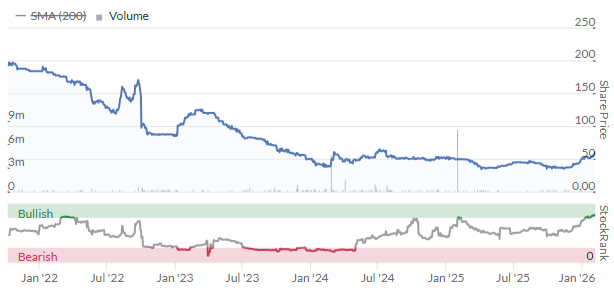
… it could also be argued that restaurant chains in general have been very poor listed investments, and that the economy and tax conditions have been unfavourable.
MEX hasn’t diluted shareholders yet, and is forecast to make modest profits this year. So the position is not all bad.
A range of strategic priorities are set out today, including the obligatory mention of artificial intelligence, but I’m impressed by the ambition and the sense of direction. In particular, they say they will “address the short tail of underperforming UK stores to eliminate loss-making stores and drive UK 4-wall EBITDA margin toward 20% as a longer-term goal.” Sounds fine - and hopefully converts into real profits.
I’m inclined to nudge our stance on this up by one notch, to AMBER/RED. Their plans include becoming a successful franchisor, and franchising is a method that does occasionally turn a business into a highly successful investment.
So I’m still cautious on this, and I'm very mindful of the debt load, but I’m willing to have a more open mind on this for the year ahead.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

59 comments
How everything on Silver was building up!
Have a good weekend
All the best
Morning Yiannos. Some people must have lost an absolute fortune on leveraged fall from $120.
But presumably there is still a reasonable expectation that paper silver price will rise from here ($77) in view of the short supply of actual silver? DD
Excellent DD!
Having explained to someone else about the silver contracts being brought FORWARD creating a short squeeze but still do not want to know (probably difficult to understand).
At least I have someone here that I can talk and have an educated conversation, despite the fact that we might have a different opinion.
Why do people get angry if you say something different about their holdings. I don’t get it.
And I have posted 5-6 different photos that I have posted on X at the time of the build up of Silver price going up from December!
Was it a secret that Silver was going to fly? They were hitting that flow from early November/December, like there was no tomorrow.
Paper Silver-you just nailed it!
Thanks
All the best
Yiannos! How wonderful for you! You've found an intelligent person to have what you like to describe as a conversation with! Presumably, you're now going to answer their question?
You're quite right, Yiannos, I am completely ignorant and naive about these things. The closest I've come to trading a bond was buying a 2nd hand copy of Goldfinger in Oxfam. Of the many things I don't understand - and perhaps you can help - is that if 99% of silver contracts are cancelled each month, why has February seen a 98% delivery rate? And how can Comex inventory drop by 40% in 3 months if 99% of people don't actually want the silver?
Try and read again but take off your blinkers please and try to understand what I have written.
CONTRACTS WERE BROUGHT BACKWARDS……..
All the best
AI and share price slides
There have been many posts on the DSMR over the last couple of weeks on this. I think the whole situation is brilliantly summarised in the Feb. Buffettology fund report released yesterday. I particularly like the analogy between current market mentality and George Orwell's Animal Farm - "chips and infrastructure good, data owners bad".
The report is worth reading and available here -
https://www.sanford-deland.com...
You may have to click to accept conditions first but it is free. Scroll down and click on 2026 then click on Feb.
Do you not think that they are ignoring one important point? Valuation, it matters. Those who either forgot this or failed to see it, Lindsell Train, Fundsmith, Buffetology and some of the Baillie Gifford have performed appallingly in the last 5 years.
Yes their 10 year numbers are good and of course they had "long duration" stocks at a time when 10 year gilt yields were cratering. From approx 3.3% in 2013 to 0.3% in 2021. (Those numbers may ne be absolutely accurate!)
Did they know they were simply playing the "discount rate falling game" but failed to sell when the discount rate started to rise? Or because they had had such a good period prior to 2021, did they think their stock picking was infallible?
A thought for the weekend!!!
Have a good one.
My thoughts on the recent price decrease on Gold/Silver/BTC.
I have been calling on a big correction on BTC for the last two months on my X account.
All of them have the same price behaviour and have nothing to do with fundamentals and the actual demand/supply side.
Wall Street has created unlimited supply through:
1. Options.
2. ETF’s.
3. Broker lending.
4. Swaps.
5. Futures.
All three have unlimited supply now and their prices are influenced by positioning/hedging/liquidation flows.
All the best
Yiannos. St what point does the physical supply and demand for (say) gold become a significant influence on the market price? Surely the spot price can’t be controlled by derivatives for ever?
How can it NOT?
Derivatives (and other instruments) daily volumes well (and I mean way well) exceed the actual spot volume of gold.
All the best
I'm thinking that the prices affect real world investment decisions, such as whether to open or close a mine or to drill for more oil, which implies that miners and drillers believe that prices reflect future demand so supply can rise to meet it. If the real supply and demand and the costs of supply don't affect prices, surely all commodities are just speculations out of touch with reality - like BTC.
I agree with your last three lines.
In fact it’s one of the best I have ever read here. Yes they are all speculative like BTC and they have grown so big because of the reasons I have explained in my first post.
BTC no longer can be regarded as something with limited supply. Yes no more BItcoins can be mined after 2040+ but WS has created more and more and more supply through these financial instruments.
Same with Silver and gold and many more.
I don’t expect everyone to understand what I am saying!
Wait for the correction in WS and you will all see where the prices of gold and silver will go……..
I am not saying there is a correction but when it comes all will be revealed.
All the best
I do not mean to be so blunt, but of course supply and demand affect prices in the real world. We have major and growing deficits in copper, uranium, and deliberately engineered deficits for the West at least in the F-block and platinum. Copper is not a speculation to the cable manufacturers like Prysmian SpA (BIT:PRY) , NKT A/S (CPH:NKT; nor Uranium to Constellation Energy (NSQ:CEG). They might use COMEX to hedge prices, but no one working in the supply chain would view that as anything other than prudent management of risk.
After a career in banking and treasury, I spent 20 years in the soft commodity markets: tea, coffee, sugar, edible oils, grain and supply and demand and the factors impacting it are critical to price discovery in spot and futures markets. We watched for bad harvests, political strife including war, monitored disease using satellites, watched the climate changing; basically anything that could impact supply. Russel Napier is right when he says forget the demand with commodities but make sure you understand the supply side. What he means is that generally demand is stable but supply can be volatile and has the larger and more frequent impact on prices. The physical market drives futures prices; the futures prices do not drive prices in anything other than the short term. These are commodities made up of real atoms ... stuff companies need.
That is not to say traders do not seek to manipulate the paper market. They do and silver is particularly susceptible because it is a small market and paper: physical runs 400:1.(1) Eight Banks Paid $1.3B for Silver Manipulation. Then in 2025, Silver Hit $83 and Shorts Collapsed.
Anyway apologies ... probably too many words for Yiannos. If you have any interest in copper market supply and demand, I recently published a paper here:
The Copper Deficit: Why the Timelines Diverge and Why Friedland Is Still the Outlier Who Might Be Right
There is a downloadable PDF on the copper market.
The most recent (i.e. yesterday) Clive Thompson tutorial
where he takes us through the actual numbers is full of pretty jaw-dropping stuff - just one quote...
"If March 2026 sees even 25% of contracts stand for delivery, COMEX would need 107 million ounces - potentially more than will be available by first notice day (February 27). If the delivery rate matches January-February intensity (50-70%), we're looking at demands for 200-300 million ounces against available inventory of 85-103 million ounces"
One thing I found really interesting is that COMEX also has "eligible silver" in the warehouses which they can't deliver because they're holding it on behalf of other people. And this eligible silver is not being drawn down significantly. Why would anyone hang on to this silver when demand is so high? Well, if the registered, deliverable silver runs out in March, and there's an unmet, huge demand for the atoms, what will happen to the price...?
Everybody needs a Clive in their life. Great share. My best guess is COMEX declare a force majeure and the longs will not be honoured ... LME did the same thing with Nickel in 2022 following the spike in Nickel prices as a result of sanctions on Russian miner, norilsk nickel.
The challenge to the LME over the cancelled nickel trades was brought by Elliott Associates LP and Jane Street Global Trading.
The High Court case is R (Elliott Associates LP & Jane Street Global Trading) v The London Metal Exchange & LME Clear Ltd. The Administrative Court dismissed their judicial‑review challenge, holding that the LME acted within its powers when it cancelled roughly US$12 billion of nickel trades during the March 2022 price spike.
Case here: Admin Court rejects $12 billion challenge to London Metal Exchange | Brick Court Chambers
The same thing will happen to these COMEX contracts. No honour among thieves ... the direct result of this is the end users are by passing the paper exchanges in the West totally and contracting directly with miners and refiners. That perennial disappointment known as Johnson Matthey (LON:JMAT) might end up a beneficiary .... might!
Still long silver, Pan American Silver (TSE:PAAS), Fresnillo (LON:FRES) and Wheaton Precious Metals (TSE:WPM) and waiting for March with a mix of amusement, anticipation and curiosity.
Force majeure gives a contractable excuse for unforeseen events. Ironic, really, given that we can watch this unfold in real time - entirely foreseen.
Controversial tutorial for someone that knows how things work in real life.
Open interest almost always goes to zero before expiry.
All these March contracts will be closed before expiry…….
All the best
Have you watched the video? I know it's quite long, but if you have, I have some follow up questions...
The headline says everything.
I am telling you from now that all these contracts, and as expiry date approaches, almost all of them will be closed.
Silver has lost approximately 40% from its highs which means that to go back there it needs to go up about 80%!
All the best
So you haven't watched it. So you cannot possibly comment on the detailed data driven analysis and historical patterns that it contains. Go on, treat yourself, a whole 23 minutes of your day. THEN tell us what you think...
Why the personal attacks?
Get a life
We are having a conversation-well I thought we did!
I have seen the headline so no need to watch anything or read or watch on what people think about silver or what’s going to happen.
Anyone with knowledge of how these markets work knows very well that all these contracts are 99% closed before expiry date.
Have you ever actually traded any of these contracts?
What happened with Silver last month, some clever traders working for a major US bank have brought BACKWARDS some of the March contracts to January and February and created a sudden short squeeze and the price jumped to $120.
Anyone with extensive experience on how options work and especially OPEN INTEREST, can easily go and examine the one and only most important KEY METRIC (no I am not telling you which one it is) and understand that at this exact time the game on Silver has finished.
What will happen tomorrow, next week or next month is simple……Just watch that KEY METRIC…….
All the best
What is your @ on x?
OptionsFlowBoss
All the best
BTC and gold dance to a completely different tune. BTC is now tightly correlated to the MAG 7 ... BTC is increasingly behaving like a tech stock ... the long run CC is 0.805, although this can swing widely on shorter time frames. Gold is a debasement trade. The CC of Gold to the NADAQ100 is between -0.2 and -0.3 depending on the time frame used. Incrementum have it at 0.13 over 90 days for the S&P500. Gold is tightly correlated with M2 money supply but I do not have the CC figure to hand but you can eyeball it on this graph.
I do not believe you are correct in your assertion that derivatives can control the price for ever, although recent events clearly demonstrate derivative positions call the price action in the short term. We are seeing very significant premiums opening up between COMEX and the Shanghai market ... the first is a paper market and the second requires physical delivery. COMEX only delivers fantasy prices which nobody in the market believes. By "nobody", I mean the end users not some wide boy derivatives trader. It has got so bad, the people I talk to at companies like Samsung, Jiaxing and Aiko are either already sourcing directly from refiners or preparing to do so, thus bypassing the fantasy paper markets.
The big squeeze in the silver market will be March as there is insufficient physical silver to deliver against open interest and market participants are increasingly demanding delivery (look at the physical delivery on COMEX ... it is up by multiple factors month on month and year on year). I think COMEX will declare a force majeure in March like the LME did with Nickel back in 2022. This was tested in court and the LME won, but at the cost of long term damage to the credibility of the market.
The future is atoms, not fantasy bits of paper traded by wide boys who would not know an atom from a bottle of beer on a Friday night. The end users are increasingly tying up the resources they need to manufacture with off take agreement with the mines as nobody who actually works in the supply chains trusts paper any more. This is the result of the long term damage done to LME as a direct result of the nickel debacle back in 2022. People will not do business with you if they do not trust you, so we are eventually going to be left with a bunch of wide boys trading fantasy bits of paper with each other but with no physical metal backing. There are already 400:1 claims on every oz of silver on COMEX.
There is no doubt that the precious metals markets have been extensively and in my view fraudulently manipulated on Friday an Monday. My old alma mata is up to their neck in it despite being fined USD1 billion for previous corrupt practices in the silver and gold markets.
(1) Eight Banks Paid $1.3B for Silver Manipulation. Then in 2025, Silver Hit $83 and Shorts Collapsed.
Too big posts make me fall asleep. I guess I am too old!
I was only talking about the volatility of recent events and the enormous financial instruments that Wall Street has created.
And it is too obvious as volatility always accelerates on a Thursday……….. and then it’s Friday that most of these expire…….
All the best
Fair enough Yiannos ... but that's not what you wrote.
All the best
It’s what I wrote you just don’t agree with it.
Fair enough.
All the best
jamesalastair
I have a quick question
For the sake of this conversation:
If the US market turns bearish and the US economy into recession. The Dow loses 40% of its value and the Nasdaq and the SP 500 60% in the next 2 years.
Where do you see the price of gold?
Thanks
All the best
I think it will fall as leveraged traders will liquidate what is most liquid to cover margin calls. The most liquid asset is usually gold. I am not one who believes gold is a hedge against what the S&P gets up to. I only believe gold is a hedge against the stupidity of central bankers. It is a debasement trade, not an equity hedge trade.
I know you don't like too many words but: (1) All Roads Lead to Gold - Alastair Kendall
Thnaks
Agreed on the first part.
The second, and as a Greek on the front line that has experienced the greatest stupidity of any government in the world (starting from Simitis fixed numbers to get into the € and finishing with Karamanlis and Papandreou), I believe the best and simplest hedge is the sale of US bonds……something that is already happening and will accelerate further at some point in the next 2-3 years. My only concern about the US market and not valuations.
Different opinions and the reason that markets always fluctuate!
All the best
We have plentt of mind numbing stupidity up here in the Scottish Parliament as well. The worst of it? The weather is shite as well.
I thought the Scottish politicians were the clever ones.
Certainly the English ones are ranked high up there with the Greeks, and I mean the recent past, present and future!
Yep, Gordon Brown was certainly one of the top Scottish politicians – announcing he was going to sell down the UK’s gold reserves in advance thus ensuring the worst possible price.
And as an exile living in Wales I have to give a shout out for Welsh politicians – they can match Greek and English varieties any day 8-)
Maybe the "profession" of politics self selects for the stupidest among us?
hi jamesalastair. I have been following commodity prices, including gold and silver, on the Trading Economics site, but your oft-quoted references to the Shanghai market makes me wonder whether TE is heavily influenced by COMEX? Is there a Shanghai equivalent of TE, or am i barking up the wrong tree?
Hi
I am afraid you will have to do some work as figures are quoted in CNY:
Silver
I was thinking of running a daily COMEX, LME, Shanghai silver and gold chart on my substack, but I know I will run out of enthusiasm once lambing starts. Also I am not a chicken bone shuggler (sorry chartist/trader), but invest with a 2 to 5 years time horizon.
Thank you. I have no problem with the currency conversion. I had a quick look for a site and couldn't find one - perhaps you know of one?
I'm not just interested in gold and silver, and my horizon is more like 18mths, but i admit to being a metrics follower once i've done the rest of my homework.
In the meantime i hope the weather improves up there (i was on Glenlivet estate last weekend), and lambing goes well for you
Glenlivet Estate is part of the Crown Estate. I did some advisory work for them back in the day. Beautiful area. I used to fish the farmer's water on the Avon, which is one of the major tribituaries of the Spey. Lovely fly water. Reach out next time ... I would be happy to show you around.
I shall, thank you. Cheers
Thanks. Very useful information.
Ilika (LON:IKA) Kelso group (LON:KLSO) Poolbeg Pharma (LON:POLB)
The first Yellowstone Advisory Private Investor Evening of 2026 will take place on Wednesday 25 February at 5.30pm.
We are delighted that Ilika Plc, Poolbeg Pharma Plc, Kelso Plc and1 TBC will join us to introduce their companies and explain the investment case.
This is a chance to meet management teams and fellow private investors face to face in a relaxed environment. Listen to company presentations and then take the opportunity to ask your questions over drinks and canapes.
The event starts at 5.30pm in EC1 and doors open at 5.15pm.
If you would like to attend please register below.
Register: Join Webinars & Events | Yellowstone Advisory
#IKA #POLB KLSO
My thoughts on HgCapital Trust (Lon: HGT) are that AI will work with software providers rather than replace software providers. Those that adapt will win. Those that don't will see margins erode. HGT may be a winner here and could be a great investment at current prices. DYOR.
Well January a good month, awful start to Feb! Which to be fair, is usually not a great month
Hi Graham, you've looked at the private equity sector previously. Would you give us your views on the HgCapital Trust (LON:HGT) update and their comments on the recent market movements relating to software valuation concerns?
Oak Bloke has just published a piece on HgCapital Trust (LON:HGT) arguing that it's been marked down too hard on fears about AI.
I’ve been out of HgCapital Trust (LON:HGT) for a while (once it go to trading within ~5% of NAV). The RNS woke me up and I’m amazed to see the discount. Im using it as my way to buy this dip. Logic:
“Boring tech” (recurring revenue stuff that everyone wants AI to take), profitable companies, historically conservative on valuations for NAV, strong leadership and now a share buyback.
Related to that, the longer they keep Visma the better in my view (in terms of cash flow/profitability). My fear previously was how they would reinvest the hole left from IPO.
Silver went from $120 to $64 in 4 days. Carnage on the CFD market....
Yes. Carnage indeed, and the crypto bros will be back at McDonalds before long.
Ha ha imagine the scenes.
A Big Mac ? Yes sir, that will be $3000 please
Silver will come back.
March is one of the largest delivery months in the year. Outstanding contracts that can stand for delivery are substantially larger than inventory available in London and New York. The trend is for more and more holders to demand physical delivery.
There is a very real possibility of a silver squeeze above $120.
Why doesn’t the market know thst?
It is public knowledge, laid out in the commitment of traders report released weekly.
So is it discounted in today's price already?
No
I am inclined to agree even though I have sold my silver position which is a portfolio decision. I will be waiting for the calm down and then consider a fresh silver position.
Yes well it also went from $60 to $120 in a matter of days, so only carnage if you bought at the very top. I hold gold and silver as long term insurance against fiat currency debasement - I was actually pretty uncomfortable with the vertical move higher and did trim a bit as was obvious it would fall back. Mostly though I am just ignoring all the short term volatility - I wish traders would stay away from precious metals.