Daily Stock Market Report (Fri 7 Feb 2025) - UK Rate Cut, AZN, RAI, AAL, VTU, ASHM, LLOY

Good morning! We have some backlog sections from Mark to start us off today.
13:30: all done for the week, have a nice weekend!
Spreadsheet accompanying this report (last updated to: 23rd Jan 2025)
UK Rate Cut
The big economic news this week has been the reduction in interest rates from 4.75% to 4.5%, the third rate cut in six months, accompanied by dovish sentiment at the Bank of England where some members believed that an even bigger cut was in order.
Governor Andrew Bailey describes the cut as “good news” - the plight of borrowers is always of slightly greater concern than the needs of savers!
However, inflation is still above the 2% target. It only very briefly fell below it in September:

This is before the impact of higher NICs, which many predict will lead to a rise in consumer prices as businesses are forced to pass on higher costs to customers.
The Bank of England itself says that it expects inflation to rise to 3.7% this year, before falling again.

So with inflation already slightly higher than the Bank’s 2% target, and expected to rise further from here, it’s a brave move to pre-emptively cut rates. After all, the Bank’s primary mandate is price stability, and other objectives are supposed to be secondary. But they say there has been “sufficient progress” when it comes to reducing inflation, to allow them to cut rates - and there has indeed been remarkable progress on that front.
On the subject of price stability, the Bank is of the view that energy and utility prices will be the main driver of inflation in the short-term, and that “underlying domestic inflationary pressures are expected to wane further”. I hope they are right, but I’m concerned that the incoming tax changes could upend that prediction.
In the Bank’s defence, it is only a 0.25% cut, and they say they will be “careful” with next steps, not committing to further cuts.
All of this was expected. However, the news that caught the market by surprise yesterday was the discovery that two members of the Monetary Policy Committee wanted to take a more radical step and to cut Bank Rate by 0.5%.
For these members, and perhaps for the committee as a whole, they now feel that the Bank must pay more attention to GDP growth and economic activity. There is an argument that weaker activity and a slightly looser labour market can in themselves fuel inflation. But at the same time, the Bank has said that the labour market is “in balance” overall, and that there is only “a small margin of slack”.
And if the economy is already producing close to its maximum capacity, there is a limit to what rate cuts can do to boost economic activity,
Even with the economy operating close to its maximum potential, GDP fell by 0.1% in 2024 Q4 and is only expected to rise by 0.1% in 2025 Q1, barely avoiding an official recession. Low productivity was singled out as the reason for this.
NICs: the bank is monitoring the NIC issue. It says that according to economic literature, “more of the adjustment is likely to come through real wages or employment than profits”, i.e. that employees are likely to bear the brunt of the cost, either through lower salaries or fewer job opportunities.
They say that labour costs are increasing by over 5% for the bottom 50% of earners, and that the elasticity of demand is higher for lower skilled workers. In other words, employers are most flexible when it comes to the number of lower skilled workers they employ. This means that these workers are the most vulnerable to changes in demand for their services, arising from higher NICs.
Here are the Bank’s conclusions:
Survey evidence and Bank staff analysis since the November Report continues to support the judgement that firms are likely to use a number of different margins in response to the change in NICs… The increase in NICs is expected to have a marginally larger impact on prices in the near term than at the time of the November Report.
…employment may be more affected than in the central assessment in the forecast. There remain considerable uncertainties around how firms will respond, however, which the Committee will continue to monitor.
And yet the Bank has set out on a rate-cutting path, despite all of the uncertainty around this issue and with price rises looming.
What this means for investors: markets are now pricing in another 50 basis points of rate cuts in 2025. I don’t see anything to get in the way of the FTSE-100 making new all-time highs this year. For homebuilders, mortgage lenders and construction companies, they can look forward to slightly easier conditions than they may have been expecting. But for importers, watch out below:

(GBPUSD)
Today's news: this afternoon, we'll have non-farm payrolls data from the United States, with a further 169,000 jobs expected and an unemployment rate of 4.1%.
Agenda
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Legal & General (LON:LGEN) (£14.8bn) | Sale of US Protection | Buyer also takes 20% interest in US Pension Risk Transfer, strategic partnership. Combined value £1.8bn | AMBER (Graham) An excellent deal that will keep L&G shareholders in clover for the next few years. No opinion on the stock due to complexity. |
Ashmore (LON:ASHM) (£1.1bn) | Half-Year Report | AUM $48.8bn, “broadly unchanged”. Net outflows improve to $1.1bn. | GREEN (Graham) The balance sheet remains very attractive. Watch out for a dividend cut if earnings remain under pressure. |
Victrex (LON:VCT) (£866m) | AGM & TU | Full year expectations unchanged. “Solid start”. Q1 revenue +9%, volume +20%. | |
| Vertu Motors (LON:VTU) (£174m) | TU (yesterday afternoon) | Profit warning. Adj. PBT significantly below exps. Dislocation in new car market. | AMBER/GREEN (Graham) Quantitatively "cheap" for those who can look past the industry issues. |
Ingenta (LON:ING) (£10m) | TU | 2024 revenues (£10.2m), EBITDA (£1.8m) in line. Sales/marketing spending to reduce 2025 EBITDA. |
Backlog
AstraZeneca (LON:AZN)
Up 5% yesterday to 11,650p (£221bn) - Final Results - Mark - AMBER
When I previewed the results in The Week Ahead, I said that the company had shown rapid growth in EPS over the last few years, but with the 2025 P/E of 15 and a forward PEG above 1, investors will be looking for signs that these forecasts are conservative. The consensus was for $53.1b of revenue and 815c of EPS. Here’s what they came in as:
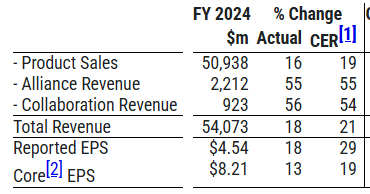
So that’s a very slight beat on revenue and EPS. However, it is worth noting that the beat would have been much bigger if they hadn’t faced currency headwinds during the year. These moves are largely unpredictable, so it is understandable that they provide their guidance at constant currency:
Guidance for FY 2025: Total Revenue is expected to increase by a high single-digit percentage and Core EPS is expected to increase by a low double-digit percentage, both at CER
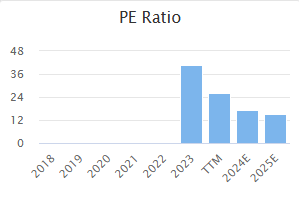
So it seems that growth is expected to moderate but still be at reasonable levels. Putting these figures into my calculator, it looks like the implication is for a likely beat to the $56.6b revenue forecast, but with Core EPS in line. If this is the case, the PEG remains above 1:
Mark’s view
I don’t see the attraction here. When Megan looked at this following the announcement of an escalating insurance fraud investigation in China, she noted that the PEG ratio was below one and hence rated it GREEN. That is no longer the case based on current guidance, so it is an AMBER for me.
Ra International (LON:RAI)
Down 86% yesterday to 0.9p (£1m) - Delisting - Mark - RED
This provider of construction and IFM services to governments and NGO’s in difficult places just scrapes into our £10m lower market cap limit. At least it did until the shares fell almost 90% today on the news that it is delisting:
As announced today, the Directors have, after a period of review, concluded that it is in the best interests of the Company and its Shareholders to seek Shareholder approval for Cancellation of the admission of the Ordinary Shares to trading on AIM.
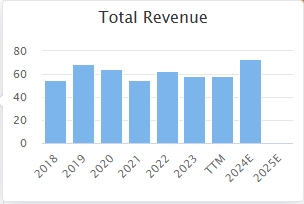
This is always a risk in a stock where founders own 80% of the shares. It is an ignominious end to a company that listed with strong growth plans. The problem was that growth in their industry is capital-intensive. When they raised cash on listing, management didn’t cash out but held on to a high proportion of the company. They presumably saw the business growing and thought they would be able to raise further capital while diluting down their stake. The growth failed to materialise, though:
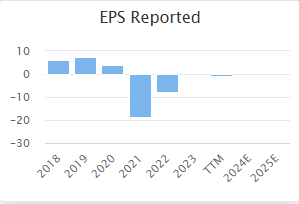
COVID delays hit profitability:
And while they generated much higher gross margins of around 20% by operating where others wouldn’t, there was a reason that others didn’t operate there. An insurgency in Cabo Delgado in Mozambique highlighted this risk, and led to further losses, including the death of an employee. At this point, the share price presumably seemed too low to raise more money without severely diluting management, so they limped on, restricted in their ability to grow out of their predicament by their lack of capital.
Today, this comes back to bite them, as along with the delisting announcement, they issue an update on trading:
For the year ended 2024 and based on unaudited management accounts, we expect to report a marginal year on year revenue increase compared with 2023. Despite this, a (pre exceptionals) loss is projected at Operating and EBITDA level primarily as a result of delayed contract commencements and mobilisation issues, which have already adversely impacted our invoicing schedule.
To strengthen our financial position, we will be initiating several cost reduction measures in 2025, including the potential divestment and closure of certain subsidiaries, in particular those that are loss making. These actions aim to maintain operational efficiency, preserve cash, and sharpen our focus on strategic contracts and key client relationships.
There is the potential for divestments to keep the show on the road, but ultimately, they say:
However, any positive impact the potential divestments may have on the Company's cashflow and profitability is expected to be offset by the reduction in revenues and resulting margins from ongoing delays in mobilisation and decreased scope of a number of key contracts.
The management here always prided themselves in doing the right thing, and I genuinely believe they aimed to do so in the past. This makes it galling that despite owning 80% of the equity, they are not making any tender offer to allow minority holders to exit at a reasonable level. The non-execs have allowed the founders to vote their shares which, with 80%, means that this is a done deal. The reality seems to be that the cost saving of delisting is now vital, and the founders don’t have the money and no one is willing to lend it to them, given where the business has ended up.
Mark’s view
The trading update highlights the risks and suggests that even those who can hold unlisted equity shouldn’t be holding on here. The 90% fall in share price looks justified. RED
Anglo American (LON:AAL)
Up 6% yesterday to 2440p (£33bn) - Q4 Production Report - Mark - AMBER
Anglo American rose yesterday on marginally better than expected Q4 copper production, which is up 9% on the previous quarter. They guide 2025 copper production at 690 Kt-750 kt, slightly below 2024 production of 773 kt, and 760 kt-820 kt in 2026. However, they have reduced their forecast for rough diamond production due to lower demand from the market.
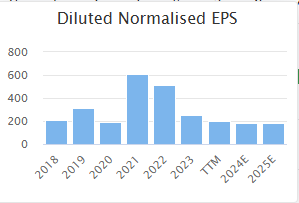
There is a theory that you should buy miners on a high P/E and sell on a low P/E as they are cyclical stocks, and by doing so, you are acting countercyclically. However, I see little sign of this in AngloAmerican’s long term EPS figures:
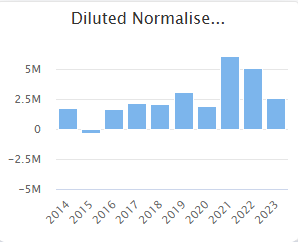
It seems to me that current forecasts are about normal for the company, and 2021/2022 were the anomoly:
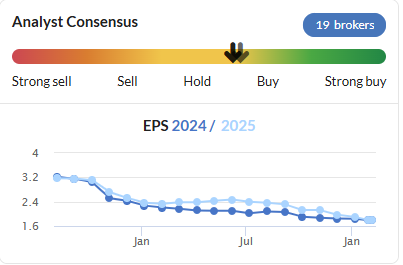
And the broker trend isn’t particularly encouraging:
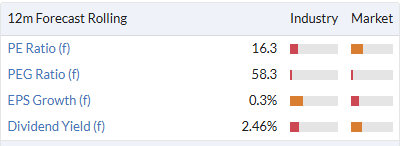
This makes paying these sorts of multiples for flat production look out of place:
Mark’s view
It is hard to get excited about flat production forecasts and declining broker forecasts, especially at these sorts of multiples. AMBER.
Graham's Section
Vertu Motors (LON:VTU)
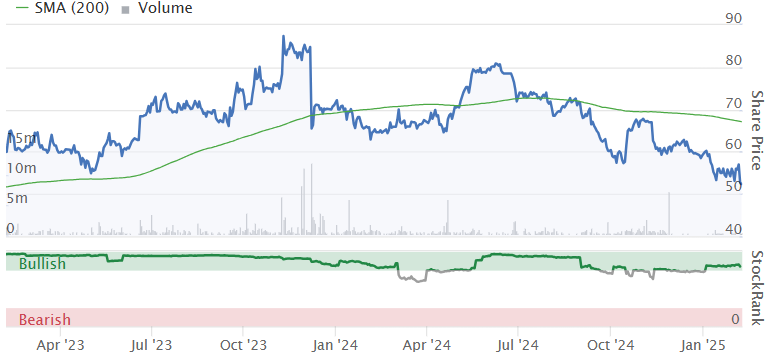
Down 7% yesterday, latest price 52.4p (£174m) - Trading Statement - Graham - AMBER/GREEN
One of the few things that is virtually guaranteed to annoy investors is the release of market-moving news in the middle of the day.
Normally, we get just an hour to digest a vast quantity of information, before the market opens. I’d prefer a system where news was released after-hours, enabling us to read at our leisure before the market opens the next day.
But then you have a situation like Vertu yesterday, where the news comes out at 2.30pm.
It’s a profit warning, with adj. PBT for FY Feb 2025 anticipated to be significantly below current market expectations.
The expectation was for adj. PBT of £34.5m.
The reason: “primarily due to dislocation in the new car market”.
Let’s pick out some of the key bullet points:
New cars: LfL volumes at VTU were ahead of market trends in the past five months, but the market trends are terrible as “UK volumes overall in the new retail channel were the lowest for 25 years including the pandemic period”.
Used: suffering from subdued consumer confidence and heavy discounting of new cars.
ZEV mandate: there is a 28% ZEV target for 2025, that “is likely to lead to further ongoing discounting activity in the new car market, continuing the margin pressure seen during the current year”. Volumes also under pressure.
Reading a little further into the ZEV issue, VTU notes that the industry failed to hit the government’s 22% ZEV target in 2024, but attempts to hit these targets are affecting the industry. The current weakness in higher-margin private channel sales (as opposed to low-margin fleet sales) reflects “consumer hesitation toward BEVs, affordability issues and more limited availability of petrol and diesel vehicles as Manufacturers prioritised compliance with percentage targets of the ZEV mandate.”
As things stand for 2025, “the increased target is likely to lead to continued pressure on new car volumes and margins as the market is increasingly distorted in favour of BEVs.”
Aftersales are still doing fine, and £10m of cost increases arising from NICs/NMW will be “fully offset” by headcount reductions, increased use of technology, and Sunday closures.
Buyback: one of the main attractions at Vertu has been the strong balance sheet that has enabled large buybacks.
Checking the most recent interim report, I see tangible net assets per share reported at 73.7p. From the balance sheet I calculate the corresponding value as £232m. The company has made a small-ish (£12.5m) acquisition since then.
That level of asset backing gives the company the confidence to plough money into buybacks and the company softened the blow of yesterday’s profit warning by announcing an additional £12m to the ongoing buyback programme. £4m has been spent already on buybacks in FY25.
They are confident they they are buying below fair value:
The Board determined that Vertu Motors plc shares are mispriced and trading at a material discount to our own assessment of intrinsic value.
Please note that a high level of asset backing is not the same thing as saying that the company has a net cash position: it had net debt at the interim results of £175m (includes £91m of leases, so the figure is £84m excluding leases). Without the use of vehicle stocking loans to help fund inventories, most car dealers would be unable to earn an acceptable ROE: VTU’s inventories are a staggering c. £800m.
CEO comment snippets:
…the Government's ZEV Mandate is causing severe disruption to the UK new car market, and the consumer environment is subdued. Despite these headwinds, the Vertu team is delivering, as seen by our significant market share gains in BEV new cars in the final quarter of the year….
Vertu's strong balance sheet, underpinned by over £320m of freehold and long leasehold property, is a comfort to our colleagues, Manufacturer partners and shareholders in these times.
Estimates: the new adj. PBT estimates at Progressive are £29.6m (FY Feb 2025) and £26.5m (FY Feb 2026).
Graham’s view
I’m inclined to leave this at AMBER/GREEN because VTU offers: a) a reasonable single-digit PER, b) a discount to tangible NAV, c) a declining share count, and d) profitability (albeit at a lower level) even in terrible market conditions.
What are the downsides? Very limited organic growth prospects. And probably a lot more market disruption to come, until/unless ZEV mandates are relaxed. If that happened, then I imagine that VTU shares would soar. But if most of the pain seems to be falling on dealers rather than consumers, perhaps that’s not very likely.
Ashmore (LON:ASHM)
Up 2% to 174.4p (£1.2bn / $1.5bn) - Half-Year Report - Graham - GREEN
This emerging markets fund manager has achieved nothing for its shareholders for many years when it comes to share price appreciation, but it has paid out enormous dividends. The yield is almost 10% currently.
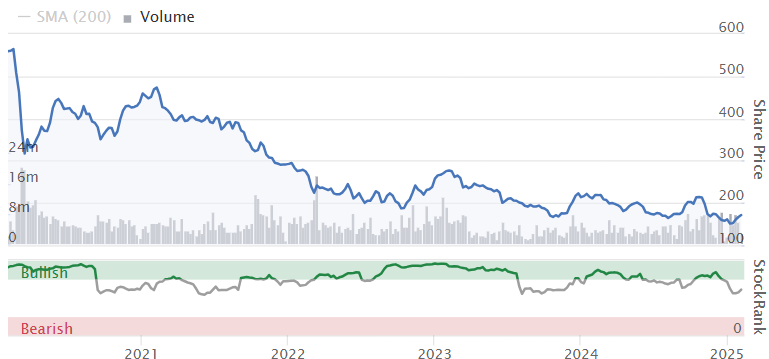
Today’s interim results are consistent with a share price in a state of long-term malaise:
Continued net outflows ($1.1bn) which are described as a “significant reduction in redemptions”.
AuM almost stable at c. $49bn, helped by positive market performance. However, average AUM was lower than before, which puts downward pressure on fees.
Net management fees are down 17%, with performance fees (a separate category) stable.
I’ve been positive on this stock despite underwhelming progress because of its ability to churn out profits in all conditions. For H1, it reports an adj. EBITDA margin of 42%, not much lower than last year’s 46%.
Overall profits do decline, with adj. PBT falling from GBP £54m in H1 last year, to GBP £44m in H1 this year.
Equities: ASHM is traditionally a debt investor but equities AUM have grown to $7bn (a year ago: $6.5bn) and are now 14% of total AUM ($48.8bn).
Macro outlook: I no longer pay too much heed to commentary from ASHM on the macro outlook as, while interesting, it never seems to have any bearing on their inflows/outflows.
Additionally, for as long as I can remember, ASHM has been saying that investors are underweight EM and in need of rebalancing into it.
I guess it’s not really possible for them to say anything else, as the whole point of the business is to convince allocators to put money into emerging markets:
Robust fundamentals, resilience and reforms evident across emerging markets, delivering superior economic growth.
Meaningful upside to asset prices in EM if US policy implementation is more measured than campaign rhetoric.
Significant rebalancing required to address investors' cyclically low EM allocations and to capture the potential upside to asset prices.
Graham’s view
Perhaps I should downgrade this to AMBER/GREEN as it’s seriously lacking in growth. However that is true of most fund managers I cover in this report, and I’m GREEN on most of them.
Turning to the Dec 2024 balance sheet, I see total equity of GBP £818m, backing up a very large portion of the market cap.
Nearly all of this value is tangible (only £88m of intangible assets), and a large part is in the form of investments that are capable of growing in value. ASHM has nearly GBP £350m of seed capital in its own funds. In total it has excess capital of GBP £550m, over and above its regulatory requirements.
All of that seed capital does serve an important operational purpose in relation to ASHM’s funds but it’s also a meaningful part of the balance sheet and the overall package that shareholders are buying into here.
There are also cash, cash equivalents and term deposits of nearly £350m.
When it comes to shareholder income, the interim dividend is unchanged at 4.8p, matching H1 adjusted earnings per share of 4.8p. The final dividend is usually 12.1p, and H2 EPS is not going to be able to fund that.
I’m going to stay positive on this with the warning that the dividend is not supported by earnings, and so a dividend cut should not come as a surprise, if it happens. I think the company can afford to continue making the payment using its balance sheet, if it so chooses, but I would not expect it to do so perpetually.
So if you’re comfortable with that situation, I still think ASHM is worth another look. If or when we see US equity valuations falter, perhaps ASHM can benefit from renewed interest in EM? Especially now that it can offer EM equity exposure.
Legal & General (LON:LGEN)
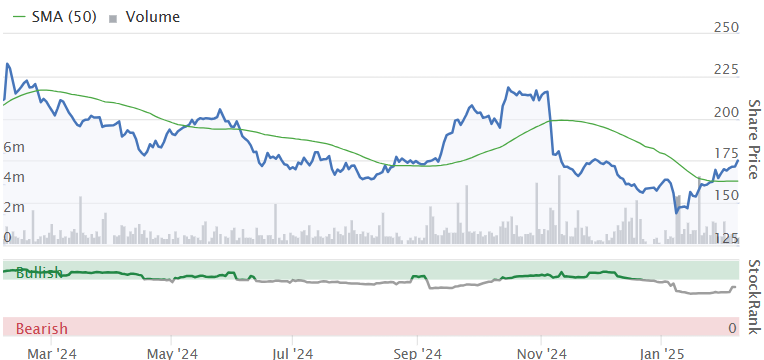
Up 3% to £2.47 (£14.5bn) - Sale of US Protection; new Strategic Partnership - Graham - AMBER
This is a short RNS considering that there is nearly £2bn at stake.
L&G is selling its US insurance business to the Japanese life insurer, Meiji Yasuda, for an equity value of $2.3bn (£1.8bn).
As part of the deal, Meiji is taking a 20% interest in L&G’s US pension risk transfer business.
Finally, Meiji intends to take a 5% interest in the overall L&G Group.
In the short-term this will allow an additional £1bn buyback for L&G, while still increasing L&G solvency ratios.
In total, L&G “expects to return the equivalent of c. 40% of its market cap to shareholders over 2025-2027 through a combination of dividends and buybacks.”
Trading update: guidance unchanged.
The company reiterates guidance for FY Dec 2024 and its plans out to 2027:
6-9% CAGR in core operating EPS (2024-27)
>20% operating Return on Equity (2025, 2026, 2027);
£5-6bn cumulative Solvency II capital generation over three years (2025-2027).
CEO comment:
"This is a transformative transaction that brings significant strategic and financial benefits to the Group and demonstrates our commitment to deliver on our strategy - sharpening our focus on core businesses, leveraging the synergies between them, and driving sustainable growth to enhance shareholder returns.
This strategic partnership brings together two highly complementary global businesses, with a shared ambition for growth, and will enable us to capitalise on the large market opportunities in US Pension Risk Transfer while driving scale and profitability in global asset management…
Graham’s view
This appears to be a good deal for L&G when we consider the disclosed summary financial information for the US protection business they are selling: operating profits of c. $90m in 2024, with net assets of $850m. In selling this for $2.3bn, they’ll record an accounting gain of over GBP £1bn. Tick, tick, tick - they’ve achieved a very nice valuation based on these numbers.
The growth in their capital base that this will allow will help them on their way to achieving their 3-year targets out to 2027. But they will be lucky if they can find more deals like this in the next two years, so it might be less straightforward to stay on track as we approach 2026 and 2027.
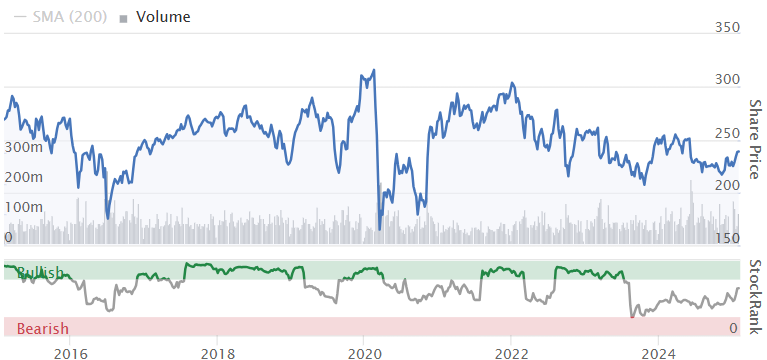
I’m neutral on this stock as it’s too large and complex, and this is just a short review. But I expect that it will probably continue to do its job of paying out vast sums to shareholders, without ever generating very much capital growth.
10-year chart:
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

75 comments
Interesting about your opinion with Vertu Motors (LON:VTU) . In all of Ed Crofts videos , dump any share instantly that gives a profit warning he keeps stating, I think he did a lot of research on this over time. 1 year plus it continues to drop I seem to remember. Bottom fishing was fine in covid times , IAG as an example but a lot better shares out there
RE VERTU
Quite often the daily reporters narrative on stock profit warnings differs from the Stockopedia research, which as you say advises to sell on a profit warning. Another recent example was Ultimate Products where in the face of a poor trading update the daily report thought that UP now offered some value.
Recently, the CE Robert Forrester has been making a lot of press about the difficulties of car dealers and the wider car industry. It occurred to me that this might be the precursor to bad news - which it was
In the case of Vertu, there could be an argument that it is a special situation. Most of the sector has been consolidated with takeovers. Vertu apparently has a strong asset base and appears at face value to be a reasonable prospect for a takeover at a Price TBV of .73.
I was a quite a long term holder but sold on the whiff of a potential problem with car financing. I didn't understand how this might play out so got out at a modest profit. I don't have much conviction for the short term prospects in the car industry so I cant see me getting back in here.
Might be a reasonable bet at current levels for those who buy into the idea of a takeover prospect.
.
A lot of these are bouncing back, take Vertu Motors (LON:VTU) it was down 13% about 30 minutes after the RNS, ended the day only down 3%.
Quite a few others as well. Selling straight away may not be best thing to do, some recover the same day or next few days, Sanderson Design (LON:SDG) and Ultimate Products (LON:ULTP) are two. Funding Circle Holdings (LON:FCH) was another.
The gold price has just risen above £2300 per ounce and given the inflationary and other outlandish policies emanating from the White House (the less said about the occupant the better) is likely to continue to rise.
This should provide a significant tail wind for Ramsdens Holdings (LON:RFX) , which from my point of view is one of the more risk adverse ways of investing in gold, given that I have no knowledge of geology and don't understand geological/mining reports Its other revenue streams, jewellery/watches, FX and pawn broking are also growing.
The share price has started to rise recently having meandered between 195p and 210p for sometime.
Consistent with my previous posts it would not surprise me if the company exceeded current market expectations. Just my view, which is perhaps expected given I have a reasonable position.
Hello Jonno, I empathise with your view on Ramsdens Holdings (LON:RFX) but if you really believed the less said about The President the better then you wouldn't have said that, you'd have said nothing.
Fair point Tein, you did make me chuckle.
Not quite tautology but heading in that direction perhaps.
Is anyone else out there disappointed by the Legal & General (LON:LGEN) share price reaction today? I have held this stock for its reliable income stream for several years. Today's good price for the US business brings an improved solvency ratio, safer dividend and the scope for a greater buy back (on a stock that is genuinely a good candidate for buy backs!) but the share price hasn't held onto more than a small fraction of the earlier gains.
Graham's write-up is a fair one in pointing out the difficulty of unravelling the complexity of this sort of business, but it is not often that you can lock in to a 9% dividend yield without too much risk of a future cut in the payout.
Though really appreciating the overall high quality of all Graham’s analysis here, I strongly disagree with his continued enthusiasm for Vertu Motors (LON:VTU) buybacks.
They issued a snide profits warning mid afternoon yesterday instead of at 7a.m too. And not just any old profits warning but a “significantly below current market expectations” warning! (That in itself is a disincentive to invest in it).
I sold a good while ago but if still holding would have sold today or yesterday on my “sell on bad news rule.” Each to their own on whether a share is GREEN or GREEN/AMBER but not sure how a Company behaving as Vertu Motors (LON:VTU) is merits such a generous rating?
They are open about “further pressures ahead” too, so another profits warning is possible. That first profits warning is quite often followed by another one.
Unfortunately I can’t fathom Graham’s continuing enthusiasm for their buybacks.with comments like “One of the main attractions is the strong balance sheet that has enabled large buybacks.”
And what happened after those “attractive large buybacks?” The Money was “ploughed in to buybacks” at over 70p last summer and at over 30% higher than the current share price. Admittedly with the benefit of hindsight, that was not good use of that money. Graham wrote today about future buybacks that “they are confident they are buying below fair value.”
But are they right to be confident about that bearing in mind their admission today that they are facing further pressures ahead? And presumably they thought they were buying below fair value when buying back much higher. They were wrong then and could be just as wrong again.
So unlike Graham, if still holding Vertu Motors (LON:VTU) I wouldn’t be seeing the announcement of an another £12 million buyback as “softening the blow.” I would see it as they haven’t learned from their previous buyback mistakes and are now going to repeat them, as another reason to sell.
Absolutely, Ken. There are just so many bad companies out there doing buybacks that are achieving no more than soaking up the selling pressure from institutions that are unhappy with trading performance. As you say, Vertu Motors (LON:VTU) will have argued that their shares were 'undervalued' when they bought them back at 70p+ last Summer but that didn't stop them falling to 52p since then.
At least Vertu Motors (LON:VTU) have the cash flow to contemplate buybacks, but there are plenty of companies out there that have uncomfortable debt on their balance sheet and don't pay dividends but still think its OK to try and prop up their share options with buy backs. Some of them have even raised fresh equity in placings and then used it to fund buy backs! I won't list the host of unsuitable stocks that have travelled this path, because there are too many to mention. However it begins with the very largest like Vodafone (LON:VOD). How on earth do they justify their stream of buybacks? £30bn+ of debt on a revenue base of less than £30bn, the stock has gone from c£2.30 to 70p in the last ten ten years due to no growth as the business is starved of capital. All surplus cash flow gets consumed by dividends (although these were halved a while back) and a steady stream of buy backs that are doing precisely zilch to benefit the company or its shareholders.
With due respect to you and sparkler Ken, I disagree with you and agree with Graham's comment. We were long term holders in Vertu but sold when I thought a bid from TDR Capital through its various subsidiaries was unlikely at that time as the dealerships TDR had bought were losing money. Vertu at that time were buying back shares as leverage in case a bid came. As car dealerships go it is a very well run still growing company. We are looking to buy in again when the share price settles after the profit warning, I think Robert Forrester is a very good CEO.
Vertu Motors (LON:VTU) JASVFS I remember your cautious comments and were completely against the grain of the prevailing investor opinion at the time, you were right then and maybe right here, certainly a reasonable performance after the warning and moreover TDR went above 10% this afternoon!
Agreed Ken, I don’t trust companies who pull stunts like this hoping it would go unnoticed. It’s like politicians releasing bad news when there’s other worldwide events dominating the news
As we hit the first quarter of the new DSMR, I wanted to give a huge shout out to Graham, Roland, Mark and Meghan for an utterly brilliant job. Change always evokes lots of uncomfortable feelings and so it appears to have been for many readers who loved the previous SCVR (as did I).
I'm baffled by those who have complained essentially that it's not uniquely tailored to their specific preferences or even share holdings (you cannot satisfy all of the people all the time) . It is what it is and I personally appreciate all of the analysis whatever the market cap or geographic listing.
The quality and breadth is astonishing for something that is turned out every single day and just as before, it's simply the cherry on the excellent cake that is all of Stocko's rich quantitive tools.
Thanks to all the writers and contributors and long may it continue.
Yes i agree. A massive amount of useful information. It is up to individual readers to sift through and find what they want.
Warpaint London (LON:W7L) getting hammered again. Instis exiting?
Yes pretty incredible really with only a slight miss to forecasts.God only knows where the bottom will be. In for the long haul now.
Some instis added at 435p yesterday, JP Morgan were sellers
Re Warpaint London (LON:W7L)
Interestingly (I think...) from the notifiable entities that have reported so far, the balance of shares purchased vs sold over the last two days (so incl. Wed) is around 579,727.
This supports the idea that on balance, the larger holders (who have to notify) were (yesterday at least) buying shares from smaller entities (which don't have a duty to notify).
It will be interesting to see what the notices look like for today's transactions.
n.b. I included Wed because Schroders had already started selling...
Warpaint London (LON:W7L) getting hammered again. Instis exiting?
According to Stocko about 700,000 shares traded today, so about 1% of the shares in issue. If that's right it's most likely nervous private investors getting out and institutions hoovering shares up. That's a classic pattern when a previous bulletin board favourite shows some signs of weakness as PIs stampede for the exit to protect their gains.
Of course, a lot of instititional holdings are on behalf of private investors, so it's not easy to tell the difference. Certainly Schroders appear to have just updated and have gone over 11%, they've added about 0.5% to their holding. JP Morgan seem to have been selling.
Not everything is immediately in the public domain so it'll take time for the dust to settle but because W7L is in a takeover situation anyone over or going over 1% must make a declaration by 3.30pm of the day following the transaction - hence why we have a flood of Form 8.3's coming through.
Either W7L was egregiously mispriced before yesterday or the price is now wrong. We'll find out in due course ..
timarr
Tradingview has 3.77m Warpaint London (LON:W7L) shares traded yesterday with a 30 day average daily volume of approx 160k. (890k so far today)
Well you might be right, timarr but 3.8m shares were traded yesterday as it fell 20% which seems like too many to be just private investors selling. If the 20% fall had produced such a bargain for institutions then wouldn't they have been big buyers this morning and sending the price back up? No, I think we can assume that there has been some institutional selling too (rightly or wrongly as we shall find out, as you say).
This is probably related to weak results from elf Beauty (NYQ:ELF). That stock is getting crushed today. https://www.cnbc.com/2025/02/0...
Are there any (other) holders of Mineral & Financial Investments (LON:MAFL) on the forum? Highly speculative, micro cap mining share that I’ve held for some time decent gain in last 2 weeks.
might be a daft question……..for this share and mining shares generally, do mining shares usually trade at or below book value? As to me they are only worth the value of the cash flow of their mines, cash they hold + value of the materials they mine so can’t see why / if mining company’s would ever trade at more than book value unless investors felt mines were undervalued?
Hi Mark, Thanks for your summary on AZN. OK I can see you might feel it isn't attractive at the current level but AZN has been an outstanding FTSE 100 performer for many years and IMHO will be for many more to come with the current pipeline, even if there are a few hurdles on the horizon in both China and the US. I am incredibly grateful that my first share was in Arthur Holden and Sons many years ago, later taken over by ICI in 1982 giving us Zeneca and now AZN. Not all shares have been retained!! I also hold GSK and know which has given me better sleep, to date!
Finally gave up on GSK (LON:GSK) at beginning of year after 25 years of share price decline or flatlining at best! Only reason I kept it for so long was the consistent dividend payment but it cost me. Now of course having sold there is a semblance of recovery. Also own AstraZeneca (LON:AZN) but sadly only bought in last few years and have top sliced some profit. Clearly picked the wrong horse back in 1999 when you look at the relative historical performance!
Thanks to Labour AstraZeneca (LON:AZN) have cancelled, their £450m expansion plans, at Liverpool. So much for growth. GSK (LON:GSK) also have concerns.
Jeremy Pilkington, Chairman of VP (LON:VP.) yesterday spent a good chunk of change on another tranche of shares in the company. He's now bought close to £1.75m since the turn of the year. He owns just over 50 percent which may put some off but he's not spending that sort of amount for PR. I hold.
Missed yesterday’s purchase. As you say one doesn’t spend the best part of £2 m for PR. One can only assume that business activity is starting to improve otherwise why would one shell out such a large amount on shares? A bit of a conundrum given that he is well into his 70s and already owns 50% or thereabouts of the equity.
I hold. A modest position bought at around 570p.
I'm not an accountant. Could someone here who is an accountant speculate on whether Jeremy Pilkington, Chairman of VP (LON:VP.) might be buying shares as part of estate planning to reduce IHT?
Politics alert: presumably Reeves could still say the National Insurance contributions plan is not going to work, shelve it, and instead put up income tax by 1% across the board as she should have in the first place?
They promised they would not increase income tax. They have boxed themselves in. Increasing income tax would hit working people.
How stupid are politicians to be guaranteeing aspects of a budget before they are in office and learning the true facts. People go into politics because they enjoy talking but lack the brains to get a proper job.
No politician who tells the truth gets elected.
Problem is most of the public couldn't handle the truth that we are past the point of getting out of jail all the choices going forward are bad tories must be loving the fact they lost I truly think short of some form of global debt reset there's no way out maybe can be kicked for another couple of decades if they can get rates back down below 2%.
Nail on head stanley1. If Rachel was to quit politics and go manage a FTSE 100 company, I would be putting on a short.
I don't want to divert us off course on this thread, but Merryn SW (in her Merryn Talks Money podcast - recommended listening fwiw) has started to refer to Reeves as 'Poor Rachel' - which always makes me chuckle when listening on the dog walk...
Hadn't picked up on that, that's just Merryn being polite ;-) Essential listening as you say, and Merryn is also one of only a handful of people I follow on Twitter.
Going back a few decades the Labour leader was John Smith. He came across as a solid man of integrity.
Well at the General election he said in a straightforward way that he planned to uncap the upper limit on NIC contributions. Result: he was roundly punished by the electorate and lost.
We get the politicians we deserve. In the UK we much prefer the narrative of an easy answer to the tax/spend dilemma. On the right it tends to be an easily culled reserve of 'waste'. On the left its an elite reserve army of super-rich, just waiting for a tweak to the tax system and HM treasury coffers will be overflowing.
Correct me if I'm wrong but didn't John Smith die before he was able to lead the party into an General Election?
You’re right wildshot. John Smith as elected Labour leader after Neil Kinnock resigned after Labour lost the 1992 General Election. The new leader after John Smith’s sudden death was Tony Blair. John Smith”s daughter, Sarah Smith is now the BBC US Editor.
Spot on Mark can you imagine saying the truth "we owe nigh on 3 trillion state pension will only be payable to those with a total income sub 15k going forward, all benefits need to be halved from today, all public sector final salary pensions won't be honored, civil servant jobs will be halved over next three years.
The country would be in flames in days.
Agreed. Politics is theatre for ugly people.
I think that Rachel Reeves has now tentatively suggested that there will be more tax rises/effective increases at the next budget. Perhaps not income tax but maybe.......
1) Betting Tax
2) Fuel Duty
3) Tobacco
4)Alcohol
5) Pension Reform
6) ISA overhaul.
or a wealth tax or gift tax? John Authers (Bloomberg) pointed out recently that QE had greatly increased inequality, which might suggest that the asset-rich are a reasonable target for a widfall tax.
Don’t give her ideas!!
No, he's right. Please do!
I thought they had scrapped that as many more millionaires may emigrate. They could end up with less tax.
She could tax assets they can’t export.
Think top 10% pay 50% of total income tax Rusty already, its the 20% economically inactive they need to find a way to motivate back into work.
Top 1% pay 28% of all income tax
Top 10% pay 60%...
No judgement, just the stats apparently....
Cripes even more than I thought Cancun.
Having set fire to the house, no doubt she is being to put it out with petrol (literally and metaphorically!).
Think employer ni changes will raise 25 bil income tax would need to go up roughly 4p in the pound to be comparable. Personally I think we are now in such a mess problems are unsolverable 10% of total tax take just pays debt interest payments, 12% goes on state pension and the incoming work generation is the smallest ever who have got to try and keep the plates spinning somehow.
For pretty much every tax now, we are to the right on the Laffer curve. So increasing the tax is actually reducing the overall take.
Its a proper mess all the West is in the US even more than us but given they are the worlds reserve currency they can probably avoid financial checkmate longer than the rest of us.
The issues are already playing out the public in Western countries won't accept cuts even when politicians dare bring them up which then leads people to start to drift into the arms of the far right.
Apologies to all for banging on about this but it really does feel like the days of relative peace and freedom are ending and darker times especially for the younger generation are here.
Anyway last rant on the subject.
I wouldn't underestimate the US consumer's ability to spend their way out of their debt problem... their society is so aspirational and entrepreneurial ( mostly in a good way, ignoring the huge wealth inequalities) that it's amazing how a new car every 2 years can drive an economy... like a super tanker...
Titon (continued) (
think investors and customers should engage with that, some good hard working tax paying people working there .
Personally I like to support them as opposed to Suckerbird and Bozo.
Also they have some really cool in house production custom made engineering , unique and historic - needs some marketing
I doubt they have ever considered marketing the company as a sexy made in uk with some funky processes
“Make essex great again”
Of course 3 million cash , 5 million real estate , 4 million stock they arent under and distress
Tom knows exactky what to do so its an execution job , step by step .
Good “project” for UK investors to support even if its a little heart ruling the head
Very willing to engage with investors and ive arranged to go back in 6 months as Im interested in what the new COO is going to do with workflow (i once did a mechanical engineering degree the only thing i loved was the Toyota stuff on continual improvements
To sum up 8 million cap
Bear
- illiquid
- under performing
- likely to warn again
- sector is average
- not going to multi. Bag
Bull
- real estate 5 mill
- 3 million cash
- 3.5 million clean stock
- CEO proven now has recrruited his “team)
- made in UK
- willing to engage and you feel like a holder of a share if the company
Very limited downside at these levels.
Id have it in my limited portfolio of stupid illiquid micro caps as a 1/2 to 2/3 position .
- titon continued
this is a british company employing british people making things in britain
Morning Graham, thanks for all the coverage this week.
Vertu Motors (LON:VTU) profit warning in the middle of the afternoon yesterday. Long predicted (the warning, not the timing!) given CEO Robert Forresters prophecy of doom interviews last Autumn (that HM Gov had forced an EV supply chain on the car industry and shut down the free market in cars, ICE in particular), so surely Vertu should be on the list for coverage today please?
Chart has been looking gradually weaker since last Spring. Broker cuts to 2025 and 2026 this morning. [I do not hold, currently uninvestable sector in my view]
Thanks for the requests re: VTU, we'll be taking a look at what happened here!
Titon update
Had a couple hours at titon yesterday
- went to colchester first to HQ bit of a graveyard , very confortable , didnt look busy or engaged (very quick observation) .
Having sales / accounting at a different site is not ideal , i had this and likely creates an “us and them” with manufacturing / workforce not “us against the world”
Drove to haverhill , painful drive so of ever closed office would probably lose fhe Colchester team, only 60k rent at colchester so no real cost .
I do think this is an issue really having everyone on site is massive positive for a company to pull together so if CEO cant show his turnaround progress in 18 months Colchester should go z
Haverhill - wow great real estate ! Good location .
In the “books” at cost of 1.5 , was last valued at 5.5 . I think worth a bit more .
CFO - really liked her attitude and the fact shes not a career CFO that jumps around .
With a good CEO and board shes right , if it was a bad CEO / family like before she wouldnt be strong enough.
Put in a hefty provision for stock over ordered in covid
Stock level 5.5 with 1.5 provision
Turnover is 16 million clean stock is 4 million so thats a pretty lean stock , 4 times stock turn .
Could squeeze another million maybe
Cash - 3 million no debt .
CEO - think hes very good been in about 6 months
Manufacturing background , logical , commercial , local (important )
Looks very good hes just hired an COO as the factory looks like some Kaizen / muda / mura / muri thinking will really help lots of operational improvements marginal gains style will take time
Factory looks under utilised and soread too wide , Tom of course knows this and COO hire is key .
New head of sales replacing old perfect last of the old guard of pocket filling under perfrorming previous bunch who were hamstrung by a founding family running it for their benefit for many years .
Clearly they had some really poor contracts before with too low margin (major window comoany ) and the turnover is vanity profit is sanity switch should have turned on but no reason for the company to make profits for shareholders so why bother
. Good to see tom getting out of these and prepared to let them go or get the right price . Hopefully he has the “ability and willingness” to walk away from bad contracts with big customers . CFO should have been waving massive flag on this to previous management (puts question mark on CFO) .
Think Tom within 12 months needs to make progress , if he doesnt Colchester site has to go and take the oain
2 other tnings
1/. I asked one of the workers
“Whats Tom like as CEO and you can be honest”
She said they were never ever listened to before and their morale had been bad for a long time .
Breath of fresh air she said”
That was really good
The absolute standout for me here is
- this is a british company employing british people making things in britain
Excellent stuff, but please put the ticker into the narrative so it comes up in future searches. Thanks
Titon Holdings (LON:TON)
Scuttlebutt can be very useful. Thanks.
Hi, any thoughts on Vertu Motors (LON:VTU) . Profit warning RNS yesterday afternoon ..odd that they didn't do a 7 am release.
UK film and TV production jumps as Hollywood bounces back from strikes. Good read across for Facilities by ADF (LON:ADF). Some interesting updates on their LinkedIn feed recently.
https://archive.ph/iKhrB
Legal & General (LON:LGEN)
Disposing of its US protection business for $2.3 / £1.8bn. Which appears to represent 25x the expected operating profits of $90m for that business (2024). This is not the best ratio for valuing an insurance company, but if you appreciate that you've already read the RNS yourself.
Legal & General (LON:LGEN) now expecting to return c. 40% of its market cap back to shareholders via buybacks & divis over the next 3 years. To save you looking, the mkt cap is £14bn.
Legal & General (LON:LGEN)
On top of the cash injection for the sale of the US businesses the purchaser, the Japanese insurer Meiji Yasuda, is intending to buy 5% of LGEN's equity. That essentially rules out a full takeover, although that wasn't very likely anyway due to the complexity of the business, but it will drive some much needed liquidity in the stock.
The deal also removes any remaining concerns about the sustainability of the dividend. The current near 10% dividend will presumably be supplemented by a buyback of about 10% of the current shares - the board has already committed to raising the dividend by 2% a year and it seems unlikely they'll change this.
Overall the deal doesn't help unravel the complexity discount of the company but it does indicate that the newish CEO António Simões intends to reshape the business, and not before time.
timarr
Medium term this looks like good news for Legal & General (LON:LGEN) shareholders. It would be nice though to see a commitment to a profitable new business model such as Amanda Blanc has introduced at Aviva (LON:AV.) .
My first thought on this announcement by Legal & General (LON:LGEN) was “wow, 40% return to shareholders”.
But breaking down the numbers:
Existing divvy c.9% and 2% per annum growth (29% ish return over 3 years).
Announced buyback £1b c. 7% of average share count on current price.
Leaves a further 3-4% to be allocated (assuming my numbers are correct).
Maybe not as needle moving as it sounds, unless as you mention, this is the direction of travel with further disposals (similar to what Amanda Blanc has done at Aviva).
And if the share price falls, they will be returning an even bigger % of the mkt cap!!!
It's a win-win!!!!!
Good morning Mark, re Ra International (LON:RAI, read my lips in yesterday's DSMR.
More good news for Secure Trust Bank (LON:STB) and Close Brothers (LON:CBG) as Govt pressure builds on the FOS (FT report):
The head of the UK’s Financial Ombudsman Service quit unexpectedly on Thursday in the middle of a major review of the consumer redress system in the financial services sector.
The departure of Abby Thomas, who has run the ombudsman since October 2022, comes as the government is stepping up pressure on all of Britain’s main regulators to ease the burden of rules on businesses in an effort to boost the country’s flagging economy.
The ombudsman has attracted criticism from the City of London for awarding compensation to customers who say they have been mistreated by financial services groups, which industry executives says deters foreign investors from the sector.
Chancellor Rachel Reeves last year called on the FOS and the Financial Conduct Authority to improve how they handle “historic market practice and mass redress events” amid fears that banks may have to pay billions of pounds in redress over motor finance mis-selling allegations.
Will this be the end of the lawfare which stops out economy moving, who knows.
I finance a car for a price I consider fair. The small print which no one reads doesn’t say the sales person got commission.
I get a multi thousand payout for absolutely nothing. It’s a total nonsense.
I find it strange we have to tell people a sales man is making a commission. Unless they are a professional that you are also paying for independent advice
Also car salesman, I've never heard anyone describe them as 'trustworthy', the stereotype is the complete opposite.