Daily Stock Market Report (Fri 7 Mar 2025) - Bund crash, JUST, ECEL, SRAD

Good morning! The deluge of results has slowed down to a trickle.
Wrapping up the report there at 12pm. Have a great weekend.
Macro - bund yields
One of the most interesting macro stories this week was the explosion in German bund yields. The bund is their equivalent to the 10-year UK gilt.
This 1-month chart illustrates it nicely:
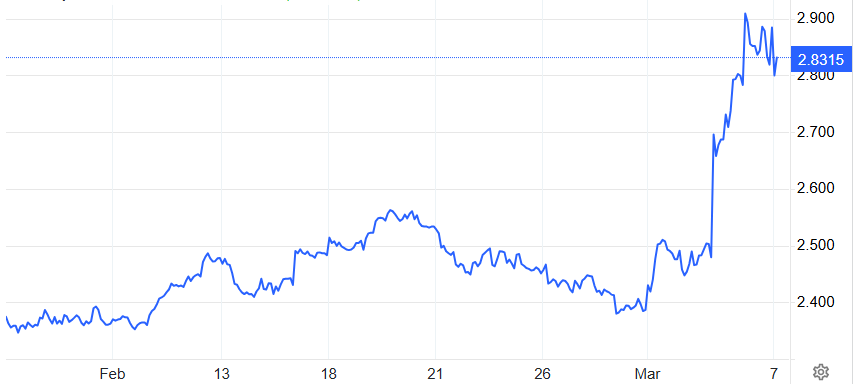
Chart courtesy of tradingeconomics.com
Wednesday has been described as the worst day for German bonds since around the time of the country's reunification in 1990.
It might not surprise you to learn that President Trump is at the heart of the story: he has repeatedly argued that other NATO members do not spend enough on their own defence. Last month, he told European leaders in a speech that "stark strategic realities prevent the United States of America from being primarily focused on the security of Europe.”
European leaders have responded. Following an election, Germany's latest crop of newly-elected politicians have indicated that they will ease their long-standing budgetary restrictions. Defence spending over 1% of GDP will be exempt from existing borrowing rules, and they also plan to set up a €500 billion infrastructure fund - a figure that's higher than their entire annual budget.
The result has been stronger European equity markets - especially in defence and construction - and higher yields.
The UK's 10-year gilt yield has also moved higher this week. Here's the 1-month chart:
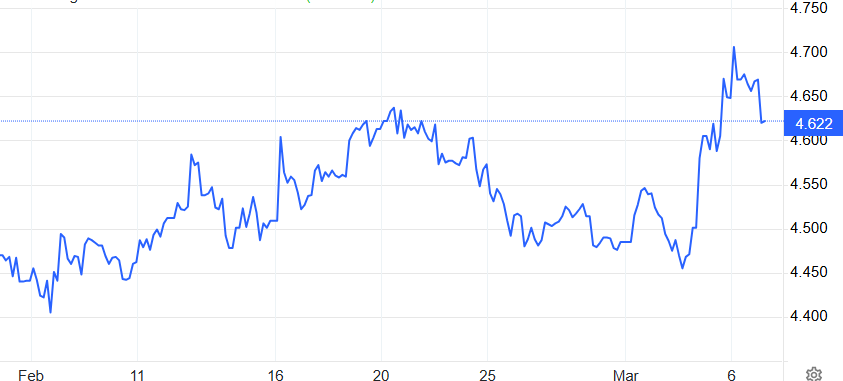
Chart courtesy of tradingeconomics.com
What we saw on Wednesday was a conventional "risk-on" move, with money flowing out of bonds and into equities.
However, these higher government bond yields are also a force for the equity markets to reckon with. If we can now earn 4.6% risk-free from the UK, or in euros 2.9% from the financially very strong German government, our expectations from corporate credit and in turn from equity markets have to be very significantly higher than this.
With attractive real returns available from vastly safer alternatives, perhaps we have to accept that it's logical for micro-caps of questionable quality to trade at the cheap earnings multiples we are currently witnessing?
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Alliance Witan (LON:ALW) (£4.9bn) | Final Results | Return +13.3% trailed benchmark (+19.6%). Average discount narrowed to 4.7%. | |
Just (LON:JUST) (£1.7bn) | Results for the year ended 31 Dec 2024 | SP -15% | AMBER/GREEN (Graham) Tentatively positive on this one; more work is needed. Market clearly doesn't like these results but there are signs of value with excellent capital coverage and very high net tangible assets per share when you include deferred profits. |
Stelrad (LON:SRAD) (£175m) | Final Results | Rev -5.7%, adj. op profit +7.6%. Robust performance continues into 2025, trading in line. | AMBER (Megan) Strengthening margins and the potential for an improvement in the markets are promising. But there are a few warning signs for me, adding an element of risk. The debt position is high, the dividend seems like a distraction and the momentum behind the share price has started to swing in the wrong direction. |
| Eurocell (LON:ECEL) (£149m) | Acquisition | £29m acquisition includes £7m defcon. | GREEN (Graham) This looks to be a highly complementary acquisition. Eurocell needs to use its credit facility to pay for it, as it's nearly an all-cash deal, but the leverage multiple at the end of 2025 is expected to be less than 1x. This would be considered a very modest degree of leverage for most businesses. |
Just (LON:JUST)
Down 16% to 137p (£1.44bn) - Results for the year ended Dec 2024 - Graham - AMBER/GREEN
I might regret looking at this one, as it’s complicated. Just is a provider of retirement products - annuities, equity release, etc.
The headline numbers today are excellent:
Underlying operating profit +34% to £504m. They had planned to double this in five years, but instead they have more than doubled it in three years.
Retirement income sales +36% to £5.3 billion (at a slightly lower new business margin)
Capital coverage 204%, far in excess of what is needed.
ROE 15% (2023: 13.5%), ahead of their 12% target.
Tangible net assets per share have risen to 254p, not far off double the current market cap.
Defined benefit pensions
Just are involved in the transfer of defined benefit pension plans away from their parent companies, and it’s a thriving business. It's now a favourable time for companies to offload their pension schemes to insurers, and they are doing it - this is something we've seen at plenty of listed companies.
Since the beginning of 2022, rising interest rates have accelerated the closure of, and in most cases eliminated, DB pension scheme funding gaps. During 2024, we wrote a record amount of DB new business, up 57% to £5,376m…
We expect the strong momentum in all segments to continue in 2025 and beyond, with multiple small, medium and large opportunities available as corporates of all sizes choose to offload legacy and complex DB pension risk to insurers. Despite record market volumes in recent years, we estimate that only c.20% of the £1.1tn DB market opportunity has transferred across to insurers thus far.
It’s great that a large opportunity still exists in this segment, but DB pensions are no longer commonly available. Sooner or later, it is surely inevitable that this line of business will dry up, when the insurance industry has taken on most of the risks.
Outlook is very positive:
…the normalisation of long-term interest rates [is] continuing to drive demand for our products. Our positioning, reputation and capabilities, including investments in our people enable us to continue to strongly execute as we take advantage of the multiple growth opportunities in our chosen markets.
We have a strong and resilient capital base, with a low-strain business model that is generating sufficient capital on an underlying basis to fund our ambitious growth plans, whilst also paying a progressive shareholder dividend that is expected to grow over time.
The share price reaction is sharply negative which forces us to find an explanation.
Some of the possible negatives in today’s report:
New business margin dropped to 8.7% (previous year: 9.1%), “principally driven by business mix”. This is described as a reversion to the medium-term average.
Accounting profit of only £113m (previous year: £172m). The accounting profit is based on transactions made in prior years and have now been earned by the passing of time, while the “underlying profit” includes profits that have not been earned yet.
The dividend of 2.5p per share doesn’t make for a particularly high yield. Earnings per share were 6.5p and “underlying” EPS were 36.3p. Given the strong capital ratio, maybe a higher payout was anticipated by some investors? That said, market expectations were for a dividend of only 2.4p.
Graham’s view
I lack the time to delve into this in more detail today but I’m happy to take a tentative AMBER/GREEN stance on the basis that it’s potentially very cheap against both earnings and assets.

Please note that on the balance sheet, there is equity of just £924m. However, add in contractual service margin - profits that will be earned over time on insurance contracts - and you get the much larger figure of £2.6 billion, or 254p per share, which is used by the company.
Overall I have a positive impression of this one and I like its prospects, but more research is needed.
Roland's Section - written on 28th January 2025
I have found a piece written by Roland in January that I inexplicably failed to publish. It covers the January trading update from Eurocell (LON:ECEL), a company that has today announced a £29m acquisition.
Apologies to Roland and to readers for failing to publish this when it was written:
Eurocell (LON:ECEL)
Down 4.4% to 151p (£151m) - Year End Trading Update - Roland - GREEN
Today’s update from this window and door specialist confirms that underlying pre-tax profit for the year ending 31 December 2024 should be in line with market expectations.
2024 was not a vintage year for the building materials sector. Like Stelrad, which I looked at yesterday, Eurocell has seen weakness in both of its key market sectors:
...with challenging macroeconomic conditions and weak consumer confidence, further compounded by uncertainty following the Autumn Budget and high interest rates, impacting activity levels in both the repair, maintenance and improvement (RMI) and new build housing markets.
Group sales for the year fell by 2% to £358m. This appears to be in line with consensus estimates of £357m in Stockopedia.
Consensus estimates are for earnings of 15.1p per share, putting Eurocell on a 2024 P/E of 10 after today’s slight fall.
Last year’s revenue drop reflects a 6% fall in sales of profiles, partially offset by a 1% rise in sales from the company’s branch network. This is said to reflect “strategic initiatives for garden rooms, windows, doors and ecommerce activity”.
Despite this limited success, pricing and costs both remain under pressure:
We are experiencing competitive pressure on selling prices in the branches, as well as overhead cost inflation across the business.
The impact of April’s National Insurance and minimum wage increase is expected to be c.£3m per year. Eurocell says it plans to offset this through selling price increases and some cost savings.
For context, I estimate these cost increases represent about 13% of Eurocell’s forecast pre-tax profit for 2024, compared to an equivalent figure of 60%-70% for Halfords!
Roland’s view
Eurocell looks well managed to me and has a good balance sheet. Management reports year-end net debt excluding leases of £3.1m today, despite a £15m share buyback last year.
My sums suggest buying back shares at current levels could provide attractive returns for shareholders, assuming market conditions improve as expected:

A modest valuation and a useful dividend yield should reduce the downside risk of holding the stock while providing a useful and well-covered income:

The StockRanks are also very positive. Eurocell is currently a Super Stock:

I can see plenty to like here and am happy to maintain our previous positive view of Eurocell. GREEN.
Graham's view (7th March): today's £29m acquisition (of which £7m is deferred) doesn't stand out to me as being particularly cheap or expensive. The acquired company ("Alunet") includes four businesses providing a range of doors and windows, e.g. patio doors, timber doors and garage doors. It made £4.5m of EBITDA on £43m of revenue in 2024, and the EBITDA multiple being paid is 6.5x - for this type of business, I would imagine that this is a fair price.
Eurocell points out that it has a £75m credit facility available, which it will need to use to pay for this deal. It still expects to have a net debt/EBITDA multiple of less than 1x at 31 December 2025.
From a strategic point of view, I can't argue against this. Alunet sounds like a highly complementary business. I also can't argue against the price paid. It does create a little financial risk for Eurocell but at this stage not to a degree that would overly concern me.
So I'm going to leave our GREEN stance unchanged. Eurocell's share price has barely moved since Roland's covered it last (it's 149p today, vs. 151p in January), so I hope he agrees!
Megan's section
Stelrad (LON:SRAD)
Down 6% to 131p (£167m) - Final Results - Megan - AMBER
In-line results from high flyer Stelrad haven’t been enough for some expectant investors this morning.
In January, the radiator manufacturer guided to a 6% fall in sales in 2024 after ongoing market weakness. It’s a weakness that has persisted since 2022 when sales peaked at £316m. In 2024 revenues fell to £290m, due to a 6% decline in the volume of radiators sold.
But in that time, the company has been making progress to recover operating margins. And that has most notably been achieved by an 11% improvement in the contribution per radiator. 2024 was the first year in the company’s history that each new radiator contributed an average of more than £20.
While demand has been declining, material prices have also been on their way down which helped support the rise in operating margins. After excluding exceptionals, operating profits rose 7% to £31.5m, equivalent to an operating margin of 10.8%.
It is good to see the company tightening the ropes while the market is weak. If the radiator contribution and margins can hold firm at current levels, the company should be well placed to thrive when demand comes back.
Inventory levels rising
It may be the preparation for a return to higher demand that prompted management to invest so heavily in inventories in 2024. The investment has been described as a move to “enhance service levels”, but the big swing (which also had a knock on effect on cash flows) may have contributed to this morning’s share price weakness.
Year-end inventories stood at £67.3m in 2024, compared to £63.3m at the end of the previous financial year. This was partly a fallout from the sales decline. Cost of goods sold fell by £20m to £201m - inventory is definitely hanging around for longer than it did in either of the previous two years.
What’s more, a £9.5m increase in working capital to £10.1m is largely the result of a stocking up of inventory.
This had a knock on effect on the cash flow statement. Cash outflows from inventories swung from a £13m decrease to a £6m increase in 2024. Operating cash inflows were down 30% to £31.4m (equivalent to an operating cash conversion of 99%). Free cash inflows dropped 46% to £9.6m (a conversion of just 58% from net profits).
Balance sheet vulnerability
A sharp drop in free cash flow isn’t a great sign, especially in light of the company’s propensity to pay an over-generous dividend. In 2024, Stelrad paid out £9.8m in dividends, which was not covered by the free cash flow. As Roland noted in his recent coverage of the company, chief executive Trevor Harvey owns 9% of the company’s shares and therefore receives £880k a year in dividends - perhaps an explanation about why the company continues to deliver such significant payouts.
The high payout and falling cash flows are also sub-optimal given the company’s meaningful debt. Total borrowings were £85.5m at the end of 2024, resulting in net debt at £67.6m. The leverage ratio is 1.55x and net gearing is over 100%.
Aside from the balance sheet vulnerability, this has a knock-on impact on finance costs which remain worryingly high.
Megan’s view: Strengthening margins and the potential for an improvement in the markets are good signs. And this is a generally promising company which generates decent returns and has a historically high propensity to generate cash. It’s also not trading on a massive PE ratio despite recent share price strength and the dividend is yielding 6%. There is definitely a positive investment case to be made.
But there are a few warning signs for me, which adds an element of risk which I am less comfortable with. The debt position is high, the dividend seems like a distraction and the momentum behind the share price has started to swing in the wrong direction. AMBER
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

60 comments
Sigmaroc (LON:SRC)
Further to my brief post this morning regarding the impact if any of the German government's proposed 500 billion euro infrastructure fund on the company. Sigmaroc is divided into 5 geographical operating regions , the Central region where it has 9 production sites supplying lime and lime products covers Germany and Czech. Lime has a diverse range of applications, including use in road construction and asphalt so any significant spending on infrastructure should provide a tailwind.
The share price has, somewhat surprisingly held onto to its recent gains and ticked up modestly to day, contrary to my expectation of the profit taking, which I take as a positive given the market volatility.
Just my thoughts and I talking my own book.
Interesting idea to bring Serica + Enquest together. From what I remember, Enquest have about 3bn of tax losses they can apply against the 40% tax rate. Serica presumably want to benefit from that?
Two interesting businesses that are very cheap getting in bed together, interesting idea. Hard to know what to make of it without more details and a lot of thought!
I was reviewing my position in Renew Holdings (LON:RNWH) this morning. The share price has taken quite a hit (-30%) following the trading update on 24 January. For context, broker EPS forecasts for this year and next have only reduced by c.9% so far.
We all know that most small caps are under a lot of selling pressure recently. What I noticed with Renew, is that the Major Shareholders page seems to show quite a clear pattern, where the AIM IHT portfolio providers have reduced their holdings by c. 10% recently. Canaccord is perhaps the exception, on the list below.
I have access to data which suggests the largest AIM portfolio providers have experienced a reduction in AUM of c.25% since last summer (the AIM market has declined by c.15% over that period). I'm not sure I can share the AUM charts here, unfortunately.
If you combine that with the fund flows data, which continues to be horrendous for active UK equity funds, it really is like trying to push water uphill, in the current environment for UK small and mid caps.
I'll tack on a small note at the end, just to say I'm really enjoying the Daily Stock Market Reports at present, especially the increased coverage of larger caps and occasional macro comments. And the volume and quality of analysis has been very impressive, on busy days like we've had recently. Keep up the good work!
re Serica Energy (LON:SQZ) ... devil is in the detail. Last time, Mercuria would appear to have out negotiated Serica Energy (LON:SQZ) into a defensive deal... that did successfully diversify away from UK Gas but at quite some cost. My "hope" is Mercuria make sure they don't get out manoeuvred by Enquest (LON:ENQ. On the face of it....Sercica could swap its cash for Enquest debt, retain 2/3 of the equity on 2x production. That seems ok if there are tax advantages to the deal... which could mean the earnings enhancement is better than equity share for both parties. This is guesswork on my part.... and Im no expert on the Enquest assets. It seems to me that Serica Energy (LON:SQZ) should be "holding the cards" here - and so either the deal doesn't happen, or it's on good terms. I will hold and see.... but that's not advice. Fingers crossed downside is limited.
About £3bn of tax losses in Enquest to take advantage of!
Synectics (LON:SNX) Following on from recent comments it looks like selling in SNX has stopped (hopefully). I topped up this morning.
Same here, added 50% to my Synectics (LON:SNX) postion late yesterday.
Something has been going on as the total volume for prior three days nearly 700k, compared to approx 55K total for the three days before that.
Not unusal for an increase in volume on a trading update/results day, but these volume suggest a big seller in the market.
Yes, l topped up Synectics (LON:SNX) yesterday around 287p. Now my largest small cap holding. Good to see the bounce today, think this should be around 360p. Whitehall still have around 25%.
Many thanks guys. Yes, I had confused earnings yield with dividend yield. I appreciate the replies. Thanks again.
Is Roland able to give an appraisal of the news this morning from Serica Energy (LON:SQZ). I understand Roland is a holder would appreciate his opinion. I hold (at a loss).
I'm afraid Roland is having a day off!
Ok, thanks Graham.
I'm also trying to make sense of it, Lincs. I have been a shareholder in Serica Energy (LON:SQZ) for many years and traded through the ups and downs. It definitely looks like the tail wagging the dog at first glance
Enquest is stonkingly cheap according to Stocko numbers, but I bought SQZ primarily for income this time around and I doubt that any combined group would continue to pay such high dividends.
Edit: The market would appear to be singularly unimpressed. After the initial enthusiasm, the shares are now being sold off.
What does it mean to be "sold off"? Both up nicely for the day
Not sure what would happen with dividends, interesting to see what they propose. The huge tax efficiencies of merging may allow them to preserve decent dividends - they'll have tonnes of spare cash being generated after tax, but less cash up front as some will go back to shareholders as part of the move - at least, that is my understanding and read of it.
Whether that means they will keep or not decent divis, hard to say, I don't really see it as obvious they would remove them, probably more likely the dividend yield will end up a just being a bit less attractive? Not sure.
Serica Energy (LON:SQZ) Shares back up to 128p now, so not very "sold off".
Looks ok but will the dividend be slashed?
Just (LON:JUST) unravelling today's results from Just is so far above me that I would appreciate any guidance as to why the SP has dropped 16% this morning. Not a sector that I would be happy committing to as I find it too complicated but maybe Graham's skills could be put to use here .
TIA
Just (LON:JUST) I'm guessing (who knows with this market) that it's due to sharply lower IFRS PBT - some may view this as the 'official' earnings figure, although not something I focus on as it is skewed by mark-to-market movements in asset vales (insurers will typically hold bonds to maturity to match liabilities so short-term price movements largely irrelevant). The key things I look at are underlying operating profit, capital coverage and return on equity which all look very positive. Very strange market reaction which looks like some sort of shorting attack. There's a call at 9.30 so worth tuning in to hopefully make a bit more sense of this.
Insurance company accounts have always been a riddle wrapped in an enigma. If you try to buy an annuity, Just (LON:JUST) offers a better income from your capital than do the likes of Aviva and L&G. So perhaps it is not surprising that their revenues have been growing usefully. What I am not in a position to understand is how much extra risk they are taking on compared with their older-established rivals. The same applies to their DB business. For me it is one to avoid - others here may understand the sector a bit better.
A funny story I'm not saying the same would apply now, about 12-15 years back from memory I worked for a major UK life company.
One day we have a meeting where its announced "we are going to start buying in db pension schemes from other parties" my reply was "er we have just closed our own one down why would we want someone elses ?".
Anyway a new top management bod is recruited on seven figures and his teams sales of db pension scheme buy in's quadruple in a year, after 18 months he has exited with a nice quadrupling of sales on his cv to brag about. Two years later its announced we won't be buying in any more db pension schemes due to losing ten's of millions.
I would also add the company in question bought an american business for a billion had no idea about the US market and ended up selling back to the people they bought from several years later for a £1.
Great example of creating shareholder value lol.
You're right they are difficult businesses to get your head around. I think most of their business is in taking on defined benefit schemes rather than annuities. Not an expert on the sector but there have been a lot of new entrants getting into this market, including Brookfield - which suggests to me there is a lot of value here. This makes sense as we now have record number of schemes in surplus looking to do buyouts.
Could someone help me out with a query? Sometime ago I read a quote on Stockopedia, from a Lord Somebodyorother, that a stock with a PE of less than 7 and an earnings yield of more than 7, would always be a sound investment. I am not planning on basing my whole investing strategy on this metric, just curious if I have remembered it correctly. How sound is it? Thanks in advance.
bruce, there is an old adage which says that if a dividend yield is higher than the PE, a share is good value. It is something I watch out for.
I presume you are referring to the dividend yield, not the earnings yield. The earnings yield is the inverse of the PE.
Yes it was Lord Lee's mantra in the early days. Not sure now as they are rare beasts.
He says there are hard to find now, he is happy with lower dividends around 4-5%.
Sounds dodgy to me, see Serica Energy (LON:SQZ) that was over 200p last year, now only 120p.
Sounds dodgy to me, see Serica Energy (LON:SQZ) that was over 200p last year, now only 120p.
And right on cue, Serica Energy (LON:SQZ) announce a possible tie up with Enquest (LON:ENQ)
https://www.londonstockexchang...
timarr
Could someone help me out with a query? Sometime ago I read a quote on Stockopedia, from a Lord Somebodyorother, that a stock with a PE of less than 7 and an earnings yield of more than 7, would always be a sound investment.
Lord Lee. He calls them square shares - PE of under 7 and a dividend yield of over 7. You have to look at debt and growth as well, but assuming the company is well run that would usually work out OK eventually. Critical thing is to avoid value traps.
timarr
Lord Lee used to look for PE less than 7 and dividend [corrected] yield of more than 7. I have found a stockopedia article bou Lord Lee but it doesn't say quite that here: https://www.stockopedia.com/bl...
I think you mean this, about 1/2 way down the article Lord Lee Interview - How he made millions from British small-cap shares
The earnings yield is the reciprocal of the P/E, so a P/E of 7 has an earnings yield of 14%. That means that the company is earning 14% p.a. of what you paid for it. Don't confuse this with he dividend yield.
Just (LON:JUST) results look good but shares down over 17%?
The 4.6% available from risk free gilts is even more appealing for investments held outside of a tax shelter. The 4.6% can be almost tax free whereas returns from shares are taxed at up to 39.5% on dividends and 24% on capital gains. I have kept my investments in shares inside tax wrappers (SIPP and ISA) but I'm now heavily invested in Gilts outside of tax wrappers.
According to Hargreaves Lansdown (LON:HL.) "Interest paid by a gilt is taxed as income" so not tax free, l hold mine in ISAs.
According to Hargreaves Lansdown (LON:HL.) "Interest paid by a gilt is taxed as income" so not tax free, l hold mine in ISAs.
If you're holding low interest gilts where the income is taken as capital gain at maturity then that's a capital gain not income. And gilts are exempt from capital gains and hence can be virtually tax free.
timarr
What about higher interest gilts, l'm getting around 5-6%, that is paid half yearly?
What about higher interest gilts, l'm getting around 5-6%, that is paid half yearly?
What about them? That's income, outside an ISA it's subject to income tax.
timarr
Which was my point, in my first post.
What can you earn on low income gilts?
What can you earn on low income gilts?
I think you need to read up on gilts, this isn't really the place for a fixed income 101.
Look up "yield to maturity".
timarr
It's not "low income" gilts, it is "low coupon" gilts you are after.
The very low coupon gilts that were issued when base rates were close to zero are now trading at large discounts to par (i.e. in the 60s & 70s, well below 100). Quite a few were issued with coupons well below 1%.
They are now trading at gross redemption yields (GRY) of 4-5%. The GRY is the yield if you hold to maturity that factors in both the coupon payments and the redemption of the bond at 100 (the so-called "pull to par").
Since you are only getting sub 1% from the coupon payments, the remaining 3-4% is coming from the capital uplift (because the bond will eventually be redeemed at 100).
There is no CGT payable on the capital uplift because gilts are CGT-free. You will pay income tax on the coupon receipts though. In effect something like 70-80% of your overall return if held to maturity will be exempt from tax.
OK thanks, that is very helpful.
The HL quote is correct but it misses the point. The secret to buying 'tax free' gilts is to buy almost zero coupon gilts that pay little interest. These are trading at a discount to the maturity price, so there is a tax free capital gain on maturity. As an example, consider T26 that pays 0.125% interest and trades today at 97.03p. In Jan 2026, it matures and pays 100p so a 2.97p capital gain which is tax free under current rules.
Thanks, that answers my question, although 2.97% gain is not a lot, unless you are high rate tax payer, probably not worth it. There are plenty of fixed rate savings bonds paying over 4.5%.
although 2.97% gain is not a lot, unless you are high rate tax payer,
It's not an annualised 2.97% gain as the gilt matures in January 2026. As Graham said in his piece, there are rates of around 4.6% available on 10 year gilts. You just chose the gilt against the duration, and risk profile, that you want.
Thanks, but 10 years is too long, l'm not a high rate tax payer, so think l will stick with the higher rate gilts, in an ISA. My TR25 matures today. I will check what the return is, think it is over 5%, not bad but cash ISAs were about the same.
I think that is why RP stated "almost" tax free in his post: The capital gain should be tax free but the coupon (interest) is taxable. Hence the strategy of holding low coupon guilts outside of an ISA once the ISA allowance is used.
How much do you gain on low coupon gilts?
Are gains on gilts still CGT free?
Are gains on gilts still CGT free?
Yes
I wonder if the proposed German infrastructure fund has any bearing on the recent share price strength of Sigmaroc (LON:SRC) ?
Who knows such difficult markets to navigate especially in UK small caps!
Interesting article that could affect Barratt Redrow (LON:BTRW) on bbc local news. https://www.bbc.co.uk/news/art...
Please could you a quick update on Eurocell (LON:ECEL) acquisition today. Looks good to me. ECEL looks very cheap on a forward p/e of 7 ish (pre today's deal)...
I'll add that to the table, Richard!
Eurocell (LON:ECEL) have taken over Alunet - would welcome thoughts if you have time
Any thoughts on Urban Logistics Reit (LON:SHED) today, I hold?
You will probably get n answer in the Investment Trust thread under Discuss. As it happens I bought SHED recently. The discount looks attractive to me. https://www.stockopedia.com/co...
Good morning team.
Encouraging results from Stelrad (LON:SRAD) today. I hold. If they can produce these figures in a difficult market it bodes well for when the construction market picks up again. These are the times where good companies get leaner and more efficient.
Having said that, I am braced for another market sell off , as seems to be the norm at the moment.
Your thought would be appreciated as always.
We'll be checking this out I'm sure, Revs8.
Am comfortable also with Stelrad (LON:SRAD) results this morning. Was slightly sceptical re its "Investment in working capital", but as most looks to be inventory, perhaps its ok.
Recovery in its markets seems to be taking its time as they were talking up recovery in parts of Continental Europe a year ago as a green shoots signal, but they are weathering the sector downturn well, paying very decent divis while we wait and seemingly improving unit profits at the same time.
Lots to like imo.
Stelrad (LON:SRAD) your prediction is looking correct Revs - down 6% so far, in line results getting a hammering (again)…