Daily Stock Market Report (Fri 7th November 2025) - ITV, RMV, MEGP, REC, RGG, IDOX, RGG

Good morning! It's a quiet end to the week - I'm hoping to update our spreadsheet after finishing today's report.
All done for today - quite an interesting set of results and profit warnings in the end! Have a great weekend everyone.
Spreadsheet accompanying this report: link (last updated to: 31st October).
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our View (Author) |
|---|---|---|---|
| Vodafone (LON:VOD) (£20.8bn | SR96) | Vodafone and AST SpaceMobile announcement | VOD and AST SpaceMobile announce a new EU satellite constellation and select Germany for Satellite Operations Centre. | |
| Rightmove (LON:RMV) (£5.0bn | SR38) | Trading Statement | SP -13% Reaffirms 2025 guidance: revenue growth 9%, 70% underlying operating margin. New 2026 guidance: revenue growth 8-10%, underlying operating profit growth 3-5%. This is lower than current market forecasts. | BLACK (AMBER/GREEN) (Graham) |
ITV (LON:ITV) (£2.5bn | SR82) | Confirms that it is in preliminary discussions regarding a possible sale of its M&E business to Sky for an enterprise value of £1.6bn. |
PINK (AMBER/GREEN) (Graham) | |
Coats (LON:COA) (£1.52bn | SR59) | 4-month period: market conditions remained subdued but performance was “in line with our expectations”. Outlook unchanged. | ||
Wizz Air Holdings (LON:WIZZ) (£1.03bn | SR28) | The orderbook of 273 total aircraft remains intact, but the delivery schedule is adjusted “to align with a more sustainable and profitable capacity growth trajectory.” | ||
ME International (LON:MEGP) (£716m | SR68) | SP -7% Revenue £311-£318m, PBT £76-79m. (2024: revenue £308m, PBT £73m.) Still exploring strategic options including potential offerors for the company. Laundry revenue +10% and continuing to roll out to new geographies although unusually warm weather impacted demand. A more serious problem in the photo business where German regulations require passport photos to be taken in the citizens’ office or by certified photographers. Outlook: uncertain macro backdrop, but group well-position to deliver growth. | BLACK (AMBER) (Graham) (also PINK) This is a weak update compared to existing revenue expectations for 2025 (£329m) and the new PBT guidance of £76-79m looks set to miss the prior estimate, too. We learned in June that the company was looking for a buyer, with the important context being that we have an 83-year-old CEO who owns 36% of the company. Probably he wishes to sell just to diversify his wealth and crystallise the value of a life’s work, although news that Germany won’t allow Photo-me photos to be used in passports is very unfortunate and makes me wonder if there is a risk that this could happen in other jurisdictions? The photo business has always been treated suspiciously by investors with the previous concern being that people would take passport photos on their phone - although the German law is a step further away from that scenario. ME Group is a high-quality business (QualityRank 97) that has been an important holding in many portfolios for years, and I respect it very much, but let’s temporarily put it on AMBER after this mild profit warning. I’ll happily upgrade it again at the next “in-line” trading update. | |
Idox (LON:IDOX) (£327m | SR66) | Idox Shares which are subject to irrevocable undertakings/ non-binding letters of intent to support the takeover have increased from 22.97% of Idox Shares to c.29.51%. | PINK (Graham) [no section below] | |
Record (LON:REC) (£117m | SR84) | SP -4% H1 FY26 revenue -9% (loss of a client with schemes across multiple products in late FY25). Net income £3.7m (H1 last year: £5.0m). “The outlook for the current financial year relative to market expectations is highly dependent on timing of closing certain projects.” Estimates: with thanks to Panmure Liberum, the FY26 revenue forecast is £40m (previously £42m), and the new PBT forecast is £9.7m (previously £11.2m). Following years also get a PBT cut of about £1m each. | BLACK (AMBER) (Graham) [no section below] This announcement doesn’t officially include a profit warning but the company’s broker confirms that forecasts for the current year (FY March 2026) need to be adjusted lower, and the new PBT forecast is 13% than the old one. In that sense it’s surprising that Record’s share price only fell by 4% today, but that might be to do with the fact the the miss is largely due to reduced performance fees - these are inherently unpredictable and so it’s possible that investors are willing to look past a weaker six-month innings when it comes to these fees (£800k vs. £1.6m in H1 last year). I’ve been a long-term fan of this business and I continue to find it interesting and worthy of research: AUM is at record highs ($110.3bn) and net flows were at breakeven in H1, which is an achievement in itself. Also, the new Record Infrastructure Equity Fund promises to generate a new long-term stream of management fee. They are also launching a Sharia-compliant Deep Tier Supply Finance Fund. Overall, then I remain a fan of this highly cash-generative, financially strong and reputable currency manager. However, to reflect that we have just witnessed a profit warning and with potential further vulnerability depending on the timing of customer agreements, I am going to downgrade our stance on it to neutral. | |
Scancell Holdings (LON:SCLP) (£102m | SR9) | Presented positive data (first reported in July) from the ongoing Phase 2 SCOPE trial of its active immunotherapy at the Society for Immunotherapy of Cancer (SITC) annual meeting. | ||
| Rentguarantor Holdings (LON:RGG) (£28m | SR10) | Conditional Subscription for approximately £2.5m | SP -42% Has conditionally raised £2.5m at 12.5p “to support the Company's growth and facilitate a wider marketing campaign, to be strategically timed with the passage of the Renters' Rights Act.” Each new share is accompanied by a warrant with strike price 17.5p. Secondary share sale: the CEO, founder and largest shareholder conditionally sells 2.2 million shares at 12.5p (his holding before the announcement was 46.8 million shares).. | RED (Graham) I’m relieved to see that I was AMBER/RED on this in August even though I was glad to see it join AIM. Invesors will probably have to vote this fundraise through as the alternative is to potentially see the company’s cash balance run thin. Accordingly I am going to downgrade my stance on this to fully RED as this runs the risk of becoming just another cash-guzzler on AIM. |
Medpal AI (LON:MPAL) (£28m | SR10) | Launches MedPal.clinic, its retail pharmacy website. | ||
| Cyanconnode Holdings (LON:CYAN) (£22m | SR9) | $5.25m Loan Note to support AMISP Tenders | Lender is a Middle Eastern climate technology company. Funds will be used as “Earnest Money Deposits” when tendering for smart metering contracts. | |
CAP-XX (LON:CPX) (£18m | SR22) | Revenue of A$4.94m (+7.6%), loss after tax A$3.93 (last year: A$6.14m loss). Four months since year end: bookings +25.4%, billings +12.1%. | ||
Argo Blockchain (LON:ARB) (£15m | SR7) | SP -10% High Court of Justice in London has approved the convening of creditor and member meetings. The Restructuring Plan is expected to be implemented on or shortly after 8 December 2025. As previously announced, existing shareholders will have their interest diluted to 2.5%. | RED (Graham) [no section below] Unless I'm mistaken, Argo's current market cap (£13.7m) suggests that the recapitalised company - with existing shareholders owning 2.5% of it - will be worth £550m . I don't know how this can possibly make sense. 2024 results showed the company mining 2.1 bitcoin per day, generating revenues of $47m, adjusted EBITDA of $5.7m, and a net loss of $55m. |
Graham's Section
ITV (LON:ITV)
Up 14% to 77.28p (£2.91bn) - Year-end Trading Update - Graham - PINK (AMBER/GREEN)
This is a tiny RNS in word count, but it has resulted in a c. £360m change to the ITV market cap today:
ITV plc ("ITV") notes the recent press speculation and confirms that it is in preliminary discussions regarding a possible sale of its M&E business to Sky for an enterprise value of £1.6bn.
There can be no certainty as to the terms upon which any potential sale may be agreed or whether any transaction will take place. A further announcement will be made in due course if appropriate.
ITV published a Q3 update which we covered briefly in yesterday's update.
Let’s explore that update in a little bit more detail now.
The tables in the update shows that Media and Entertainment division was responsible for the majority of revenues in the year-to-date, but not by much:
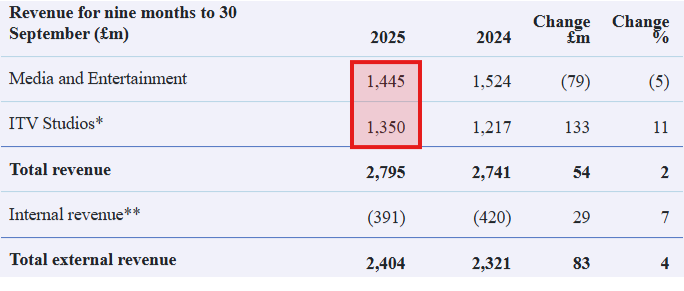
M&E is the broadcaster/streamer that includes the company’s linear TV channels and ITVX, and also their YouTube channels.
ITV Studios is the large media production and distribution group responsible for a wide range of familiar content - The Voice, Love Island, The Chase, I’m a Celebrity, etc.
The Q3 update shows M&E revenue falling by 5% year-on-year, although there were pockets of growth within that - digital advertising revenue up 15%. Market share of commercial viewing on linear TV fell slightly, from 32.3% to 31.8%.
In a difficult advertising environment, the company has been doing ok - there is no doubt that it has been challenged by the conditions.
For example, if I scroll back further, to the interim results, I find that the M&E division produced an adjusted EBITDA of only £35m - less than half of the prior year. That gives an uninspiring EBITDA margin of less than 4%, on £955m of H1 revenue. The absence of a major football tournament in 2025 explains only some of the weakness.
ITV Studios generated much higher margins: £107m of adjusted EBITDA on £893m of revenue (giving an EBITDA margin around 12%).
So the studios business has produced more profits and at higher margins than M&E. This is also true for FY 2024 (ITV studios: £299m adjusted EBITDA, M&E: £260m adjusted EBITDA).
Graham’s view
I’m inclined to upgrade our stance on this by at least one notch - to AMBER/GREEN - to reflect the arrival of a catalyst that could unlock a huge amount of value for shareholders.
Sky’s motivations are pretty obvious - why not add more channels and streaming services and enjoy even bigger scale? Sky News (ironically reporting on the story) says that the goal is to create “a UK-focused streaming giant”. ITVX has become a valuable asset, it seems.
The suggested enterprise value of £1.6 billion would be 6x last year’s adjusted EBITDA. Remember that EBITDA multiples should be much lower than P/E multiples - so 6x EBITDA might actually be a reasonable price for everyone.
ITV reported net debt of £586m at the half-year, with a low leverage multiple of 1.1x. The injection of £1.6bn, if it happens, could eliminate some or all of the debt, expand the Studios business, and still allow for a large surplus to be returned to shareholders.
Exciting times for the company's shareholders - well done to anyone who was contrarian enough to invest in this cheap big-cap.
Rightmove (LON:RMV)
Down 13% to 568p (£4.39bn) - Trading Statement - Graham - BLACK (AMBER/GREEN)
(At the time of publication, Graham has a long position in RMV.)
I’ve been invested here since 2018. It has been an ok investment - paying a small dividend, reducing the share count, and maintaining very high market share in the UK property portal market.
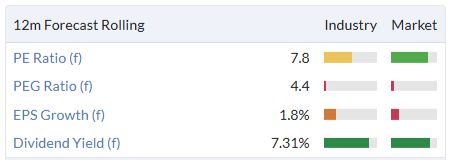
EPS was 17.7p in 2018, versus 28.7p expected this year.
Today’s update has been met with dissatisfaction by the market. The key news is that “Rightmove is accelerating technology investment to build an even stronger platform and to drive sustainable growth over the medium to long term”.
More investment means more spending and lower earnings in the short-term.
Bullet points from the business update:
>80% market share in consumer time per Comscore (nothing new here), and more usage of Rightmove’s home-moving tools.
Estate agents: highest retention in H1 2025 for over 10 years.
Growth areas (Commercial Property, Mortgages, Rentals): 7% of H1 revenues vs. 5% in 2023.
And this is where they will be investing more:
Consumer - the Rightmove App, and AI search capabilities.
AI-powered operations - back-end infrastructure and AI interfaces.
R&D to fast-track new growth opportunities.
The goal: “enhanced network effects, more efficient operations, and sustained double-digit growth.”
Outlook: reaffirming 2025 guidance which is 9% revenue growth (previous guidance range was 8-10%), 70% underlying operating margin.
2026 guidance: revenue growth 8-10%, with underlying operating profit growth 3-5%, “reflecting the increased investment outlined above”.
I think this is technically a profit warning, as the market had previously pencilled in profit growth of about 10% for 2026.
The company provides this handy table outlining their guidance and ambitions:
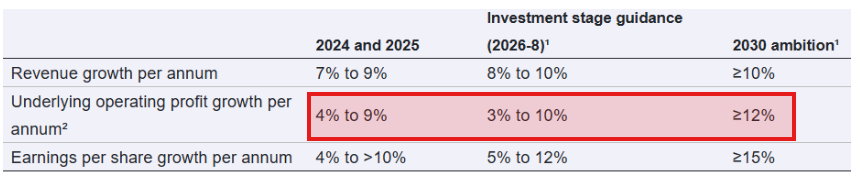
Note that earnings per share can grow faster than operating profit growth due to factors including share buybacks.
Market update: there has been a continuation of existing trends in the property market, e.g. favourable mortgage rates vs. last year (albeit higher now than was expected last year), listings continue to increase, and prices are "broadly flat at a national level compared to last year”. Some uncertainty around the forthcoming Autumn budget.
CEO comment:
“AI is now becoming absolutely central to how we run our business and plan for the future. We are already working on a wide range of exciting AI-enabled innovations for the benefit of our partners and consumers, and see vast potential utilising our leading reach and connected data. We are investing to accelerate our capabilities, which we are confident will create an even stronger platform and higher-growth business over time. We aim to further advance our leading digital position in the UK property ecosystem.”
Graham’s view
The share price reaction is perhaps a little harsh in my view, but I can see why investors might not like today’s update.
Firstly, it is technically a profit warning, albeit one that has been dressed up in the best possible way: as a voluntary decision to invest for the medium- to long-term.
The most common criticism of Rightmove as an investment is that it doesn’t grow fast enough - that it’s a high-quality business but that the funds it earns can’t be profitably invested.
In that context, I don’t mind the company using more cash for investment for a few years, to see if it can turbo-charge growth. I think it’s fair to say that the possibilities of digital investment are probably more exciting now than they were a couple of years ago, and so the timing of this decision does make some sense to me.
The negatives?
Well, a sceptic could argue that the company could be starting to feel the heat of competition from Onthemarket (and others). It could be argued that the decision to “accelerate growth” is not as voluntary as Rightmove are making out, but is instead required in order to stay ahead of determined competition.
Personally, I’m a little uneasy when I hear Rightmove say that “AI is and will continue to be central to all that we do”. I never thought of this as an AI stock before, and I don’t think of it as one now. It’s a marketplace platform and while it will certainly use AI in various ways - dealing with search requests, user queries - I don’t see this as being core to the investment case.
So I am a little worried that the company might be getting distracted by investor euphoria around AI. It must be difficult to ignore the extreme valuations attached to AI businesses, and tempting to try to get involved in some way.
I was AMBER/GREEN on this last time. Given that it is still profitable, and that profits are still growing, and that it remains a fundamentally high-quality business (QualityRank 95), I’m reluctant to downgrade our stance on this. The P/E multiple is now less than 20x which historically I have viewed as a sign of a potential buying opportunity here.
Therefore, I am perhaps controversially not going to downgrade our stance on this one today, despite the cuts that analysts will be making to their profit forecasts for the next few years. As before, the debate around this stock is to do with merely how fast profits will grow - and the range of possible outcomes doesn’t seem very wide to me. Either profits will grow at 12%+ by 2030 as planned or perhaps growth will get stuck in the single digits.
This is a luxury problem to have in business and so I do think a moderately positive stance remains justified. But do bear in mind that I am talking up my own book here!
The chart is not encouraging in the short-term and in StockRank terms this is a Falling Star, which is considered to be a losing style:
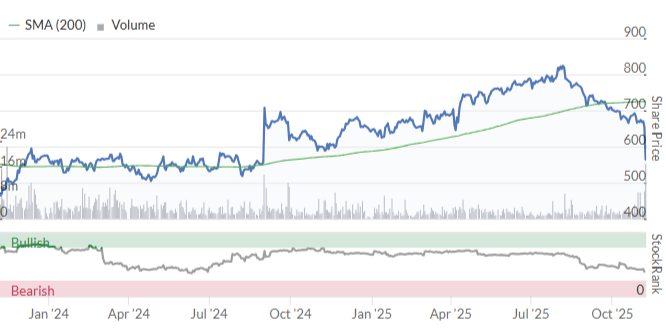
Putting on my technical analyst goggles, I would see long-term support above 500p and I’d also bear in mind that the rejected takeover offer last year was at 775p. I don’t think the business has changed all that much since then!
Rentguarantor Holdings (LON:RGG)
Down 42% to 12.95p (£16m) - Conditional subscription for approximately £2.5m - Graham - RED
This is an illiquid share with 69% of shares held by its top holders according to the StockReport, so dramatic moves are always possible, but even so - this is a stunning fall today.
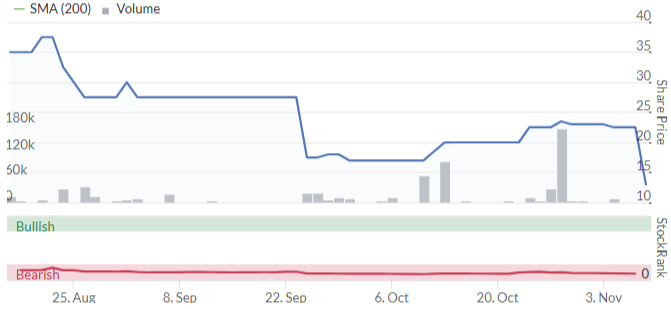
I’m relieved to see that I was AMBER/RED on it in August even though I was glad to see it join AIM.
The valuation at £40m seemed rather high to me, and the company apparently agrees as it is happy to raise money at an enormous 44% discount to last night’s close (12.5p vs. 22.5p). Worse, the new shares each come with a warrant that can be exercised at 17.5p, which means more dilution if the share price recovers.
If the warrants aren’t exercised, the amount of dilution is admittedly not huge: only 20 million new shares on top of 125 million existing shares. However, it’s the extremely low pricing of the fundraise, compared to the existing share price, which indicates just how out of line that prior share price was.
Also, this debacle is combined with news of the founder-CEO looking to trim his holding a little, at 12.5p. I guess he must agree that it was radically overvalued at 22.5p.
Graham’s view
While the company trumpets growth and marketing as the reasons for the fundraise, they also say:
The net proceeds will also, to a lesser degree, be utilised towards maintaining the Company's working capital position as it grows.
Interim results showed the company earning H1 revenues of just under £1m, an operating loss of £400k+ for the six months, and finishing up with cash of just over £700k.
I think investors will have to vote this fundraising through as the alternative is to potentially see the company’s cash balance run thin. Accordingly I am going to downgrade my stance on this to fully RED as this runs the risk of becoming just another cash-guzzler on AIM.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

66 comments
ME International (LON:MEGP) (I hold). I was a bit surprised at the market reaction to the year end announcement yesterday given the profits were pretty much in line with the mid year forecast that they issued. Only downside is sales to analysts forecasts but that isn't a million miles away from the midyear position also H1x2. The fact that they are making profit before tax of 25%, selling Photo's and Washing services, is outstanding. Plus with a potential sale on the cards I would have expected a bit more stability on this announcement, particularly after the midyear price drop. At a current EV/EBITDA of 5 the sale price could be a significant upgrade (ca >300p), and the owner will definitely be looking at getting the best return. Lets face it for a business of this nature they've done extremely well over a long period of time with constant growth in Operating Margin (excluding COVID). I'd be interested in counter arguments - I'm thinking of topping up.
Rightmove (LON:RMV) I found it interesting to compare the old style property search experience on RightMove with AI-driven searches on Jitty.com . If I were looking in a small search area, I'd rather just get a notification of each new property as its comes up without any fancy AI getting in my way. But if I had a large search area with lots of properties, then AI might be helpful. I guess that this is what RightMove management are worried about.
Rightmove and Autotrader are both similar businesses, property and vehicle advertising portals. Both are likely to be at serious near future risk, specifically from AI, but also Social Media and Google Ads. etc.... Estate Agents and Car Dealers (the main source of both companies profits) are aware of this and are actively looking to find an alternative at a more realistic price. Just search for a " Bungalow for sale in Watford" on Google using the AI function or "VW Polo near me" to see how well AI performs. Both Estate Agents and Car Dealers are not having the best of times at the moment, while Rightmove and Autotrader are celebrating increased profits at mouth watering operating margins. This doesn't sit well with Agents or Dealers. Sentiment is definately not positive for both of these companies and the share price is witness.
This must surely depend on each companies proprietary (clean) data bases. They will have exhaustive data on local characteristics. The Uk has been very slow to exploit these databases, I think because they have not been kept clean due to lack of IT investment in the past. There should be many areas where this could become a BH style 'moat'. Providing analytics no one can match.
I thought the primary fuction of any business is to keep their customers happy. Are they happy? In general very unhappy! Perhaps less unhappy with the rental side of Rightmove. Big Moats such as Auto Trader and Rightmove are all very well, but if the majority of your BtoB customers are eager to Jump Ship given the opportunity of a reasonable alternative at a realistic price, then BE PREPARED
People been predicting the doom of Autotrader and Rightmove for ages
They have serious moats that are not easy to overcome. Don't underestimate the value of being a household name that people go direct to without ever hitting a search tool. They also have huge proprietary datasets and integrations / relationships with people in their sectors that would be hard or impossible for others to replicate. No one that has tried to compete with them has ever managed to beat them and customers that try to walk away from them always go running back before long. They also can (and do) leverage AI to build on top of the advantages they already have.
Sure their customers wish they didn't have to pay so much but they DO pay...because they get so much value out of it. And they keep coming back year after year after year despite the grumblings about how much it costs. If it wasn't worth the money they'd walk, but it is, so they don't (or at least never for very long).
think AutoTrader have made a mistake with their new deal builder, wheree a buyer can reserve a car for £99, which takes it off the market for up to 28 days, or so while they decide if they want it or not!
Can see lots a traders moving to Ebay motors and other platforms, because someone "might" like that vehicle, it means they cannot sell it and I'm sure a large proportion will pass. Meanwhile its been sat at the dealer doing nothing ...think they might have shot themselves in the foot
I assume that's on an opt in basis and the dealers will not stay using it if it isn't working? Usual idea is that yes some people will mess around with it but as long as enough good conversions happen then dealers will take the good with the bad, if overall they're up. If not they'll choose to list without taking part in deal builder.
No doubt its great margin for AT for whoever does stick in it and plenty will because it lets you have a serious online offering without the huge upfront investments companies like Cazoo and Cinch put in.
Tan Delta Systems (LON:TAND) I hold
If you heard enough about property sales, crashes etc, this may be of interest from an investment perspective.
Yesterday I posted about an RNS that announced a phase 2 trial with a Global Online Retailer which I am almost certain is Amazon. rmilleree and ISAallowance raised questions some of which I was able to answer but the latter asked about competition. I contacted the CEO, Chris Greenwood asking specifically what competitive advantage TAND had that made this Global retailer choose their oil sensors over other products which appeared to do the same job.
This morning I received an answer which I reproduce below:
"It's fair to say that there a number of different products and techniques in the market for monitoring oil in real time, we do however have a unique technology and approach which allows us to accurately trend an oil from brand new to end of life, which no other product can do.
This key differentiator allows our customers to easily move from historic time-based oil changes to condition based, which generally results in a 30% to 50% extension in oil life with all of the associated operational, commercial and environmental benefits.
Our ability to track normal behaviour (as above) also enables us to identify abnormal events which when combined with our suite of analytics delivers unrivalled actionable insight, further enhancing our customers operational practices.
Our core technology is also very easy to adapt, allowing us to offer a wide variety of solutions targeting specific customer needs, which has been key for this specific opportunity."
Firstly I'm impressed to get a reply so quickly and an explanation that even I can understand. I also took a look at the company website and what they call their "oil database". This contains over 600 different oils that allows the sensor to be calibrated to the specific characteristics of the oil being used. You can read about it here:
https://www.tandeltasystems.co...
In conclusion, TAND does appear to have unique technology and the opportunity to sell their products into a global market of diverse industries where significant cost savings are available to the customer. If you wish to know more, these case studies provide examples:
https://www.tandeltasystems.co...
Seems strange that you can still buy ITV shares below the recent highs, given Comcast offer. Which if you add to the rough capitalisation of the studio business should deliver a share price around 100p, maybe concerns over market dominance and regulation.
Seems strange that you can still buy ITV (LON:ITV) shares below the recent highs, given Comcast offer. Which if you add to the rough capitalisation of the studio business should deliver a share price around 100p, maybe concerns over market dominance and regulation.
Last year Temple Bar suggested ITV Studios was worth £3.5 billion as a standalone entity. Add the proposed £2.3 billion (including debt) for the rest of the business and you have a £6 billion valuation compared to a current EV of £3.2 billion, so somewhere shy of 150p a share.
Quite clearly the market doesn't believe in these numbers or that the deal(s) will go though. Streamers and studios are under significant pressure but the value in ITV's back catalogue alone is surely significant.
The market has been right about ITV (LON:ITV) for a very long time while I've been being wrong, but UK market pricing has been badly awry for a while ...
timarr
I hold just a small position I bought when ITV was v cheap, never felt confident to add to it but never felt the need to sell it either, nice dividends and the constant opportunity for some M&A to finally happen.
I'm not sure the studio business can be treated as a completely standalone entity separate from the main ITV business. While they do make some external productions, most of their programmes are made for ITV - I've always had the view that if ITV declines then the studio business will go down with it. Also, if Comcast do buy ITV would they not start shifting programme making to their own studios? Not sure if that is a risk but it could obviously hurt the ITV studio business.
Not that I pay much / any attention to brokers but this morning Barclays has cut price target to 75 and Bernstein has cut to 74.
Is that lack of liquidity the main reason a lot of small / mid caps are falling on no news?
Who knows,budget concerns maybe. My portfolio has had an axe taken to it past 2 weeks
General uncertainty ahead of the budget. Even if the budget is bad news, expect a recovery (to a greater or smaller extent) afterwards.
With all due respect this report used to start much earlier, we’d even have analyses before the bell on potential market movers. What’s the plan going forward or is later and later analysis the new normal?
I feel we need some more Analysts to help Graham out and inject the energy back into these reports.
I have no words!
I am bit speechless as well ...
I'm not sure that is my memory. I remember some days they didn't happen at all, coincidentally often after late night drunken tweets.
ITV (LON:ITV) and ME International (LON:MEGP) if you have time Graham thanks.
ME International (LON:MEGP) I hold, felt update all a bit...flat. underwater now
With a great likelyhood of a property crash next year or so, I would have thought Rightmove (LON:RMV) would not be the best stock to be in. Where I am in south Devon, the number of properties for sale is over four times the usual average number, mainly due to a large presence of second homes and AirB&B owners running shy of new tax rules etc. Very little is selling and three out of four properties on the market are now showing reduced prices.
We are also quite simply at the end of the property cycle - ref. Fred Harrison, the economist!
Thanks for the insight. Living in London I forget that I'm in a bubble where a wheelie bin costs £1m and sells within a month
Nano - i take your point, but maybe next year your wheelie bin will only be worth £750k and wouldn't sell if on the market. Thinking about it - that might help Rightmove (LON:RMV) as many more properties would be sat stagnating on their website? Mmmm. interesting thought!
It looks like you are indeed in a bubble. Prime Central London property harder to sell this year than a labour budget, as landlords try to sell up.
Rightmove (LON:RMV) dip looks like a rentry point for me, after taking the money a couple of years back on the aborted bid from Oz, missing the subsequent rise.
Like their agent customers, RMV have the support of the rental market while sales are sluggish and today's HPI report from Halifax matches last week's lending numbers. I appreciate that forecasts have changed, but the long awaited housing recovery is peaking through with interest rates likely to fall in December and the possibility of some stimulus in the budget.
Halifax "Demand from buyers has held up well coming into autumn, despite a degree of uncertainty in the market, with the number of new mortgages being approved recently hitting its highest level so far this year."
I'm not fussed about my own house price (as I dont see it as an asset). Around me (new wimbledon) small mid terrace 3 beds (fully extended, no driveways, narrow roads where you have to go to the end of the road to turn your car around) are increasingly going on the market at £1m which is far too high imo, but people keep paying up!
I meant near Wimbledon!
I took it as New Malden
I have been predicting a proper house price crash since 2006 as houses were overvalued at the time.
Still waiting.
The biggest two things hindering England's growth and causing societal issues are houses costing too much and a really **** public transport system outside the M25. This has been known for nearly 30 years - and probably longer.
Surprised to see such a big fall - surely everyone knew the housing market had already stalled and the market should have priced this in?
RE: Rightmove (LON:RMV)
Surprised to see such a big fall - surely everyone knew the housing market had already stalled and the market should have priced this in?
The fall isn't due to the housing market stalling but because they're reducing profit forecasts to invest in AI. As usual, the good burghers of the City of London have zero capacity to look beyond the next quarter and their own bonuses.
Perhaps more pertinently it suggests that the wise heads who make forecasts haven't fully thought through the implications for shorter term profitability for data driven companies. Who'd have thought?
In fact the nature of the UK property market, which relies on local knowledge and relationships, probably means Rightmove (LON:RMV) will be OK as long as they invest sensibly. It's quite difficult to disintermediate that kind of market purely by technology, as previous attempts to do so have shown.
timarr
Yes I think it's the increased AI spend that's spooked markets. I must admit Rightmove doesn't feel like the sort of company that would benefit that much from AI - it's basically a marketplace. They give a few examples - mainly around enhanced search and valuation tools - but these feel quite peripheral to the core business and not sure it's going to drive much growth.
Recently there's been no mention (I may have missed something and I haven't read the annual report) of Trainline's investment in AI? I would imagine the iterations of data required to offer rail tickets, especially internationally, is huge relative to housing transactions. Trainline is a big beneficiary of data analytics, so they're either comfortable with any investment and it's BAU, or perhaps it's underestimating the necessary investment to keep ahead?
For me, it is companies with a large number of white collar office workers (particularly those doing fairly routine tasks) that could see the most benefit from AI as these jobs are cut out. I don't have the figures but I wouldn't imagine Rightmove have a massive amount of this type of worker relative to the size of the business.
Rightmove (LON:RMV)
Rightmove have a massive amount of this type of worker relative to the size of the business.
and i would presume then opposite - they have sales of £468 mill and bet profit of £243 mill - there is very few listed companies that can deliver that kind of operating margins at the bottom line.
compare that to foxtons have £185 mill sales and only £19 mill of net profit - so i woudl guess they are waay more top heavy staff costs wise ref
infact per quick copilot check - foxtons has staff costs of £65 mill compared to rightmove £39 mill less costs despite having nearly treble the sales and tenfold the level of profits !
who whole point of the new "one platform" is that ticketing is going to be much simpler than before - all tickets are going to be merged into being provided via the one core provider (i am not saying third party agents like trainline wont sell the tickets !!)- thats less work than the current sytem where theer are numerous different o providers all have their own pricing and ticketing arragmenents that dont tie up.
Yes, no one can argue that the One Ticket initiative is a great idea. Ticketing is a complex process so good luck to them re-engineering the systems and numerous interfaces that would make this possible (and stop it falling over every time there's a software patch.) In the interim Trainline should be investing to exploit the many terabytes of customer behaviour data they already possess. For the time being I'll assume they are...
Trainline (LON:TRN)
them re-engineering the systems and numerous interfaces that would make this possible
well at the moment there are possibly 10-15 different operators sytems out there that manage the process as a provider (not specificlaly ref sellinh the tickets )- you could simply take the one withn the best it and use that for all tickets - so the easy solution is probbaly there right now and simply needs to be added to. for trainline they will deffo go from integrating 10-15 to one - so it has to be simpler for them - as other shave said they may even get tehn job of running the platform here perhaps ? not sure if thats idle spculation of wishful thnking or informed commentary ?
Trainline should be investing to exploit the many terabytes of customer behaviour data they already possess. For the time being I'll assume they are...
well yes thats their job isnt it and they seem to do that welll
The prospect of lower interest rates and a chronic lack of supply would suggest a UK 'property crash' is not something that is imminent.
Well everybody talks about lack of supply, why then are properties not selling? I think it is affordable low rent properties we are short of. Prices in London have come down a lot but properties especially leasehold are not selling as first time buyers are not buying, so holding up the chain. Landlords are not buying as they are leaving the market.
"Well everybody talks about lack of supply, why then are properties not selling?"
I think in part you have answered your own question. The property market is driven by affordability rather than availability.
I notice that in London, there is agreement to reduce the percentage of affordable housing in developments from 35% to 20 % in order to stimulate numbers. This follows on from the rapid decline in completions and will no doubt be driven by housebuilders.
Affordable housing is a catchy phrase, but it can only be two things, one the house size is smaller or that someone else is subsidising the cost. Or possibly both. It is difficult to achieve this in other parts of the UK- not just London.
What ever the outcome in London, I doubt that there will be a UK house price crash. Quite possible that recent buyers in certain parts of the country will be in a period of negative equity, but probably not a crash.
Well everybody talks about lack of supply, why then are properties not selling?
well it costs more to move now with seond home stamp duty and the like (thats before we get stuff in thne buedget) - volume of sales and prices should necessariuly bne totally connected at the hip. facts are house prices are still going up even if thats below inflation increases. even ref moretgages and tehn like with added moeny laundering its simply not as simple to get a mortgage as it was back in the day for some.
With a great likelyhood of a property crash next year or so, I would have thought Rightmove (LON:RMV) would not be the best stock to be in.
There's no historical precedent for a house price crash while interest rates are falling, although a broader economic crisis could cause a fall in prices. Generally crashes only occur when owners are forced sellers, as otherwise people tend to hang on until prices recover.
Rightmove (LON:RMV) is an interesting case study on the side-effects of AI - it's going to force existing incumbants in many industries to invest to maintain their market position and who knows what the outcome of that will be? AI picks and shovels players will presumably be best placed to pick up the investment cash for the next few years.
timarr
With a great likelyhood of a property crash next year or so
where does this expectation come from - i thought we had a shortage of housing in this country ?
dont get me wrong some fluffy parts of the country may suffer if prices have been silly season previously - for most places though in built up areas where people just need a home that does the job - i dont see the prices coming down when there are more new people turning up than homes to house these people - those numbers are pretty basic - we have more new peoplem arriving than homes to house them - thats crazy.
i would say anywhere thats been holiday home central has potentially been in a bubble that doesnt really represent your average uk home.
There is no such a thing as an imminent property crash and no real evidence to support it. The market is not going to fly but it’s not dead. Also the practice on Rightmove and the reduction in house prices from their original asking price is nothing new.
Anyone with a bit of financial knowledge can study the banking sector and their recent earnings and reports to confirm my view.
Anything else it’s just scaremongering.
Take it from someone that rents tens of properties and always out looking for any new opportunities.
All the best
I take it you are not renting out properties in the UK?
I take it you are not renting out properties in the UK?
i cant speak for yiannos - but my viewpoint alignms with his - albeit i would never say never ref crash - just zlich evidence.
i do have property rental yes - and i deal with many clients who rent property - some ara leaving the market - but i see zilch evidence that prices for standard residential properties are about to crash. if they are being sold to owner occupiers thats not bad thing.
my thoughts are like anyone else guesswork - but with house prices having risen below inflation since 2023 - i think there is very little bubble in the market - the reality is house prices have dropped in real tems since 2023 - thats a pretty healhy position - going up in actual numbers but no runway jumps in prices.
There are some amazing opportunities up North (Liverpool-Manchester-Chester) for people that know how to shop around and how to rent properties to foreign students.
They are willing to pay upfront 10 months (duration of a student rental contract) as well.
It’s like any other business-full 24/7 commitment.
All the best
'It’s like any other business-full 24/7 commitment'
That's why I like investing in shares - you don't get a phone call in the middle of the night saying the boiler has blown up.
ME International (LON:MEGP)
Rightmove (LON:RMV)
You can get it in the morning though in a rather similar but most costly way if you are not helpful -:)
All the best John
I am yes.
80% of them is renting properties for uni students.
How are you going to deal with the RRB?
Property prices have had so many "reasons" to crash in the UK, yet they have not in last decades. Stagnation / lower YoY increases in value very normal in a 4% mortgage world. If we go down to 3.5% they'll start to move a bit more again imo
Don't understand how anyone can still be expecting a crash at this point. Interest rates return to somewhat normal levels and property price growth returns to somewhat normal levels too. Doesn't mean its a crash...
Don't understand how anyone can still be expecting a crash at this point
i think if you look you will always find some people predicting a crash at any time thats life - its like the old chesnut of how long will your hair get before man united win 5 in a row - some think its a bit of short term fun expecting that to happen sometime - not realising they are making their life damn hard work for the forseeible future and probably beyond.
Yes we have lots of inward migration but that does not mean that they are able to buy property. Prices are coming down because there are no buyers.
House prices have been falling relative to incomes for several years, especially in London. Long may it continue, but it's not as if we're sitting atop a market peak.
The crash in Rightmove (LON:RMV) share price comes a day after the interest rate is re-afirmed at 4 percent and 19 days before Reeve's Budget announcement, never mind AI which may or not complicate things. My story is that I needed a new roof back in July and sold Rightmove to fund it although the share price was still going up. For once my investment had a happy ending yet today I was considering buying in again to catch the dead act bounce. Second thoughts about volatility in the housing market made me add to Thor Explorations (LON:THX) .
International Consolidated Airlines SA (LON:IAG) in line update. Continuing weakness in the trans Atlantic numbers. Mr Trump getting the blame for that. I hold. Although it might get the Spanish Archer if it falls.
Probably as much to do with the very unpopular changes to the BA Executive Club as much as anything else. After the changes were announced, there was a large amount of rival Airlines giving customers favourable status switching to their own reward schemes.
International Consolidated Airlines SA (LON:IAG) should perhaps look closer to home for some of the blame...
ITV (LON:ITV)
ITV plc ("ITV") notes the recent press speculation and confirms that it is in preliminary discussions regarding a possible sale of its M&E business to Sky for an enterprise value of £1.6bn.
https://www.londonstockexchang...
Assuming the value of the other part of the business, ITV Studios, is north of £2 billion - possibly north of £3 billion - then ITV's current market cap of £2.5 billion may be offering considerable value ...
timarr
Don't you just wish all share purchases were like this - I bought back into ITV yesterday and sold out for a nice profit this morning, held for less than 24hrs - and I'm not normally a trader! But alas, my good luck was to end - tumble dryer has packed up and needs replacing.....and there goes a chunk of my profits. Ce La Vie :-)
and for every success story there is a sad one, I was thinking of buying ITV yesterday as it was below my last sell price, one more day I thought as I have a habit of buying too early, the rest is history
My first thought.... wouldn't this takeover of ITV (LON:ITV) be dead in the water from the starting blocks, given how dominant Sky would be in the M&E space in the UK post acquisition? This could get caught up in CMA purgatory for years?
My first thought.... wouldn't this takeover of ITV (LON:ITV) be dead in the water from the starting blocks, given how dominant Sky would be in the M&E space in the UK post acquisition?
The issue is likely to be advertising where the combined entity would have over 70% of the UK market. In commercial programming terms ITV is already dominant.
More interesting question is who else might take an interest, both parts of ITV are unique assets.
timarr