Daily Stock Market Report (Friday 18th September 2026) - DNM, RCN, SCT, KIE

Bank of England left Bank Rate unchanged at 3.75%, as expected. The vote split on the MPC was six in favour of holding rates and three in favour of raising rates - the same split as we saw at the last meeting.
But while a rate hike has been postponed, it is now firmly on the horizon:
There has been little evidence so far of material second-round effects in price and wage-setting. However, the risk of such effects, against which policy needs to lean, is greater the longer higher energy prices persist or are more volatile.
Inflation is seen reaching 4% in Q1 of next year (double the BoE’s target), and household inflation expectations have “remained elevated”.
In relation to the Iran conflict, “given the passage of time since the onset of the conflict, most members placed more weight on energy prices staying higher for longer in the absence of a lasting de-escalation”.
Overall, “risks to the inflation outlook were tilted further to the upside compared with at the time of the previous MPC meeting”.
Six members of the committee still voted to maintain rates. But traders now expect a rate hike later this year and then possibly three hikes next year, taking Bank Rate all the way to 4.75%.
In the words of Governor Andrew Bailey: “if the conflict in the Middle East persists for an extended period, as appears to be the case, and the risk of second-round effects emerging increases, it is likely that policy may have to tighten.”
Barring a miracle, we can expect a significantly higher interest rate environment next year.
Overnight market movements:
The FTSE is down 0.1% at 10,800
S&P 500 is up 0.3% at 7,660
Brent crude (November) is down 1.3% at $100.30/bbl
Gold is up 1% at $4,385/oz
Bitcoin is up 1.3% at $77,500
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Investec (LON:INVP) (£5.6bn | SR82) | “The Group is expected to deliver results in line with guidance provided in May 2026. Stable year to date financial performance was underpinned by disciplined execution, strong client franchises, continued balance sheet growth and sound asset quality.” H1 adjusted EPS 3-7% ahead of prior period. | ||
Harworth (LON:HWG) (£583m | SR26) | Board of Harworth remains unanimous and unequivocal in its rejection of the Revised Offer at 177.5p per share. | TAKEOVER (rejected by the Board) | |
Boohoo (LON:DEBS) (£409m | SR49) | Iain McDonald has been reappointed to the Board as Non-Executive Chair. He was on the board between June 2017 and February 2026. “I am a material investor both personally and via the funds managed by my business, Belerion Capital Group, and this is a measure of the degree to which I believe in the potential of the business.” Two independent NEDs join with immediate effect. | ||
Savannah Resources (LON:SAV) (£155m | SR33) | No revenue, £2m loss. Phase 1 definitive feasibility study: US$3.2bn EBITDA, US$1.9bn free cash flow, unlevered Post-tax net present value US$913m, post-tax IRR of 43% and a Post-tax payback period of 1.9 years. Key technical priorities for the remainder of 2026 are to complete the current field programme, advance Fieldwork & Front End Engineering Design, submit RECAPE (environmental compliance report) and secure the bypass-road declaration of environmental report. | ||
Redcentric (LON:RCN) (£98m | SR48) | The final cash consideration for the Disposal was higher than estimated at £124.9m and the Company has received the final balancing payment of £9.46m from Stellanor. | AMBER (Graham) A nice little bonus for Redcentric and its owners with the total received for its data centre disposal being £124.9m, higher than the £122.85m that was expected back in May. However, most of this figure was already received, and the final balancing payment has now been paid. Redcentric carried out a £90m tender offerin July; its remaining business is now purely an "MSP" (IT managed services provider), which is something I tend to treat as a people business, and not something I'd want to put on a very high earnings mutliple. At a P/E of 15.5x currently, a neutral stance makes sense to me here. | |
Defence Holdings (LON:ALRT) (£25m | SR2) | Initial six-month pilot commencing immediately. “Due to the confidential and security-sensitive nature of the engagement, there are limitations on the information the Company is able to share with the market at this time.” | ||
Dianomi (LON:DNM) (£11m | SR85) | For each share, Dianomi shareholders will be entitled to receive 64p in cash and “a Contingent Consideration Unit which may deliver up to 24 pence in cash”. 68% premium (excluding Contingent Consideration Unit).. | TAKEOVER (Graham) | |
Tekcapital (LON:TEK) (£8m | SR45) | Portfolio company Vesari Inc. has engaged a capital markets adviser in connection with a contemplated business combination with a to be identified special purpose acquisition company. |
Backlog
Softcat (LON:SCT)
Up 2% this week to £18.98 (£3.7bn) - Graham - AMBER ↓
Lots of news from this large “IT infrastructure products and services provider”.
We have been moderately positive on Softcat - see Roland in May.
The company has been performing strongly, “supported by customer demand for AI-enabled infrastructure and continued pull forward of some orders due to memory shortages”.
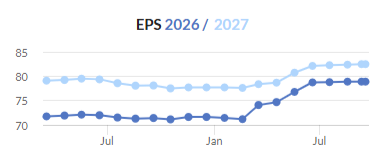
Earnings forecasts have been rising, and the stock has been trading expensively at c. 24x earnings:
Which brings us to the big news this week: the acquisition of GDT, “a leading US-based, multi-vendor IT solutions provider”.
GDT is based in Texas and serves “approximately 700 upper-mid market and enterprise customers”.
Here’s the rationale in a nutshell (the bolded part):
The Acquisition provides multiple routes to value creation. It will create an even stronger Softcat, providing Softcat customers with access to expanded, credible US fulfilment and additional vendor capabilities in high demand infrastructure areas. It will create enhanced value for GDT, through the opportunity to create a broader US-based IT solutions provider via access to Softcat's expansive capabilities and team. In combination, Softcat and GDT will serve as a global partner to customers navigating today's complex IT requirements, backed by an enhanced service delivery capability, unlocking increased competitiveness and the ability to drive cross-sell and increased wallet share.
In numbers, there will be “high single-digit to low double-digit underlying EPS accretion in the first full fiscal year with modest financial leverage.”.
The EPS forecast for the current financial year (FY July 2027) is 82.5p, so I guess this means an additional c. 8p of EPS in FY28?
The cost: enterprise value of $1,050m (£785m) on a cash-free debt-free basis.
This will be paid for via:
Existing cash £100m
New debt facilities of £550m, primarily in the form of an RCF.
Equity placing £350m.
These three items add up to £1 billion, which is more than the enterprise value associated with the deal, so it seems that they are planning to have plenty of spare liquidity.
Graham’s view
My main concern is whether the deal represents good value.
The announcement tells us that GDT had gross assets at $719m (as of Dec 2025) and that it generated net income of minus $58.4m in that financial year. Neither of these numbers is particularly useful. Net assets would be far more interesting than gross assets.
This is more interesting:
For the twelve months ended December 2026, GDT is expected to deliver c.$240m gross profit at a year-on-year growth rate of c.30%, and c.$80m EBITDA on a U.S. GAAP basis.
Based on the 2025 result, I’d have some doubts as to how much of that EBITDA will be converted into real profits.
However, based on Softcat’s statement that it expects “high single-digit to low double-digit underlying EPS accretion in the first full fiscal year”, I think we can pencil in c. 101p of EPS in FY July 2028, vs. existing forecasts of 91.9p.
As for pound figures, the net profit forecast for FY28 was £184m.
The new profit forecast will be based on a higher share count: an additional c. 19 million shares are being issued (close to 10% of the existing share count).
Very roughly speaking, I think this means that net profits will increase by about 20%, thanks to this deal (in order to deliver 10% of incremental EPS, after dilution of about 10%).
So that’s an extra c. £37m of net profits on top of the existing £184m forecast.
I can easily believe that $80m of EBITDA - or whatever GDT’s EBITDA is by 2028 - might convert to net profits around that level.
But it’s also worth bearing in mind that the FY28 profit forecast will take into account higher leverage during FY28, and so the forecast of higher EPS is after the headwind of a higher interest charge. GDT’s real contribution to profits might be more like £40-45m.
Personally, I would not be overly excited about an investment costing £785m that was expected to generate incremental profits of this size.
However, Softcat itself trades quite expensively:
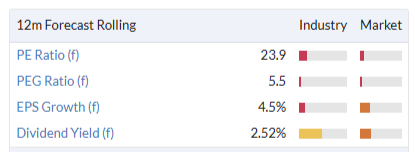
Anything connected to AI infrastructure can be expected to command a full price these days, and US-based valuations tend to be more expensive than valuations on this size of the pond. So I can understand why this might have ended up costing more than $1 billion.
Roland was moderately positive in May. While I do think Softcat can afford to make this acquisition (with the help of some equity dilution), the combination of a high price for Softcat itself, the price for GDT which also looks pretty high to me, and the increased use of leverage, means that I prefer for us to take a neutral stance on Softcat at this time.
Kier (LON:KIE)
Up 29% this week to 313.6p (£1.36bn) - Graham - GREEN ↑
Now let’s catch up with these results which were published on Tuesday:
Kier Group plc… a leading UK infrastructure and construction group, announces its results for the year ended 30 June 2026… and provides an update on its strategic priorities and medium-term financial targets.
Highlights:
Revenue up 7.5% to £4.4bn
Adjusted operating profit +6.7% to £169.8m
Operating free cash flow £206m (121% cash conversion)
Net cash finished the year at £232m, but don’t forget that this number swings a lot. Average net cash during the year was just £11m.
Looking ahead, Kier says it’s enjoying “excellent forward visibility”:
Order book up 8% to £11.9bn, >95% of FY27 revenue and >70% of FY28 revenue already secured.
Changed strategy
Kier announced that it’s pulling out of property development. At housingtoday.co.uk, CEO Stuart Togwell is quoted saying:
“It just made sense to me to put our effort into infrastructure and construction, given the volatility of the property market. We need to concentrate on where the growth is, which is infrastructure and construction.”
This marks a big potential change when it comes to Kier’s capital employed and its cyclicality - and probably a good one.
Let’s compare the company’s previous medium-term targets (from their FY25 results) and compare them to the targets published this week.
- Old revenue target: GDP+ growth through the cycle
- New revenue target: mid-single digit growth.
As they remove the cyclical impact of property development, they feel emboldened to seek mid-single digit growth and try not to track GDP - very nice. As a principle, lower volatility and lower cyclicality mean higher quality.
- Adjusted operating margin: unchanged target of 4.0-4.5%.
- Old cash flow conversion target: c. 90%
- New cash flow conversion target: > 90%, a slight improvement
- Old balance sheet target: “average net cash with investment of surplus cash”.
- New balance sheet target: “average net cash of >£200m, by FY29”. This is not a positive, but it can’t be unwise to keep a healthy cash balance given the swinginess of cash in Kier's industries.
Their new adjusted EPS target is “double-digit growth”. They did not have any specific target growth rate before.
The changes to the medium-term targets aren’t radical, but they are all neutral or positive and in aggregate suggest a meaningful improvement in the quality of the business.
The bottom line is that this will be a more focused business, and probably a higher-quality one.
Trading update: a strong trading update also goes some way towards explaining the improved medium-term targets.
The Group enters FY27 with strong foundations and clear strategic priorities, to make the most of the sizeable opportunity in front of it. In particular, Kier brings good momentum into the new financial year, with recent significant contract and framework awards, strong order book growth and an expanding pipeline. This gives the Group confidence, looking at FY27, that earnings will be at the top end of the Board’s prior expectations.
Graham’s view
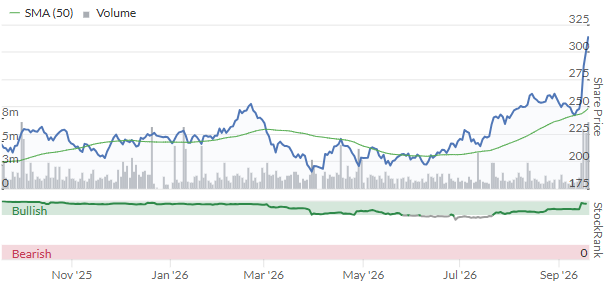
The 29% increase in the share price this week seems enormous, but it’s due to several positive features of this week’s results.
FY27 is doing better than expected
The company is leaving a cyclical, capital-intensive activity (property development)
It’s now focused on two categories, infrastructure and construction, which is easier for investors and analysts to understand.
The new medium-term targets are generally stronger than the old ones.
There is now a double-digit EPS growth target, promising decent growth in the years ahead (easier said than done, of course!)
We were moderately positive on this before - see Roland’s coverage in July
I’m happy to go GREEN now, seeing as this is a Super Stock.
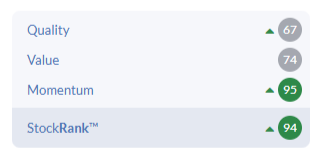
Objectively, I don’t see it as a major bargain at this level (P/E 12x according to the StockReport). So I probably will take us back to AMBER/GREEN in a few months. But let’s respect the very strong momentum here for the time being. This was a truly excellent set of news on Tuesday.
Graham's Section
Dianomi (LON:DNM)
Up 68% at 63.75p (£19m) - Recommended Acquisition of Dianomi plc - Graham - TAKEOVER
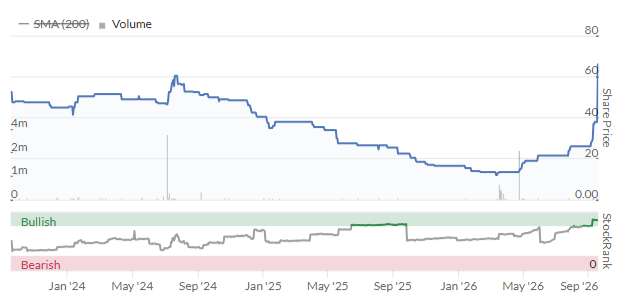
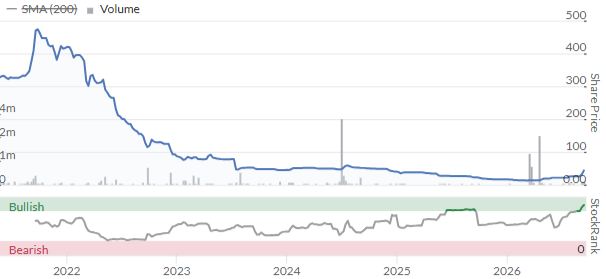
We haven’t looked at this tiny stock since it issued a horrible profit warning back in 2023. I took a neutral stance on it that day, at 47p, as its £14m market cap was supported by about £8m of cash.
The share price drifted lower in the years since then, before today’s excellent takeover offer:
What it does: “premium native advertising for the business, finance and lifestyle sectors”.
In plain English, it sits between advertisers and publishers, connecting them and helping brands to position their ads in high-value websites.
Its recent interim results did not attract comment from us:
Revenue +2% to £13.4m
EBITDA loss £0.1m (H1 last year: £0.6m loss)
I tend to take a pretty harsh line on companies that are loss-making at the EBITDA level: they may have lots of potential, but they tend to make for some of the riskiest investments. Dianomi has been around for a while - it’s a 2021 IPO - and its profits have been sporadic at best.
On the bright side, that EBITDA figure was moving in the right direction and it had retained a very decent chunk of cash considering the small size of the business: £6m as of June 2026.
There was also a nice trading update for H2:
Positive trading momentum has continued into H2, with revenue in July and August increasing by 14% year-on-year.
This update was published just ten days ago - the planned acquisition must have been in the works for a while before this.
The buyer: Taboola, a large New York-based advertising technology company. It’s publicly-listed: Taboola.Com (NSQ:TBLA), with a market cap equivalent to £744m. So this is a small deal for it.
The price: 64p per share in cash, a 68% premium to last night’s close, valuing the company at £19m.
If we deduct the £6m cash balance, the enterprise value for the deal is only £13m, or half of the company’s annual revenues. Potentially quite cheap, if Taboola can wring some efficiencies, synergies and growth out of it?
Taboo will also pay up to an additional 24p per share in cash through “contingent consideration units”:
The payment of additional consideration through the Contingent Consideration Units is subject to a subset of Dianomi's publishers incorporating certain provisions of the Taboola Group's standard terms in their publisher agreements… within the agreed time frame and subject to a minimum threshold, and the net revenue generated by these publishers.
No promises are made that any of this contingent consideration will be paid, but considering that DNM’s closing price yesterday was just 38p, the potential for an additional 24p is significant.
Rationale
Taboola are excited, saying that Dianomi is a “natural fit… with complementary publisher and advertiser relationships, and is complementary to Taboola's existing global footprint.”
And from Dianomi’s perspective, they agree with all of this, adding:
The Dianomi Board also had regard to the environment facing small-capitalisation AIM-quoted technology companies, in which constrained liquidity and a persistent discount to intrinsic value are reflected in depressed share prices.
Graham’s view
Strategically, this takeover makes perfect sense to me. Dianomi and Taboola are similar businesses, even if Taboola is much larger and broader in scope.
Financially, it’s good to see a proper premium being paid, rewarding shareholders and the company for maintaining a very strong balance sheet. And it’s nice to see ordinary shareholders getting to take part in contingent consideration - hopefully these contingent consideration units will pay something out!
And so the takeover trend continues, even at the lowest end of the market cap scale. I agree with the Dianomi board that a "a persistent discount to intrinsic value" is pretty common on AIM these days.
For the record, this is still a failed 2021 IPO: the placing price when it listed was 273p, and it never paid a dividend. So over five years, patient investors from the IPO have still lost over 75% of their original investment.
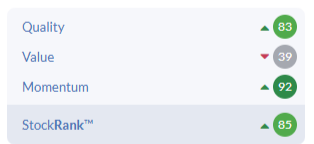
But for those willing to invest at the bottom end of AIM, there were a few clues that things were improving lately, including a very strong MomentumRank and a high overall StockRank. So well done to anyone who did take the plunge here recently!
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

19 comments
Anyone know much about Defence Holdings (LON:ALRT) ? A pivot from Guild Esports to doing something (but I am not sure what) in defence tech.....
Defence Holdings (LON:ALRT)
Someone mentioned this sometime ago when it was around 3p.
My answer is still the same: A future zero!
All the best
Elixirr International (LON:ELIX) not really risen into results Mon, could be telling. Could be completely wrong, to hold or sell that is the question
I think this is a clear hold. At 6x EBITDA this is 50% undervalued. Also heard rumours that Stephen Newton is very frustrated with the share price and is trying everything to get the price moving in the right direction…
Financials/profitability all ok, know some were worried about organic growth from last update, seems constant selling pressure
Elixirr International (LON:ELIX) The problem is that this one is under the radar - it just gets ignored, including by Stocko.
In an RNS on 3/8 it stated "The Group will announce its interim results for the six months ended 30 June 2026 on 21 September 2026". https://www.londonstockexchang... I make that to be this coming Monday but is it in https://www.stockopedia.com/a/... NOPE! Is it in https://www.investorschronicle... NOPE!
Boohoo (LON:DEBS) I would normally shoot myself before even thinking about looking at a ' rag trade' stock but the various developments caught my eye given this seems like a pretty significant proposed transformation. Thinking about dipping a toe here but would appreciate any thoughts on recent developments and the plan proposed. Not that there is anything in a name but the current one has undertones of the past so maybe Debenhams!!!
Looks like Kromek's days of having a good stock rank are over. It was a surprise how well the stock rankings caught this initial move. However, this has always been a poorly run company that has ultimately always failed to deliver. They are super smart scientists but unfortunately don't seem to have a great grasp on business.
Thanks to all who attended the Yellowstone Advisory Private Investor Event on Wednesday night. We heard some great presentations from 4 very different companies: If you’d like to see any of the presentations from Central Asia Metals (LON:CAML) Kenmare Resources (LON:KMR) Currys (LON:CURY) or Rockwood Strategic (LON:RKW) please email info@yellowstoneadvisory.com
A good reminder that there are lots of excellent smaller companies listed on the UK stock market.
If you’ve not attended one of these private investor evenings before but would like to, we have one more event planned for 2026 and it will be on 11 November.
Thanks for the suggestions - I am having a catch-up with TPFG now but I'll cover Kier and Softcat later this afternoon.
Wow... Dianomi (LON:DNM) . Traded c14p not too long ago this year. 64p cash takeover, minimium.
I'd had my eye on this as I work in the marketing sector. Still can't see the value here. And it looked like it was going to zero.
But it makes sense for Taboola, who do very similar ad network services for publishers. Can strip out fixed costs. Cross sell to both sides of the ad network - Advertisers and Publishers.
Well done anyone who held!
Thoughts on the Softcat (LON:SCT) acquisition and trading statement would be appreciated, Graham. Clearly Softcat (LON:SCT) has continued its positive trading momentum with a further profit upgrade last night, but I always shudder a little when UK stocks make big moves into the US. No information given on either revenues or operating margins at GDT but the multiple paid suggests lower quality earnings than Softcat (LON:SCT) .
Airtel Africa (LON:AAF) shares are down over 7% because of "Airtel Money now seeks to raise at least $800 mln, substantially below its previous target of $1.5 bln-$2 bln".
Graham, would appreciate your view on Kier if you have a chance this week. Popped this week from their results this week
Harworth (LON:HWG) Graham - would be. interested to read your thoughts as the announcement today contains a lot more than the simple rejection of 177.5p offer! thanks
Bought some Investec (LON:INVP) in the extended hours, decent dividend to make laying cash earn over time
Also note Softcat (LON:SCT) buying a US company last night:
https://www.stockopedia.com/a/...
Trading update in there, too.
timarr
Big deal that. Havent seen a UK->US acquisition of size for a long time!
For anyone interested in more detail on the Softcat (LON:SCT) takeover of GDT, the link below is the BRRMedia recording of the Analysts presentation and Q&A. Some interesting points raised.
https://stream.brrmedia.co.uk/...